
 Veterinary Insulin Drugs Market | 2026-2036
Veterinary Insulin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Insulin Drugs Market Analytics
Subscription-based insulin replenishment programs is expanding how manufacturers monetize chronic diabetes care in companion animals. Zoetis Inc. leverages its direct-to-clinic distribution network to secure recurring orders from veterinary practices. Merck Animal Health anchors its position through long-standing relationships with large animal hospital chains. Boehringer Ingelheim Vetmedica differentiates via specialized veterinary sales forces that provide dosing protocol training alongside product delivery.
Veterinary insulin drugs comprise recombinant and synthetic peptide formulations engineered to regulate blood glucose in diabetic animals, typically requiring pH-buffered aqueous solutions with specific potency measured in international units per milliliter. These products serve the primary commercial purpose of managing insulin-dependent diabetes mellitus in companion animals under veterinary supervision. Long-acting insulin formulations command premium positioning due to reduced injection frequency and improved glycemic stability in feline and canine patients. Subcutaneous injection dominates delivery mode adoption, though veterinary clinics increasingly seek pen-device compatibility to align with human-diabetes caregiver familiarity. Dogs represent the largest animal-type segment by volume, while cats drive faster growth due to higher Type II diabetes prevalence in aging, indoor-kept populations.
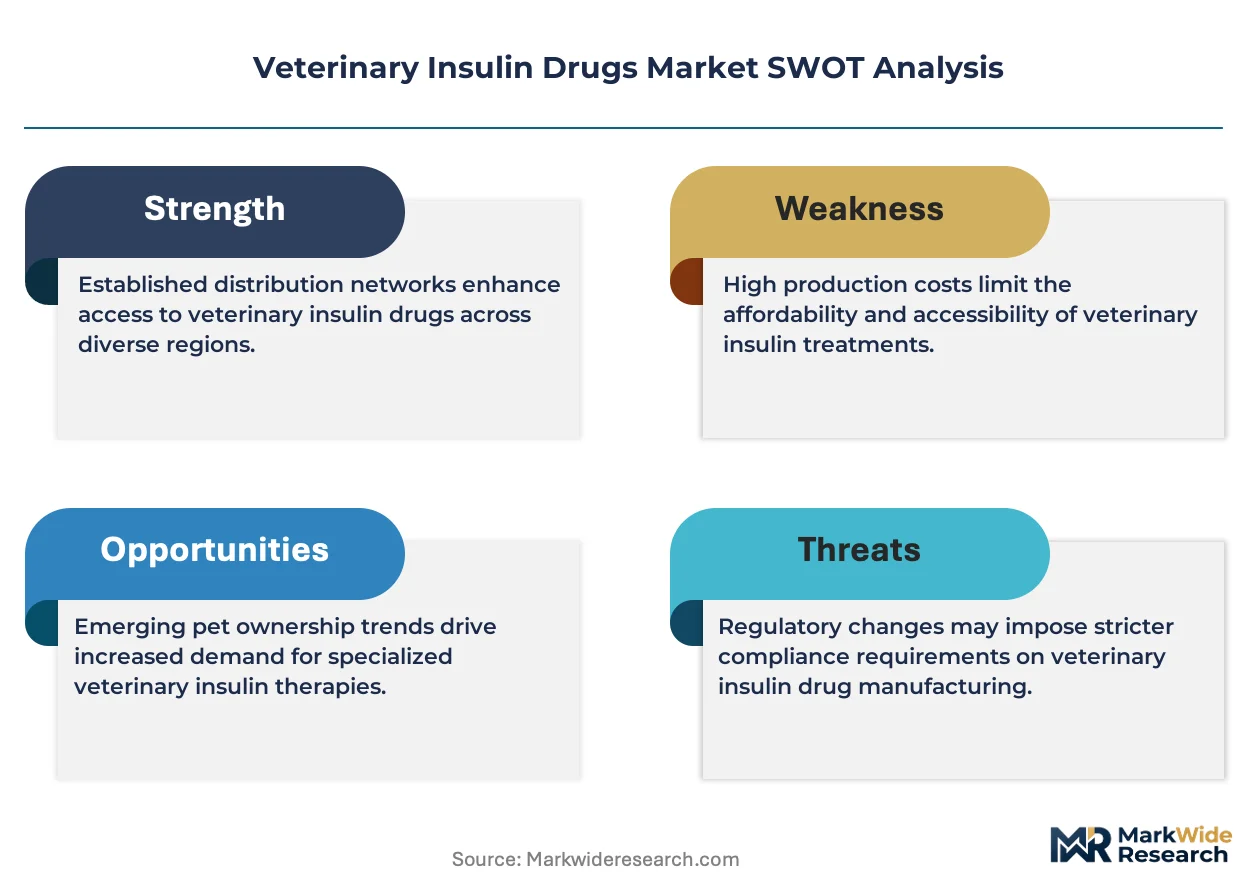
FDA Center for Veterinary Medicine and EMA Committee for Medicinal Products for Veterinary Use set purity and immunogenicity benchmarks that determine market access for new insulin entrants. USDA APHIS monitors interstate shipment compliance for biologic products, adding a logistics compliance layer to distribution strategy. Stakeholders must monitor how evolving pharmacovigilance requirements for animal biologics reshape post-approval obligations and competitive moats.
Market Dynamics
Companion animal diabetes diagnoses are accelerating faster than veterinary endocrinology capacity can scale, creating a structural bottleneck where insulin demand outpaces trained specialist availability and forcing manufacturers to embed dosing protocols directly into product packaging and digital support tools.
Growth Catalysts
- Pet Insurance Penetration:Reimbursement coverage for chronic conditions in the United States now extends to insulin therapy, reducing owner cost barriers and extending treatment adherence.
- FDA CVM Biologic Purity Standards:Tighter immunogenicity benchmarks for recombinant proteins are validating premium positioning for domestically manufactured insulin against imported alternatives.
- Feline Indoor Lifestyle Epidemiology:Obesity-linked Type II diabetes in aging, sedentary cat populations is generating sustained demand for long-acting basal insulin analogs.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Recombinant insulin peptide synthesis relies on a narrow supplier base concentrated in Switzerland and Denmark, exposing finished-dose manufacturers to single-source fragility.
- Cold Chain Integrity Costs:pH-buffered aqueous formulations require uninterrupted 2-8°C storage from manufacture through clinic administration, inflating logistics expenditure in warmer climates.
- Human Insulin Substitution:Off-label use of human NPH and glargine products in veterinary settings constrains pricing power for purpose-formulated animal insulins.
Strategic Opportunities
- Pen-Device Compatibility Convergence:Veterinary clinics are retrofitting workflow for human-diabetes pen systems, creating entry paths for manufacturers with dual-species device platforms.
- Subscription Replenishment Models:Direct-to-clinic auto-ship programs lock in recurring revenue and reduce competitive bidding exposure for chronic therapy contracts.
- USDA APHIS Interstate Commerce Expansion:Streamlined biologic shipment compliance is enabling regional distributors to serve multi-state veterinary hospital chains without facility licensing duplication.
Industry Challenges
- Veterinary Endocrinology Training Pipeline:Board-certified specialists remain scarce relative to diagnosed case volume, forcing general practitioners to manage complex glycemic protocols without specialist backup.
- Pharmacovigilance Reporting Burden:Post-approval adverse event documentation for animal biologics is intensifying, requiring manufacturers to maintain dedicated veterinary medical information departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Insulin Drugs Market |
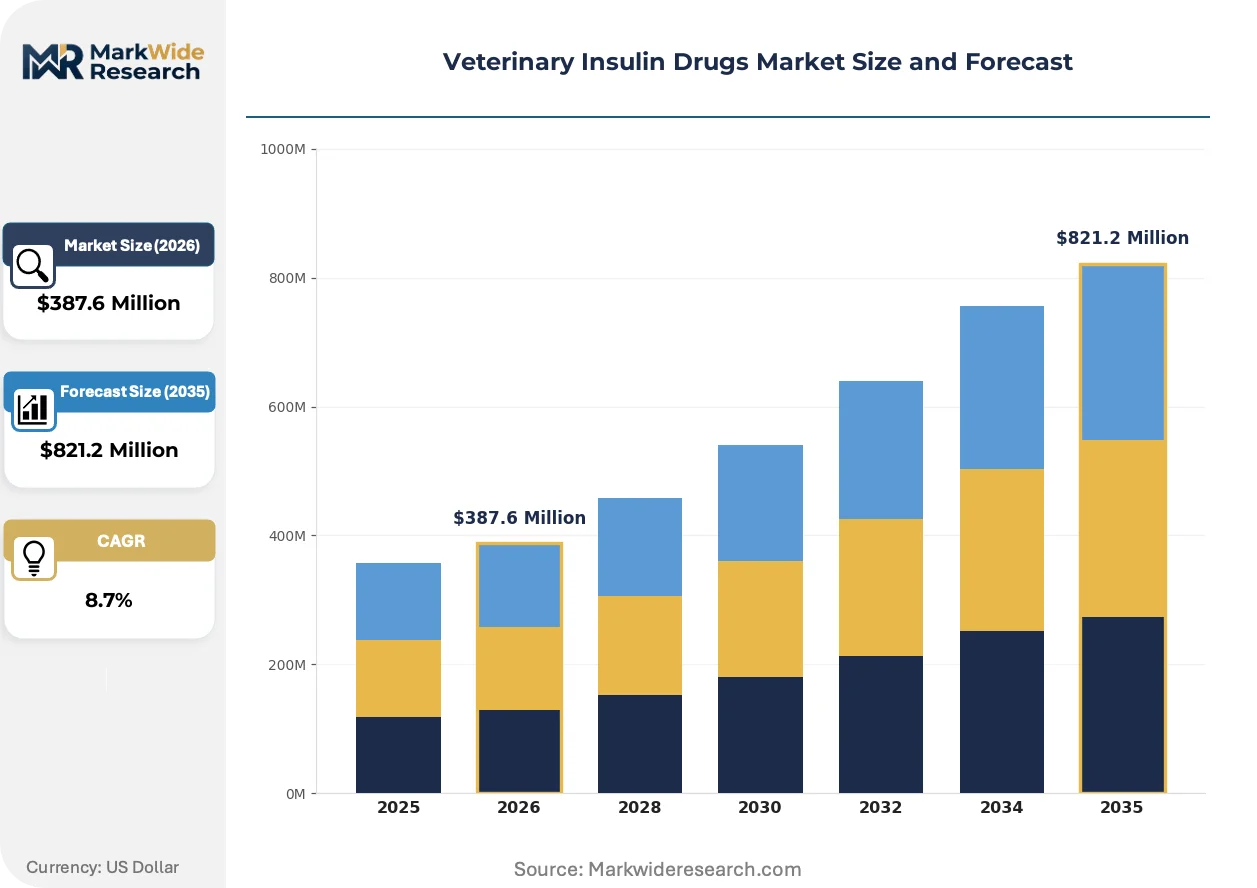
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short-Acting Insulin, Intermediate-Acting Insulin, Long-Acting Insulin, Mixed Insulin Delivery Mode: Subcutaneous Injection, Intravenous Injection, Inhalation, Oral Administration End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Pet Owners Animal Type: Cats, Dogs, Horses, Other Companion Animals |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Vetmedica, Elanco, Vetoquinol S.A., Novo Nordisk, Eli Lilly & Company, Sanofi-Aventis, Biocon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Insulin Drugs Market Evolving Landscape
Digital glycemic monitoring and automated dosing support are compressing the expertise gap between specialist and general practice, while regulatory harmonization efforts are reshaping how manufacturers validate product claims across jurisdictions.
Continuous glucose monitoring sensors adapted from human diabetes care are automating real-time glycemic tracking in hospitalized companion animals. Emergency and referral practices in the United States are deploying these systems to reduce manual blood glucose curve construction. The technology is automating data collection previously performed by credentialed veterinary technicians, compressing labor cost per case and enabling overnight monitoring without staffing escalation.
EMA Committee for Medical Products for Veterinary Use is tightening immunogenicity data requirements for novel insulin analogs seeking European market authorization. Manufacturers must now submit extended anti-insulin antibody monitoring from field safety studies. Long-acting basal formulations targeting feline diabetes are experiencing the longest pre-approval review timelines as a result, delaying revenue recognition for pipeline assets.
Veterinary practice consolidation is compressing purchasing autonomy for individual clinicians. Large corporate hospital groups in the United States are centralizing formulary decisions at headquarters level, displacing traditional distributor relationships with direct manufacturer contracts negotiated at enterprise scale. This concentration is most visible in southern and western states where private equity-backed roll-ups have achieved highest regional density.
Veterinary Insulin Drugs Market Segmentation
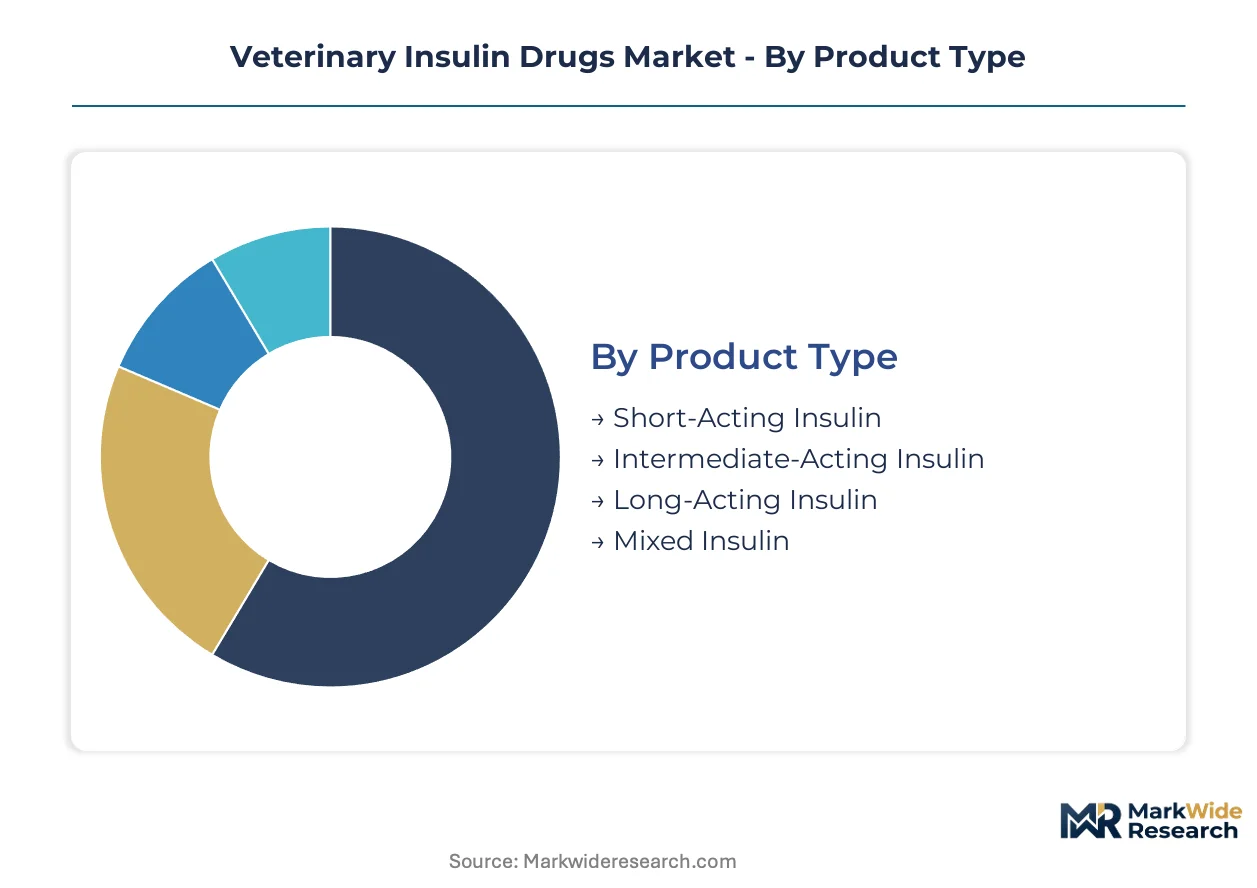
Veterinary insulin drugs segment across pharmacokinetic profiles, administration routes, care settings, and species-specific metabolic requirements. Each dimension shapes procurement decisions, reimbursement pathways, and manufacturer R&D prioritization differently.
Product Type:
Veterinary clinicians select insulin duration based on glycemic curve patterns and owner compliance capacity, with cost per treatment day heavily influencing formulary placement.
- Long-Acting Insulin:Basal analogs such as insulin glargine and detemir provide 12-24 hour glucose control with reduced injection frequency. Demand concentrates in feline diabetes management across the United States, where owner adherence constraints favor simplified dosing schedules.
- Short-Acting Insulin:Rapid-onset formulations including regular insulin and lispro analogs enable precise meal-time glycemic correction. Emergency and referral practices in high-density metropolitan areas deploy these for diabetic ketoacidosis stabilization and perioperative glucose management.
- Intermediate-Acting Insulin:NPH formulations balance cost and duration for budget-conscious general practices managing stable canine diabetes.
- Mixed Insulin:Pre-combined basal-bolus preparations serve resource-limited settings where single-vial simplicity outweighs titration precision.
Volume sits with intermediate-acting formulations; growth tilts toward long-acting analogs.
Delivery Mode:
Route selection reflects veterinary workflow efficiency, species anatomy, and the availability of caregiver training support from manufacturers.
- Subcutaneous Injection:Standard administration via U-40 or U-100 syringes dominates outpatient chronic management. Companion animal practices across Germany and France favor this route for its equipment simplicity and established owner education protocols.
- Intravenous Injection:Hospitalized critical care applications require continuous-rate infusion capability. Emergency referral centers in the United Kingdom utilize IV insulin for hyperglycemic crisis management and surgical glycemic control.
- Inhalation:Exubera-derived dry powder devices for feline diabetes reached limited commercialization before withdrawal; residual interest persists in needle-averse owner segments.
- Oral Administration:No clinically effective oral insulin bioavailability exists; research-stage permeation enhancers target future canine applications.
Subcutaneous injection commands absolute volume share; intravenous delivery expands fastest within tertiary referral settings.
End User:
Procurement authority and reimbursement structure vary sharply across care settings, determining price sensitivity and contract loyalty.
- Veterinary Clinics:Independent and corporate general practices generate recurring prescription volume through chronic disease management. Corporate hospital chains in the southern United States centralize formulary decisions at regional headquarters, displacing traditional distributor relationships.
- Animal Hospitals:Emergency and specialty referral centers require rapid-acting and continuous-infusion insulin inventories for acute metabolic crises. These facilities in metropolitan California and Texas maintain broader formularies with premium positioning tolerance.
- Research Institutions:Academic veterinary medical centers purchase insulin for diabetes pathophysiology studies and veterinary student training.
- Pet Owners:Direct-to-consumer channels remain limited; most owner acquisition flows through veterinary prescription with clinic markup.
Procurement volume aggregates at veterinary clinics; revenue expansion concentrates in animal hospitals.
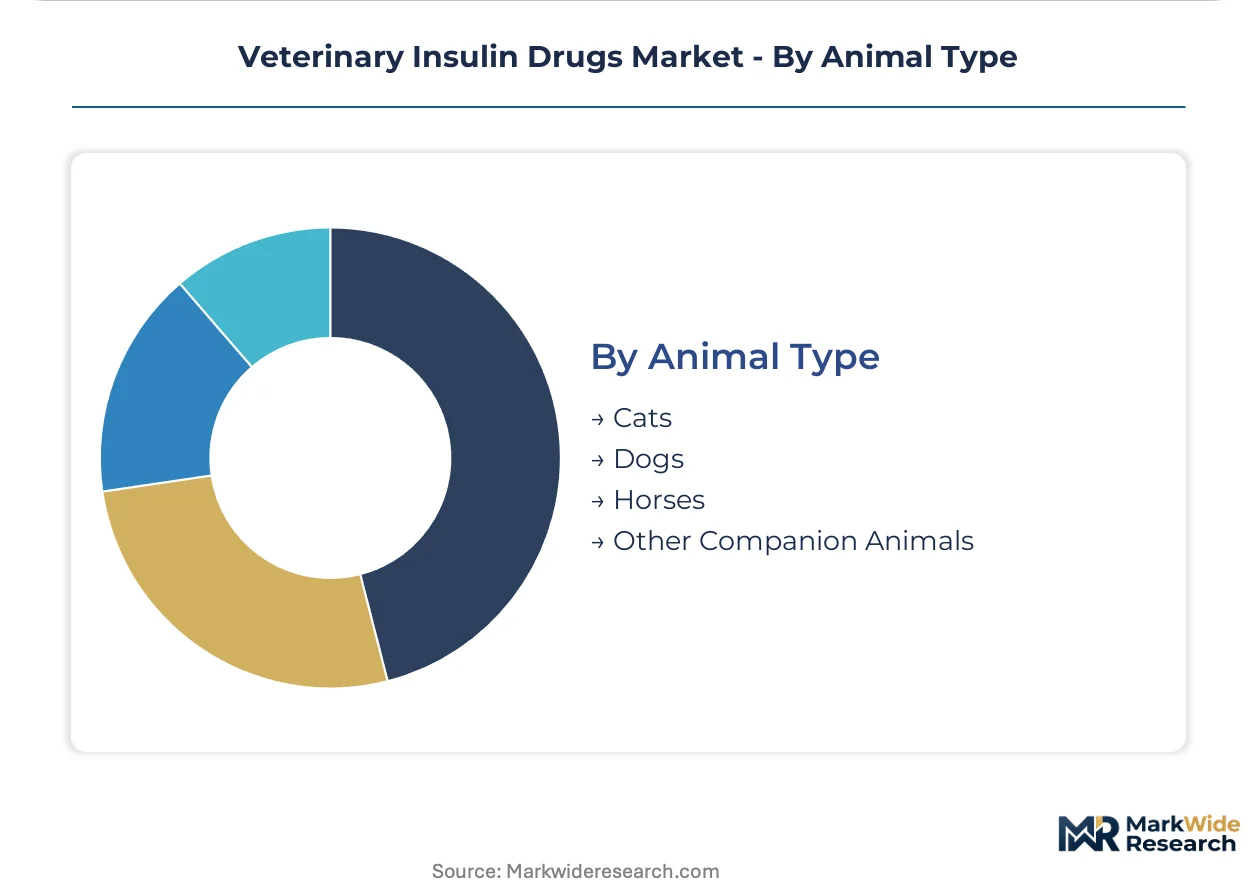
Animal Type:
Species-specific insulin pharmacokinetics and disease prevalence patterns determine product development investment and marketing resource allocation.
- Cats:Obligate carnivores with Type II diabetes predominance respond preferentially to long-acting basal analogs. Aging, indoor-kept feline populations in Japan and Australia generate sustained demand for glargine and detemir formulations with reduced hypoglycemia risk profiles.
- Dogs:Insulin-dependent Type I diabetes requires twice-daily intermediate-acting protocols in most cases. Canine patient volume in the United States and United Kingdom supports the largest absolute prescription base despite slower per-case growth.
- Horses:Equine metabolic syndrome and pituitary pars intermedia dysfunction create niche insulin requirements for hyperinsulinemia management rather than replacement therapy.
- Other Companion Animals:Ferret insulinoma and rabbit diabetes represent minimal commercial volume with compounded pharmacy reliance.
Absolute volume rests with canine patients; feline applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finished-dose veterinary insulin production concentrates in Switzerland and Denmark, while consumption tilts toward the United States, Japan, and Western Europe where companion animal diabetes diagnoses outpace specialist veterinary capacity.
United States
Pet insurance reimbursement for chronic insulin therapy and corporate veterinary hospital consolidation drive procurement volume. FDA Center for Veterinary Medicine enforces biologic purity standards that validate domestically manufactured products. Metropolitan California and Texas host the densest concentrations of emergency referral centers deploying continuous glucose monitoring systems.
Germany
General practitioner preference for U-40 syringe protocols and established owner education infrastructure sustain intermediate-acting insulin demand. The country's national pharmaceutical regulator aligns with EMA immunogenicity benchmarks for recombinant protein approvals. Bavaria and North Rhine-Westphalia concentrate corporate veterinary chains centralizing formulary decisions at regional headquarters.
Japan
Aging indoor-kept feline populations generate sustained demand for long-acting basal analogs with reduced hypoglycemia risk profiles. METI oversees pharmaceutical manufacturing standards while PMDA evaluates novel insulin analogs for veterinary use. Tokyo and Osaka metropolitan areas anchor specialist referral networks managing complex glycemic cases.
United Kingdom
Emergency referral centers in London and the Southeast utilize intravenous insulin infusion for hyperglycemic crisis management. The Veterinary Medicines Directorate enforces pharmacovigilance reporting requirements for animal biologics. Greater Manchester and Birmingham clusters support academic veterinary medical centers training students in diabetes pathophysiology protocols.
Australia
Feline obesity-linked Type II diabetes in sedentary urban pet populations drives glargine and detemir adoption. The Therapeutic Goods Administration coordinates with state veterinary boards on biologic product registration. Sydney and Melbourne house the largest concentrations of specialist endocrinology practices managing complex diabetic cases.
Veterinary Insulin Drugs Market Competitive Landscape
Capital-heavy producers with captive fermentation capacity compete with asset-light formulation specialists outsourcing peptide synthesis to contract manufacturers. The market structure consolidates around three to five integrated animal health conglomerates controlling distribution networks and direct-to-clinic relationships. Strategic archetypes include vertically integrated biologic manufacturers, human-pharma diversifiers leveraging cross-species insulin platforms, and regional distributors with cold-chain logistics specialization. Competitive moves center on subscription-based replenishment program deployment and veterinary sales force expansion for dosing protocol training.
Within the integrated animal health tier, Zoetis Inc. and Merck Animal Health exemplify capital-heavy producers with direct-to-clinic distribution networks securing recurring chronic therapy contracts. Boehringer Ingelheim Vetmedica occupies a position emphasizing specialized veterinary sales forces. Among human pharmaceutical diversifiers, Eli Lilly & Company and Novo Nordisk represent cross-species insulin platform leverage. Elanco and Vetoquinol S.A. sit within the mid-tier specialist category. Biocon anchors the emerging-market supplier archetype.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Vetmedica |
| Elanco |
| Vetoquinol S.A. |
| Novo Nordisk |
| Eli Lilly & Company |
| Sanofi-Aventis |
| Biocon |
| Others |
Value Network & Pricing Analysis
Long-acting basal analog certification against FDA CVM immunogenicity benchmarks creates a three-tier pricing structure across premium, standard, and economy levels that separates Swiss-manufactured recombinant products from Danish-sourced alternatives and compounded formulations, with each tier commanding distinct cold-chain logistics configurations and distributor margin structures.
Pricing Analysis
Margin tightening in intermediate-acting formulations reflects off-label human insulin substitution by cost-conscious general practitioners. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA CVM purity certification and cold-chain integrity guarantees. Corporate veterinary hospital chains in the southern United States extract volume discounts through centralized formulary negotiations. Independent clinics in Germany and France exhibit highest price sensitivity due to U-40 syringe protocol standardization limiting product switching.
Supply Chain Analysis
Specialized fermentation technician availability constraints in Switzerland and Denmark limit recombinant insulin peptide synthesis capacity expansion. Finished-dose formulation draws from Swiss and Danish API concentration with Austrian and German fill-finish capabilities. Single-source fragility in recombinant peptide synthesis creates vulnerability to batch contamination events. Distribution runs through direct-to-clinic auto-ship programs and regional cold-chain specialists serving multi-state veterinary hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary insulin drug manufacturing is consolidating around capital-heavy producers with captive fermentation capacity as FDA CVM immunogenicity documentation requirements force smaller competitors toward contract manufacturing dependency.
For Market Incumbents: Anticipate margin compression from human-pharma diversifiers leveraging cross-species insulin platforms by deepening captive fermentation capacity in Switzerland and Denmark. Secure board-certified veterinary endocrinologist advisory relationships to embed dosing protocols into digital support tools before general practitioner workflow automation displaces specialist-dependent positioning. For New Entrants and Emerging Players: Launch via pen-device compatibility convergence targeting corporate veterinary hospital chains retrofitting workflow for human-diabetes pen systems. White-space opportunity concentrates in feline long-acting basal analogs for aging indoor-kept populations in Japan and Australia where METI and TGA regulatory pathways offer faster authorization than FDA CVM timelines. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists possessing cold-chain logistics specialization given USDA APHIS interstate commerce expansion enabling multi-state distribution without facility licensing duplication. Long-term viability favors asset-light formulation specialists with contract manufacturing relationships over capital-intensive fermentation buildout. Monitor EMA Committee for Medicinal Products for Veterinary Use immunogenicity data requirement intensity as inflection indicator for pipeline asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA CVM immunogenicity benchmarks validate premium positioning for domestically manufactured insulin against imported alternatives. |
| Manufacturing Scale-Up | Captive fermentation capacity in Switzerland and Denmark secures API supply against single-source fragility in recombinant peptide synthesis. |
| Distribution Channel Expansion | Direct-to-clinic auto-ship programs lock in recurring revenue from corporate veterinary hospital chains centralizing formulary decisions. |
| Product Launch | Pen-device compatibility convergence aligns veterinary workflow with human-diabetes caregiver familiarity in metropolitan California and Texas. |
| Strategic Partnership | Board-certified veterinary endocrinologist advisory relationships embed dosing protocols into digital support tools for general practitioner management. |
Research Methodology
Document review covered FDA CVM approval filings, EMA veterinary marketing authorization submissions, USDA APHIS interstate shipment compliance records, and corporate veterinary hospital chain procurement disclosures, complemented by interviews with veterinary endocrinology specialists, animal health regulatory affairs leads, formulary directors at corporate hospital groups, cold-chain logistics operators, and recombinant peptide synthesis contract manufacturers. Secondary validation drew from pharmaceutical trade customs data, veterinary medical journal publication databases, and companion animal insurance reimbursement trend reports. Bottom-up prescription volume modeling and top-down market sizing triangulated against manufacturer production capacity disclosures.
Segment-level demand projections across product type, delivery mode, end user, and animal type dimensions fed into analytical framework outputs over the projection horizon. CAGRs were derived from regression analysis against companion animal diabetes diagnosis incidence curves and veterinary endocrinology specialist training pipeline constraints. Industry-specific forecast inputs incorporated feline obesity epidemiology data and pet insurance penetration trajectories by metropolitan statistical area.
The model assumes a particular technology adoption path for continuous glucose monitoring sensor deployment; alternative pathways for automated glycemic tracking would alter the outlook. Forecasts reflect assumptions regarding FDA CVM immunogenicity benchmark stability, cold-chain infrastructure investment continuity, and corporate veterinary practice consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market