
 Global Closed System Transfer Devices Market | 2026-2036
Global Closed System Transfer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Closed System Transfer Devices Market Foresight
Oncology center procurement is pivoting toward needle-free closed system transfer devices as frontline chemotherapy administration expands. Equashield LLC leverages proprietary dual-needle barrier technology to dominate hazardous drug compounding workflows. Becton, Dickinson and Company sustains manufacturing scale across multiple geographic clusters through integrated device production. ICU Medical, Inc. specializes in vial adapter configurations that anchor its position in hospital pharmacy automation.
Closed system transfer devices are mechanical barrier systems engineered to prevent escape of hazardous drug aerosols, vapors, and droplets during compounding and administration, typically incorporating elastomeric seals and Luer Lock interfaces rated for pressure differentials up to 45 psi. These systems serve the primary industrial purpose of eliminating occupational exposure to antineoplastic and other hazardous pharmaceuticals in healthcare settings. The needle-free product type segment leads current revenue contribution due to superior user safety profiles and reduced sharps injury liability. Cytotoxic drug preparation applications command the deepest margin pools as pharmaceutical manufacturers and contract compounders face mandatory containment protocols. Deployment through hospital pharmacies remains the dominant channel, though home healthcare represents the fastest-growing structural outlet as oral chemotherapy alternatives expand.
The USP Chapter 800 standard from the United States Pharmacopeia and the FDA's guidance on sterile compounding jointly mandate closed system transfer device utilization for hazardous drug handling, directly conditioning product certification requirements and procurement eligibility across American oncology facilities. EMA's MDR framework and REACH chemical safety protocols in Europe impose parallel conformity obligations that filter market access for non-compliant device manufacturers. Stakeholders must monitor evolving EPA waste containment rules and state-level occupational safety amendments that will recalibrate total cost of ownership calculations for institutional buyers.
Market Dynamics
The needle-free CSTD segment is compressing adoption timelines across oncology centers as USP Chapter 800 enforcement hardens procurement specifications for hazardous drug containment infrastructure.
Growth Catalysts
- USP Chapter 800 Mandate:The United States Pharmacopeia standard compels institutional pharmacies to deploy closed system transfer devices for all hazardous drug handling, creating non-negotiable demand pull across American healthcare facilities.
- German Hospital Pharmacy Upgrades:EMA safety requirements for cytotoxic handling are forcing hospital pharmacies in Germany to replace legacy compounding equipment with certified CSTD systems ahead of scheduled compliance deadlines.
- Needle-Free Barrier Technology:Dual-needle barrier configurations are eliminating sharps injury liability while improving user throughput during high-volume chemotherapy preparation workflows.
Market Restraints
- Elastomeric Seal Input Concentration:Specialized medical-grade elastomer supply concentrates among three Asian polymer compounders, exposing device manufacturers to raw material allocation risk during demand surges.
- MDR Certification Friction:The European Union's Medical Device Regulation imposes extended conformity assessment timelines for novel CSTD interfaces, delaying market entry for next-generation designs by 12-18 months.
- Legacy Vial Access Substitution:Conventional needle-based drug transfer systems retain installed base advantages in cost-constrained emerging markets, slowing premium CSTD penetration outside regulated jurisdictions.
Strategic Opportunities
- Home Healthcare Channel Expansion:Oral chemotherapy administration protocols are extending hazardous drug handling into residential settings, creating demand for portable CSTD configurations designed for non-clinical environments.
- EMA-REACH Convergence:The alignment of medical device and chemical safety frameworks in Europe is streamlining multi-certification pathways for manufacturers with integrated quality management systems.
- Automation Interface Integration:Robotic compounding systems in hospital pharmacies require standardized CSTD docking protocols, opening specification control opportunities for device vendors with early automation partnerships.
Industry Challenges
- Containment Validation Talent Scarcity:Qualified industrial hygienists capable of performing surface wipe sampling and air monitoring for hazardous drug exposure verification remain concentrated in major metropolitan oncology clusters.
- Legacy Pharmacy Workflow Integration:CSTD deployment requires reconfiguration of existing sterile compounding cleanroom layouts, forcing capital-intensive facility modifications that strain pharmacy renovation budgets.
- Interoperability Standardization Delays:Absence of universal Luer Lock dimensional tolerances across device manufacturers creates connection compatibility failures during multi-vendor pharmacy environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Closed System Transfer Devices Market |
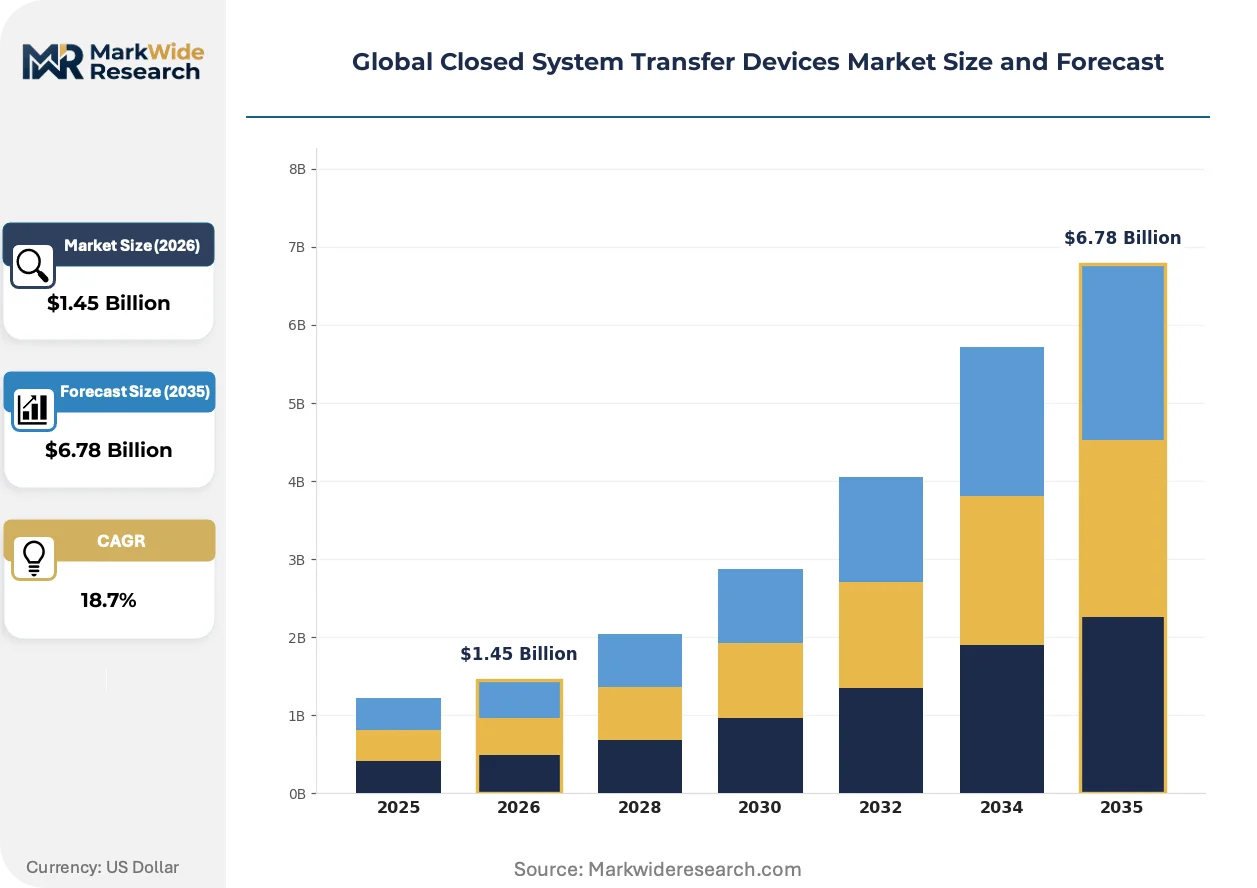
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luer Lock, Spike, Needle-Free, Vial Adapter, Bag Spike, Others Application: Cytotoxic Drug Preparation, Chemotherapy, Parenteral Drug Delivery, Hazardous Drug Handling End User: Pharmaceutical Manufacturers, Specialty Clinics, Oncology Centers, Research Laboratories Deployment Model: Hospital Pharmacies, Outpatient Facilities, Home Healthcare, Ambulatory Services |
| Companies Covered | Equashield LLC, Yukon Medical, LLC, Becton, Dickinson and Company, Terumo Corporation, JMS Co., Ltd., ICU Medical, Inc., Baxter International Inc., West Pharmaceutical Services, Inc., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Closed System Transfer Devices Market Shifts & Advancements
Disposable cartridge-based CSTD architectures are displacing reusable systems as contamination risk economics favor single-use configurations in high-throughput compounding operations.
Closed system transfer devices incorporating pre-assembled vial-syringe adapters are decentralizing hazardous drug preparation from centralized hospital pharmacies to satellite oncology infusion centers. These integrated configurations reduce assembly steps by eliminating separate component mating. Community cancer clinics in the United States are adopting these streamlined systems to enable same-day chemotherapy preparation without dedicated compounding infrastructure.
The EPA's evolving waste containment rules for hazardous pharmaceutical disposal are forcing CSTD manufacturers to redesign product end-of-life protocols. Device housings must now accommodate dual-stream segregation of contaminated components from recyclable materials. Oncology facilities in California and Washington are piloting manufacturer take-back programs to satisfy state-level extended producer responsibility mandates ahead of federal rule finalization.
Group purchasing organizations are consolidating CSTD vendor panels from multi-source to sole-source or dual-source arrangements, compressing supplier diversity in favor of volume-based pricing agreements. Hospital systems exceeding 50 infusion centers are demanding enterprise-wide standardization to simplify nursing training and inventory management. This concentration is most visible across the largest American integrated delivery networks, where pharmacy directors now prioritize vendor scale over product feature differentiation.
Global Closed System Transfer Devices Market Segmentation
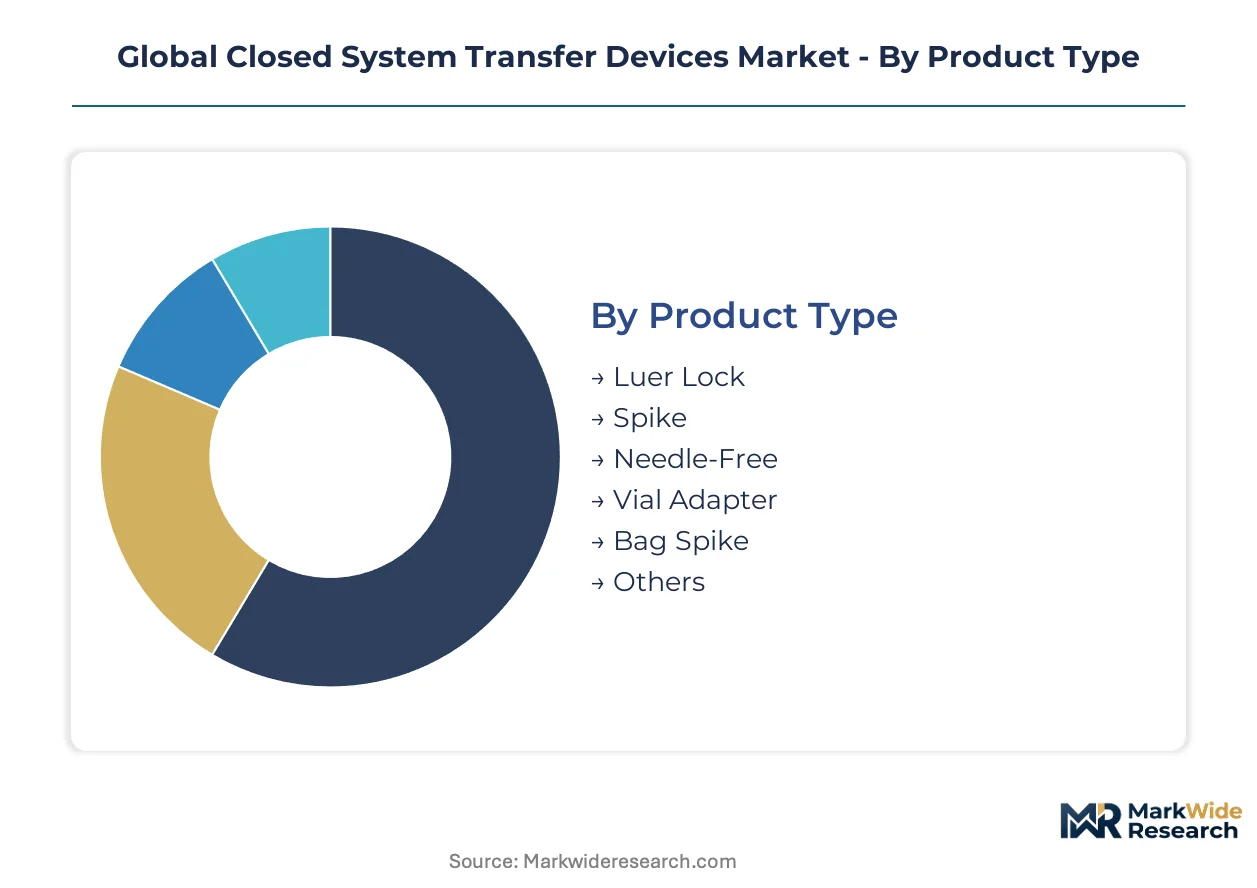
Segmentation in closed system transfer devices reflects divergent regulatory certification burdens across product architectures and use environments. Each dimension carries distinct conformity requirements from FDA, EMA, and national occupational safety bodies that shape procurement eligibility and margin structures.
Product Type:
Needle-Free and Luer Lock configurations carry the heaviest certification load, requiring FDA 510(k) clearance plus USP Chapter 800 validation documentation for hazardous drug containment claims. Spike and bag spike variants face lighter premarket scrutiny but must demonstrate equivalent barrier performance under OSHA workplace exposure limits.
- Needle-Free:Dual-needle barrier architecture eliminates sharps injury risk while maintaining elastomeric seal integrity under 45 psi pressure differentials. Oncology centers across the United States are consolidating procurement around these systems as USP Chapter 800 enforcement hardens and liability exposure from needlestick injuries escalates insurance premiums.
- Luer Lock:Standardized threaded interface enables universal syringe connection but demands precise dimensional tolerance control to prevent connection failures in multi-vendor pharmacy environments. German hospital pharmacies are driving specification tightening as EMA MDR conformity assessments raise the bar for interface reliability documentation.
- Spike:Piercing element for IV bag access with integrated check valve; deployed primarily in high-volume compounding operations where throughput velocity outweighs connection versatility requirements.
- Vial Adapter:Pre-assembled vial-syringe mating component that reduces preparation steps; favored by satellite oncology infusion centers lacking dedicated compounding infrastructure.
- Bag Spike:Specialized large-bore access device for parenteral solution containers; common in ambulatory chemotherapy suites with standardized protocol menus.
- Others:Custom adapter configurations for specialty drug containers and legacy vial formats; niche demand from research laboratories handling experimental therapeutics.
Leading the category by volume: Needle-Free. Growing fastest: Vial Adapter.
Application:
Margin concentration varies sharply across application segments, with cytotoxic handling commanding premium pricing due to mandatory containment validation requirements and specialized industrial hygiene oversight.
- Cytotoxic Drug Preparation:Compounding workflows for antineoplastic agents require documented surface wipe sampling and air monitoring protocols under USP Chapter 800. Contract compounders in the United States face non-negotiable CSTD deployment for OSHA compliance, creating locked-in demand with limited price elasticity.
- Chemotherapy:Administration-phase applications span infusion center nursing workflows where device simplicity and training standardization dominate procurement criteria. Community cancer clinics are adopting pre-assembled configurations to enable same-day treatment initiation without centralized pharmacy delays.
- Parenteral Drug Delivery:Broad-spectrum intravenous medication administration including antibiotics and biologics; CSTD adoption here is elective rather than mandated, creating price-sensitive demand patterns.
- Hazardous Drug Handling:Catch-all category encompassing hormonal agents, monoclonal antibodies, and other biologics with reproductive toxicity profiles; EPA waste containment rules are expanding the scope of drugs requiring closed-system handling.
Maximum margin capture: Cytotoxic Drug Preparation. Steepest expansion trajectory: Chemotherapy administration in satellite settings.
End User:
Procurement authority and technical sophistication diverge dramatically across end-user categories, from centralized pharmaceutical manufacturing quality systems to decentralized clinic nursing workflows.
- Oncology Centers:Frontline chemotherapy administration sites with direct nursing exposure to hazardous drugs; USP Chapter 800 mandates drive non-discretionary CSTD procurement with emphasis on user throughput and training simplicity.
- Pharmaceutical Manufacturers:Sterile compounding operations for commercial drug production face FDA current Good Manufacturing Practice requirements plus containment validation for occupational exposure limits. Batch scale and automation integration dominate specification development.
- Specialty Clinics:Rheumatology, dermatology, and other infusion specialties handling hazardous biologics; smaller volume profiles create demand for flexible, low-inventory CSTD configurations.
- Research Laboratories:Investigational drug handling with protocol-specific containment needs; procurement emphasizes vendor technical support and custom adapter availability over standardized configurations.
Deepest volume concentration: Oncology Centers. Fastest procurement cycle acceleration: Pharmaceutical Manufacturers facing FDA inspection intensity.
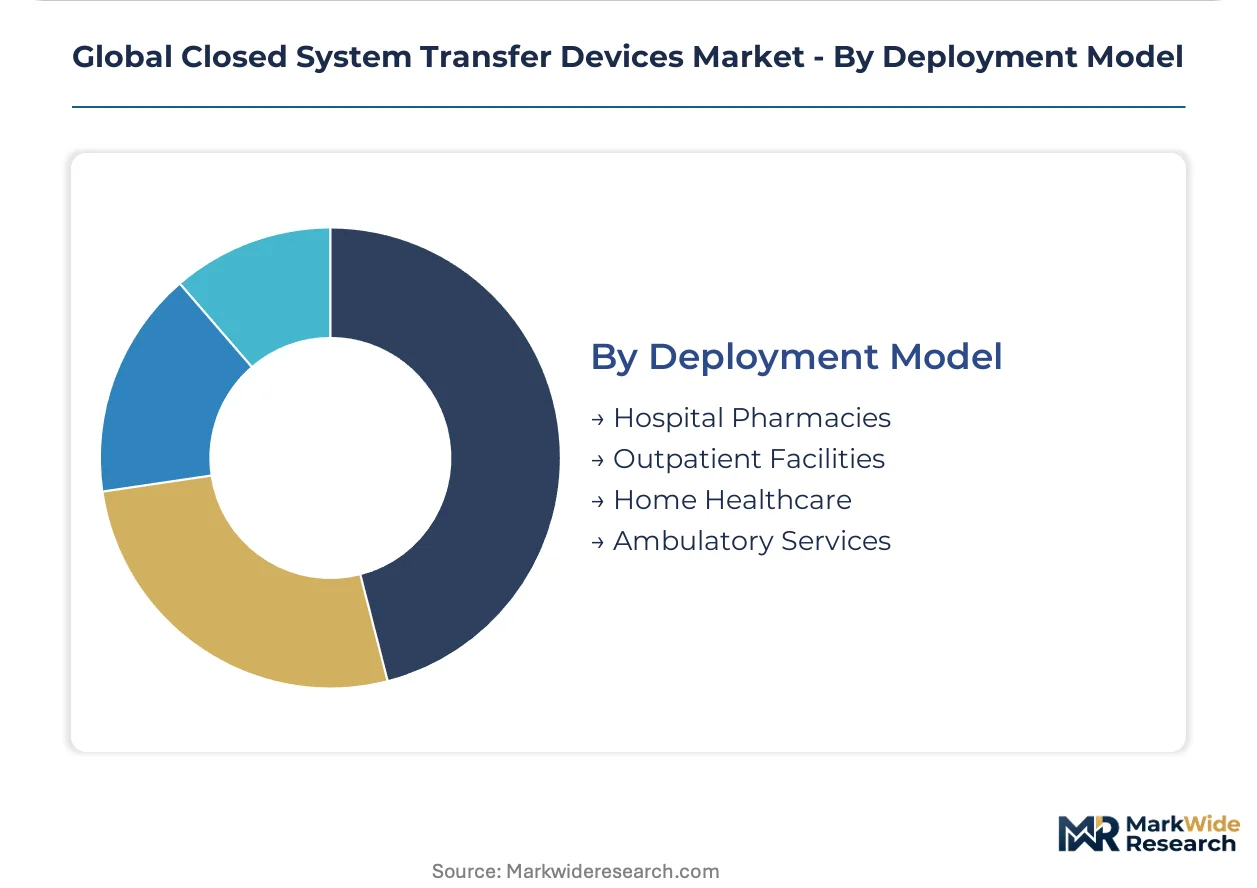
Deployment Model:
Channel economics shift with care setting migration, as hospital pharmacy infrastructure investments contrast with home healthcare portability requirements and reimbursement constraints.
- Hospital Pharmacies:Centralized compounding operations with robotic automation integration and cleanroom infrastructure; procurement emphasizes vendor scale, enterprise standardization, and group purchasing organization contract compliance.
- Home Healthcare:Residential administration of oral chemotherapy alternatives and subcutaneous biologics; portability, patient self-administration training, and disposal logistics dominate product design requirements.
- Outpatient Facilities:Satellite infusion centers and community oncology suites; demand centers on pre-assembled configurations that eliminate compounding infrastructure requirements.
- Ambulatory Services:Mobile chemotherapy administration and visiting nurse programs; device durability in transport and field conditions shapes specification priorities.
Current revenue anchor: Hospital Pharmacies. Gaining share fastest: Home Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in Singapore and Ireland are concentrating CSTD production capacity through tax-advantaged facilities serving European and Asia-Pacific distribution networks.
United States
Oncology centers in Houston and New York Metro are scaling needle-free CSTD procurement to satisfy USP Chapter 800 inspection timelines. The FDA's sterile compounding guidance reinforces mandatory containment protocols. Hospital pharmacies across the Mayo Clinic network in Minnesota are completing infrastructure upgrades ahead of OSHA enforcement windows.
Germany
Hospital pharmacies in Bavaria and North Rhine-Westphalia face EMA MDR conformity deadlines for cytotoxic handling equipment. REACH chemical safety protocols impose dual certification burdens on device manufacturers. The Heidelberg oncology cluster is piloting pre-assembled vial adapter configurations for satellite infusion centers.
Japan
PMDA quality system requirements are accelerating CSTD adoption in Tokyo and Osaka metropolitan hospital systems. METI industrial standards for hazardous drug containment shape procurement specifications. The Nagoya pharmaceutical manufacturing corridor is integrating closed-system protocols into robotic compounding installations.
Switzerland
Swissmedic device certification timelines are filtering market access for novel CSTD interfaces in Basel and Zurich hospital networks. The country's precision manufacturing base supports elastomeric seal component sourcing for European device assemblers. Geneva's oncology research institutes are validating next-generation barrier technologies.
Australia
TGA conformity assessment pathways are harmonizing with ISO standards for hazardous drug containment in Sydney and Melbourne healthcare systems. State-level occupational safety amendments in Victoria are expanding CSTD mandate scope beyond cytotoxics. The Brisbane hospital pharmacy network is standardizing on single-vendor enterprise contracts.
Global Closed System Transfer Devices Market Competitive Landscape
Top-tier vendors anchor enterprise-scale hospital system contracts, while mid-cap specialists occupy automation integration niches. The vendor base stratifies across three tiers: multinational device conglomerates with integrated manufacturing footprints, regional specialists with pharmacy workflow expertise, and emerging entrants targeting home healthcare portability requirements. Two dominant competitive moves are reshaping positioning: strategic partnerships with robotic compounding system manufacturers, and geographic expansion through distributor acquisitions in Asia-Pacific markets.
Within the integrated manufacturing tier, Becton, Dickinson and Company and Baxter International Inc. exemplify scale-driven positioning through diversified device portfolios spanning multiple therapeutic categories. ICU Medical, Inc. occupies a specialized position in vial adapter configurations that align with hospital pharmacy automation trends. These three entities represent contrasting archetypes—conglomerate breadth, integrated device-solution bundling, and component-level specialization—without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Equashield LLC |
| Yukon Medical, LLC |
| Becton, Dickinson and Company |
| Terumo Corporation |
| JMS Co., Ltd. |
| ICU Medical, Inc. |
| Baxter International Inc. |
| West Pharmaceutical Services, Inc. |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
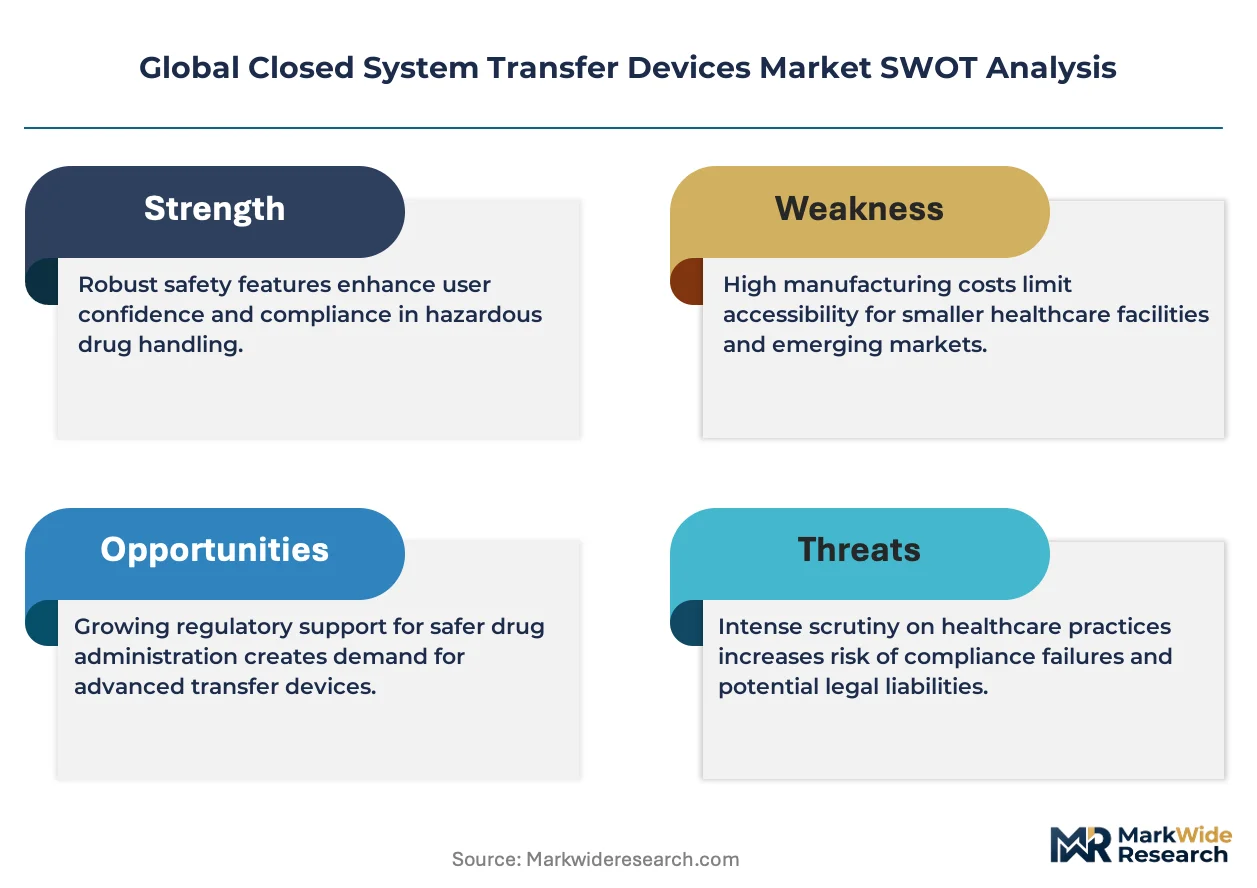
Backward integration into medical-grade elastomer compounding anchors supply positions for leading device manufacturers while insulating them from raw material allocation shocks that would otherwise compress margins. This captive supply strategy simultaneously supports pricing power in premium needle-free configurations where USP Chapter 800 certification creates procurement stickiness among American oncology centers.
Pricing Analysis
Short lead-time premiums of four to six weeks command pricing advantages over standard delivery windows as German hospital pharmacies face EMA MDR conformity deadlines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared needle-free systems from CE-marked alternatives and uncertified legacy spike configurations. Cost compression in economy tiers is intensifying because Asian compounders are absorbing volume discounts to maintain share against integrated manufacturers. Contract research organizations and small specialty clinics exhibit highest price sensitivity, while pharmaceutical manufacturers facing FDA inspection intensity show least elasticity.
Supply Chain Analysis
FDA 510(k) clearance and EMA MDR conformity assessment documentation function as procurement gating mechanisms that filter supplier qualification. Medical-grade elastomer feedstock concentrates among polymer compounders in Japan, Germany, and Singapore, while finished device assembly clusters in Ireland, Switzerland, and the United States to leverage tax-advantaged pharmaceutical zones. Single-source vulnerability in specialized Luer Lock dimensional tolerance manufacturing exposes multi-vendor pharmacy environments to connection compatibility failures. Distribution runs through group purchasing organization contracts and direct hospital system agreements rather than open-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into elastomeric seal production and robotic compounding system partnerships has become the defining competitive race as manufacturers seek to lock in specification control. Players capturing upstream polymer compounding or downstream automation interfaces will anchor margin positions through the projection horizon.
For Market Incumbents: To counter emerging entrants with portable home healthcare configurations, incumbents should acquire regional specialists with pharmacy workflow expertise and deepen backward integration into Asian polymer compounders to secure elastomer allocation priority during demand surges. For New Entrants and Emerging Players: The premium-to-economy price-point gap in vial adapter configurations offers entry traction for players targeting satellite oncology infusion centers in Australia and Japan where pre-assembled systems eliminate compounding infrastructure requirements. Focus initial go-to-market efforts on TGA and PMDA certification pathways to bypass FDA 510(k) backlog delays. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational device conglomerates seeking automation integration capabilities. Long-term viability favors targets with dual FDA-EMA certification portfolios and established GPO contract positions. Watch for EPA waste containment rule finalization as inflection indicator for take-back program infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Compounding Partnership | Standardized CSTD docking protocols with automated pharmacy systems lock in specification control at Mayo Clinic-scale networks. |
| EMA-REACH Integrated Certification | Dual medical device and chemical safety compliance streamlines market access for Heidelberg oncology cluster deployments. |
| Home Healthcare Portability Development | Patient self-administration training programs extend hazardous drug handling into residential settings for oral chemotherapy alternatives. |
| Asian Polymer Compound Acquisition | Captive elastomer supply insulates against raw material allocation risk during USP Chapter 800 enforcement windows. |
| Extended Producer Responsibility Program | Manufacturer take-back pilots in California and Washington satisfy state mandates ahead of federal EPA rule finalization. |
Research Methodology
FDA 510(k) filings, EMA MDR submission databases, and hospital procurement contract records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with oncology pharmacy directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers provided qualitative validation of adoption timelines and certification friction points. Bottom-up volume estimates from product-type segmentation were triangulated against top-down healthcare expenditure analysis across the analysis window.
Historical trendline analysis of CSTD procurement volumes informed baseline trajectory assumptions, with forward projections incorporating segmentation dimensions across product architecture, application environment, end-user category, and deployment channel. CAGRs were derived from regression-adjusted growth rates applied to regulatory mandate enforcement schedules and infrastructure upgrade cycles. Forecast inputs included USP Chapter 800 inspection intensity projections and robotic compounding system installation rates at hospital pharmacy facilities.
Inputs from FDA premarket notification databases and EMA conformity assessment registries were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around quarterly volume estimates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and elastomer supply stability. A model refresh is warranted upon material change in EPA hazardous pharmaceutical waste rule finalization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Oxygenator Market
Medical Devices
Intermittent Catheters Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Heating Pads Market
Medical Devices
Low Vision Aids Market