
 Spinal Needles Market | 2026-2036
Spinal Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Needles Market Outlook
Aftermarket service revenue for needle maintenance and calibration is rewriting how suppliers capture lifetime value from spinal needle placements. Becton Dickinson and Company leverages its broad hospital contracting network to sustain recurring instrument service income. Medtronic anchors its position through deep integration with neuromodulation and spine navigation platforms. Smiths Medical competes by specializing in regional anesthesia delivery systems that bundle needles with procedural trays.
Spinal needles are hollow, beveled or non-cutting-tip instruments, typically manufactured from 304-grade stainless steel with 18-27 gauge diameters and lengths ranging from 1.5 to 5 inches, designed to penetrate the dura mater for intrathecal medication delivery, cerebrospinal fluid sampling, or epidural catheter introduction. Tuohy needles with curved Huber tips dominate epidural applications where catheter threading reliability determines procedural success, while pencil-point needles such as the Whitacre and Sprotte designs lead lumbar puncture and spinal anesthesia segments due to reduced post-dural puncture headache incidence. Stainless steel remains the default material specification across hospital procurement standards, though coated steel variants are gaining traction in pain management clinics seeking enhanced tactile feedback during fluoroscopic guidance.
The FDA enforces Class II medical device controls through 510(k) premarket notification pathways for spinal needles, while the EU Medical Device Regulation mandates notified body conformity assessment and CE marking with enhanced clinical evidence requirements under MDR Article 9. ISO 7864 specifies sterile hypodermic needle performance testing that manufacturers must satisfy for international market access, directly shaping product validation timelines and R&D allocation. Stakeholders must monitor how evolving FDA guidance on reusable versus single-use spinal access instruments reshapes capital expenditure and disposable revenue mix across their installed base strategies.
Market Dynamics
The spinal needles market is experiencing structural compression as ambulatory surgical centers consolidate purchasing power and demand bundled anesthesia delivery systems rather than standalone instruments. This shift from acute care hospital procurement to outpatient facility contracting is redrawing competitive boundaries around procedural tray integration and service-level agreements.
Growth Catalysts
- Same-day surgery expansion:United States, Germany, and Japan are expanding ambulatory procedure volumes for spinal anesthesia and pain management interventions, creating concentrated demand corridors for specialized needle configurations.
- MDR Article 9 compliance:Enhanced clinical evidence requirements under the EU Medical Device Regulation are elevating barriers for marginal suppliers, consolidating market access around established manufacturers with robust quality management systems.
- Pencil-point needle adoption:Whitacre and Sprotte tip designs are displacing cutting-tip alternatives in lumbar puncture applications due to demonstrated reductions in post-dural puncture headache incidence.
Market Restraints
- 304-grade stainless steel price volatility:Raw material cost fluctuations for medical-grade steel alloys compress margin structures for manufacturers without backward integration into metal sourcing.
- FDA 510(k) pathway congestion:Premarket notification backlogs for Class II spinal access devices extend product launch timelines and defer revenue recognition for novel tip geometries.
- Reusable instrument competition:FDA guidance evolution on reusable versus single-use spinal access instruments threatens disposable revenue streams in cost-conscious hospital systems.
Strategic Opportunities
- Pain management clinic expansion:Fluoroscopy-guided spinal procedures in outpatient settings create demand for coated steel variants with enhanced tactile feedback properties.
- Regional anesthesia bundling:Procedural tray integration combining Tuohy needles with catheter systems captures higher per-procedure revenue than standalone instrument sales.
- ISO 7864 harmonization:Convergence around international sterile hypodermic needle performance standards reduces validation costs for multi-market product launches.
Industry Challenges
- Quality management system certification:MDR notified body conformity assessment timelines frequently exceed 18 months, compressing effective patent protection windows for innovative tip designs.
- Legacy instrument service integration:Aftermarket calibration and maintenance capabilities require specialized technical training that many distributors lack, creating channel capability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Needles Market |
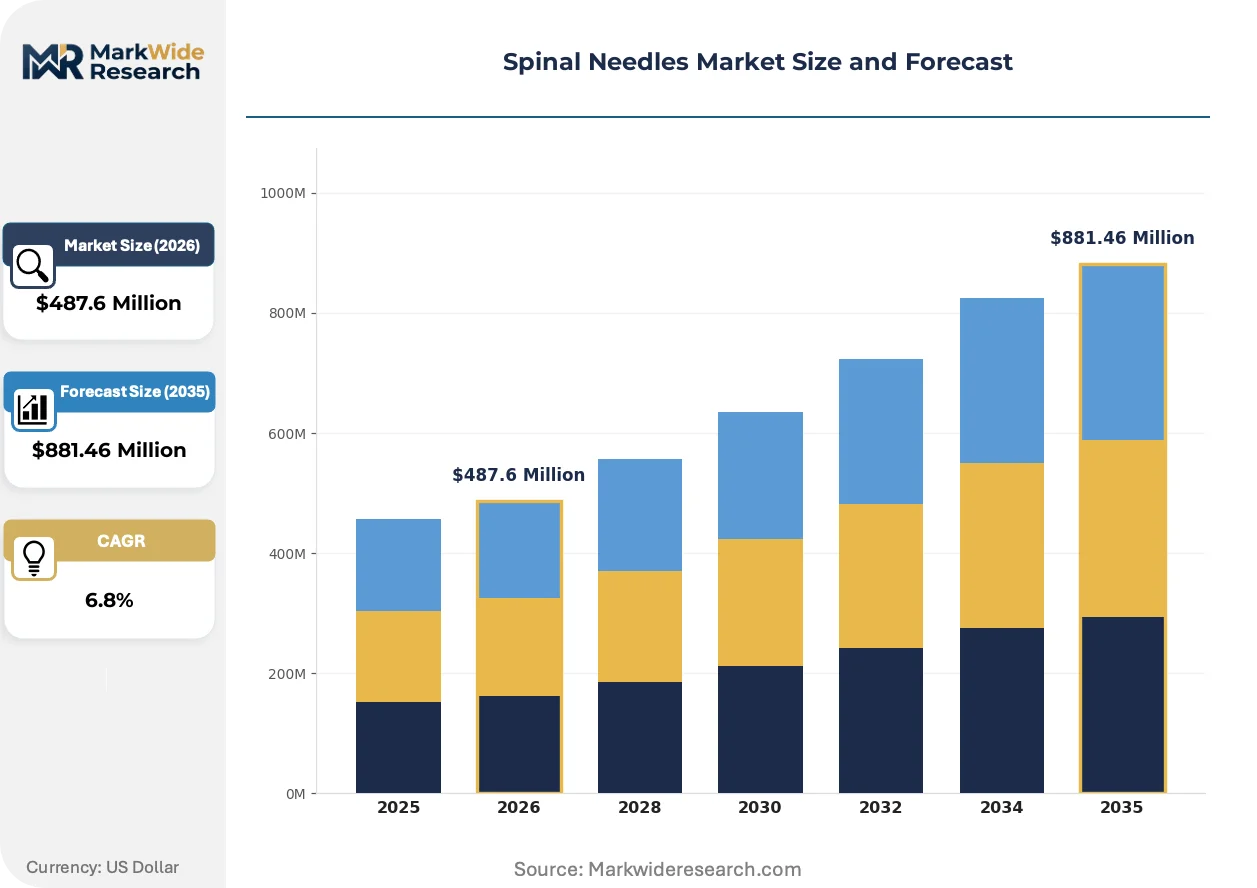
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Needles, Tuohy Needles, Pencil-Point Needles, Epidural Needles Material: Stainless Steel, Plastic, Coated Steel, Alloy Application: Anesthesia, Pain Management, Diagnostic Procedures, Surgical Procedures End User: Hospitals, Clinics, Surgical Centers, Research Facilities |
| Companies Covered | Boston Scientific Corporation, Smiths Medical, B. Braun Melsungen AG, Argon Medical Devices, Cook Medical, Becton Dickinson and Company, Medtronic, Nipro Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Needles Market Strategic Shifts
Active innovation in spinal needle design is compressing the performance gap between premium and standard product tiers while regulatory harmonization efforts streamline multi-market access strategies. These forces are simultaneously enabling manufacturer margin defense and buyer cost containment.
Coated steel variants with enhanced fluoroscopic visibility are collapsing the distinction between premium tactile feedback instruments and economy-grade alternatives. Pain management clinics performing image-guided interventions are adopting these materials at accelerating rates. The technology is collapsing price premiums previously commanded by specialized tip geometries alone.
EU Medical Device Regulation enforcement through notified body conformity assessment is elevating clinical evidence requirements for CE marking. Manufacturers must now submit expanded technical documentation and post-market surveillance plans. Spinal anesthesia product lines with legacy approvals face renewal pressure that favors larger competitors with dedicated regulatory affairs infrastructure.
Aftermarket service unbundling from instrument procurement contracts is restructuring supplier-buyer relationships. Ambulatory surgical centers are separating needle purchases from maintenance agreements, pressuring bundled pricing models. This pattern is most visible in United States contracting where group purchasing organizations negotiate discrete line items for capital equipment, disposables, and technical service.
Spinal Needles Market Segmentation
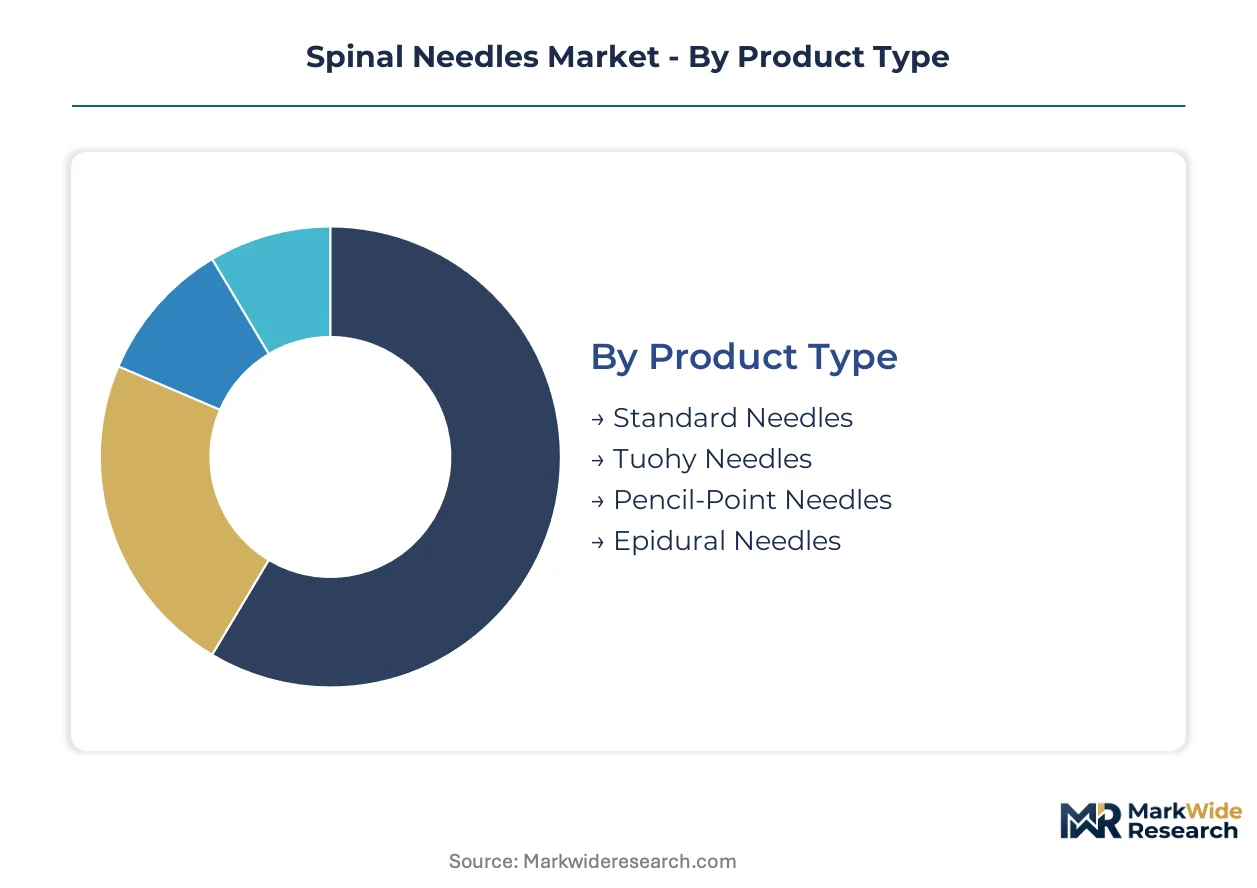
Spinal needle segmentation reveals how procurement patterns fragment across clinical settings. Each dimension carries distinct service intensity requirements that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply by tip geometry complexity. Tuohy and pencil-point designs demand calibration protocols that standard cutting-tip alternatives rarely require.
- Standard Needles:These cutting-tip instruments serve high-volume lumbar puncture applications with minimal technical support overhead. Procurement concentrates in United States emergency departments where cost-per-procedure metrics dominate vendor selection.
- Tuohy Needles:Huber-tip curved designs enable reliable epidural catheter threading through dense ligamentum flavum. German ambulatory surgical centers specify these configurations for same-day orthopedic procedures requiring continuous anesthesia delivery.
- Pencil-Point Needles:Whitacre and Sprotte tip geometries reduce post-dural puncture headache incidence through dural fiber separation rather than cutting.
- Epidural Needles:Specialized large-bore instruments accommodate catheter introduction for extended pain management protocols.
Standard needles hold the largest share; momentum sits with pencil-point configurations.
Material:
Material cost tiers determine margin structures and aftermarket revenue potential. Coated variants command premium positioning through enhanced fluoroscopic visibility.
- Stainless Steel:304-grade medical steel remains the procurement default across hospital purchasing standards. Japanese acute care facilities specify this material for MRI-compatible instrument sets where magnetic interference must be eliminated.
- Coated Steel:Fluoropolymer and parylene coatings enhance tactile feedback during image-guided interventions. United States pain management clinics in Florida and Texas are adopting these variants for fluoroscopy-directed spinal procedures at accelerating rates.
- Plastic:Disposable polymer alternatives serve research and training environments where sterilization infrastructure is limited.
- Alloy:Nickel-titanium and specialized metallurgical formulations address niche flexibility requirements in complex anatomical approaches.
Stainless steel dominates procurement volumes; coated steel variants are expanding most quickly.
Application:
Application segmentation tracks how procedural settings reshape instrument specification requirements. Anesthesia delivery demands bundled tray configurations that diagnostic applications rarely require.
- Anesthesia:Spinal and epidural anesthesia for cesarean delivery, orthopedic surgery, and urological procedures requires precise gauge selection and tip geometry matching. German same-day surgical facilities are consolidating purchasing around integrated anesthesia delivery systems rather than standalone instruments.
- Pain Management:Chronic back pain interventions, cancer pain protocols, and palliative care applications drive demand for coated steel variants with enhanced fluoroscopic visibility. United States outpatient clinics in Arizona and Nevada specify these for image-guided injection procedures.
- Diagnostic Procedures:Lumbar puncture for meningitis evaluation, subarachnoid hemorrhage detection, and multiple sclerosis monitoring employs standard cutting-tip or pencil-point configurations.
- Surgical Procedures:Intraoperative cerebrospinal fluid drainage and intrathecal chemotherapy administration require specialized large-bore access.
Anesthesia captures the largest application share; pain management shows the steepest expansion trajectory.
End User:
End-user concentration determines contracting leverage and service bundling requirements. Surgical centers are unbundling instrument procurement from maintenance agreements.
- Hospitals:Acute care facilities maintain diversified instrument inventories across anesthesia, neurology, and emergency medicine departments. United States health systems in California and New York negotiate multi-year service agreements covering calibration, repair, and replacement protocols.
- Surgical Centers:Ambulatory facilities performing same-day spinal anesthesia and pain management concentrate purchasing power through group purchasing organizations. Japanese day-surgery clinics are expanding procedural volumes fastest.
- Clinics:Outpatient pain management and diagnostic facilities drive coated steel adoption for fluoroscopy-guided interventions.
- Research Facilities:Academic medical centers and contract research organizations require specialized configurations for clinical trial protocols.
Hospitals retain the largest installed base; surgical centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spinal needle procurement patterns diverge sharply across major markets. The United States prioritizes ambulatory surgical center integration, Germany emphasizes same-day orthopedic anesthesia protocols, and Japan concentrates acute care demand within hospital-based neurology departments.
United States
Group purchasing organizations consolidate procurement for ambulatory surgical centers across Florida, Texas, and Arizona. FDA 510(k) premarket notification pathways govern Class II spinal access device approvals. Pain management clinics in Phoenix and Dallas drive coated steel variant adoption for fluoroscopy-guided interventions.
Germany
Same-day surgical facilities in Bavaria and North Rhine-Westphalia specify Tuohy needle configurations for continuous epidural anesthesia. EU Medical Device Regulation notified body conformity assessment elevates clinical evidence requirements under MDR Article 9. The Munich surgical cluster anchors procurement for integrated anesthesia delivery systems.
Japan
Acute care hospitals in Tokyo and Osaka maintain diversified inventories across anesthesia and neurology departments. PMDA medical device approval pathways align with international harmonization standards. Day-surgery clinics in the Kanto region are expanding spinal anesthesia volumes fastest among OECD markets.
United Kingdom
NHS procurement frameworks prioritize cost-per-procedure metrics for lumbar puncture applications in emergency departments. MHRA post-market surveillance requirements align with EU MDR transition timelines. The London metropolitan health system negotiates multi-year service agreements covering calibration and replacement protocols.
Australia
TGA medical device registration pathways facilitate market access for ISO 7864-compliant sterile hypodermic needle products. Pain management clinics in New South Wales and Victoria adopt coated steel variants for image-guided spinal procedures. The Sydney metropolitan cluster concentrates demand for pencil-point needle configurations in diagnostic applications.
Spinal Needles Market Competitive Environment
Capability concentration sits with specialized regional anesthesia system integrators; scale advantage sits with diversified hospital contracting networks. The market structures around three tiers: integrated medical technology conglomerates with neuromodulation platforms, dedicated anesthesia delivery specialists with procedural tray bundling expertise, and regional manufacturers with ISO-certified production capacity. Dominant competitive moves include backward integration into 304-grade stainless steel sourcing and strategic partnerships with ambulatory surgical center group purchasing organizations.
Within the integrated technology tier, Medtronic and Boston Scientific Corporation exemplify platform-anchored positioning through deep neuromodulation and spine navigation integration. Becton Dickinson and Company occupies a scale-driven position leveraging broad hospital contracting networks. Smiths Medical represents the specialized anesthesia delivery archetype with regional anesthesia system bundling expertise.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Smiths Medical |
| B. Braun Melsungen AG |
| Argon Medical Devices |
| Cook Medical |
| Becton Dickinson and Company |
| Medtronic |
| Nipro Corporation |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
304-grade stainless steel price volatility compresses margin structures for manufacturers lacking backward integration into metal sourcing, forcing tiered pricing that separates premium coated variants from economy-grade cutting-tip instruments while reshaping procurement patterns toward multi-year service bundling.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with group purchasing organizations negotiating multi-year contracts that bundle instrument supply with calibration services. Price differentiation rests on ISO 7864 compliance tier and after-sales service intensity, with ambulatory surgical centers exhibiting highest sensitivity due to unbundled procurement mandates. Cost compression in standard needle tiers intensifies because raw material fluctuations transmit directly to manufacturers without captive steel supply.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized medical device foundries in Germany, Japan, and the United States holding ISO 13485-certified capacity for precision needle grinding. Production draws from 304-grade stainless steel feedstock, fluoropolymer coating chemistries, and sterile packaging materials. Single-source vulnerability concentrates in Japanese steel alloy suppliers serving MRI-compatible instrument specifications. Distribution runs through hospital contracting networks and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pencil-point needle adoption represents a high-growth disruption as Whitacre and Sprotte tip designs displace cutting-tip alternatives, with FDA guidance evolution on reusable instruments creating additional inflection pressure across procurement patterns.
For Market Incumbents: Harden quality management system certification against MDR Article 9 renewal timelines that compress effective patent protection windows. Deepen backward integration into 304-grade stainless steel sourcing to defend margin position against commodity volatility. Anchor installed base through neuromodulation platform integration that raises switching costs for hospital systems. For New Entrants and Emerging Players: Pursue pain management clinic expansion in fluoroscopy-guided intervention settings where coated steel variant demand outpaces established supply relationships. Target United States outpatient facilities in Arizona and Nevada as the most penetrable geography given accelerating procedural volume growth. Lead with tactile feedback differentiation and rapid CE marking pathways under ISO 7864 harmonization. For Investors and Strategic Acquirers: EU Medical Device Regulation enforcement reshapes the acquisition landscape toward targets with dedicated regulatory affairs infrastructure and notified body relationships. Long-term viability centers on anesthesia delivery system integrators with procedural tray bundling capabilities. Monitor FDA 510(k) pathway congestion metrics as the signal to watch for revenue recognition timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 9 compliance elevates barriers for marginal suppliers without clinical evidence infrastructure. |
| Hospital System Partnership | Group purchasing organization contracts secure multi-year revenue visibility across ambulatory networks. |
| Backward Integration | Captive 304-grade stainless steel supply insulates margin structures from medical alloy price volatility. |
| Software Companion Development | Navigation platform integration raises switching costs in spine surgery and neuromodulation segments. |
| Reimbursement Strategy | Same-day surgery expansion in United States and Germany creates procedure volume tailwinds for anesthesia delivery. |
Study Parameters
Initial hypotheses were tested against primary input from anesthesia department heads, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and ISO standard revision records. Bottom-up demand modeling across tip geometry configurations converged with top-down market sizing through trade data triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, material grade, application setting, and end-user facility tier. CAGRs were derived from procedure volume trajectories and instrument replacement cycles specific to spinal anesthesia and pain management protocols. Forecast inputs incorporated ambulatory surgical center expansion rates and regulatory approval timeline assumptions.
Sensitivities concentrate around FDA guidance evolution on reusable instruments, MDR notified body assessment backlogs, and 304-grade stainless steel commodity swings. Quarterly review of same-day surgery volume data and premarket notification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Lacrimal Devices Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
External Nasal Dilator Market