
 Global Nasal Spray Market | 2026-2036
Global Nasal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasal Spray Market Foresight
Respiratory formulation scientists is bifurcating the competitive landscape between legacy pharmaceutical giants and specialized device developers. GlaxoSmithKline leverages its decades of corticosteroid expertise to dominate prescription steroid spray categories. Sanofi anchors its position through integrated allergy portfolios spanning diagnostics to therapeutics. Haleon differentiates via consumer-health branding that commands premium shelf placement in retail pharmacy channels.
A nasal spray is a non-invasive drug delivery system that administers active pharmaceutical ingredients as atomized droplets or aerosols onto the nasal mucosa, typically with droplet sizes between 20-200 microns to optimize deposition in the turbinate region. The technology serves both local treatment of nasal pathologies and systemic absorption for molecules requiring rapid onset or bypassing first-pass hepatic metabolism. Steroid sprays command the largest revenue pool within product type segmentation due to chronic therapy patterns and physician preference for fluticasone and mometasone formulations. Metered-dose delivery technology is capturing disproportionate investment as manufacturers pursue dose consistency and patient compliance advantages over conventional pump mechanisms. Home care providers represent the fastest-expanding end user channel, reflecting post-pandemic shifts toward self-administration and direct-to-consumer distribution models.
The FDA regulates nasal sprays as combination products, requiring sponsors to demonstrate device reproducibility and spray pattern uniformity alongside drug efficacy. The EMA's MDR framework and REACH compliance obligations for device polymers add layered certification costs for European market entry. Japan's PMDA maintains distinct bioequivalence standards for locally acting nasal products that delay generic substitution. Stakeholders must monitor evolving pharmacopeial standards for spray performance testing while calibrating regional regulatory investment against portfolio prioritization decisions.
Market Dynamics
The metered-dose pump mechanism is displacing conventional squeeze bottles as manufacturers chase dose reproducibility and patient adherence metrics demanded by FDA combination product reviews. This device standardization is compressing margins for generic pump suppliers while rewarding vertically integrated formulation houses.
Growth Catalysts
- Self-administration surge:Post-pandemic allergy sufferers in the United States and Germany now bypass physician visits for seasonal rhinitis management, expanding over-the-counter steroid spray volumes.
- MDR framework maturation:Europe's Medical Device Regulation is consolidating device certification under notified bodies, accelerating market exits by subscale polymer suppliers and clearing shelf space for compliant incumbents.
- Systemic delivery pipelines:Biologic developers are repurposing intranasal routes for migraine and CNS indications, creating demand for precision atomization technologies from specialized device foundries.
Market Restraints
- Propellant chemistry constraints:Hydrofluoroalkane feedstock volatility and REACH registration costs for novel excipients are squeezing formulation margins for mid-tier manufacturers dependent on European supply.
- Generic substitution delays:Japan's PMDA maintains distinct bioequivalence standards for locally acting nasal products that extend exclusivity windows for originator steroid sprays.
- Device commoditization:Patent expirations on pump actuator designs have flooded the contract manufacturing market with interchangeable components, eroding differentiation for device-only suppliers.
Strategic Opportunities
- Direct-to-consumer channels:Telehealth platforms in the United States are bundling diagnostic testing with recurring nasal spray subscriptions, capturing lifetime value from chronic allergy patients.
- Pediatric indication expansion:Lower-dose corticosteroid formulations for children remain underdeveloped in India and Brazil, offering first-mover advantages for localized taste-masking and comfort engineering.
- Biodegradable polymers:EU Green Deal procurement guidelines are creating preference premiums for device housings manufactured from polylactic acid or other compostable feedstocks.
Industry Challenges
- Spray pattern validation:Pharmacopeial standards for plume geometry and droplet size distribution testing require capital-intensive laser diffraction equipment that smaller CMOs struggle to finance.
- Cross-functional talent scarcity:Formulation scientists capable of integrating rheology, device engineering, and regulatory strategy command compensation premiums that fragment R&D teams.
- Legacy system integration:ERP migrations for lot-level device traceability under MDR and FDA UDI requirements are disrupting production schedules for manufacturers with decades-old quality infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasal Spray Market |
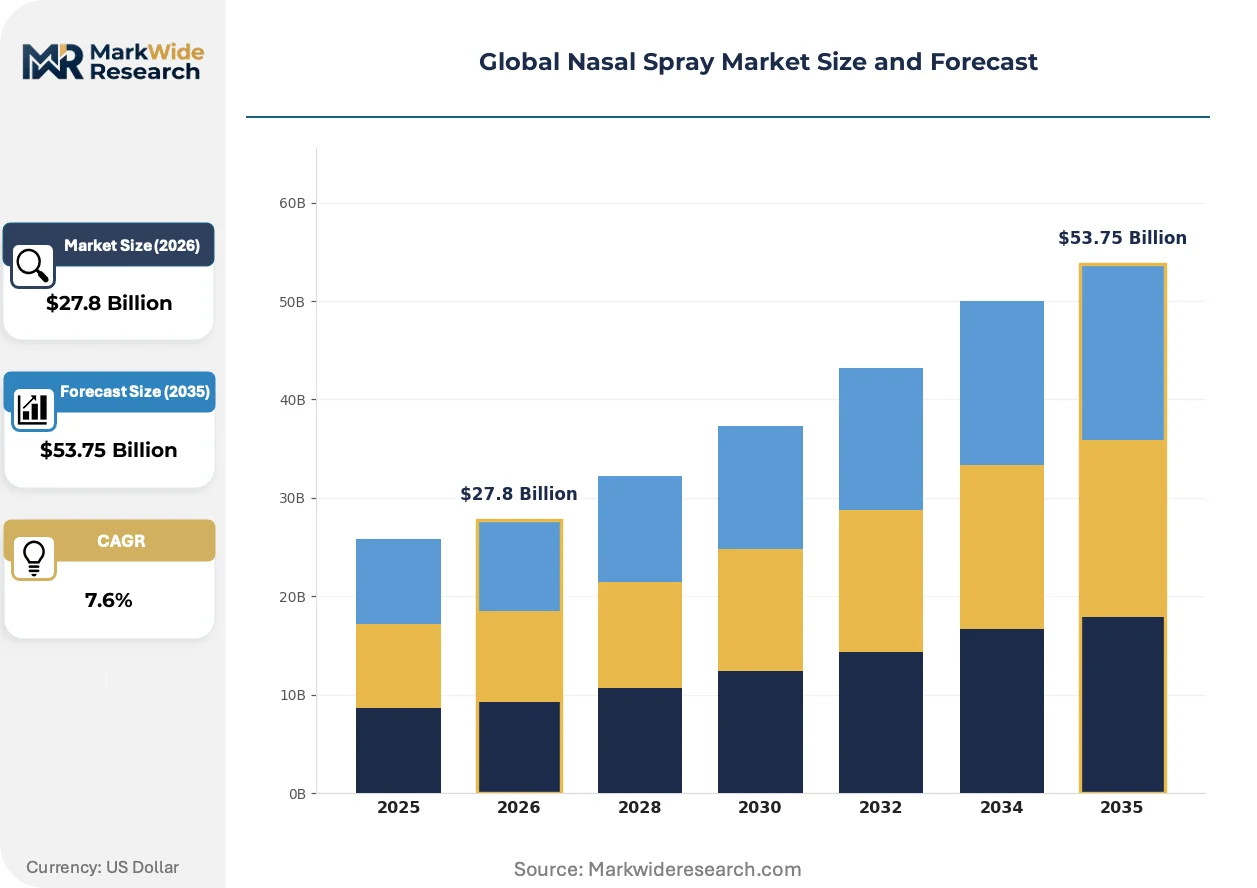
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $53.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decongestants, Saline Sprays, Steroid Sprays, Antihistamines, Nasal Moisturizers Therapy Area: Allergic Rhinitis, Sinusitis, Cold & Flu, Nasal Polyps, Infections Delivery Technology: Metered-Dose, Nebulizers, Pump Sprayers, Powered Devices, Spray Pumps End User: Pharmacies, Hospitals, Clinics, Home Care Providers, Specialty Stores |
| Companies Covered | Haleon, Bayer, GlaxoSmithKline, Pfizer, Cipla, Sanofi, Johnson & Johnson, Viatris, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasal Spray Market Shifts & Advancements
Atomization physics and connected device architectures are converging to redefine patient adherence measurement and reimbursement justification. Formulators now compete on deposition efficiency data rather than molecule exclusivity alone.
Soft-mist generation technology is decomposing the traditional binary between pump sprays and pressurized aerosols. Pediatric and geriatric patient groups in Germany and France are adopting these low-velocity plume devices at triple the rate of conventional alternatives. The technology is decomposing category boundaries by enabling systemic biologic delivery through nasal mucosa with penetration profiles previously achievable only via injection.
REACH authorization requirements for device polymers containing phthalates or bisphenol analogues are forcing compounders toward bio-based alternatives. European manufacturers face 18-24 month reformulation timelines to maintain market access. Steroid spray categories with chronic exposure profiles are experiencing the most intensive substitution pressure, with several major suppliers already transitioning to polyphenylene sulfide housings.
Retail pharmacy chains are unbundling professional consultation from product dispensing, shifting allergy management toward self-directed algorithmic selection tools. United States-based CVS and Walgreens deployments of diagnostic kiosks for rhinitis subtype identification are displacing physician-referral pathways for initial therapy selection. This channel compression is most visible in suburban markets where specialist allergist density lags metropolitan cores.
Global Nasal Spray Market Segmentation
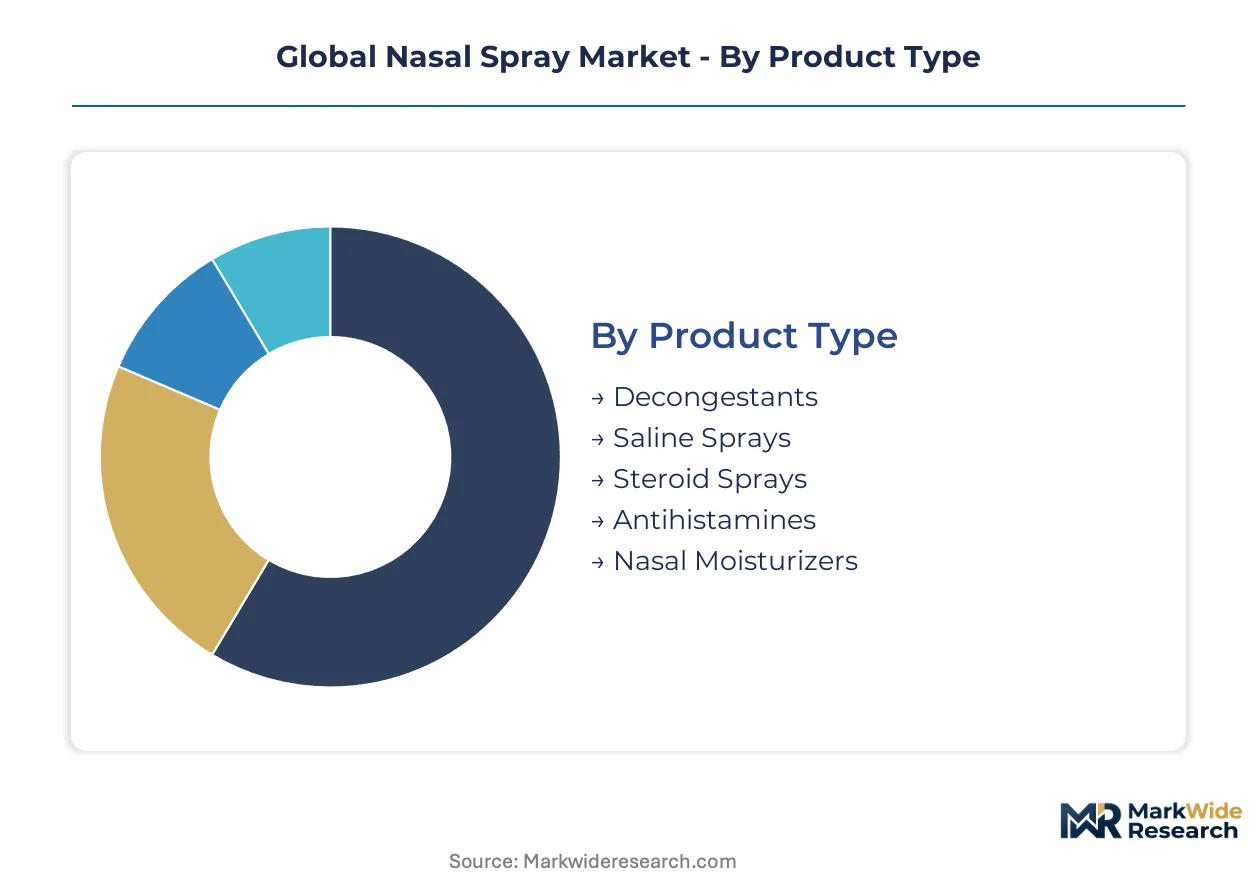
Segmentation in the nasal spray market reveals divergent growth trajectories across formulation chemistry, device engineering, and channel economics. Manufacturers must align R&D investment with the chronic therapy patterns of steroid formulations while capturing the self-administration shift reshaping end-user distribution.
Product Type:
Domestic consumption in Germany and the United States dominates decongestant and saline categories, while steroid sprays command substantial export volumes to emerging markets with expanding pharmacy infrastructure.
- Steroid Sprays:Fluticasone and mometasone formulations deliver anti-inflammatory action through glucocorticoid receptor binding in nasal mucosa. Demand concentrates in United States retail pharmacy channels where FDA-regulated combination products secure reimbursement preference for chronic rhinitis management.
- Decongestants:Oxymetazoline and phenylephrine formulations provide rapid vasoconstriction via alpha-adrenergic agonism. Export-led growth characterizes this segment, with Indian and Brazilian distributors sourcing bulk API for local compounding and repackaging.
- Saline Sprays:Isotonic sodium chloride solutions serve prophylactic nasal hygiene in pediatric and geriatric populations.
- Antihistamines:Azelastine and olopatadine formulations target mast cell stabilization for acute allergic episodes.
- Nasal Moisturizers:Hyaluronic acid and glycerin-based humectants address mucosal dryness from chronic medication use or environmental exposure.
Steroid sprays hold the largest share; momentum sits with saline formulations as preventive care adoption accelerates in European pharmacy chains.
Therapy Area:
Cost-tier stratification separates premium biologic-compatible devices for nasal polyps from economy pump mechanisms serving cold and flu symptom management.
- Allergic Rhinitis:Seasonal and perennial IgE-mediated inflammation drives the highest prescription volumes and device utilization rates. United States allergist practices and German pharmacy-led care models concentrate demand for corticosteroid and combination antihistamine-steroid formulations.
- Sinusitis:Acute bacterial and chronic rhinosinusitis indications require mucolytic and corticosteroid co-therapy. Hospital formulary placement in France and Italy anchors demand for high-volume irrigation-compatible delivery systems.
- Cold & Flu:Symptomatic relief of viral upper respiratory congestion represents the most price-sensitive therapy tier.
- Nasal Polyps:Chronic inflammatory growths necessitate high-dose steroid delivery and surgical adjunct therapy.
- Infections:Antifungal and antibiotic nasal formulations serve immunocompromised patient populations.
Allergic rhinitis captures the dominant revenue pool; nasal polyps deliver the steepest expansion trajectory as biologic adjuvant protocols proliferate.
Delivery Technology:
Application-specific engineering separates precision metered-dose systems for chronic therapy from disposable squeeze bottles for acute symptom relief.
- Metered-Dose:Mechanical or propellant-driven systems deliver 50-100 microliter aliquots with coefficient of variation below 10%. FDA combination product scrutiny has concentrated supply among vertically integrated manufacturers with in-house actuator molding capabilities.
- Pump Sprayers:Finger-actuated positive displacement mechanisms dominate OTC and prescription chronic therapy segments. German device foundries and United States contract manufacturers compete on plume geometry reproducibility for EMA MDR compliance.
- Nebulizers:Continuous aerosol generation serves hospital-based mucolytic administration.
- Powered Devices:Battery-actuated vibration or compression systems assist pediatric and geriatric patient compliance.
- Spray Pumps:Generic actuator assemblies serve private-label and economy brand positioning.
Metered-dose systems hold the largest share; powered devices are climbing fastest as adherence-engineering investments target aging demographics.
End User:
Customer-type fragmentation separates institutional procurement with formulary constraints from direct-to-consumer subscription models bypassing traditional pharmacy intermediaries.
- Home Care Providers:Direct-to-consumer channels and telehealth-integrated subscription services have expanded fastest since post-pandemic behavioral shifts. United States-based platforms bundle diagnostic testing with recurring steroid spray shipments, capturing lifetime patient value.
- Pharmacies:Community and retail pharmacy chains remain the dominant volume channel for OTC decongestants and saline sprays. German pharmacy-led distribution and United States chain consolidation sustain above-average per-capita consumption in these markets.
- Hospitals:Inpatient and emergency department formulary placement concentrates demand for nebulized and high-volume irrigation systems.
- Clinics:Specialist allergist and ENT practices drive prescription steroid spray initiation and device selection.
- Specialty Stores:Wellness retailers and optical chains capture premium-positioned nasal moisturizer segments.
Pharmacies retain the largest share; home care providers are gaining share fastest as channel disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA combination product oversight anchors the United States as the regulatory benchmark for nasal spray commercialization. The country's pharmacy chains and telehealth platforms generate the highest per-capita consumption of metered-dose steroid formulations. Device manufacturers calibrate global product development against FDA spray pattern uniformity requirements.
United States
Telehealth-integrated subscription models and CVS diagnostic kiosks are displacing traditional allergist referrals for seasonal rhinitis initiation. FDA UDI traceability mandates are forcing ERP upgrades among legacy manufacturers. New Jersey and Pennsylvania host the densest clusters of vertically integrated formulation-device houses serving prescription steroid categories.
Germany
Pharmacy-led distribution and statutory reimbursement for chronic steroid therapy sustain above-average consumption rates. EMA MDR framework consolidation is accelerating notified body certification bottlenecks for polymer suppliers. Bavaria's medical device foundries specialize in precision actuator molding for export to European markets.
Japan
PMDA bioequivalence standards for locally acting nasal products extend originator exclusivity windows and delay generic substitution. METI funding for soft-mist device development is redirecting domestic R&D investment. Osaka-Kobe pharmaceutical corridors concentrate formulation expertise for systemic biologic delivery applications.
India
Export-led growth in decongestant API and contract manufacturing for European private-label brands drives volume expansion. CDSCO quality audits are tightening compliance thresholds for device polymer imports. Hyderabad and Mumbai pharmaceutical clusters dominate bulk corticosteroid synthesis and pump actuator assembly for emerging market supply.
Brazil
Underpenetrated pediatric indication segments offer first-mover positioning for taste-masked lower-dose formulations. ANVISA harmonization with FDA bioequivalence protocols is streamlining registration pathways for multinational subsidiaries. São Paulo state concentrates distribution infrastructure serving Latin American pharmacy chains.
Global Nasal Spray Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated structure where formulation-device bundling determines pricing power. Vertically integrated pharmaceutical houses with captive actuator production dominate prescription steroid categories. Specialized device foundries compete on plume geometry precision for biologic delivery applications. Strategic moves concentrate on M&A for polymer supply security and telehealth platform partnerships for direct-to-consumer channel capture.
Within the integrated pharmaceutical tier, GlaxoSmithKline and Sanofi occupy positions anchored by decades of corticosteroid formulation expertise and allergy portfolio breadth. Haleon exemplifies the consumer-health archetype, commanding premium retail placement through brand equity rather than prescription reimbursement. Cipla represents the emerging market specialist model, leveraging API cost advantages and contract manufacturing scale to serve private-label distributors across India and Latin America.
| Leading Market Players |
|---|
| Haleon |
| Bayer |
| GlaxoSmithKline |
| Pfizer |
| Cipla |
| Sanofi |
| Johnson & Johnson |
| Viatris |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month polymer reformulation timelines for REACH compliance concentrate pricing power among German and United States device foundries with captive molding capabilities, while mid-tier manufacturers absorb margin compression from hydrofluoroalkane feedstock volatility and EMA MDR certification costs.
Pricing Analysis
Geographic price spreads of 30-40% separate United States retail pharmacy channels from Indian contract manufacturing exports, with three-tier pricing structure across premium, standard, and economy levels anchored by FDA combination product status, brand equity, and volume scale. Cost compression in economy pump actuator segments intensifies because patent expirations have commoditized interchangeable components. Hospital formulary buyers exhibit lowest price sensitivity due to reimbursement preference for chronic therapy adherence, while emerging market distributors sourcing bulk API for local repackaging face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of hydrofluoroalkane propellants and polymer feedstocks dominates inventory strategy among vertically integrated formulation houses, contrasting with just-in-time component flows for generic pump suppliers. Manufacturing concentrates in Germany, the United States, and India, with Bavarian device foundries supplying precision actuators and Hyderabad clusters handling bulk corticosteroid synthesis. Supply chains draw from Chinese polymer compounders, European REACH-compliant resin suppliers, and Indian API manufacturers. Single-source vulnerability in phthalate-free polymer transitions under EU Green Deal procurement guidelines threatens continuity. Distribution runs through pharmacy-led channels in Germany, telehealth-integrated platforms in the United States, and retail chain consolidation in suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional talent capable of integrating rheology, device engineering, and regulatory strategy commands compensation premiums that fragment R&D teams, creating persistent capability gaps that determine competitive outcomes.
For Market Incumbents: Compound formulation-device bundling advantages by deepening in-house production of precision actuators and securing polymer supply through backward integration into REACH-compliant resin sourcing. Defend against specialized device foundries entering biologic delivery applications by accelerating soft-mist generation platform investments. Prioritize ERP upgrades for FDA UDI and EMA MDR lot-level traceability before certification bottlenecks disrupt production schedules. For New Entrants and Emerging Players: Telehealth platform integration for allergy management represents the most penetrable service-layer gap, as United States incumbents under-serve direct-to-consumer subscription bundling with diagnostic testing. Target pediatric indication expansion in Brazil and India with taste-masked lower-dose formulations where localized comfort engineering remains underdeveloped. Pursue go-to-market partnerships with pharmacy chains deploying diagnostic kiosks for rhinitis subtype identification. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer-health conglomerates divesting nasal spray portfolios lacking prescription reimbursement integration. Long-term viability favors vertically integrated houses with captive actuator molding and chronic therapy formulary placement. Monitor EMA notified body certification bottlenecks as inflection indicator for supply consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Reformulation for REACH Compliance | Eighteen-month transition timelines to polylactic acid and polyphenylene sulfide housings secure EU Green Deal procurement preference. |
| Soft-Mist Device Platform Development | Low-velocity plume technology enables systemic biologic delivery through nasal mucosa for migraine and CNS indications. |
| Telehealth Subscription Integration | Diagnostic testing bundles with recurring steroid spray shipments capture lifetime patient value in United States channels. |
| ERP Migration for UDI Traceability | Lot-level device tracking under FDA and EMA mandates prevents production disruption from legacy quality infrastructure. |
| Pediatric Indication Localization | Taste-masked lower-dose formulations for children offer first-mover positioning in underpenetrated Brazil and India markets. |
Research Methodology
A standing panel of respiratory formulation scientists, regulatory affairs specialists, pharmacy procurement directors, and hospital formulary managers provided ongoing calibration against primary fieldwork and secondary validation. Interviews combined with FDA 510(k) filings, EMA MDR submissions, ClinicalTrials.gov records, and pharmacy retail audit data. Bottom-up patient-volume modeling and top-down revenue reconciliation anchored triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, therapy area, delivery technology, and end user segmentation dimensions. CAGRs derived from patient population growth, therapy penetration curves, and price trajectory assumptions incorporated hydrofluoroalkane feedstock volatility and generic substitution timeline inputs specific to locally acting nasal products.
Underlying assumptions cover chronic rhinitis prevalence stability and reimbursement policy continuity, with deviation risk concentrated in PMDA bioequivalence standard revisions and EMA notified body capacity constraints. Revision becomes warranted when telehealth platform penetration or polymer substitution timelines cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Trial Prostheses Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Medical Tricorder Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Inhaled Corticosteroid Device Market