
 Medical Device Outsourcing Market | 2026-2036
Medical Device Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Outsourcing Market Intelligence
ISO 13485 certification upgrades are reorganizing supplier qualification criteria across the contract manufacturing landscape. Sanmina Corporation leverages vertically integrated electronics manufacturing to dominate high-reliability printed circuit board assemblies for Class III devices. Integer Holdings Corporation anchors its position through specialized catheter and neurovascular component production. Jabil Inc. competes via global footprint scale, operating FDA-registered facilities across multiple cost tiers.
Medical device outsourcing encompasses the delegation of product design, component fabrication, final assembly, sterilization, regulatory filing support, and post-market surveillance to third-party specialists, typically governed by ISO 13485 quality management systems and FDA 21 CFR Part 820 compliance frameworks. The practice enables original equipment manufacturers to reduce fixed capital intensity while accessing specialized cleanroom molding, laser welding, or ethylene oxide sterilization capabilities that would require prohibitive in-house investment. Manufacturing services within the service type dimension sustain the largest revenue pool due to recurring purchase orders and multi-year supply agreements, though regulatory affairs outsourcing is expanding fastest as EU MDR technical documentation requirements overwhelm smaller OEM quality departments. Diagnostic equipment within the product type category commands premium pricing through complex optical alignment and precision fluidic handling that limits qualified supplier pools.
FDA Quality System Regulation enforcement, EU Medical Device Regulation notified body capacity constraints, and ISO 13485:2016 transition deadlines collectively determine market access viability for contract manufacturers. The FDA's intensified foreign supplier inspection program has redirected OEM sourcing decisions toward established registrants with proven inspection histories. Stakeholders must monitor notified body consolidation in Europe and FDA resourcing commitments for overseas inspections to anticipate qualification bottlenecks.
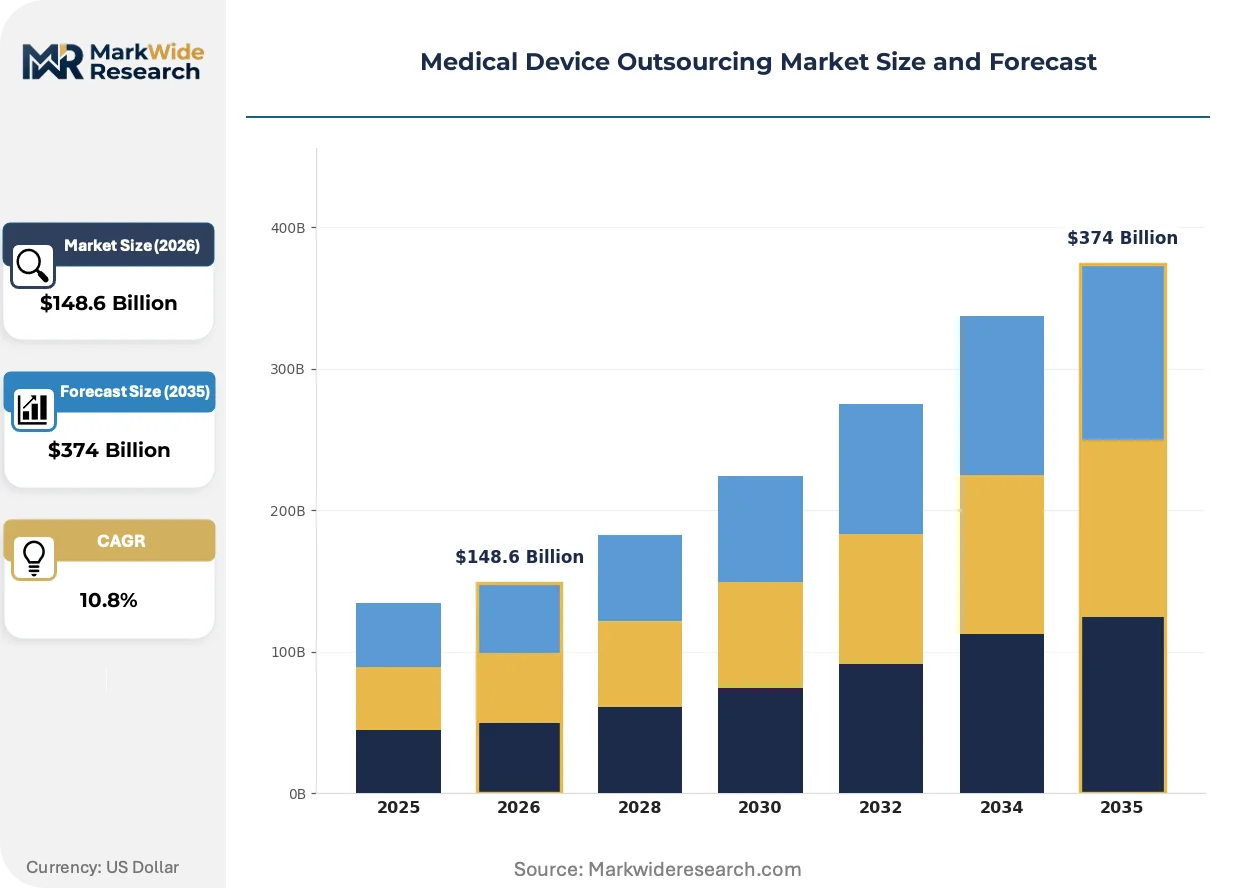
Market Dynamics
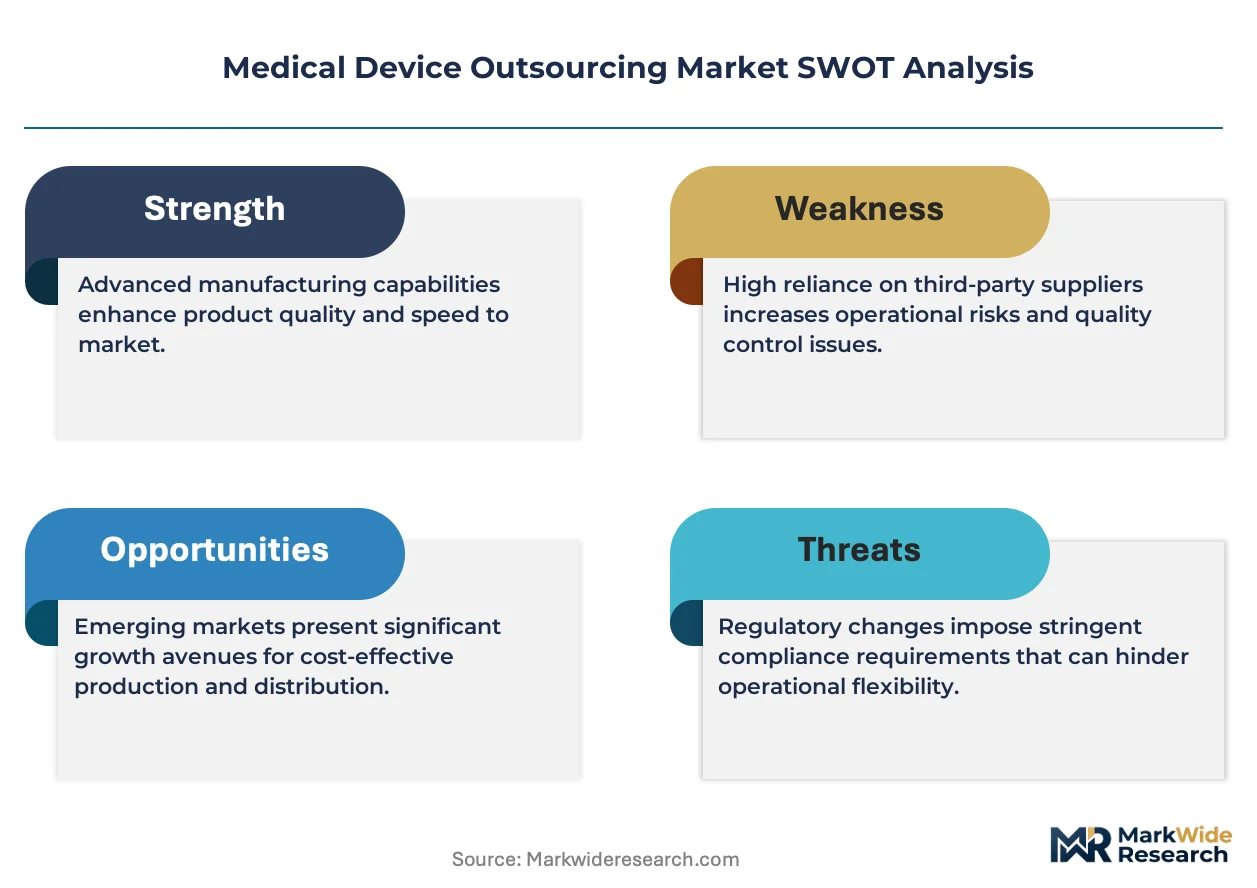
EU MDR notified body capacity constraints and FDA foreign supplier inspection intensification are compressing qualification timelines for contract manufacturers, forcing OEMs to consolidate supplier relationships around established registrants with proven compliance histories.
Growth Catalysts
- Ethylene oxide sterilization demand:Orthopedic implant manufacturers are expanding third-party sterilization contracts as in-house EtO capabilities face EPA emission scrutiny and facility upgrade costs.
- ISO 13485:2016 transition:Certification upgrades are disqualifying smaller machine shops from Class II and III device supply chains, concentrating purchase orders among qualified contract manufacturers.
- Ireland's Galway cluster:Multiple FDA-registered contract facilities serving European and North American OEMs are attracting sterilization and validation service expansions from multinational suppliers.
Market Restraints
- Notified body consolidation:EU MDR implementation has reduced the number of active notified bodies from over 80 to fewer than 40, creating certification bottlenecks for contract manufacturers seeking CE marking.
- Cleanroom molding capex requirements:ISO Class 7 and 8 cleanroom facilities for polymer component production require capital intensity that excludes mid-tier contract manufacturers from diagnostic and surgical device supply chains.
- Laser welding skill scarcity:Precision joining of nitinol and cobalt-chrome components for cardiovascular devices requires specialized technicians whose training pipelines remain underdeveloped across manufacturing regions.
Strategic Opportunities
- Neurovascular component production:Integer Holdings Corporation's specialized catheter manufacturing model demonstrates white space for contract manufacturers with micro-extrusion and braiding capabilities to serve stroke intervention device OEMs.
- Regulatory affairs outsourcing:EU MDR technical documentation requirements are overwhelming smaller OEM quality departments, creating demand for contract manufacturers offering bundled regulatory filing support.
- Printed circuit board assembly convergence:Sanmina Corporation's vertically integrated electronics manufacturing for Class III devices shows opportunity for contract manufacturers combining PCBA with final device assembly under single quality systems.
Industry Challenges
- 21 CFR Part 820 remediation timelines:FDA Quality System Regulation enforcement actions against foreign contract manufacturers are extending supplier qualification cycles and delaying product launches for dependent OEMs.
- Ethylene oxide supply chain reconfiguration:Sterilization facility closures due to community emission concerns are forcing OEMs to qualify alternative contract sterilizers across extended geographic distances.
- Multi-site quality system integration:Jabil Inc.'s global footprint scale requires harmonized FDA-registered facility management that smaller competitors struggle to replicate without enterprise-level quality infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Outsourcing Market |
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $374 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manufacturing, Design, Regulatory Affairs, Testing, Packaging End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Product Type: Surgical Devices, Diagnostic Equipment, Monitoring Devices, Therapeutic Equipment Technology: Robotics, Wearable Technology, Imaging, Biologics |
| Companies Covered | Sanmina Corporation, Plexus Corp., Flex Ltd., West Pharmaceutical Services, Celestica HealthTech, Jabil Inc., Integer Holdings Corporation, Phillips-Medisize, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Outsourcing Market Strategic Shifts & Innovations
Additive manufacturing for patient-specific orthopedic implants is reshaping production economics for contract manufacturers, compressing batch sizes while elevating regulatory scrutiny on process validation.
Laser powder bed fusion for titanium and cobalt-chrome orthopedic implants is bifurcating contract manufacturing capabilities between specialists with in-house metal additive qualifications and traditional CNC shops facing exclusion from patient-specific device supply chains. Spine and craniomaxillofacial OEMs are consolidating supplier relationships around additive-capable contract manufacturers. This technology is bifurcating the orthopedic implant outsourcing landscape into qualified additive specialists and commodity machining suppliers.
EU MDR's Unique Device Identification requirements and enhanced clinical evidence mandates are extending technical documentation preparation timelines for contract manufacturers supporting legacy device transitions. Notified body capacity constraints are forcing OEMs to prioritize their highest-margin product lines for recertification. Class III implantable device categories face the most severe qualification bottlenecks, with some contract manufacturers establishing dedicated EU MDR project offices in Dublin and Brussels.
Long-term supply agreements with embedded sterilization and regulatory support are displacing transactional component purchasing for high-risk device categories. OEM procurement functions are consolidating vendor bases around contract manufacturers offering vertically integrated design-through-distribution capabilities. This consolidation pattern is most visible in cardiovascular and neurovascular device segments, where single-source contract manufacturing relationships now span five-to-seven year terms with automatic renewal clauses.
Medical Device Outsourcing Market Segmentation
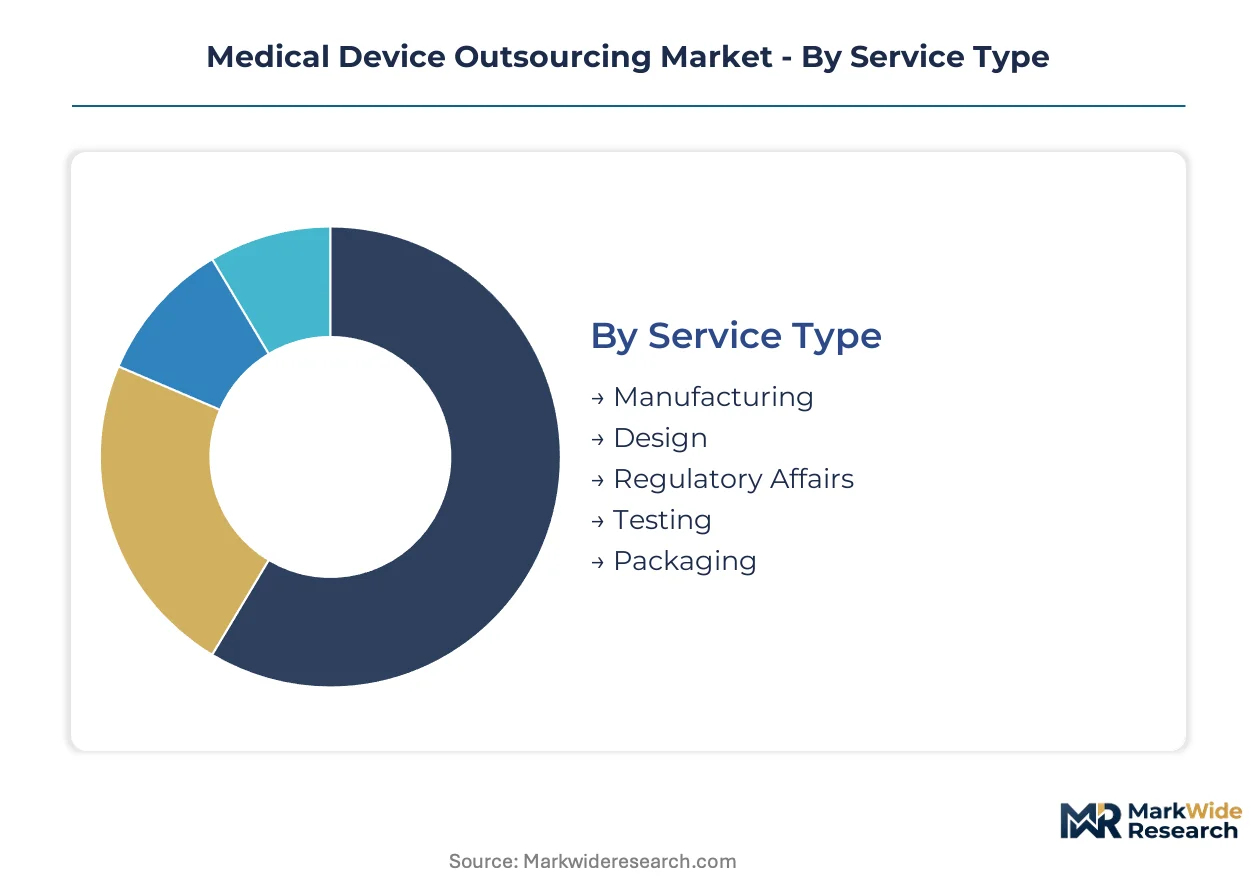
Segmentation in medical device outsourcing reveals where OEM procurement power concentrates and which service categories face displacement from in-house capability investments. Contract manufacturers compete differently across these dimensions, with quality system requirements and capital intensity creating divergent margin structures.
Service Type:
Regulatory Affairs outsourcing faces the strongest substitution pressure as larger OEMs build internal EU MDR technical documentation teams, while Manufacturing services resist displacement due to cleanroom and sterilization asset specificity.
- Manufacturing:Encompasses component fabrication, final assembly, and sterilization under ISO 13485 and FDA 21 CFR Part 820 frameworks. Demand concentrates in Ireland's Galway cluster and Costa Rica's medical technology free trade zones, driven by orthopedic implant OEMs seeking EtO sterilization capacity as EPA scrutiny forces facility closures in the United States.
- Regulatory Affairs:Covers technical documentation preparation, FDA 510(k) submissions, and EU MDR notified body correspondence. Smaller OEM quality departments in Germany and France are outsourcing CE marking support as notified body consolidation from over 80 to fewer than 40 organizations creates certification bottlenecks.
- Design:Includes industrial design, human factors engineering, and design-for-manufacturing optimization for Class II and III devices.
- Testing:Encompasses biocompatibility validation, sterilization efficacy verification, and accelerated aging studies per ISO 10993 and ISO 11137 standards.
- Packaging:Covers sterile barrier system design, accelerated shelf-life testing, and distribution simulation per ASTM D4169 protocols.
Manufacturing retains volume leadership; Regulatory Affairs holds the steepest expansion curve.
End User:
Procurement authority varies sharply across customer type, with hospital IDNs wielding consolidated contract manufacturing specifications that reshape supplier qualification requirements.
- Hospitals:Integrated delivery networks in the United States and national health systems in the United Kingdom are consolidating vendor bases around contract manufacturers with vertically integrated design-through-distribution capabilities. Multi-year sole-source agreements now span five-to-seven year terms with automatic renewal clauses for cardiovascular and orthopedic device categories.
- Diagnostic Centers:Independent imaging and laboratory facilities in Japan and South Korea demand precision fluidic handling and complex optical alignment that limits qualified supplier pools to specialists with ISO Class 7 cleanroom molding capabilities.
- Clinics:Outpatient surgical centers and physician office laboratories drive demand for single-use disposable devices with simplified sterilization validation requirements.
- Research Institutions:Academic medical centers and contract research organizations require small-batch production flexibility and expedited regulatory filing support for investigational device exemptions.
Hospitals dominate contract value; Diagnostic Centers are climbing the fastest on precision component demand.
Product Type:
Technology complexity and regulatory classification create tiered pricing structures across device categories, with Class III implantables commanding premium positioning.
- Diagnostic Equipment:Complex optical alignment, precision fluidic handling, and embedded electronics integration limit qualified supplier pools. Demand concentrates in Massachusetts and California medical technology corridors, where contract manufacturers combine PCBA with final device assembly under single quality systems.
- Surgical Devices:Encompasses minimally invasive instrumentation, electrosurgical units, and robotic surgery accessories requiring laser welding of nitinol and cobalt-chrome components.
- Monitoring Devices:Wearable and bedside patient monitoring systems with wireless connectivity and cybersecurity validation requirements.
- Therapeutic Equipment:Infusion pumps, ventilators, and dialysis systems with embedded software and human factors engineering demands.
Diagnostic Equipment commands margin leadership; Surgical Devices are gaining share fastest on robotics adoption.
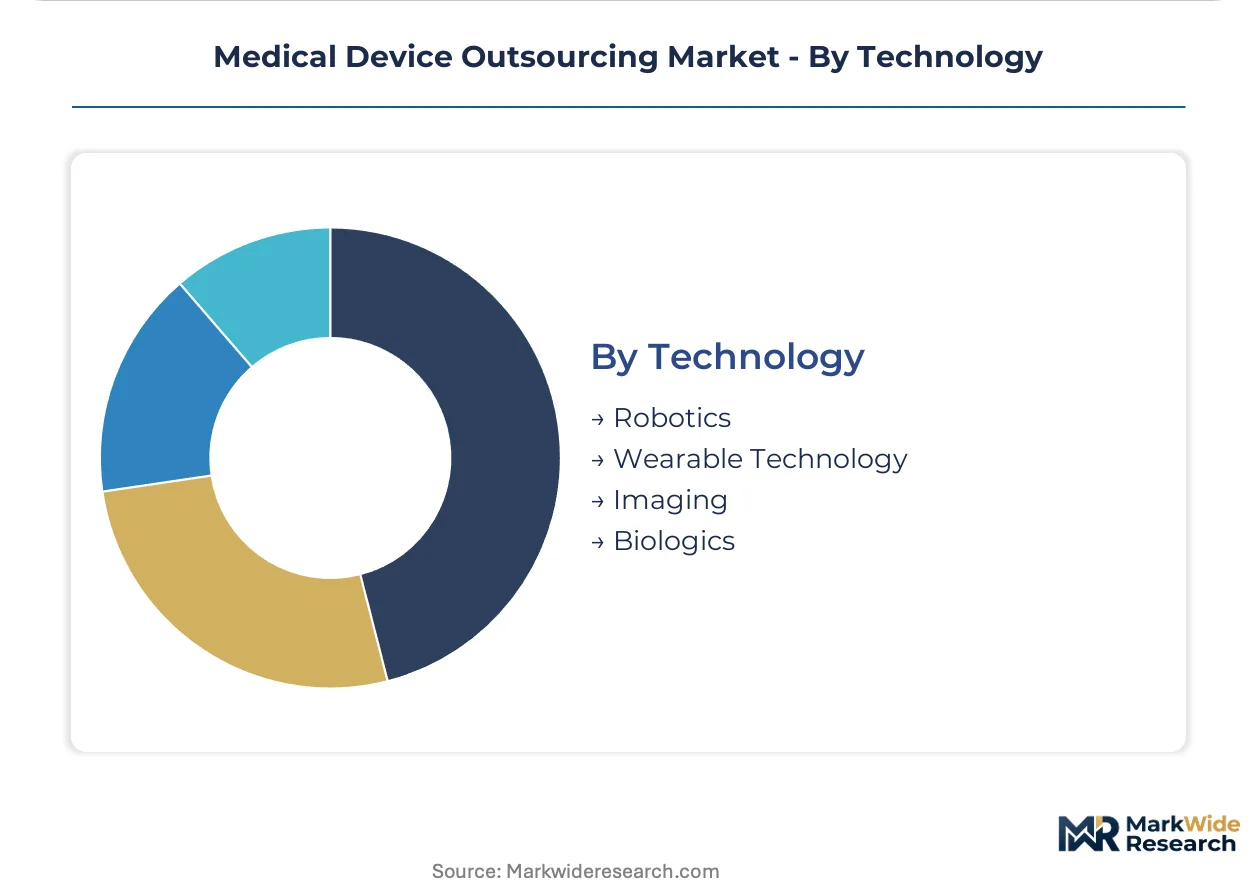
Technology:
Capital intensity and regulatory novelty separate mature technology platforms from emerging capability investments requiring specialized technician pipelines.
- Robotics:Surgical and rehabilitation robotics requiring precision motion control, haptic feedback systems, and IEC 62304 software lifecycle validation. Integer Holdings Corporation and Sanmina Corporation are consolidating supplier relationships around additive-capable contract manufacturers with in-house metal qualifications for patient-specific orthopedic implants.
- Imaging:MRI-compatible components, radiation shielding, and detector assembly with stringent electromagnetic compatibility requirements.
- Wearable Technology:Continuous glucose monitors, cardiac event recorders, and remote patient monitoring devices with biocompatibility and battery safety validation.
- Biologics:Combination products integrating living tissue or biologically active materials with device components, requiring aseptic processing and cell therapy manufacturing expertise.
Imaging sustains revenue concentration; Robotics is expanding most quickly on surgical automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in medical device outsourcing favor nations with dual FDA-EU regulatory alignment, as OEMs seek contract manufacturers capable of serving both North American and European markets without duplicate qualification cycles. Ireland and Costa Rica have built persistent trade surpluses in sterilization and finished device assembly, while Germany and Switzerland maintain net importer positions for high-complexity components.
United States
Orthopedic implant OEMs in Indiana and Massachusetts are expanding EtO sterilization contracts as EPA emission scrutiny forces facility upgrades. FDA intensified foreign supplier inspection programs are redirecting sourcing toward domestic FDA-registered contract manufacturers with proven inspection histories. The Minneapolis-St. Paul corridor concentrates catheter and cardiovascular device contract manufacturing, with Integer Holdings Corporation and Phillips-Medisize anchoring supplier relationships.
Ireland
Galway's medical technology cluster attracts sterilization and validation service expansions from multinational suppliers serving both European and North American OEMs. EU MDR notified body capacity constraints are forcing contract manufacturers to establish dedicated project offices in Dublin. Multiple FDA-registered facilities in the west coast region now handle complex polymer component production for Class III devices.
Germany
Smaller OEM quality departments in Baden-Württemberg and Bavaria are outsourcing EU MDR technical documentation preparation as notified body consolidation creates certification bottlenecks. The country's national pharmaceutical regulator enforces stringent post-market surveillance requirements that favor established contract manufacturers with harmonized quality systems. The Munich medical technology corridor concentrates precision machining and laser welding capabilities for cardiovascular devices.
Costa Rica
Medical technology free trade zones in the Central Valley region attract orthopedic implant OEMs seeking EtO sterilization capacity as US facility closures force supply chain reconfiguration. The country's export-oriented regulatory framework aligns with FDA Quality System Regulation requirements. Multiple contract manufacturers have expanded cleanroom molding operations to serve diagnostic equipment OEMs.
Switzerland
Swissmedic's rigorous device classification system favors contract manufacturers with ISO 13485:2016 certification upgrades for Class III implantable devices. The Lake Geneva region and Basel area concentrate precision component fabrication for neurovascular and spinal applications. Swiss orthopedic OEMs are consolidating supplier relationships around additive-capable contract manufacturers with in-house metal qualifications.
Medical Device Outsourcing Market Key Industry Players
Concentration sits with vertically integrated electronics specialists and dedicated medical device contract manufacturers possessing multi-site FDA registration. The vendor base separates into three tiers: global-scale diversified manufacturers with harmonized quality systems across cost tiers, mid-cap specialists with concentrated catheter or sterilization capabilities, and regional fabricators facing disqualification from Class II and III supply chains. Competitive moves center on M&A to acquire additive manufacturing qualifications and strategic partnerships to secure notified body capacity access.
Among diversified contract manufacturers, Sanmina Corporation exemplifies the vertically integrated electronics archetype through high-reliability printed circuit board assembly capabilities. Jabil Inc. occupies the global footprint scale position with FDA-registered facilities spanning multiple cost tiers. Integer Holdings Corporation anchors the specialized component tier through concentrated catheter and neurovascular production expertise. These three represent distinct competitive positioning vectors: electronics convergence, geographic arbitrage, and therapeutic specialization.
| Leading Market Players |
|---|
| Sanmina Corporation |
| Plexus Corp. |
| Flex Ltd. |
| West Pharmaceutical Services |
| Celestica HealthTech |
| Jabil Inc. |
| Integer Holdings Corporation |
| Phillips-Medisize |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
EtO sterilization capacity replacement by gamma and e-beam alternatives is simultaneously redrawing supplier geography toward Costa Rica and Ireland while compressing pricing power for legacy US sterilization networks facing EPA compliance costs. This substitution dynamic concentrates procurement leverage with orthopedic OEMs capable of qualifying multi-modal sterilization pathways across dual-registered facilities.
Pricing Analysis
Industrial OEM buyers anchor contract manufacturing pricing through multi-year sole-source agreements spanning five-to-seven year terms with automatic renewal clauses. Three-tier pricing structure across FDA-registered premium, ISO 13485-standard, and non-certified economy suppliers reflects certification grade and volume scale differentiation. Cost compression in standard-tier component supply is intensifying because notified body consolidation has reduced qualified supplier pools. Hospital IDNs wield the least price sensitivity due to patient-risk liability, while outpatient surgical centers drive aggressive standard-tier negotiation.
Supply Chain Analysis
Strategic stockpiling of nitinol and cobalt-chrome feedstock dominates cardiovascular device supply chains, contrasting with just-in-time polymer resin flows for diagnostic disposables. Manufacturing concentration rests on Ireland, Costa Rica, and Switzerland as dual FDA-EU registered hubs. Raw material dependencies draw from titanium powder for additive implants, medical-grade silicone for catheters, and ethylene oxide for terminal sterilization. Single-source vulnerability persists in laser welding technician pipelines. Distribution runs through GPO-contracted hospital systems and direct OEM-to-manufacturer agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical device outsourcing sits at a regulatory inflection disruption where EU MDR technical documentation mandates and FDA foreign inspection intensification are compressing qualification timelines and consolidating vendor relationships around compliance-proven registrants.
For Market Incumbents: Shield market position by accelerating backward integration into additive manufacturing qualifications for patient-specific orthopedic implants, countering exclusion from spine and craniomaxillofacial supply chains. Fortify quality infrastructure across multi-site FDA registrations to replicate Jabil Inc.'s harmonized facility management model, defending against smaller competitors' ISO 13485:2016 disqualification. For New Entrants and Emerging Players: Differentiate on micro-extrusion and braiding capabilities for neurovascular catheter production, targeting the white space Integer Holdings Corporation has demonstrated in stroke intervention devices. Penetrate EU MDR regulatory affairs outsourcing as the most accessible entry vector, offering bundled technical documentation support to overwhelmed German and French OEM quality departments through Dublin-based project offices. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated electronics specialists with Class III PCBA capabilities. Long-term viability hinges on additive manufacturing qualification assets and notified body relationship depth. Acquisition targets should display harmonized FDA-EU quality systems across multiple cost-tier geographies. Watch FDA foreign supplier inspection clearance rates as the critical inflection signal; material deterioration would accelerate OEM sourcing concentration and inflate qualified registrant valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) pathway acceleration secures North American market access before EU MDR bottlenecks clear. |
| CE Marking Pathway | Notified body pre-submission engagement in Dublin addresses EU MDR technical documentation capacity constraints. |
| Hospital System Partnership | IDN sole-source agreements with automatic renewal clauses lock in five-to-seven year revenue visibility. |
| Software Companion Development | IEC 62304 validation for connected diagnostic devices differentiates against commodity hardware suppliers. |
| Reimbursement Strategy | CMS coding alignment for Class III implantables determines commercial viability for orthopedic OEM clients. |
Research Approach
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors converged on the working assumptions driving this analysis. Primary interviews with contract manufacturing executives and OEM procurement leads combined with secondary validation from FDA 510(k) filings, EU MDR notified body correspondence, hospital procurement databases, and customs trade data. Bottom-up facility capacity assessments and top-down market sizing triangulated across the analysis window.
Segmentation dimensions modeled encompass service type, end user procurement authority, product technology complexity, and regional regulatory alignment clusters. CAGRs were derived through growth driver decomposition and constraint factor weighting across the projection horizon. Forecast inputs incorporated sterilization capacity utilization rates, notified body queue lengths, and additive manufacturing qualification timelines.
Decision-makers should treat outputs as directional under stable FDA foreign inspection resourcing and EU MDR notified body capacity assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside ISO 13485:2016 transition completion and EtO facility emission compliance trajectories. Revision becomes warranted when FDA warning letter issuance rates or notified body withdrawal events cross thresholds indicating systemic qualification bottleneck escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Cranial Perforator Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Autosamplers Market
Medical Devices
Global Sacral Nerve Stimulation Market