
 Asia-Pacific Medical Device Market | 2026-2036
Asia-Pacific Medical Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Device Market Analysis
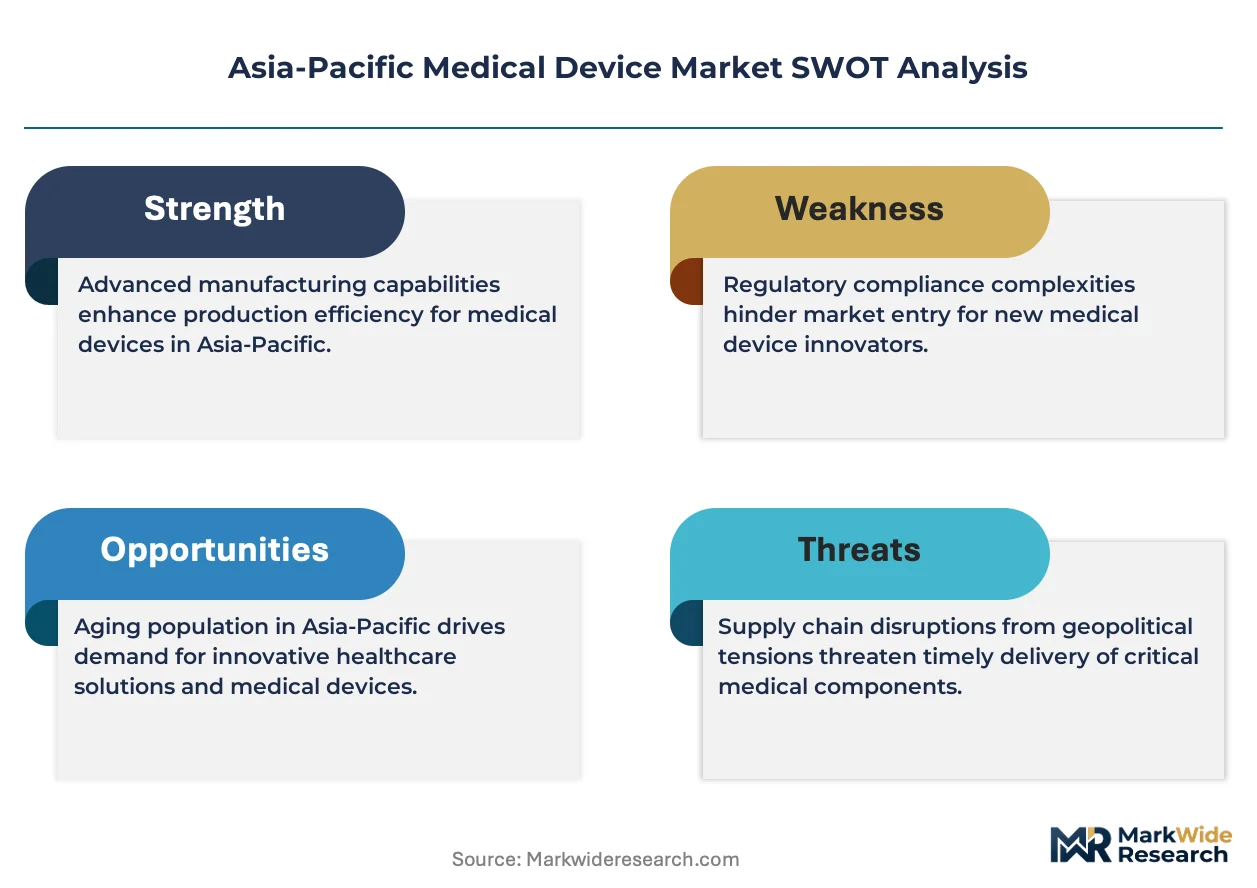
ISO 13485 certification is redrawing competitive boundaries across the Asia-Pacific Medical Device Market. Medtronic leverages its established quality management infrastructure to maintain broad regulatory access. Siemens Healthineers sustains R&D intensity in advanced imaging modalities. Shenzhen Mindray Bio-Medical Electronics anchors its position through cost-engineered patient monitoring systems with regional channel control.
Medical devices encompass instruments, apparatus, and machines intended for diagnosis, prevention, monitoring, or treatment of disease, typically incorporating biocompatible materials and precision-engineered components manufactured under validated cleanroom protocols. Diagnostic Devices command the largest revenue pool due to recurring capital replacement cycles in hospital radiology departments. Surgical Instruments generate concentrated margins from specialized electrosurgical and minimally invasive toolkits. Patient Monitoring Equipment is expanding fastest as telemedicine delivery modes integrate with cloud-connected bedside systems.
Japan's PMDA, China's NMPA, and Australia's TGA enforce divergent registration pathways that fragment product approval timelines and reshape regional launch sequencing. India's CDSCO has aligned medical device rules with international standards, reducing entry friction for multinationals. Stakeholders must monitor harmonization negotiations between ASEAN regulatory bodies to anticipate consolidated market access frameworks.
Market Dynamics
ISO 13485 certification requirements are restructuring competitive access across the Asia-Pacific Medical Device Market, forcing manufacturers to rebuild quality management infrastructure or exit high-margin hospital procurement channels entirely.
Growth Catalysts
- China's NMPA fast-track pathways:Priority review channels for innovative devices accelerate market entry for novel interventional cardiology products. Tertiary hospitals in Shanghai and Beijing expand catheterization lab capacity.
- Telemedicine infrastructure mandates:Government directives in multiple Asia-Pacific jurisdictions require cloud-connected patient monitoring in rural healthcare networks. Bedside system upgrades drive replacement demand.
- Biocompatible polymer advances:Next-generation materials reduce thrombogenicity in implantable devices. Japanese and South Korean manufacturers leverage domestic polymer science capabilities.
Market Restraints
- Input cost volatility:Medical-grade titanium and cobalt-chrome alloy prices fluctuate with mining supply disruptions. Orthopedic implant margins compress when raw material hedging fails.
- PMDA audit intensity:Japan's tightened quality management system inspections for foreign manufacturers extend approval timelines. Small and mid-cap entrants face disproportionate compliance burdens.
- Technical limitation in miniaturization:Battery energy density constraints restrict functionality in implantable neurostimulators. Device longevity targets exceed current power cell capabilities.
Strategic Opportunities
- India's CDSCO alignment:Harmonization with international standards reduces registration friction for multinationals. Underpenetrated tier-two and tier-three cities present expansion targets.
- AI-integrated diagnostic imaging:Machine learning algorithms embedded in radiology workstations enable automated anomaly detection. Software-as-a-service models create recurring revenue streams.
- ASEAN regulatory consolidation:Ongoing harmonization negotiations between national regulatory bodies may yield unified market access frameworks. Early positioning in draft standard development secures influence.
Industry Challenges
- Clinical engineering talent scarcity:Biomedical equipment maintenance expertise concentrates in metropolitan hospital systems. Rural facilities face extended equipment downtime.
- Legacy system integration complexity:New patient monitoring platforms must interface with decades-old hospital information systems. Custom middleware development inflates deployment costs.
- IP licensing fragmentation:Patent thickets around drug-eluting stent coatings require multiple royalty negotiations. Freedom-to-operate analyses consume legal resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Device Market |
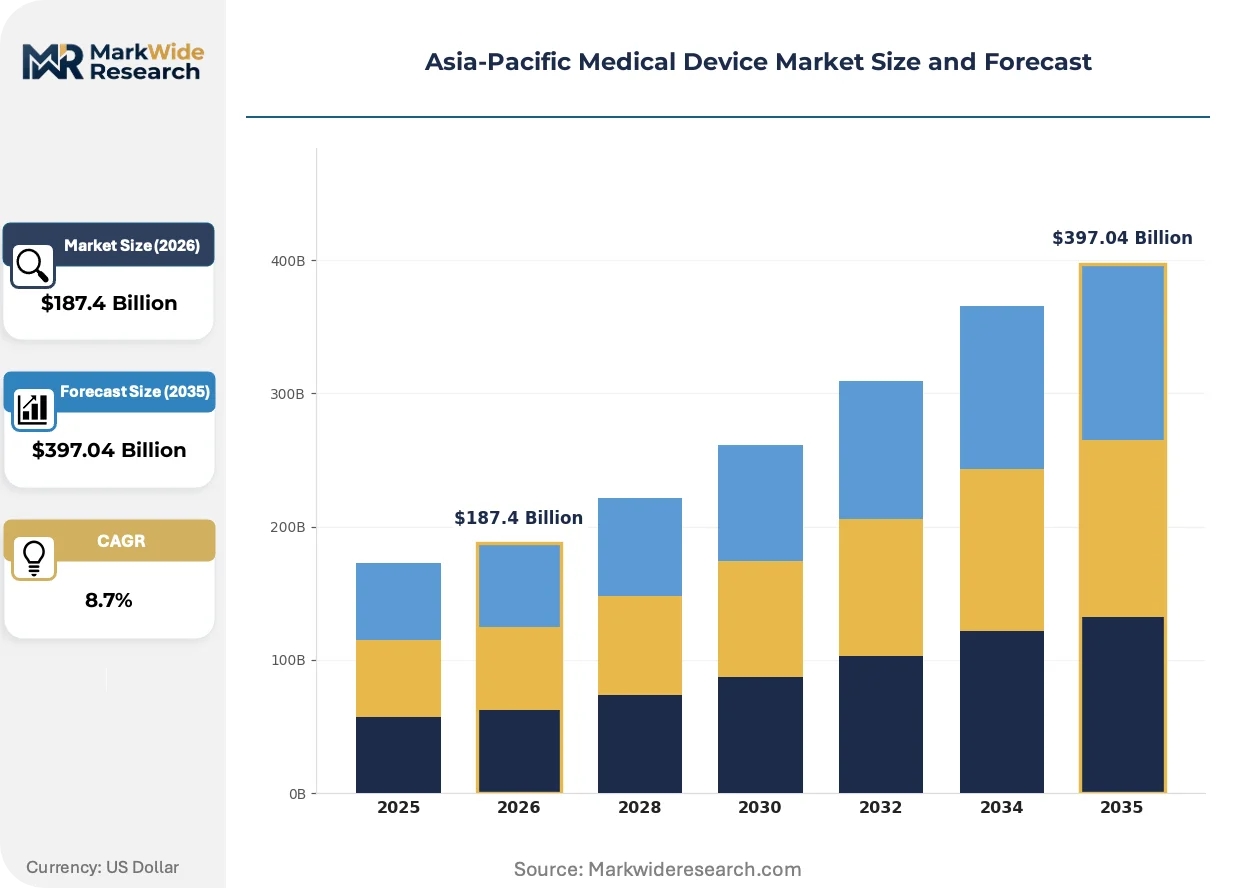
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Instruments, Patient Monitoring Equipment, Orthopedic Devices Delivery Mode: Telemedicine, In-person Consultations, Home Healthcare, Mobile Health Apps End User: Hospitals, Clinics, Rehabilitation Centers, Emergency Services Application: Cardiology, Neurology, Orthopedics, General Surgery |
| Companies Covered | Medtronic, Johnson & Johnson Services, GE HealthCare, Siemens Healthineers, Koninklijke Philips, Abbott Laboratories, Nipro Corporation, Shimadzu Corporation, Shenzhen Mindray Bio-Medical Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Device Market Emerging Trajectories
Digital connectivity and regulatory convergence are redefining product architecture and go-to-market sequencing across the Asia-Pacific Medical Device Market. Three developments merit particular attention.
Point-of-care ultrasound devices are fragmenting traditional radiology department purchasing patterns. Emergency departments and intensive care units in Australian and Singaporean hospitals acquire compact, tablet-based systems for bedside imaging. This diffusion is compressing capital equipment sales cycles and forcing imaging OEMs to rebuild channel relationships with clinical department heads rather than centralized procurement.
Japan's PMDA has implemented risk-based classification reforms that accelerate approval for software-as-a-medical-device products. Diagnostic algorithms that previously required full hardware submissions now qualify for streamlined review. Chinese AI imaging startups are redirecting regulatory strategy toward Tokyo to leverage this pathway before NMPA implements comparable frameworks.
Public hospital procurement in China's tier-one cities now emphasizes total cost-of-ownership metrics over upfront capital expenditure. Service contracts, training commitments, and upgrade guarantees factor into vendor selection. This recalibration favors established manufacturers with regional service infrastructure over low-cost imports lacking local technical support networks.
Asia-Pacific Medical Device Market Segmentation
Product architecture and delivery modality choices determine reimbursement pathways and regulatory burden across the Asia-Pacific Medical Device Market. Segment boundaries increasingly blur as diagnostic capabilities migrate from hospital radiology departments toward point-of-care settings.
Product Type:
Margin pools concentrate in capital-intensive modalities with recurring consumable revenue and in implantable devices with premium material specifications.
- Diagnostic Devices:Imaging systems, in-vitro analyzers, and molecular diagnostic platforms incorporating precision optics and bioreagent chemistry. China's tier-one hospitals in Shanghai and Beijing drive replacement demand as NMPA fast-track pathways accelerate novel modality approvals.
- Surgical Instruments:Electrosurgical generators, minimally invasive toolkits, and robotic-assisted platforms requiring validated sterilization protocols. Japanese tertiary centers prioritize single-use disposable instruments to reduce cross-contamination risk.
- Patient Monitoring Equipment:Bedside multi-parameter systems and wearable biosensors with cloud telemetry. Telemedicine infrastructure mandates across multiple Asia-Pacific jurisdictions expand addressable market beyond traditional hospital procurement.
- Orthopedic Devices:Joint replacement implants and trauma fixation systems manufactured from medical-grade titanium and cobalt-chrome alloys.
Diagnostic Devices holds installed capacity. Patient Monitoring Equipment is rotating up the share rankings.
Delivery Mode:
Volume distribution tracks regulatory clarity for remote care reimbursement and physical infrastructure density in rural versus urban catchments.
- Telemedicine:Synchronous video consultation platforms with integrated diagnostic peripheral connectivity. Australian and Singaporean hospital networks deploy compact point-of-care ultrasound for emergency department bedside imaging.
- In-person Consultations:Traditional clinical encounters with device-assisted examination in dedicated procedure suites. China's public hospital infrastructure upgrades concentrate procurement authority in tier-one city procurement centers.
- Home Healthcare:Remote patient monitoring with cellular-connected devices and nurse-coordinated intervention protocols.
- Mobile Health Apps:Software-as-a-medical-device products leveraging Japan's PMDA risk-based classification reforms for streamlined approval.
Telemedicine claims regulatory momentum. Home Healthcare is climbing the fastest as reimbursement frameworks mature.
End User:
Customer concentration patterns reflect capital availability and clinical engineering staffing depth across facility types.
- Hospitals:Tertiary medical centers with catheterization labs, hybrid operating theaters, and centralized sterilization services. Cardiology departments across the region expand interventional device procurement as procedure volumes recover.
- Clinics:Outpatient facilities with limited imaging capability and referral relationships to hospital networks. India's tier-two and tier-three cities present expansion targets as CDSCO alignment reduces multinational entry friction.
- Rehabilitation Centers:Post-acute facilities with physical therapy equipment and prosthetic fitting services.
- Emergency Services:Pre-hospital care with portable monitoring and defibrillation systems.
Hospitals command capital deployment. Clinics are gaining share fastest through ambulatory surgery migration.
Application:
Clinical specialization depth determines price realization and service contract attach rates.
- Cardiology:Interventional devices including drug-eluting stents, electrophysiology catheters, and implantable pacemakers. Patent thickets around stent coatings require multiple royalty negotiations and consume legal resources.
- Neurology:Implantable neurostimulators and diagnostic electroencephalography systems. Battery energy density constraints restrict functionality as device longevity targets exceed current power cell capabilities.
- Orthopedics:Arthroplasty implants and spinal fixation systems with biocompatible polymer advances reducing thrombogenicity.
- General Surgery:Open and minimally invasive procedural toolkits across multiple anatomical targets.
Cardiology dominates procedural volume. Neurology shows steepest expansion trajectory as neurostimulator indications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors distribution efficiency for high-value medical device imports across East Asia. Container throughput at this facility enables just-in-time delivery of precision-manufactured components to regional assembly plants. Cold-chain logistics corridors radiating from this hub sustain temperature-sensitive bioreagent integrity.
China
Tertiary hospitals in Shanghai and Beijing drive procurement of interventional cardiology devices as catheterization lab capacity expands. NMPA fast-track pathways accelerate novel modality approvals for innovative manufacturers. The Yangtze River Delta cluster concentrates domestic production of patient monitoring systems with integrated cloud telemetry.
Japan
PMDA risk-based classification reforms attract software-as-a-medical-device developers seeking streamlined regulatory pathways. Aging demographics sustain replacement demand for implantable cardiac devices in Kanto metropolitan hospitals. The Kansai region anchors precision polymer science capabilities serving biocompatible material specifications.
India
CDSCO alignment with international standards reduces entry friction for multinational device manufacturers targeting tier-two and tier-three cities. Public hospital infrastructure upgrades concentrate procurement authority in Delhi-NCR and Maharashtra state medical colleges. Gujarat pharmaceutical manufacturing corridors extend into disposable surgical instrument production.
Australia
TGA regulatory clarity supports telemedicine infrastructure mandates requiring cloud-connected patient monitoring in rural healthcare networks. Emergency departments in Sydney and Melbourne hospitals acquire compact point-of-care ultrasound for bedside imaging. The Victorian biomedical precinct anchors diagnostic imaging R&D with university hospital partnerships.
South Korea
MFDS enforcement of quality management system standards shapes competitive access for implantable device manufacturers. Seoul metropolitan tertiary centers prioritize single-use disposable instruments to reduce cross-contamination risk. The Daegu-Gyeongbuk medical cluster concentrates domestic production of advanced imaging components.
Asia-Pacific Medical Device Market Vendor Landscape
Listed leaders compete with private specialists across quality certification and regional channel depth. The vendor base stratifies into three tiers: established multinationals with ISO 13485 infrastructure, mid-cap regional specialists with concentrated geographic presence, and emerging domestic players leveraging cost-engineered production. Market structure rewards backward integration into precision component manufacturing and captive control over biocompatible material supply. M&A activity targets regulatory approval portfolios and established hospital procurement relationships.
Among diversified health technology conglomerates, Medtronic, Johnson & Johnson Services, and GE HealthCare exemplify archetypes with established quality management infrastructure spanning multiple regulatory jurisdictions. These entities occupy positions where certification breadth enables broad hospital procurement access. Siemens Healthineers and Koninklijke Philips sit within the imaging systems tier, while Abbott Laboratories and Nipro Corporation represent specialists with concentrated regional channel control. Shenzhen Mindray Bio-Medical Electronics anchors the domestic Chinese specialist position.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson Services |
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips |
| Abbott Laboratories |
| Nipro Corporation |
| Shimadzu Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification and price tiering across the Asia-Pacific Medical Device Market, forcing manufacturers to absorb compliance costs or surrender high-margin hospital procurement channels to certified competitors. This regulatory threshold simultaneously concentrates supply among quality-infrastructure holders and stratifies pricing power by certification status.
Pricing Analysis
Volume-discount tiering separates premium ISO 13485-certified manufacturers from uncertified economy suppliers. Price differentiation rests on certification grade and after-sales service bundling rather than raw material quality alone. Cost compression in the economy tier intensifies as Chinese domestic players absorb margin erosion to maintain share. Public hospital procurement committees in China's tier-one cities exhibit lowest price sensitivity due to total cost-of-ownership evaluation frameworks.
Supply Chain Analysis
Japan and South Korea anchor precision polymer and advanced imaging component production serving implantable device specifications. Medical-grade titanium draws from Australian mining corridors and Japanese refining capacity. Single-source vulnerability concentrates in cobalt-chrome alloy supply chains subject to mining disruption. Distribution runs through Shanghai Yangshan port logistics with cold-chain corridors sustaining bioreagent integrity to regional assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in telemedicine infrastructure mandates creating procurement niches outside traditional hospital procurement hierarchies. Point-of-care device demand from emergency departments and intensive care units reshapes vendor selection criteria toward clinical department heads.
For Market Incumbents: Compound certification breadth into channel lock-in by extending ISO 13485 infrastructure to cover software-as-a-medical-device submissions before NMPA implements comparable frameworks. Deepen backward integration into biocompatible polymer production to offset raw material cost volatility threatening orthopedic implant margins.
For New Entrants and Emerging Players: Anchor in India's tier-two and tier-three cities where CDSCO alignment reduces multinational entry friction but service infrastructure remains thin. Target compact point-of-care ultrasound systems for Australian and Singaporean emergency departments bypassing centralized radiology procurement. Lead with clinical department relationships rather than GPO contract chasing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding concentrated ASEAN hospital procurement relationships but lacking quality management scale. Five-to-ten year viability hinges on regulatory harmonization completion across ASEAN bodies. Watch draft standard development participation as signal of influence positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Quality management infrastructure gates access to Japan's PMDA audit pathways and Chinese tertiary hospital procurement. |
| Software-as-a-Medical-Device Development | PMDA risk-based classification reforms enable streamlined Tokyo regulatory strategy before NMPA framework completion. |
| Point-of-Care Ultrasound Commercialization | Emergency department procurement bypasses centralized radiology purchasing patterns in Australian and Singaporean hospitals. |
| Biocompatible Polymer Backward Integration | Captive polymer supply secures margin protection against medical-grade titanium and cobalt-chrome alloy price volatility. |
| Telemedicine Infrastructure Partnership | Government mandates for cloud-connected patient monitoring in rural networks expand addressable market beyond traditional hospital procurement. |
Methodological Framework
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings across the Asia-Pacific Medical Device Market. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at multinational manufacturers combined with secondary validation from NMPA submission records, PMDA approval databases, CDSCO registration filings, and ASEAN harmonization draft documents. Bottom-up installed base modeling and top-down healthcare expenditure allocation triangulate market sizing.
Sensitivity analysis across certification status, regional regulatory cluster, and delivery modality segmentation dimensions shapes volume and value outputs over the projection horizon. CAGRs derive from procedure volume trajectories, replacement cycle analysis, and technology diffusion curves. Industry-specific forecast inputs incorporate catheterization lab capacity expansion plans in Shanghai and Beijing tertiary hospitals alongside telemedicine infrastructure deployment schedules across Australian rural health networks.
Underlying assumptions cover NMPA fast-track pathway continuity, PMDA audit intensity stabilization, and ASEAN regulatory harmonization progression, with deviation risk concentrated in raw material supply disruptions and clinical engineering talent scarcity extending rural equipment downtime. Recalibration cycles align with material shifts in regulatory approval timelines and hospital infrastructure upgrade program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IOL Delivery Systems Market
Medical Devices
Low Vision Aids Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Heating Pads Market
Medical Devices
Global Pupillometer Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Pectus Bar Market