
 Europe Insulin Pumps Market | 2026-2036
Europe Insulin Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulin Pumps Market Insights
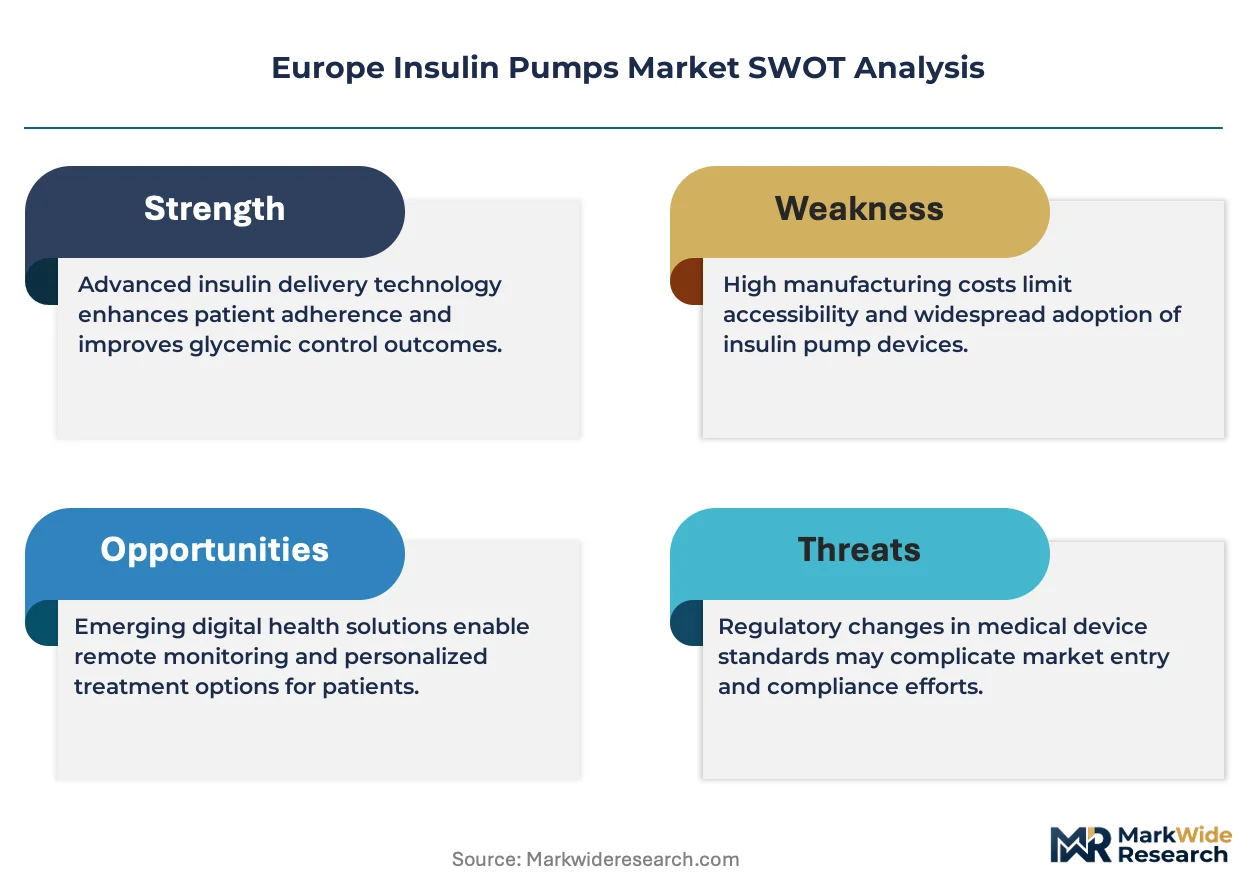
Closed-loop algorithm certification is reorganizing competitive tiers in the Europe insulin pumps landscape. Medtronic leverages its early automated insulin delivery approvals to anchor premium positioning across Western European markets. Ypsomed specializes in patch pump miniaturization and competes aggressively on form factor and discretion for active patient segments.
An insulin pump is a programmable, battery-powered medical device that delivers rapid-acting insulin through a subcutaneous infusion set at pre-set basal rates and patient-triggered bolus doses, typically with delivery precision measured in increments of 0.025 to 0.1 units. Its primary commercial purpose is to replace multiple daily injection regimens with continuous subcutaneous insulin infusion, improving glycemic control while reducing hypoglycemic episodes. Connected insulin pumps with integrated continuous glucose monitoring represent the fastest-expanding product tier, as reimbursement frameworks in major European markets increasingly favor sensor-augmented pump therapy over standalone devices. Among end users, home care dominates volume while diabetes clinics capture disproportionate margin from training-intensive onboarding and remote monitoring subscriptions.
The EU Medical Device Regulation and CE marking requirements under the new MDR framework are extending clinical evaluation timelines and raising barriers for non-European manufacturers seeking European market access. EMA guidance on digital health technologies and national health technology assessment bodies in Germany, France, and England are reshaping reimbursement criteria toward outcomes-based pump procurement. Stakeholders must monitor evolving interoperability standards between pump systems and continuous glucose monitoring platforms, as regulatory pressure for open-protocol compatibility intensifies across European health systems.
Market Dynamics
The EU Medical Device Regulation is compressing competitive timelines as manufacturers race to accumulate clinical evidence for connected pump systems before CE marking deadlines. This regulatory pressure is redrawing market access boundaries across Western European reimbursement corridors.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation is accelerating consolidation among manufacturers with robust clinical data portfolios. CE marking renewal requirements are filtering out marginal competitors.
- Home Care Migration:Type 1 diabetes patients are shifting from clinic-based insulin management to residential settings. Reimbursement pathways in Germany and France now favor continuous subcutaneous infusion over multiple daily injections.
- Sensor Integration:Continuous glucose monitoring convergence with pump hardware is creating closed-loop therapy demand. Health technology assessment bodies in England are prioritizing sensor-augmented devices in procurement frameworks.
Market Restraints
- Clinical Evidence Burden:The MDR framework demands expanded post-market surveillance and clinical investigation documentation. Small manufacturers face insurmountable resource requirements for regulatory dossiers.
- Reimbursement Fragmentation:National health technology assessment processes vary sharply between France, Germany, and the United Kingdom. Divergent evidence standards delay commercial launch sequencing.
- Single-Source Component Risk:Precision insulin delivery motors and MEMS sensors concentrate among Asian contract manufacturers. European pump assemblers remain exposed to supply chain disruption.
Strategic Opportunities
- Eastern European Expansion:Poland and Romania present underpenetrated addressable markets with nascent reimbursement for continuous glucose monitoring-integrated pumps. Private pay segments absorb premium devices ahead of public coverage.
- Interoperability Mandates:Open-protocol compatibility requirements emerging from Dutch and Scandinavian health systems are creating first-mover advantages for modular platform architectures.
- Algorithm Licensing:Closed-loop control software is separating from hardware monetization. Specialist firms are capturing recurring revenue through subscription-based automated insulin delivery updates.
Industry Challenges
- Clinical Affairs Talent Scarcity:Regulatory affairs specialists with MDR technical documentation experience command premium compensation. Manufacturers compete for limited pools of notified body liaison expertise.
- Cybersecurity Certification Complexity:Connected pump systems must satisfy both medical device and data protection frameworks. GDPR compliance for real-time glucose data transmission adds validation layers.
- Legacy System Integration:Hospital diabetes clinics operate entrenched electronic health record architectures. Pump data interoperability with proprietary clinic management software requires costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulin Pumps Market |
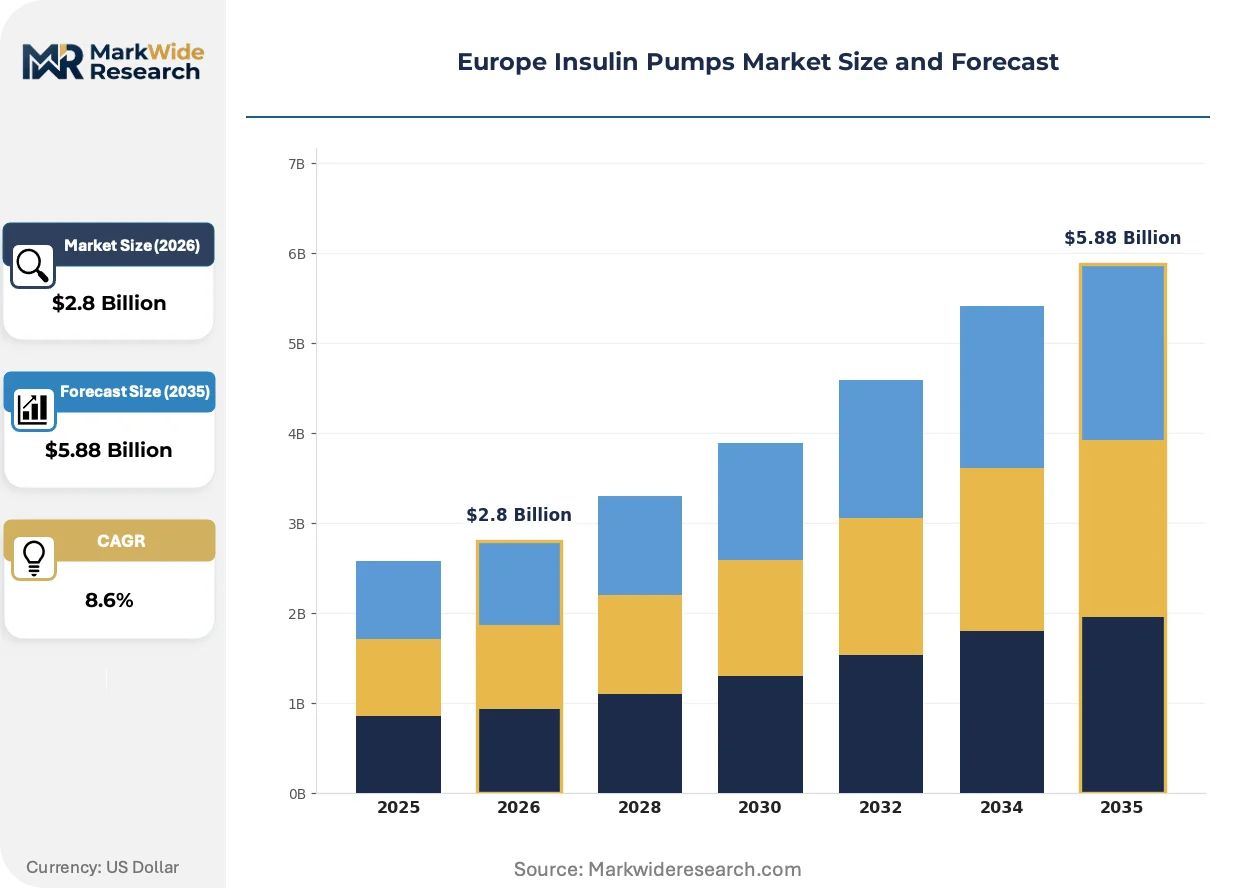
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Insulin Pumps, Patch Pumps, Connected Insulin Pumps, Insulin Reservoirs End User: Hospitals, Home Care, Diabetes Clinics, Pharmacies Technology: Wireless Technology, Continuous Glucose Monitoring, Insulin Delivery Systems, Advanced Algorithms Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Pediatric Diabetes, Gestational Diabetes |
| Companies Covered | Medtronic, Tandem Diabetes Care, Insulet Corporation, Roche, Ypsomed, Terumo Corporation, Cellnovo, SOOIL Development, ViCentra, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulin Pumps Market Trends and Innovations
Patch pump form factors are displacing traditional tethered devices as patient preference for discretion and mobility intensifies. Algorithm sophistication and manufacturing precision are converging to enable new device categories.
Microfluidic insulin delivery mechanisms are miniaturizing reservoir and pumping assemblies into wearable patches no larger than a coin. Adolescent and young adult Type 1 patients in Germany and the United Kingdom are adopting these devices at rates exceeding traditional pump upgrades. Form factor compression is eliminating tubing failure modes while enabling waterproofing and extended wear duration.
CE marking requirements under the MDR are extending clinical evaluation timelines from eighteen to thirty-six months for novel pump systems. Manufacturers are responding by front-loading clinical investigation investment and prioritizing predicate device equivalence pathways. Patch pump categories face the steepest documentation burdens due to limited established benchmarks.
Subscription-based remote monitoring is displacing upfront hardware transactions in diabetes clinic procurement. French and English hospital systems are unbundling device acquisition from training and glycemic data analytics services. This shift compresses capital expenditure cycles while elongating vendor-patient relationship duration.
Europe Insulin Pumps Market Segmentation
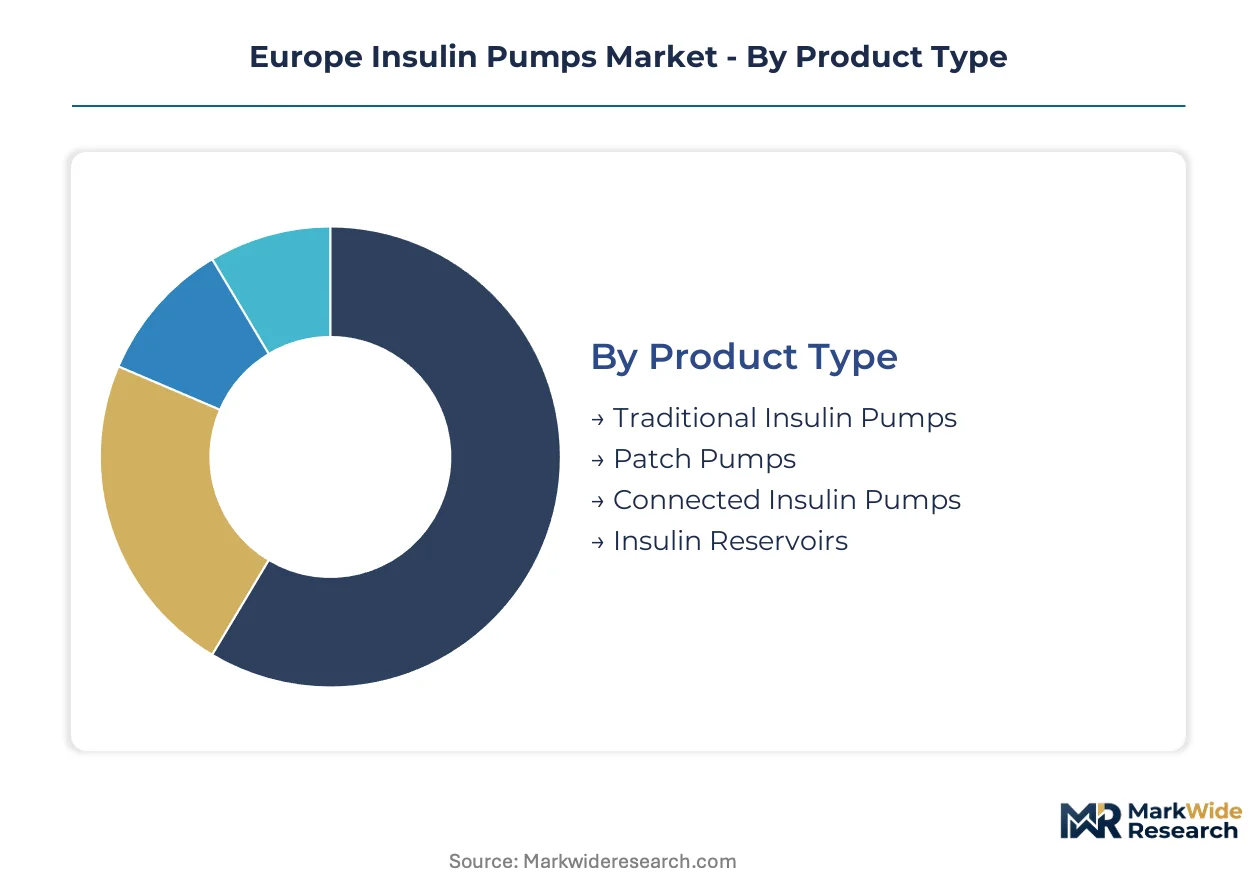
Device configuration and care setting selection in the Europe insulin pumps market reflect divergent reimbursement pathways and patient autonomy preferences across national health systems. Segment performance varies sharply between Western European markets with mature sensor integration coverage and Eastern European markets where private payment dominates premium device access.
Product Type:
Domestic manufacturing concentration in Switzerland and Germany supplies traditional pump systems across the region, while patch pump adoption spreads fastest in export-oriented Nordic and Benelux markets seeking discreet form factors.
- Traditional Insulin Pumps:Tethered devices with external tubing and programmable basal-bolus profiles remain the reimbursement standard in France and Italy. German diabetes clinics favor these systems for training-intensive patient onboarding where physical button interfaces reduce cognitive load.
- Connected Insulin Pumps:Bluetooth-enabled devices transmitting real-time dosing data to smartphone applications are capturing procurement preference in England and the Netherlands. CE marking under MDR Article 10.4 demands expanded cybersecurity documentation for wireless connectivity modules.
- Patch Pumps:Tube-free wearable devices adhere directly to skin with integrated insulin reservoirs.
- Insulin Reservoirs:Disposable 1.8mL to 3.0mL cartridges compatible with specific pump architectures.
Traditional insulin pumps hold the largest share; momentum sits with connected insulin pumps.
End User:
Cost tier stratification separates capital-intensive hospital procurement from recurring revenue opportunities in home care and diabetes clinic subscription models.
- Home Care:Residential Type 1 diabetes management dominates volume across Germany, France, and the United Kingdom. Reimbursement frameworks in these markets now cover continuous glucose monitoring-integrated pump therapy for patients failing multiple daily injection regimens.
- Diabetes Clinics:Specialized outpatient centers capture disproportionate margin through bundled device acquisition, patient training, and remote monitoring subscriptions. French hospital systems are unbundling these services to elongate vendor relationships beyond hardware replacement cycles.
- Hospitals:Inpatient acute care settings deploy pumps for perioperative glycemic control and diabetic ketoacidosis management.
- Pharmacies:Retail distribution channels serve cash-pay segments and replacement supply needs.
Home care generates the highest volume; diabetes clinics deliver the steepest margin expansion trajectory.
Technology:
Application maturity separates established insulin delivery mechanisms from emerging algorithmic control layers requiring fresh clinical evidence under MDR.
- Continuous Glucose Monitoring:Sensor-augmented pump systems integrate subcutaneous glucose sensors with predictive low glucose suspend functionality. Health technology assessment bodies in England prioritize these devices in procurement frameworks over standalone pumps.
- Advanced Algorithms:Closed-loop control software automating insulin dose adjustment based on sensor glucose trends is separating from hardware monetization. Specialist firms license these algorithms through subscription models to pump manufacturers lacking in-house automation expertise.
- Wireless Technology:Bluetooth Low Energy and near-field communication protocols enable smartphone connectivity and data transmission.
- Insulin Delivery Systems:Precision micro-piston and peristaltic pumping mechanisms measured in 0.025-unit increments.
Continuous glucose monitoring anchors current procurement; advanced algorithms are climbing the fastest.
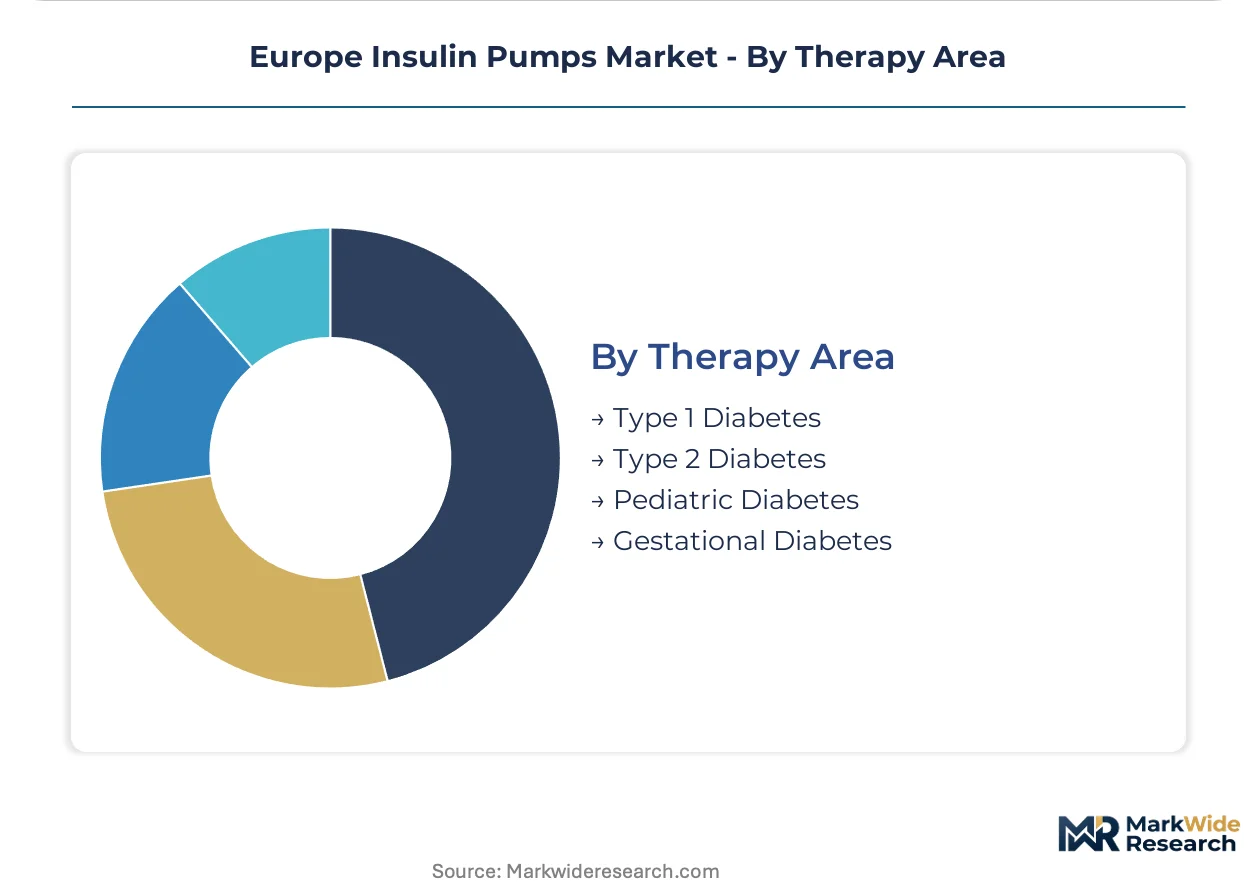
Therapy Area:
Patient population characteristics determine device feature requirements and reimbursement urgency across European health systems.
- Type 1 Diabetes:Absolute insulin deficiency patients require continuous basal insulin delivery and precise bolus calculation. Pediatric and adolescent adoption in Germany and the United Kingdom drives demand for waterproof, discreet patch pump form factors compatible with active lifestyles.
- Pediatric Diabetes:Patients under 18 years require specialized pump features including remote parent monitoring and school nurse interface compatibility. ANSM in France maintains distinct reimbursement approval pathways for pediatric indications.
- Type 2 Diabetes:Insulin-resistant patients with residual beta-cell function represent an expanding addressable market as progressive beta-cell failure intensifies.
- Gestational Diabetes:Temporary insulin requirements during pregnancy create short-duration pump rental opportunities.
Type 1 diabetes commands the deepest market penetration; pediatric diabetes is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for insulin pumps varies sharply across European reimbursement environments. German and French patients face minimal out-of-pocket costs, while Polish and Romanian buyers absorb substantial private payments. This demand-elasticity contrast concentrates premium device penetration in Western corridors while Eastern markets absorb mid-tier alternatives.
Germany
Home care reimbursement through statutory health insurers covers continuous glucose monitoring-integrated pumps without prior authorization. The Federal Joint Committee (G-BA) mandates outcomes-based evidence for new device categories. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia assemble precision insulin delivery systems for export across the continent.
France
Diabetes clinics in Île-de-France capture margin from bundled training and remote monitoring subscriptions. ANSM maintains distinct pediatric approval pathways that accelerate device access for patients under 18. The Lyon-Grenoble corridor hosts algorithm development specialists licensing closed-loop control software to pump manufacturers.
United Kingdom
NICE technology appraisals prioritize sensor-augmented pump therapy in procurement frameworks across England. NHS England's Diabetes Treatment and Care Programme bundles device provision with glycemic data analytics services. Cambridge and Oxford clusters concentrate on microfluidic miniaturization for next-generation patch pump architectures.
Netherlands
Dutch health systems are mandating open-protocol compatibility between pump systems and continuous glucose monitoring platforms. The National Health Care Institute (ZIN) evaluates interoperability as a procurement criterion. Eindhoven's high-tech ecosystem supplies MEMS sensors and wireless connectivity modules to regional pump assemblers.
Poland
Private pay segments absorb premium devices ahead of public reimbursement expansion for continuous subcutaneous insulin infusion. The national health fund (NFZ) maintains restricted coverage for Type 1 diabetes patients failing multiple daily injection regimens. Warsaw and Krakow diabetes centers are piloting remote monitoring subscriptions for affluent patient cohorts.
Europe Insulin Pumps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European insulin pumps landscape. Established medical technology conglomerates anchor premium positioning through automated insulin delivery approvals and clinical evidence portfolios. Specialized pump manufacturers compete on form factor miniaturization and patch pump discretion. Mid-tier assemblers pursue geographic expansion into underpenetrated Eastern European markets. Dominant competitive moves include algorithm licensing partnerships and MDR compliance-driven consolidation of clinical affairs capabilities.
Within the diversified medical technology tier, Medtronic and Roche occupy positions exemplifying integrated device and data platform strategies. Among pump-specialized manufacturers, Ypsomed and Insulet Corporation represent archetypes of form factor innovation and tube-free wearable delivery systems. Tandem Diabetes Care sits within the connected pump vector, anchoring smartphone-integrated therapy management. These named entities illustrate how competitive positioning separates across hardware miniaturization, algorithmic control, and ecosystem integration dimensions.
| Leading Market Players |
|---|
| Medtronic |
| Tandem Diabetes Care |
| Insulet Corporation |
| Roche |
| Ypsomed |
| Terumo Corporation |
| Cellnovo |
| SOOIL Development |
| ViCentra |
| Others |
Pricing and Supply Chain Analysis
Micro-piston motor substitution for legacy peristaltic pumping mechanisms is redrawing component sourcing maps from Swiss and German precision engineering clusters toward Asian MEMS foundries, simultaneously compressing bill-of-materials costs and exposing European pump assemblers to single-source vulnerability in precision insulin delivery actuators.
Pricing Analysis
After-sales revenue from disposable infusion sets, reservoir cartridges, and remote monitoring subscriptions now exceeds hardware margins over the device lifetime. Three-tier pricing structure across premium closed-loop systems, standard sensor-augmented pumps, and economy tethered devices separates reimbursement-eligible offerings from cash-pay segments. Pricing pressure stems from health technology assessment bodies demanding outcomes-based evidence for premium tier access. Home care patients in Germany and France show lowest price sensitivity due to statutory coverage, while private-pay buyers in Poland and Romania absorb full device costs.
Supply Chain Analysis
Inventory buffers for precision insulin delivery motors and glucose sensor membranes now stretch beyond eighteen months as manufacturers front-load component procurement ahead of MDR compliance deadlines. European pump assembly concentrates in Switzerland, Germany, and the Netherlands, drawing from Taiwanese MEMS foundries and South Korean battery cell suppliers. Single-source dependency on Asian contract manufacturers for micro-piston actuators creates tariff exposure and logistics chokepoint risk. Distribution runs through hospital procurement consortia in France and England, diabetes clinic direct accounts in Germany, and retail pharmacy channels for replacement supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDR technical documentation expertise has become the binding constraint for market access, with notified body liaison specialists commanding compensation premiums that filter marginal competitors from CE marking pathways.
For Market Incumbents: Compound regulatory affairs capabilities through targeted acquisition of clinical investigation boutiques and MDR dossier specialists before CE marking renewal deadlines filter weaker portfolios. Anchor premium positioning by accelerating automated insulin delivery algorithm submissions to NICE and G-BA, locking in reimbursement preference ahead of sensor integration mandates from Dutch and Scandinavian health systems. For New Entrants and Emerging Players: Anchor in Eastern European private-pay corridors where reimbursement gaps create cash-pay absorption capacity for mid-tier patch pump alternatives. Target Poland and Romania's nascent continuous glucose monitoring-integrated pump markets through direct-to-clinic distribution bypassing entrenched hospital procurement consortia. Lead with waterproof form factors and adolescent lifestyle compatibility to differentiate from incumbent tethered systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical data platform specialists over pure hardware manufacturers. Algorithm licensing firms with recurring subscription revenue and MDR-compliant technical documentation portfolios represent the most defensible acquisition targets. Watch for NICE technology appraisal decisions on closed-loop systems as the signal for reimbursement tipping points that will reorder competitive tiers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10.4 compliance separates market access winners from filtered competitors in notified body queues. |
| Algorithm Licensing Partnership | Subscription-based automated insulin delivery software separates recurring revenue from hardware replacement cycles. |
| Hospital System Partnership | NHS England's bundled procurement frameworks favor vendors integrating device provision with glycemic data analytics. |
| Software Companion Development | GDPR-compliant smartphone applications for real-time glucose monitoring satisfy Dutch interoperability mandates. |
| Reimbursement Strategy | G-BA outcomes-based evidence requirements determine premium tier access in Europe's largest statutory coverage market. |
Research Methodology
Operator-level perspectives from diabetes clinic directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads anchored the qualitative base for this study. Primary interview findings triangulated against EMA guidance documents, notified body MDR certification databases, hospital procurement records from NHS England and German statutory insurers, and continuous glucose monitoring integration standards from Dutch health systems. Bottom-up patient population modeling and top-down device shipment validation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across reimbursement expansion scenarios in Eastern Europe and MDR compliance delay assumptions. The analytical framework modeled pump configuration, care setting, technology integration level, and patient age cohort across the projection horizon. CAGRs derived from segment-level adoption curves weighted by national reimbursement maturity. Forecast inputs included health technology assessment body approval timelines and sensor-augmented therapy penetration rates by country.
Material uncertainties — regulatory timeline slippage, supply chain disruption in precision actuator sourcing, and reimbursement policy reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Bariatric Beds Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Hip Kits Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Electronic Pill Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Wireless Portable Medical Devices Market