
 Non-Invasive Ultrasound Stimulation Market | 2026-2036
Non-Invasive Ultrasound Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Ultrasound Stimulation Market Analytics
High-intensity focused ultrasound certification is redrawing competitive thresholds in therapeutic devices. GE Healthcare anchors its position through deep R&D investment in precision acoustic targeting systems. Siemens Healthineers dominates European hospital procurement channels with integrated imaging-therapy platforms. Philips Healthcare extends its footprint in home care segments through wearable form factors that merge diagnostic monitoring with stimulation delivery.
Non-invasive ultrasound stimulation employs acoustic energy transmission through tissue without incision, typically operating at frequencies between 20 kHz and 10 MHz with intensity thresholds calibrated for neuromodulation or thermal bioeffects. The technology serves clinical purposes spanning pain suppression, accelerated bone remodeling, and selective tissue ablation. Pulsed ultrasound architectures occupy the largest installed base due to their safety margin in outpatient settings, while high-intensity focused ultrasound commands premium pricing in aesthetic and oncologic applications where precision tissue targeting justifies capital intensity. Wearable devices represent the fastest-growing product tier as miniaturization of transducer arrays enables continuous ambulatory therapy.
FDA 510(k) premarket notification requirements shape device development cycles and clinical evidence standards for manufacturers seeking US market access, while the EU Medical Device Regulation imposes stricter post-market surveillance obligations that lengthen certification timelines. ISO 13485 quality management systems and IEC 60601-1-2 electromagnetic compatibility standards form baseline compliance infrastructure for cross-border commercialization. Stakeholders must monitor evolving reimbursement codes for non-pharmacological pain interventions, as coverage determinations by CMS and parallel bodies in Germany and Japan will dictate whether clinical adoption outpaces hardware innovation.
Market Dynamics
Portable ultrasound stimulation hardware is compressing clinical workflows toward point-of-care delivery, forcing manufacturers to reconcile hospital-grade precision with ambulatory form factors and rechargeable power architectures.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare and Medicaid Services is creating dedicated billing codes for non-pharmacological pain interventions, directly incentivizing hospital procurement of stimulation units.
- Pulsed ultrasound safety profile:Outpatient clinics favor acoustic architectures with thermal safety margins that permit unsupervised patient use, accelerating deployment in physical therapy chains.
- Sports medicine infrastructure:Professional athletic franchises in the United States are building dedicated rehabilitation facilities equipped with portable stimulation hardware for accelerated injury recovery protocols.
Market Restraints
- Transducer material concentration:Piezoelectric ceramic supply chains concentrate in East Asian manufacturing zones, exposing device assemblers to input volatility and geopolitical friction.
- EU MDR certification timelines:The European Union Medical Device Regulation imposes extended post-market surveillance obligations that delay commercial launches by 18-24 months relative to FDA pathways.
- Pharmacological substitution:Low-cost oral analgesics and topical NSAID formulations retain physician preference for mild-to-moderate pain cases, limiting addressable patient populations.
Strategic Opportunities
- Home care channel penetration:Direct-to-patient distribution models bypass institutional procurement bottlenecks, capturing margin previously allocated to hospital purchasing consortia.
- Neuromodulation convergence:Integration of transcranial ultrasound with wearable EEG monitoring enables closed-loop therapeutic adjustment, opening psychiatric and cognitive enhancement applications.
- Japan's aging demographic mandate:METI reimbursement policies for home-based rehabilitation equipment create regulatory tailwinds for compact stimulation devices in elderly care markets.
Industry Challenges
- Acoustic engineer scarcity:Specialized expertise in beamforming algorithm development and transducer array miniaturization commands premium compensation, constraining R&D scaling.
- Legacy EMR integration:Hospital information systems require customized HL7 FHIR interfaces to capture stimulation dosage and patient response data, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Ultrasound Stimulation Market |
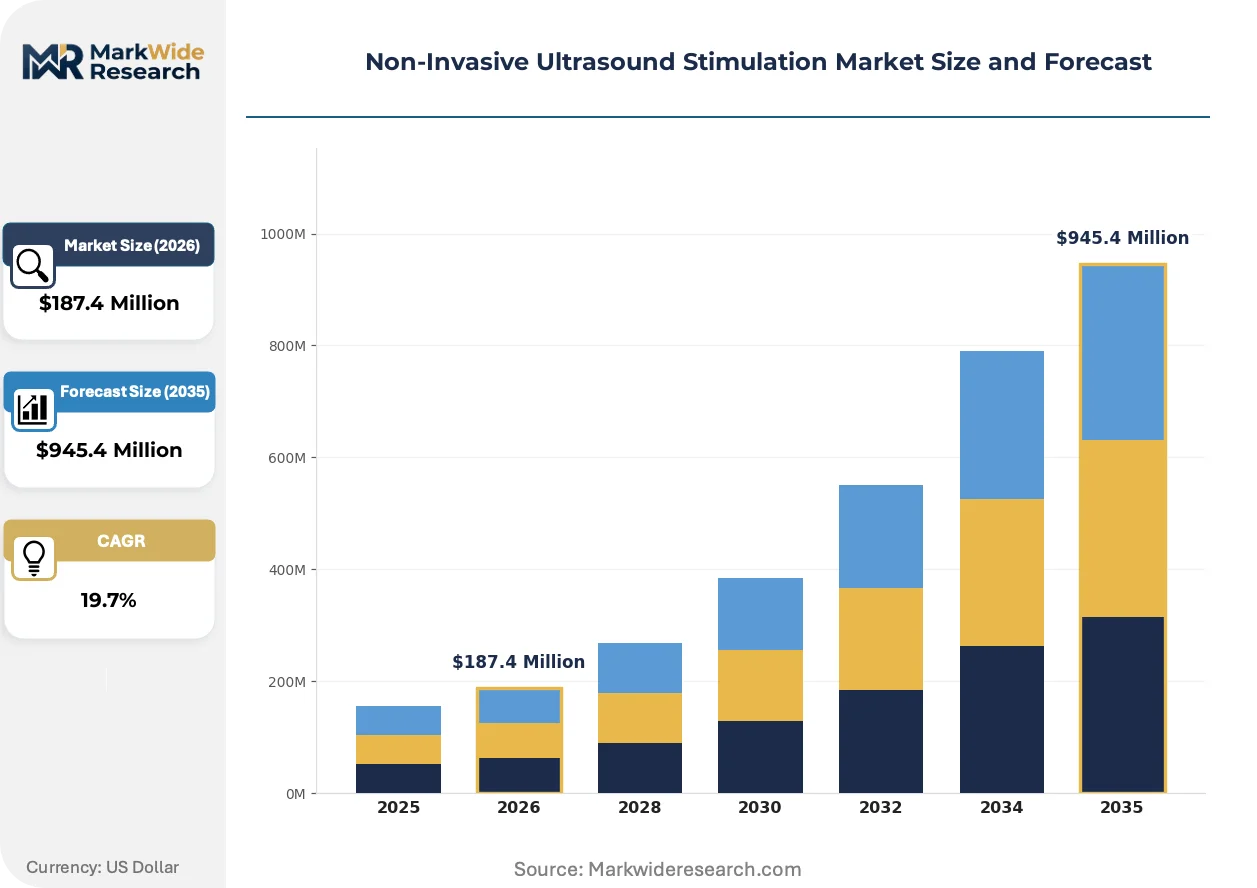
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Devices, Diagnostic Equipment, Wearable Devices, Portable Units Technology: Pulsed Ultrasound, Continuous Wave, High-Intensity Focused Ultrasound, Low-Intensity Pulsed Ultrasound Application: Pain Management, Tissue Regeneration, Bone Healing, Aesthetic Treatments End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Canon Medical Systems Corporation, Mindray Medical International Limited, FUJIFILM Corporation, Samsung Electronics, Neuromod Devices Ltd, SonaCare Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Ultrasound Stimulation Market Evolving Landscape
Hardware miniaturization and algorithmic beam steering are collapsing the distinction between diagnostic imaging and therapeutic delivery, enabling single-device platforms that alternate between assessment and intervention modes.
MEMS-based capacitive micromachined ultrasound transducers are displacing conventional piezoelectric assemblies in wearable stimulation devices. Sports medicine clinics and home care providers are adopting CMUT arrays for their lower power consumption and silicon-compatible manufacturing. This displacement is compressing unit economics toward consumer-electronics cost structures while maintaining clinical-grade acoustic output precision.
The FDA's 510(k) premarket notification pathway for therapeutic ultrasound devices is streamlining evidence requirements for predicate-based submissions. Manufacturers with cleared imaging platforms can leverage existing acoustic safety data to accelerate neuromodulation indications. Rehabilitation device divisions within diversified health technology conglomerates are exploiting this regulatory efficiency to outpace pure-play competitors in US market entry.
Hospital purchasing committees are consolidating vendor relationships around full-stack platform providers rather than point-solution suppliers. Integrated imaging-therapy systems that bundle diagnostic capability with stimulation delivery are capturing preference over standalone devices. This concentration is most visible in German and Japanese acute care networks, where procurement standardization across facility clusters favors multi-modal equipment contracts.
Non-Invasive Ultrasound Stimulation Market Segmentation
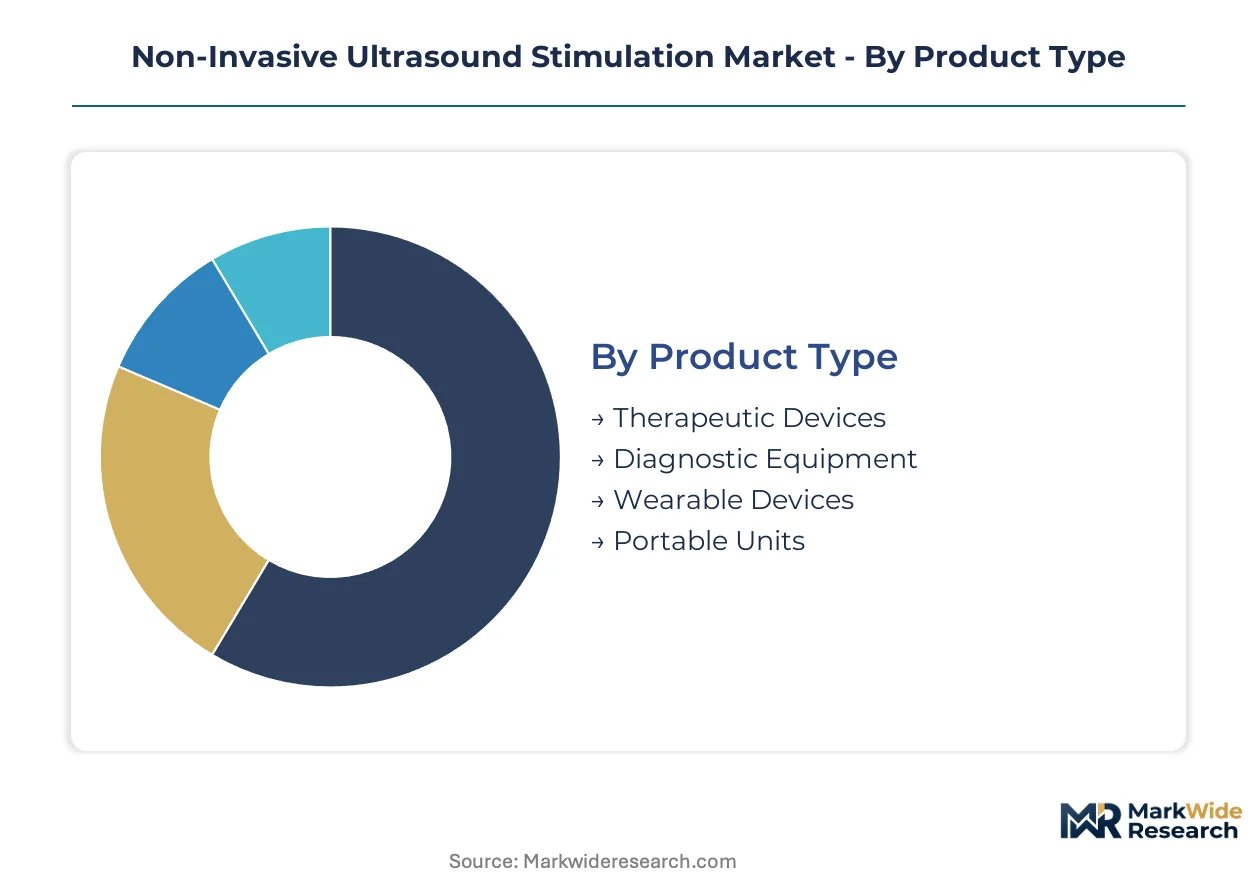
Segmentation in the non-invasive ultrasound stimulation market reveals how hardware form factors, acoustic architectures, and care delivery settings allocate capital across the value chain. Manufacturers configure R&D portfolios and pricing strategies around these divisions.
Product Type:
Premium margin pools concentrate in devices that bridge clinical precision with ambulatory deployment, rewarding manufacturers who solve the power-versus-portability equation.
- Therapeutic Devices:Stationary systems deliver calibrated acoustic energy for supervised clinical interventions. Rehabilitation centers in Germany and Japan prioritize these units for their dose reproducibility and integrated safety interlocks.
- Diagnostic Equipment:Imaging platforms with dual-mode therapeutic capability command the highest ASPs by collapsing capital expenditure into single-vendor relationships. Siemens Healthineers and GE Healthcare anchor hospital procurement through these integrated systems.
- Wearable Devices:MEMS-based CMUT arrays enable continuous ambulatory therapy with rechargeable architectures. METI reimbursement codes in Japan accelerate home care adoption.
- Portable Units:Battery-powered hardware for point-of-care delivery in sports clinics and outpatient chains. US physical therapy franchises deploy these for accelerated injury recovery protocols.
The dominant share belongs to Therapeutic Devices, while Wearable Devices is closing the gap fastest.
Technology:
Acoustic energy modulation schemes differentiate safety profiles and addressable indications, with thermal bioeffect thresholds determining regulatory pathway complexity.
- Pulsed Ultrasound:Intermittent energy delivery maintains tissue temperature below thermal damage thresholds, enabling unsupervised patient use. Outpatient clinics in the United States favor this architecture for its liability profile and CMS reimbursement alignment.
- Continuous Wave:Sustained acoustic output generates thermal effects for deep tissue heating applications. Physical therapy chains deploy these systems where supervised heating protocols justify hardware investment.
- High-Intensity Focused Ultrasound:Precision beam steering enables selective tissue ablation without incision. Aesthetic and oncologic applications in South Korea and the United States command premium pricing for capital-intensive installations.
- Low-Intensity Pulsed Ultrasound:Sub-thermal energy delivery for bone remodeling and soft tissue repair. Orthopedic clinics prescribe these devices for fracture healing acceleration.
Pulsed Ultrasound holds the installed base lead, though High-Intensity Focused Ultrasound generates the steepest margin expansion.
Application:
Clinical indication breadth determines market access complexity, with pain interventions offering the largest addressable patient populations and aesthetic applications delivering the highest per-procedure economics.
- Pain Management:Neuromodulation through acoustic nerve suppression targets chronic and post-surgical pain. FDA 510(k) predicate pathways accelerate commercialization for manufacturers with cleared acoustic platforms.
- Tissue Regeneration:Cellular mechanotransduction stimulation accelerates wound healing and soft tissue repair. German hospital networks integrate these protocols into post-operative care standards.
- Bone Healing:Low-intensity pulsed protocols for fracture non-union and osteoporosis management. Japanese elderly care facilities deploy compact units under METI reimbursement.
- Aesthetic Treatments:High-intensity focused applications for body contouring and skin tightening. South Korean aesthetic clinic chains drive volume through packaged procedure offerings.
Pain Management captures the broadest reimbursement coverage, while Aesthetic Treatments climbs fastest on per-session economics.
End User:
Procurement authority and reimbursement access separate institutional buyers from direct-to-patient channels, with home care representing the largest uncaptured volume opportunity.
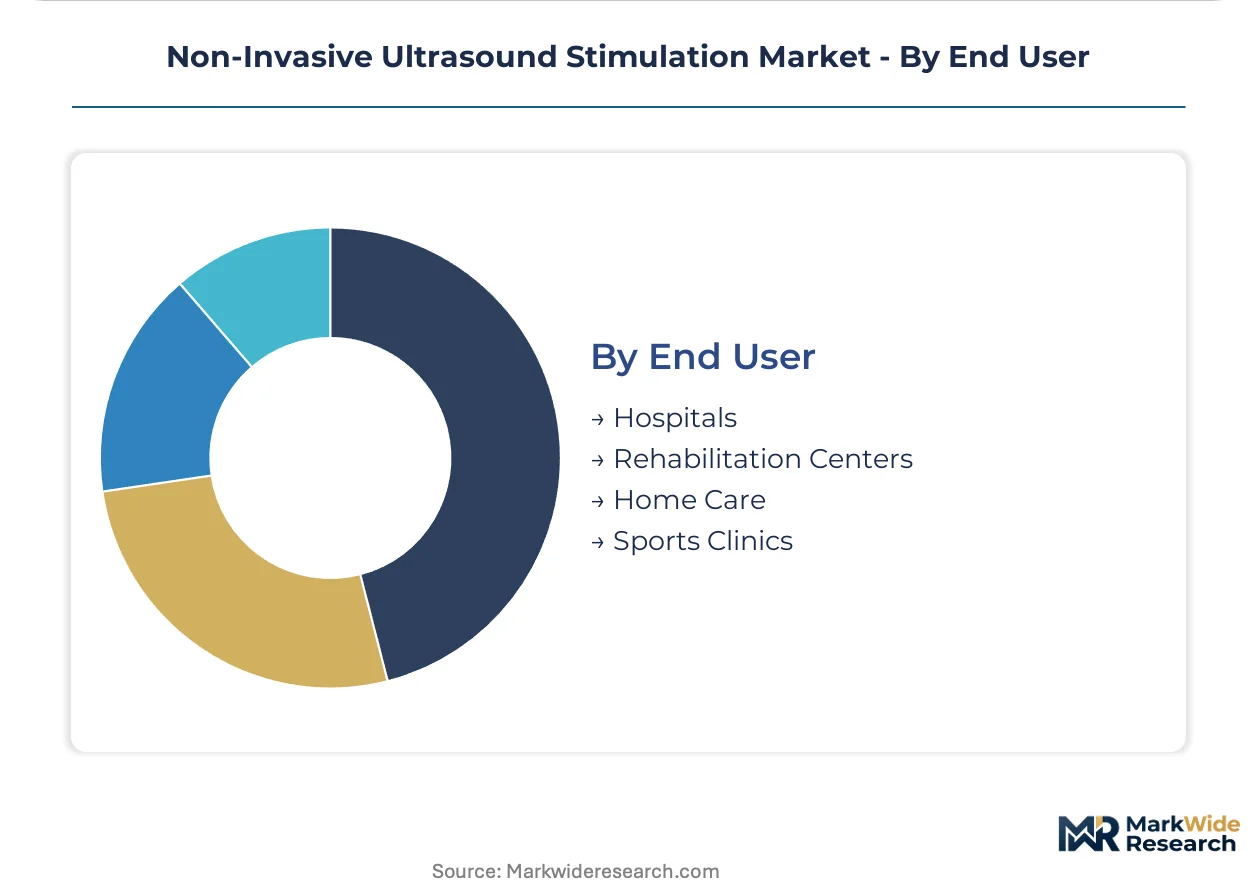
- Hospitals:Integrated imaging-therapy platforms dominate acute care procurement through multi-year service contracts. German and Japanese facility clusters standardize on full-stack vendors.
- Rehabilitation Centers:Dedicated facilities for post-acute recovery prioritize portable hardware with EMR connectivity. US physical therapy chains expand device fleets under CMS billing code expansion.
- Home Care:Direct-to-patient distribution bypasses institutional purchasing bottlenecks. Japan's aging demographic mandate creates regulatory tailwinds for compact stimulation devices.
- Sports Clinics:Professional athletic franchises equip dedicated rehabilitation facilities with portable units for accelerated return-to-play protocols.
Hospitals retain the largest capital deployment, though Home Care is gaining share fastest on demographic and reimbursement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision acoustic hardware to Japanese hospital networks, while South Korean aesthetic clinic chains import HIFU capital equipment from US manufacturers. Trade corridors concentrate high-value therapeutic device flows between established regulatory jurisdictions.
United States
CMS reimbursement expansion for non-pharmacological pain interventions drives procurement across physical therapy chains and sports medicine franchises. FDA 510(k) predicate pathways accelerate commercialization timelines for manufacturers with cleared acoustic platforms. The Boston-Cambridge corridor hosts concentrated R&D activity in neuromodulation hardware.
Germany
Hospital purchasing consortia standardize procurement around full-stack imaging-therapy platforms from diversified health technology conglomerates. EU MDR certification requirements impose extended post-market surveillance obligations that lengthen commercial launch timelines. The Baden-Württemberg industrial cluster anchors precision transducer manufacturing for European distribution.
Japan
METI reimbursement policies for home-based rehabilitation equipment create regulatory tailwinds for compact stimulation devices serving elderly care markets. PMDA quality standards align with international IEC 60601-1-2 electromagnetic compatibility benchmarks. The Kanto region surrounding Tokyo concentrates device assembly operations for domestic and export markets.
South Korea
Aesthetic clinic chains drive volume demand for high-intensity focused ultrasound systems through packaged body contouring and skin tightening procedures. MFDS regulatory frameworks emphasize post-market safety monitoring for thermal bioeffect devices. Seoul-based manufacturing facilities supply capital equipment across Asia-Pacific aesthetic markets.
United Kingdom
NHS procurement frameworks prioritize cost-effective portable units for outpatient rehabilitation services amid budget consolidation pressures. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific approval pathways. The Oxford-Cambridge arc hosts emerging ventures in wearable CMUT-based stimulation hardware.
Non-Invasive Ultrasound Stimulation Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory sophistication dimensions. The vendor base stratifies between diversified imaging conglomerates with full-stack platforms and pure-play neuromodulation ventures with targeted acoustic architectures. Three archetypes dominate: imaging-therapy integrators, wearable CMUT specialists, and HIFU capital equipment manufacturers. M&A activity concentrates on MEMS transducer technology acquisitions, while strategic partnerships target EMR integration capabilities.
Within the imaging-therapy integrator tier, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify scale-driven platform consolidation. These diversified conglomerates anchor hospital procurement relationships through multi-year service contracts spanning diagnostic and therapeutic modalities. Their positioning reflects decades of regulatory navigation across FDA, EU MDR, and PMDA jurisdictions.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| FUJIFILM Corporation |
| Samsung Electronics |
| Neuromod Devices Ltd |
| SonaCare Medical |
| Others |
Value Network & Pricing Analysis
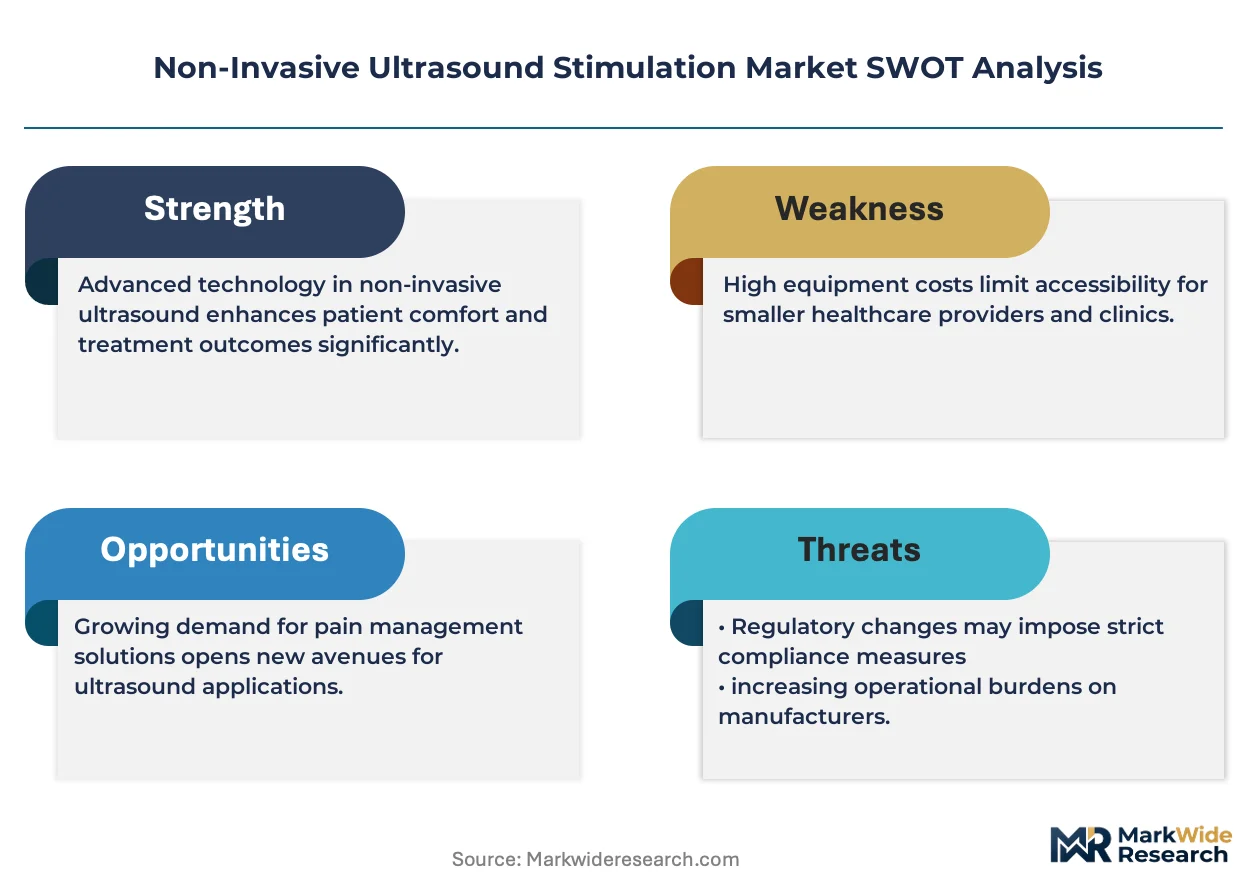
FDA 510(k) premarket notification requirements gate both supplier qualification and price differentiation simultaneously, as cleared predicate platforms command premium positioning while uncertified entrants face extended commercialization timelines that compress margin recovery windows.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels, with integrated imaging-therapy platforms from diversified conglomerates capturing premium positioning through multi-year service bundling while portable units face cost compression from physical therapy chain consolidation. Price differentiation hinges on FDA clearance tier and after-sales service intensity, with reimbursement-aligned devices carrying lower price sensitivity than cash-pay aesthetic systems.
Supply Chain Analysis
Piezoelectric ceramic feedstock concentration in East Asian manufacturing zones exposes device assemblers to input volatility, with Japan, South Korea, and China dominating transducer material output. CMUT silicon wafer fabrication draws from semiconductor foundry capacity in Taiwan and South Korea. Single-source vulnerability in specialty piezoelectric formulations threatens production continuity. Distribution runs through hospital purchasing consortia in Germany, GPO contracts in the United States, and direct-to-patient channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from software companion platforms and remote monitoring subscriptions expands faster than hardware unit sales, creating recurring revenue layers that justify upfront equipment subsidies.
For Market Incumbents: Secure EMR integration capabilities through targeted acquisition of HL7 FHIR interface specialists, as hospital information system connectivity becomes a non-negotiable procurement criterion. Lock in exclusive supply agreements with Japanese piezoelectric ceramic manufacturers to preempt input cost volatility that threatens margin compression in portable device tiers.
For New Entrants and Emerging Players: Differentiate on closed-loop neuromodulation algorithms that merge wearable EEG monitoring with transcranial ultrasound delivery, a white-space application with minimal incumbent penetration. Target Japan's home care channel where METI reimbursement codes reduce customer acquisition friction compared to institutional procurement battles in the United States and Germany.
For Investors and Strategic Acquirers: EU MDR certification timeline extensions reshape the acquisition landscape, as capital-constrained pure-plays face 18-24 month commercialization delays that erode runway. Prioritize targets with cleared FDA 510(k) platforms and existing CMS reimbursement alignment. Watch for CMS billing code expansion for non-pharmacological pain interventions as the signal indicating accelerated hospital procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway Expansion | Leveraging cleared acoustic safety data accelerates neuromodulation indication approvals for manufacturers with imaging platforms. |
| CMUT Transducer Technology Acquisition | MEMS-based capacitive micromachined ultrasound transducers enable wearable form factors with silicon-compatible manufacturing economics. |
| Hospital System Partnership | Multi-year service contracts with German and Japanese acute care networks secure preference over standalone device vendors. |
| Software Companion Development | Remote monitoring platforms capture recurring revenue streams that offset hardware margin compression in portable segments. |
| Reimbursement Strategy | CMS billing code alignment for non-pharmacological pain interventions directly incentivizes physical therapy chain procurement. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and rehabilitation clinic directors provided ongoing calibration against primary field intelligence. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement filings, hospital procurement contract registries, and EU MDR technical documentation repositories. Bottom-up unit shipment estimates triangulated against top-down addressable patient population models.
Cross-referencing against external benchmarks confirmed output consistency across the projection horizon. Segmentation dimensions spanned hardware form factor, acoustic architecture, clinical indication, and care delivery setting. CAGRs derived from logistic adoption curves fitted to historical penetration data and reimbursement policy trajectories. Forecast inputs incorporated transducer material cost indices and regulatory approval timeline distributions.
Material uncertainties — reimbursement coverage reversals, piezoelectric supply disruptions, and EU MDR enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions about continued CMS policy direction and stable East Asian manufacturing output. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Coil Assisted Flow Diverters Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market