
 Natural Fatty Acids Market | 2026-2036
Natural Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fatty Acids Market Intelligence
The direct-to-manufacturer sales channel for specialty oleochemicals is fragmenting as smaller cosmetic brands bypass traditional distributors. Large-scale producers like Wilmar International leverage extensive agricultural supply chains to maintain cost leadership in commodity grades. In contrast, BASF specializes in high-purity fatty acids for pharmaceutical and personal care applications. KLK OLEO competes through its integrated palm oil operations, ensuring consistent feedstock for its global production network.
Natural fatty acids are carboxylic acids with long aliphatic chains, derived from vegetable oils like palm and coconut or animal fats. Their functionality as emulsifiers, surfactants, and lubricants stems from the distinct properties of their hydrocarbon tails. Oleic acid, a monounsaturated fat, dominates the food and beverage application segment due to its stability and health profile. Lauric acid represents the fastest-growing product type, driven by its use in soaps and detergents within the personal care industry.
The European Chemicals Agency (ECHA) enforces REACH registration for all fatty acid volumes, influencing trade flows into the EU. Concurrently, the US FDA's GRAS (Generally Recognized as Safe) notifications and India's FSSAI standards govern their use in food and supplements. Future investment decisions depend on navigating the divergent chemical safety and food contact material regulations across key consumer markets.
Market Dynamics
The fundamental shift toward verifiable, plant-derived ingredients, driven by stringent clean-label regulations in the personal care and food sectors, is the primary force shaping the natural fatty acids market. This pressure reorients supply chains toward certified sustainable sources.
Growth Catalysts
- Regulatory Pressure:The EU's REACH framework forces cosmetic brands toward plant-based inputs, increasing demand for fatty acids as clean-label emulsifiers.
- Functional Food Demand:China’s food processing industry is escalating its use of oleic acid as a stable, functional ingredient in new packaged foods.
- Surfactant Chemistry:Lauric acid's effectiveness in soaps and detergents drives its adoption in the personal care industry, replacing synthetic surfactants.
Market Restraints
- Feedstock Price Volatility:Production costs are linked to price swings in palm and coconut oil, creating margin instability for oleochemical producers.
- Geographic Supply Risk:Dependence on palm oil from Indonesia and Malaysia exposes the supply chain to regional weather events and export policy shifts.
- Synthetic Substitution:In industrial applications like lubricants, synthetic fatty acids offer a price-stable alternative, capping demand during high commodity price cycles.
Strategic Opportunities
- Pharmaceutical Excipients:Producing high-purity fatty acids for pharmaceutical formulations opens a high-value market beyond traditional food and industrial uses.
- Emerging Consumer Markets:Targeting the expanding personal care industries in countries like Brazil and India provides new geographic growth avenues for oleochemical suppliers.
- Direct Sales to Niche Brands:Establishing direct sales channels to service smaller cosmetic brands bypasses traditional distributors and captures higher-margin business.
Industry Challenges
- Regulatory Navigation:Manufacturers face complexity and cost in complying with divergent chemical safety rules, such as the EU's REACH and the US FDA's GRAS notifications.
- Sustainability Certification:Securing and maintaining sustainability certifications for feedstocks like palm oil is costly and complex, yet increasingly a prerequisite for market access in Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fatty Acids Market |
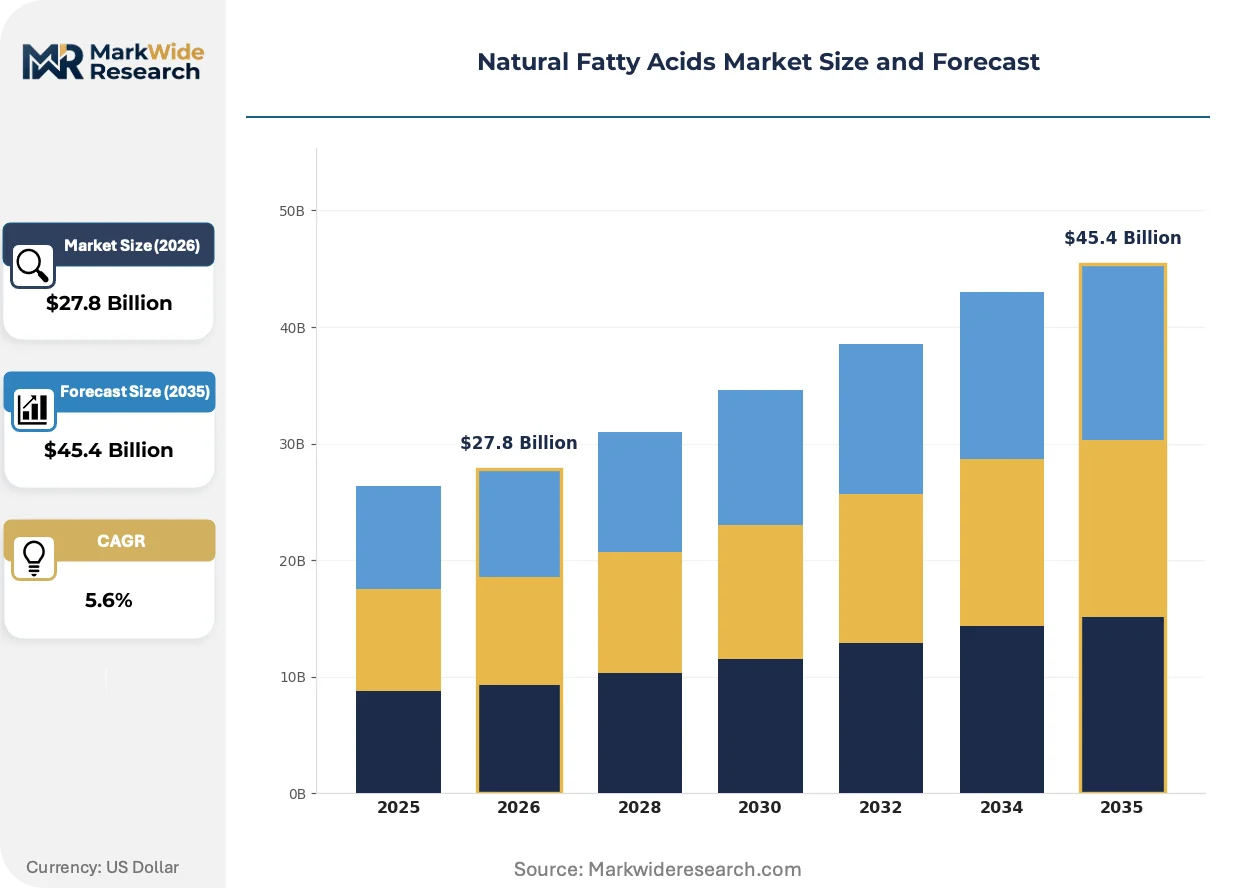
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $45.4 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lauric Acid, Oleic Acid, Palmitic Acid, Stearic Acid, Linoleic Acid Application: Food & Beverage, Personal Care, Pharmaceuticals, Animal Nutrition, Lubricants End User: Cosmetic Manufacturers, Dietary Supplement Producers, Animal Feed Providers, Specialty Chemical Firms Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Plastic Bottles, Metal Cans |
| Companies Covered | Lascaray S.A., BASF, Kraton Corporation, Wilmar International, Cargill, Ingevity, NINGBO INNO PHARMCHEM CO.,LTD., KLK OLEO, Forchem Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fatty Acids Market Strategic Shifts & Innovations
Advanced fermentation and enzymatic processes are redefining production possibilities for specialty fatty acids. This biotechnological shift enables the creation of tailored molecules with specific functionalities, moving beyond the limitations of traditional agricultural feedstocks and their inherent variability.
Enzymatic interesterification is a key process technology used to rearrange fatty acids on a glycerol backbone, modifying the physical properties of fats and oils. Food manufacturers are adopting this to create structured lipids and trans-fat-free shortenings for bakery and confectionery products. This technology is collapsing the rigid link between a specific feedstock like palm oil and a desired functionality, enabling more flexible sourcing.
India's FSSAI has implemented stringent limits on trans-fatty acids in foods, alongside comprehensive labeling mandates for packaged goods. This regulatory action compels food manufacturers to reformulate products, substituting partially hydrogenated oils with healthier alternatives rich in oleic acid. The domestic edible oil and snack food industries are now investing in high-oleic sunflower and rapeseed oil processing to comply.
A significant buying pattern change involves smaller cosmetic brands increasingly bypassing traditional multi-layered distribution networks. These agile companies are establishing direct procurement relationships with oleochemical producers or using digital B2B marketplaces to source specialty fatty acids in smaller volumes. This disintermediation is most pronounced in the North American and Western European natural cosmetics sectors, where speed-to-market is critical.
Natural Fatty Acids Market Segmentation
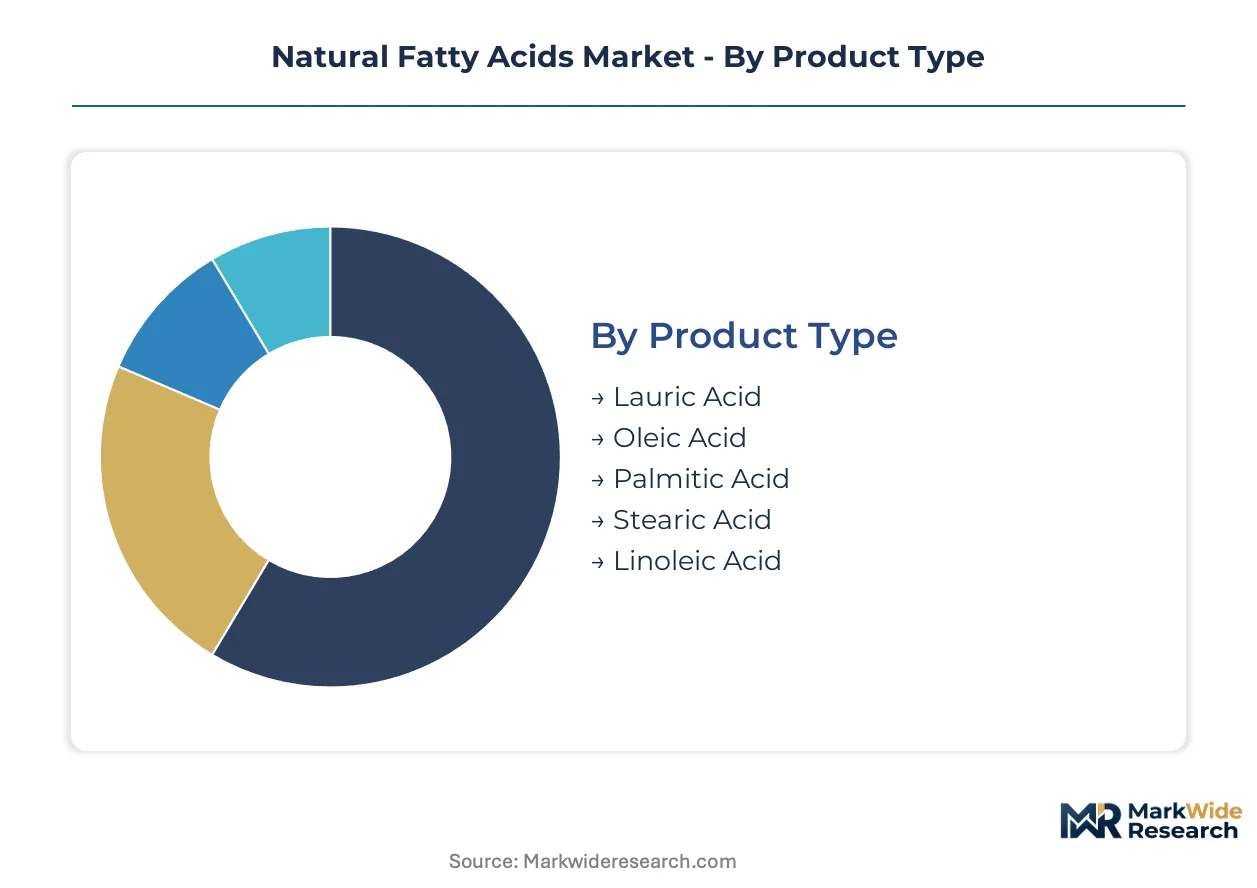
The natural fatty acids market is complex, reflecting diverse product chemistries and end-use requirements across various industries. Understanding these distinct segments allows manufacturers to tailor product offerings and optimize supply chain strategies. Each segment exhibits unique growth drivers and regulatory landscapes influencing its market trajectory.
Product Type:
The product type segment spans both mature and rapidly expanding fatty acid molecules, each with distinct functional properties and market applications.
- Lauric Acid:This saturated fatty acid, primarily sourced from coconut and palm kernel oils, is known for its excellent foaming and cleansing properties. Demand is expanding within the personal care industry, particularly for clean-label soaps and detergents in North America.
- Oleic Acid:A monounsaturated fatty acid abundant in olive oil and high-oleic sunflower oil, it offers high stability and a favorable health profile. China's food processing industry is escalating its use of oleic acid as a functional ingredient in new packaged foods.
- Palmitic Acid:As a common saturated fatty acid, it is widely present in palm oil and animal fats, often used as an emulsifier and texturizer.
- Stearic Acid:This saturated fatty acid finds extensive use in cosmetics, plastics, and rubber manufacturing due to its lubricating and thickening properties.
- Linoleic Acid:An essential polyunsaturated omega-6 fatty acid, it is valued in nutritional supplements and certain cosmetic formulations for skin barrier support.
Oleic Acid retains volume leadership; Lauric Acid holds the steepest expansion curve.
Application:
The application landscape for natural fatty acids is broad, ranging from high-volume industrial uses to specialized, high-purity formulations.
The diverse application scope drives demand for specific fatty acid profiles and purity levels. Each sector imposes unique performance criteria and regulatory compliance standards.
- Food & Beverage:Natural fatty acids serve as emulsifiers, stabilizers, and nutritional components in various food products, enhancing texture and shelf life. China's rapidly expanding food processing sector is a significant consumer of stable fatty acid derivatives.
- Personal Care:Fatty acids are critical ingredients in cosmetics, soaps, and detergents, functioning as surfactants, emollients, and conditioning agents. The global shift towards plant-derived, clean-label formulations directly impacts this segment.
- Pharmaceuticals:High-purity fatty acids act as excipients, solubilizers, and active pharmaceutical ingredients in drug formulations.
- Animal Nutrition:These acids are added to animal feed to improve energy content, palatability, and nutrient absorption for livestock.
- Lubricants:Fatty acid derivatives function as base oils and additives in bio-based lubricants, offering biodegradability and performance in industrial settings.
Food & Beverage applications remain central; Personal Care applications are expanding most quickly.
End User:
The end-user segment reflects the varied business models and specific product needs of companies utilizing natural fatty acids in their manufacturing processes.
Different end-user types exhibit distinct purchasing behaviors and require tailored product specifications, impacting sales channels and technical support needs.
- Cosmetic Manufacturers:These firms incorporate natural fatty acids into clean-label cosmetic formulations, seeking emulsifying and conditioning properties. Smaller brands increasingly bypass traditional distributors to source specialty grades directly.
- Dietary Supplement Producers:Companies in this sector use fatty acids for their nutritional value, often as active ingredients or carriers in softgels and liquid supplements.
- Animal Feed Providers:Manufacturers blend fatty acids into animal feed to enhance energy density and overall nutritional content for livestock and poultry.
- Specialty Chemical Firms:These companies utilize natural fatty acids as building blocks for a wide array of derivatives, including surfactants, esters, and amines, for diverse industrial applications.
Cosmetic Manufacturers drive demand for specialized grades; Specialty Chemical Firms require diverse portfolios.
Packaging Type:
The packaging type segment addresses the logistical and handling requirements for transporting natural fatty acids, varying by volume, physical state, and end-user facility capabilities.
Packaging choices are primarily dictated by order volume, product form (liquid or solid), and the specific storage and handling infrastructure of the customer.
- Drums:Standard 55-gallon drums are common for liquid fatty acids, suitable for mid-volume shipments to industrial clients.
- Bulk Bags:Also known as Flexible Intermediate Bulk Containers (FIBCs), these are used for solid or flaked fatty acids in large quantities, offering efficient handling.
- Intermediate Bulk Containers:IBCs, typically 275 or 330 gallons, offer a cost-effective solution for volumes larger than drums but smaller than tank trucks.
- Plastic Bottles:Smaller volumes of specialty or high-ppurity fatty acids, often for personal care or pharmaceutical applications, are packaged in plastic bottles.
- Metal Cans:Used for specific grades of fatty acids where product integrity, UV protection, or solvent compatibility is critical for smaller volumes.
Drums facilitate standard shipments; Bulk Bags address large-scale industrial requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for natural fatty acids exhibits a distinct asymmetry, with feedstock-rich Southeast Asian nations influencing global supply costs while European markets dictate high-purity product specifications. This dynamic creates complex trade flows and investment incentives across major consumer regions. Regulatory frameworks also diverge significantly, impacting market access for various product types.
China
China's rapidly expanding food processing industry drives significant demand for oleic acid as a stable, functional ingredient in new packaged foods. The country's FSSAI standards govern the permissible use of natural fatty acids in food and supplements. Processing hubs in the Yangtze River Delta are investing in high-oleic sunflower and rapeseed oil processing to meet domestic needs.
United States
The United States personal care sector demands clean-label emulsifiers and surfactants, increasing consumption of lauric and oleic acids. The US FDA's GRAS notifications provide regulatory pathways for natural fatty acids in food and dietary supplements. Cosmetic manufacturers in California and the Northeast corridor are actively seeking plant-derived inputs.
Germany
Germany's pharmaceutical and high-end personal care industries create a strong pull for high-purity fatty acids, particularly for excipients and specialized formulations. The European Chemicals Agency (ECHA) enforces REACH registration for all fatty acid volumes entering the EU market. The Rhine-Ruhr industrial cluster remains a key center for oleochemical processing and research.
India
India's expanding personal care market and the FSSAI's stringent limits on trans-fatty acids compel food manufacturers to reformulate products. This regulatory action drives demand for healthier alternatives rich in oleic acid for the domestic edible oil and snack food industries. Maharashtra and Gujarat anchor significant oleochemical production and consumption within the country.
Indonesia
Indonesia remains a foundational supplier of palm oil, directly impacting the global availability and pricing of lauric and palmitic acids. The country's export policies and sustainability certifications significantly influence international trade flows for natural fatty acid feedstocks. Major palm oil production and refining operations are concentrated on Sumatra and Kalimantan islands.
Natural Fatty Acids Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying foundational oleochemicals. The market exhibits a tiered structure, with large-scale commodity producers contrasting with niche high-purity suppliers serving specialized applications. Strategic archetypes include integrated palm oil refiners, diversified chemical conglomerates, and specialized bio-based ingredient manufacturers. Capacity expansion, strategic partnerships, and targeted portfolio diversification remain dominant competitive moves across the industry.
At the scale-driven end, Singapore-headquartered Wilmar International represents global cost leadership in commodity grades, leveraging extensive agricultural supply chains for natural fatty acids. Malaysia-based KLK OLEO exemplifies a vertically integrated model, ensuring consistent feedstock supply through its comprehensive palm oil operations. German-based BASF AG occupies a distinct position as a diversified chemical conglomerate, specializing in high-purity fatty acids tailored for pharmaceutical and personal care applications. These firms collectively demonstrate the market's segmentation between high-volume commodity production and specialized ingredient supply.
| Leading Market Players |
|---|
| Lascaray S.A. |
| BASF |
| Kraton Corporation |
| Wilmar International |
| Cargill |
| Ingevity |
| NINGBO INNO PHARMCHEM CO.,LTD. |
| KLK OLEO |
| Forchem Oyj |
| Others |
Cost & Logistics Intelligence
Indonesia's concentrated palm oil production capacity directly influences global pricing power for lauric and palmitic acids. This supply concentration creates distinct pricing dynamics and supply chain vulnerabilities for downstream manufacturers of natural fatty acids.
Pricing Analysis
Configured-to-order pricing for high-purity fatty acids coexists with commodity spot pricing for standard grades. The dominant pricing model incorporates contract-based long-term offtake agreements for bulk volumes and transactional pricing for specialized ingredients. Price differentiation stems from purity grade requirements, specific sustainability certifications like RSPO, and volume scale. Pricing softness reflects volatility in palm and coconut oil feedstock prices. Smaller cosmetic brands exhibit higher price sensitivity for specialty grades, while pharmaceutical manufacturers prioritize purity over cost.
Supply Chain Analysis
Oleochemical processing capacity concentrates heavily in Southeast Asian nations, particularly Indonesia and Malaysia, due to their proximity to palm oil plantations. The supply chain draws from raw material dependencies on palm oil, coconut oil, and high-oleic sunflower oil. Geographic supply risk arises from regional weather events and export policy shifts in these key producing countries. Distribution runs through both traditional multi-layered networks for commodity grades and direct-to-manufacturer channels for specialized, smaller-volume fatty acids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural fatty acids market is experiencing a significant buyer-power shift, driven by smaller cosmetic brands increasingly bypassing traditional distributors for direct procurement.
For Market Incumbents:Build integrated feedstock control to mitigate commodity price volatility and secure consistent supply. Wilmar International and KLK OLEO demonstrate this strategic advantage, leveraging extensive agricultural supply chains for cost leadership. Invest in R&D for high-purity applications like pharmaceutical excipients to counter margin pressure from synthetic substitution in industrial uses. Obtaining sustainability certifications remains critical for market access in Europe.
For New Entrants and Emerging Players:Establish a beachhead in niche segments requiring specialized, high-purity fatty acids, such as pharmaceutical formulations or premium personal care. Target the expanding personal care industries in emerging consumer markets like Brazil and India. A viable go-to-market angle involves leveraging digital B2B marketplaces to service smaller cosmetic brands seeking direct procurement relationships and faster speed-to-market.
For Investors and Strategic Acquirers:Long-term, this sits as an essential ingredient play because natural fatty acids underpin the clean-label movement across food and personal care. Target specialized bio-based ingredient manufacturers with strong R&D capabilities in enzymatic processes or integrated oleochemical producers with robust sustainability certifications. The signal to watch is regulatory tightening, such as India's FSSAI limits on trans-fatty acids, driving reformulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Oleic Processing | Supports reformulation efforts in food and beverage sectors in China and India. |
| Backward Integration into Feedstock Cultivation | Mitigates price volatility and ensures consistent supply for oleochemical producers. |
| Investment in Enzymatic Production Technologies | Enables tailored fatty acid molecules with specific functionalities, reducing feedstock dependency. |
| Establishment of Direct Sales Channels | Captures higher-margin business from niche cosmetic brands bypassing distributors. |
| Portfolio Diversification into Pharmaceutical Excipients | Accesses high-value market segments beyond traditional food and industrial applications. |
Research Approach
A spread of perspectives from oleochemical producers, cosmetic R&D managers, food product formulators, and regulatory affairs specialists converged on the working assumptions for this analysis. This involved primary interviews with key industry stakeholders complemented by extensive secondary validation from ECHA REACH filings, US FDA GRAS notifications, India's FSSAI standards, and customs trade data, ensuring a robust bottom-up and top-down triangulation.
The demand-supply-balance framing informed the analytical framework, projecting market trends across the analysis window. Segmentation dimensions modeled included product type, application, end-user, packaging type, and purity grade. Compound annual growth rates were derived from historical trends and projected market drivers, with feedstock price trends and clean-label adoption rates serving as critical forecast inputs.
Sensitivities concentrate around geopolitical events impacting palm oil supply, unforeseen regulatory changes, and rapid synthetic material innovations. Forecasts reflect assumptions regarding these market dynamics. Quarterly review of feedstock commodity prices, regulatory updates, and consumer preference shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Food Grade Alginate Market