
 Food Texture Market | 2026-2036
Food Texture Market Size, Share, and Industry Trends Forecast 2026-2036
Food Texture Market Intelligence
China's expansion of hydrocolloid production facilities is rewriting the supply dynamics for key texturants, impacting global cost structures and ingredient availability. Cargill leverages its extensive agricultural sourcing to secure raw materials for starches and fibers. Meanwhile, Tate & Lyle specializes in developing clean-label texturizing solutions for health-conscious consumer segments. Kerry Group competes by integrating texture modification into its broader taste and nutrition system offerings for food manufacturers worldwide.
Food texture involves using agents to modify the physical properties and mouthfeel of food and beverage products. These ingredients, such as hydrocolloids, control parameters like viscosity, gelation, and emulsification to enhance product stability and consumer sensory experience. Hydrocolloids and emulsifiers represent foundational product types, while demand for plant-derived fibers is accelerating. Applications in meat alternatives and dairy products are expanding rapidly, driven by formulation shifts toward plant-based ingredients.
Regulatory frameworks significantly influence ingredient formulation and market access. The U.S. Food and Drug Administration (FDA) governs the GRAS status of texturants, while the European Food Safety Authority (EFSA) manages E-number approvals and clean-label claims. In China, compliance with national GB standards for food additives is mandatory. Ingredient suppliers must navigate these divergent requirements to ensure product compliance and market acceptance across key geographies.
Market Dynamics
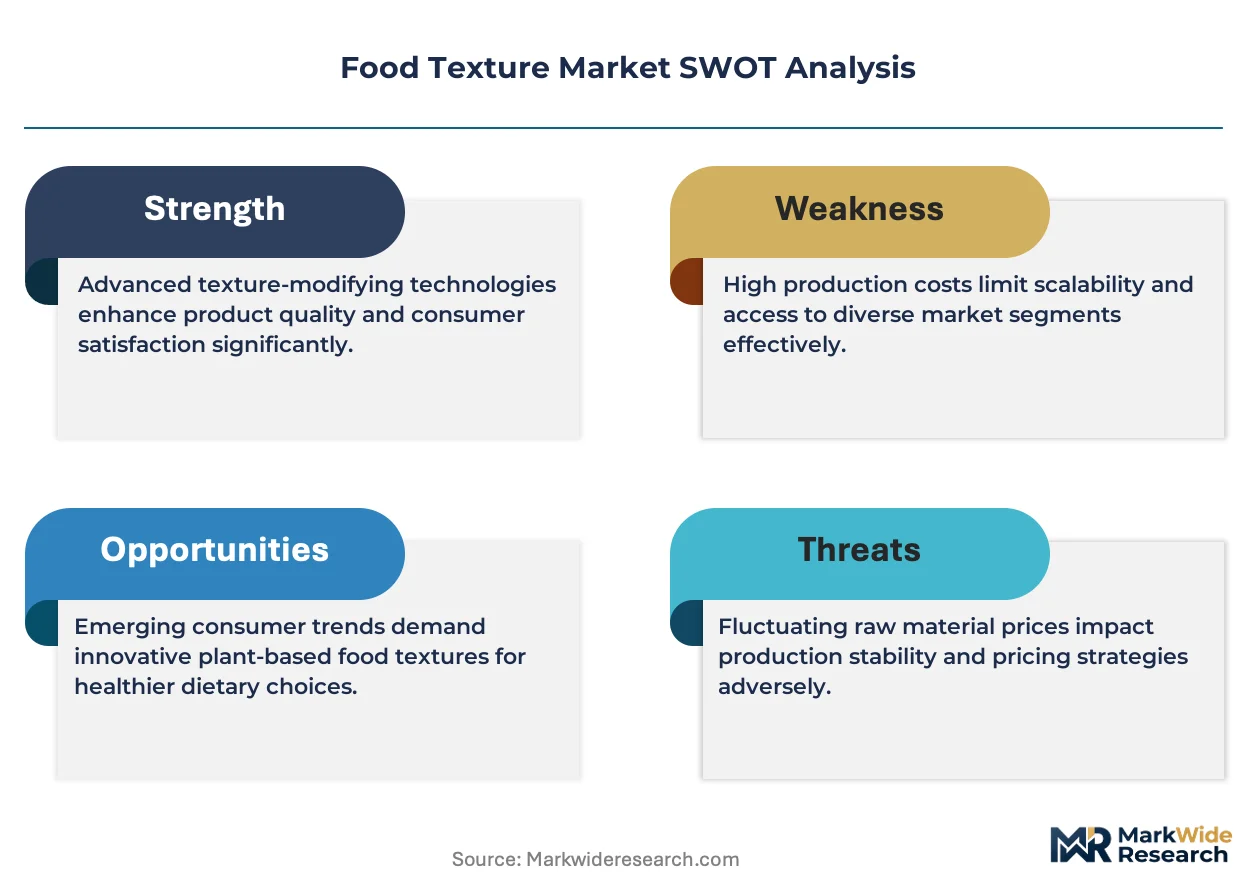
The central tension in the food texture market is the divergence between consumer demand for clean-label, plant-based foods and the industrial-scale supply dynamics of hydrocolloids. This creates a constant push-pull between formulation innovation and cost-containment strategies for manufacturers.
Growth Catalysts
- Plant-Based Demand:Consumer adoption of plant-based diets is accelerating the need for sophisticated texturants in meat and dairy alternatives to replicate the mouthfeel and structure of conventional products.
- Clean-Label Regulations:European Food Safety Authority (EFSA) clean-label guidelines encourage manufacturers to replace synthetic additives with natural texturants like fibers and specific hydrocolloids, creating demand for these ingredients.
- Asian Industrialization:The expansion of China's food processing sector establishes a concentrated demand hub for texturizing agents, supporting both domestic hydrocolloid production and imports of specialized fibers.
Market Restraints
- Supply Chain Concentration:Global dependency on a few geographies, like China for certain hydrocolloids, introduces significant price volatility and supply chain risk for food manufacturers worldwide.
- Regulatory Divergence:Disparate approval pathways, such as the FDA's GRAS system versus EFSA's E-number framework, increase compliance costs and delay market entry for ingredient suppliers.
- Technical Hurdles:Natural texturants often exhibit performance variability under different processing conditions, such as high heat or acidity, limiting their use-case and requiring more formulation expertise.
Strategic Opportunities
- Novel Applications:Developing texturizing systems for 3D-printed foods, particularly for personalized nutrition and complex meat analogues, presents a high-value opportunity for specialized hydrocolloid blends.
- Geographic Expansion:Southeast Asian markets offer white-space opportunities for texturant suppliers to adapt solutions for the region's growing packaged food industry and unique culinary profiles.
- Formulation Technology:The convergence of AI-driven platforms with high-throughput screening can drastically shorten R&D cycles for creating novel texture systems that meet precise sensory and functional targets.
Industry Challenges
- Raw Material Volatility:Securing a consistent supply of natural raw materials, such as specific seaweeds or plant saps, is a major operational challenge due to climate impacts and geopolitical factors in sourcing regions.
- Compliance Burden:Adhering to the complex web of national food additive regulations, including China's mandatory GB standards, demands significant investment in local expertise and extensive product testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Texture Market |
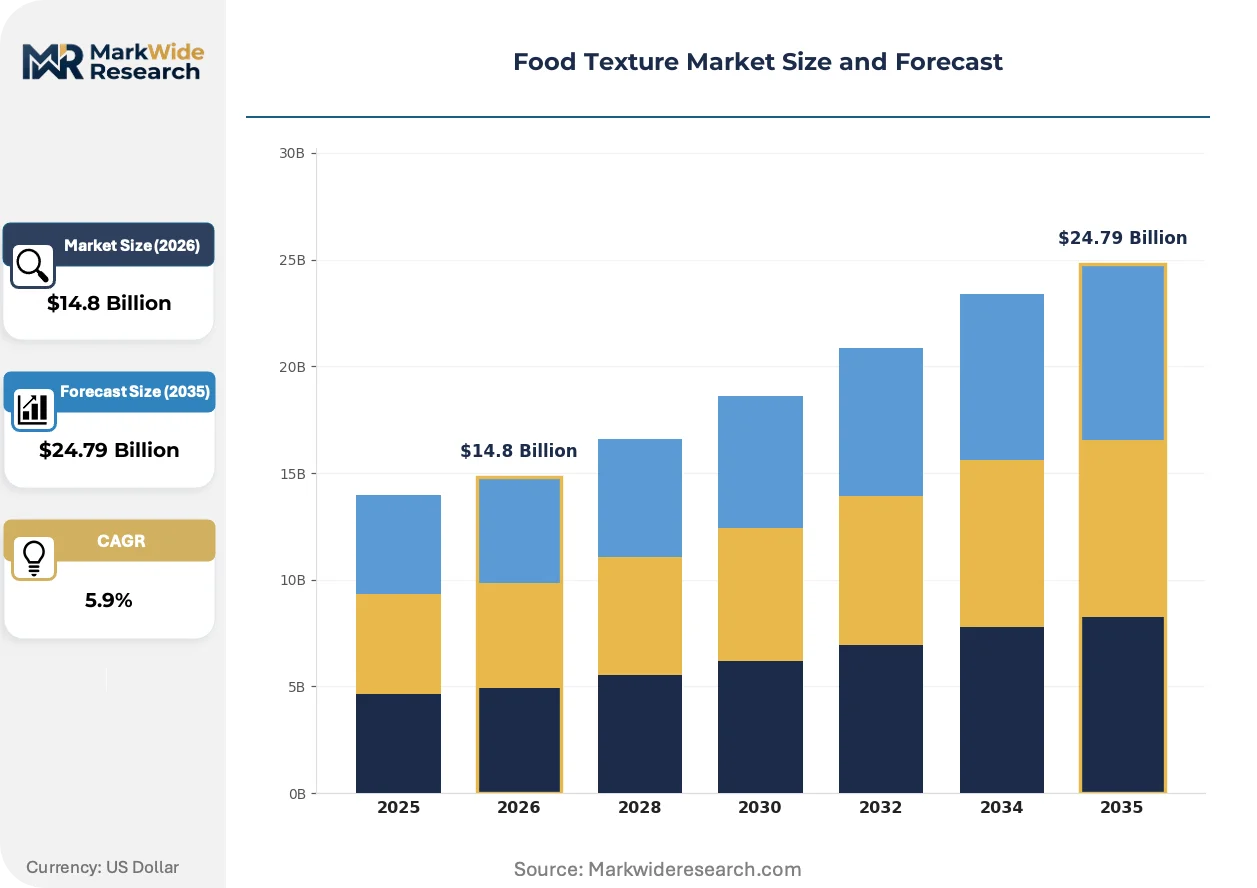
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Emulsifiers, Enzymes, Starches, Fibers Application: Bakery, Confectionery, Beverages, Dairy Products, Meat Alternatives End User: Food & Beverage Manufacturers, Food Service Providers, Ingredient Suppliers, R&D Laboratories Form: Powder, Liquid, Granular, Gel, Paste |
| Companies Covered | Tate & Lyle, Kerry Group, Archer-Daniels-Midland Company, DuPont de Nemours, International Flavors & Fragrances, Cargill, CP Kelco, Ashland, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Texture Market Strategic Shifts & Innovations
Formulation science is evolving from using single-function ingredients to designing integrated texture systems. This shift addresses consumer demand for both superior sensory experiences and transparent, clean-label ingredient lists, altering how food products are developed and marketed.
Precision fermentation is a key technological advance, creating novel proteins and polysaccharides that function as highly effective texturizing agents. Innovators in alternative dairy and egg replacement categories are rapidly adopting these for their unique gelling and emulsifying capabilities. The market’s technology focus is migrating from simply modifying existing starches to engineering bio-identical texturants with superior performance and clean-label credentials.
The U.S. Food and Drug Administration (FDA) is applying greater scrutiny to the "Generally Recognized as Safe" (GRAS) notification process for new ingredients. This regulatory action is forcing suppliers to provide more extensive safety and toxicological data, extending development timelines for novel texturants. The hydrocolloid segment is most impacted, prompting suppliers to invest more in upfront clinical studies to secure a favorable GRAS determination.
A significant behavioral change sees food manufacturers seeking integrated "taste and texture" solutions from a single supplier instead of procuring individual components. This trend disrupts the traditional ingredient sales model, improving the competitive positioning of suppliers that offer pre-blended systems for applications like plant-based yogurts. This demand pattern is most visible in North America and Europe, where speed-to-market is a critical factor.
Food Texture Market Segmentation
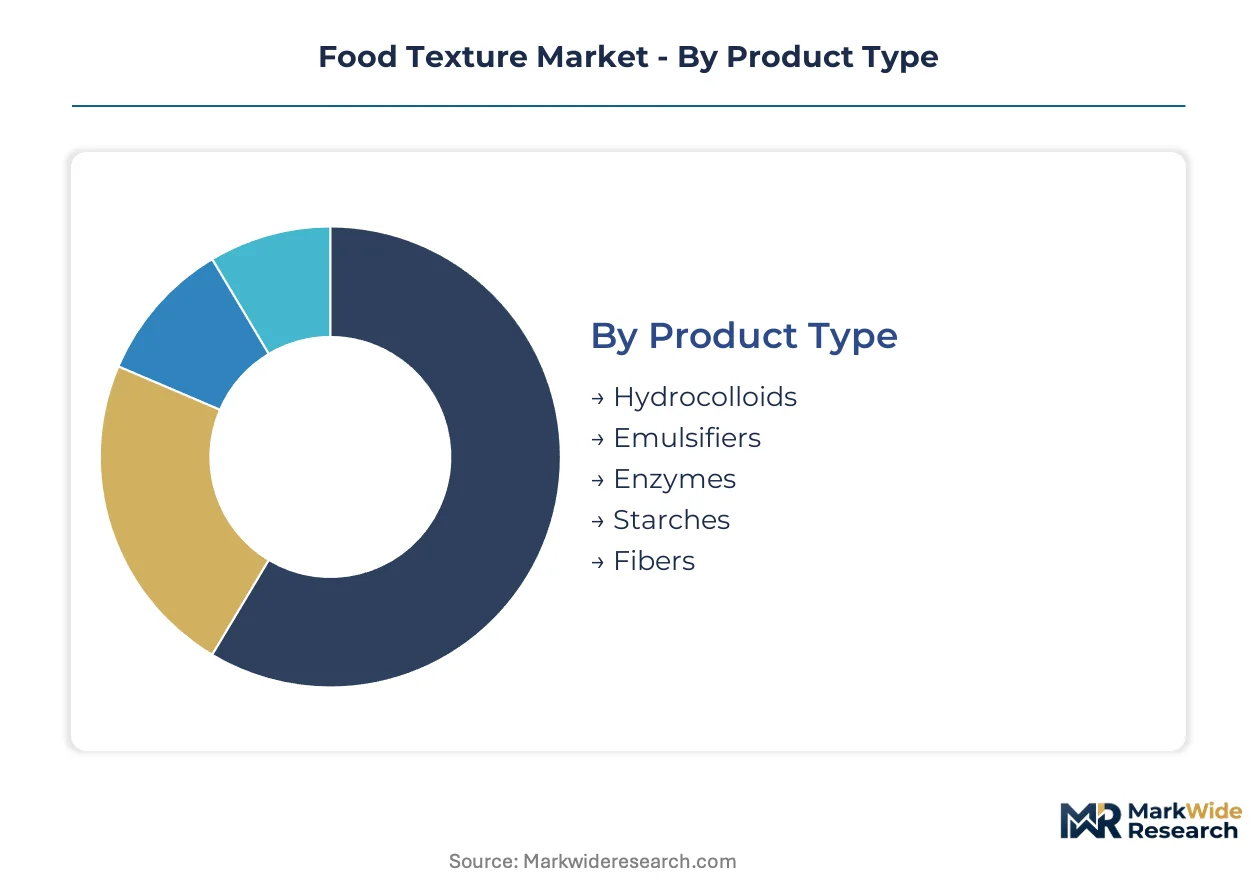
The Food Texture Market's segmentation provides a granular view of ingredient types, application areas, and end-user demands shaping product development. Understanding these distinct segments is crucial for ingredient suppliers and food manufacturers to align innovation with specific market needs and regulatory landscapes.
Product Type:
The functional characteristics of texturants define their utility across various food and beverage formulations.
- Hydrocolloids:These ingredients, derived from natural sources, significantly impact viscosity, gelation, and emulsification in food products. Demand for clean-label hydrocolloids is concentrating in European and North American markets, driven by consumer preference for natural ingredients.
- Fibers:Plant-derived fibers enhance texture, provide bulk, and contribute to nutritional profiles in numerous food applications. Formulation shifts towards plant-based meat and dairy alternatives in Asian markets, particularly China, accelerate fiber adoption.
- Emulsifiers:Emulsifiers stabilize oil-in-water or water-in-oil systems, preventing phase separation in processed foods.
- Enzymes:Enzymes modify protein structures and starch functionality, improving dough rheology and product shelf-life.
- Starches:Starches serve as primary thickening and gelling agents, offering cost-effective texture solutions across the food industry.
Starches hold installed capacity. Fibers is rotating up the share rankings.
Application:
End-use application segments reflect the diverse functional requirements for texture modification in consumer products.
- Meat Alternatives:This segment requires sophisticated texturants to replicate the fibrous structure and mouthfeel of conventional meat products. Consumer adoption of plant-based diets in the U.S. and Germany drives significant ingredient innovation in this category.
- Dairy Products:Texturants in dairy, including plant-based dairy, provide desired creaminess, stability, and body to yogurts, cheeses, and beverages. Formulation shifts towards vegan options in the UK and France create new opportunities for specialized hydrocolloids.
- Bakery:Bakery products utilize texturants to control crumb structure, moisture retention, and dough workability.
- Confectionery:Confectionery applications use texturants for gelling, thickening, and crystallization control in candies and jellies.
- Beverages:Texturants provide mouthfeel, stability, and suspension properties in various liquid food products.
Meat alternatives exhibit the steepest expansion trajectory.
End User:
Customer type delineation highlights the primary actors driving procurement and innovation in the food texture supply chain.
- Food & Beverage Manufacturers:These entities integrate texturants into their product formulations to achieve specific sensory attributes and processing efficiencies. Manufacturers in Japan and South Korea prioritize clean-label and functional texturants for their diverse product portfolios.
- Ingredient Suppliers:Ingredient suppliers develop and distribute a wide array of texturizing agents, often offering customized blends and technical support. China's expanding food processing sector supports robust demand for these specialized ingredients.
- Food Service Providers:Food service operations use texture ingredients for on-site preparation and menu item consistency.
- R&D Laboratories:These laboratories conduct research on novel texturant functionalities and application development for future food products.
Food & Beverage Manufacturers represent the largest demand volume.
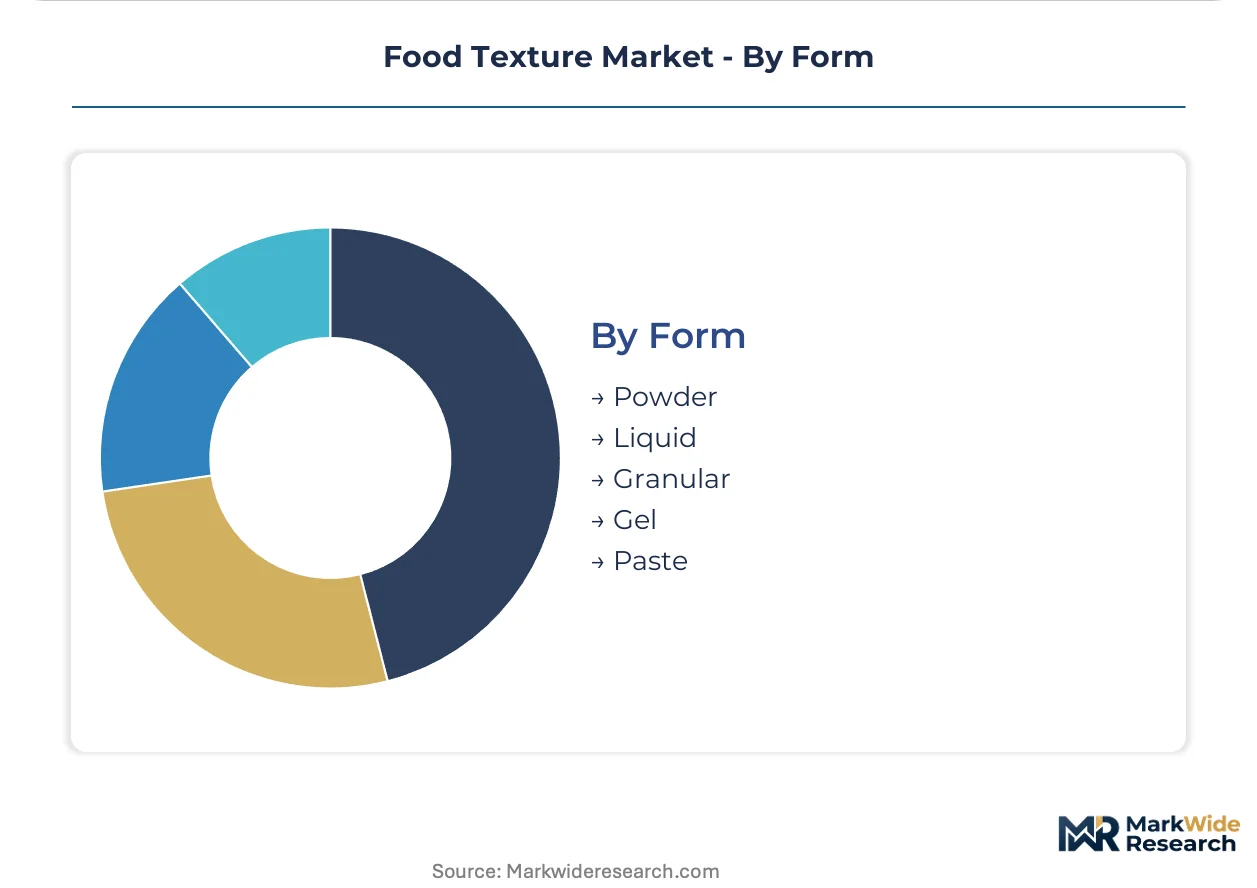
Form:
The physical form of food texturants influences their handling, solubility, and integration into different production processes.
- Powder:Powdered texturants offer ease of handling, precise dosing, and excellent shelf stability for dry blending applications. The widespread use of powdered hydrocolloids in processed foods across India and Brazil underscores this segment's utility.
- Liquid:Liquid texturants provide immediate dispersion and can simplify processing steps, particularly in beverage and dairy applications. European beverage manufacturers increasingly seek pre-hydrated liquid solutions for efficiency gains.
- Granular:Granular forms offer controlled dissolution rates and reduced dusting during handling.
- Gel:Gel forms are often pre-hydrated solutions used in specific applications requiring immediate texture contribution.
- Paste:Paste forms provide high concentration and specific rheological properties for specialized food systems.
Powdered forms maintain widespread utility across diverse product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global food texture market exhibits significant regional variations in both supply dynamics and demand drivers. Supply-side concentration in key geographies heavily influences ingredient availability and cost structures worldwide. This creates a complex interplay of local preferences, regulatory landscapes, and industrial capacities.
China
China's expanding food processing sector drives substantial demand for texturizing agents, particularly for plant-based food formulations. Compliance with national GB standards for food additives is mandatory, guiding ingredient selection. The Yangtze River Delta region is a major hub for hydrocolloid production, impacting global supply chains.
United States
United States consumer adoption of plant-based diets fuels demand for sophisticated texturants in meat and dairy alternatives. The U.S. Food and Drug Administration (FDA) governs GRAS status, influencing market entry for novel ingredients. Innovation clusters in California actively develop new texture solutions for alternative protein markets.
Germany
German food manufacturers prioritize natural texturants for plant-based dairy and meat alternatives, driven by health-conscious consumers. European Food Safety Authority (EFSA) clean-label guidelines encourage natural fibers and specific hydrocolloids. North Rhine-Westphalia hosts a significant food processing industry, concentrating demand for functional ingredients.
India
India's burgeoning processed food sector creates widespread utility for powdered hydrocolloids, particularly in convenience food applications. The Food Safety and Standards Authority of India (FSSAI) regulates food additives, ensuring product compliance. Food manufacturing hubs in Maharashtra drive substantial procurement of cost-effective texture solutions.
Japan
Japanese food and beverage manufacturers prioritize clean-label and functional texturants for their diverse product portfolios. Compliance with national food additive standards, overseen by METI, ensures ingredient quality and safety. The Kanto region serves as a key center for food R&D and advanced texturant application development.
Food Texture Market Key Industry Players
Global ingredient conglomerates and specialized texturant developers split the food texture market. The industry structure reflects a tiered landscape, with large players offering extensive portfolios and niche firms focusing on specific functional solutions. Diversified ingredient suppliers leverage their broad capabilities, while specialized companies drive innovation in clean-label and high-performance texturants. Competitive moves often involve strategic partnerships to expand application knowledge and targeted acquisitions to integrate novel technologies or market access.
Among the large, diversified ingredient suppliers, Cargill leverages its extensive agricultural sourcing to secure raw materials for starches and fibers. Tate & Lyle occupies a strong position in developing clean-label texturizing solutions, catering to health-conscious consumer segments. Kerry Group exemplifies the strategy of integrating texture modification into broader taste and nutrition system offerings for food manufacturers worldwide. These companies demonstrate varying approaches to market leadership, from raw material control to integrated solution provision.
| Leading Market Players |
|---|
| Tate & Lyle |
| Kerry Group |
| Archer-Daniels-Midland Company |
| DuPont de Nemours |
| International Flavors & Fragrances |
| Cargill |
| CP Kelco |
| Ashland |
| Ingredion Incorporated |
Cost & Logistics Intelligence
China's concentrated hydrocolloid production facilities exert significant influence over global texturant pricing. This upstream control impacts the margin structures of downstream food and beverage manufacturers.
Pricing Analysis
European Food Safety Authority (EFSA) clean-label guidelines dictate the pricing tier structure for natural texturants. Pricing primarily follows contract-based long-term offtake agreements, with premium-mid-economy differentiation based on certification level and customization. Cost compression for commodity starches is intensifying due to ample supply. Food & Beverage Manufacturers exhibit high price sensitivity for bulk ingredients, while R&D laboratories pay premiums for novel solutions.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support supplier liquidity in a capital-intensive industry. Supply concentrates in China for hydrocolloids and Southeast Asia for natural raw materials like seaweeds. The market relies on specific plant saps and specialized starches. Commodity price volatility, driven by climate impacts, represents a significant supply chain risk. Distribution runs through direct sales channels from ingredient suppliers to food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food texture market requires a strong substitution defense strategy from incumbents. Precision fermentation, creating novel bio-identical texturants, represents a significant threat to traditional ingredient suppliers.
For Market Incumbents:Harden core intellectual property around integrated texture systems to counter the performance variability of natural texturants. Invest in R&D for AI-driven formulation platforms, accelerating novel ingredient discovery. Pursue targeted acquisitions of specialized clean-label firms to expand portfolios. This strategy mitigates the threat from emerging bio-identical texturants and regulatory scrutiny on GRAS status.
For New Entrants and Emerging Players:Southeast Asian markets offer significant underpenetration for specialized texturant solutions tailored to local culinary preferences. Target the rapidly expanding packaged food industry within this region. Focus on developing customized hydrocolloid blends for unique regional applications. A go-to-market strategy emphasizing technical support and localized formulation expertise will accelerate adoption.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-cap ingredient specialists focused on clean-label solutions or niche hydrocolloids. Long-term viability remains strong due to fundamental demand for food modification, but formulation needs are evolving. Target precision fermentation innovators or firms with strong intellectual property in integrated texture systems. The successful commercialization of bio-identical texturants represents a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in AI-driven Formulation | Accelerates development of novel texture systems that meet precise sensory and functional targets. |
| Acquisition of Clean-Label Specialists | Expands portfolio of natural texturants, aligning with EFSA clean-label guidelines. |
| Capacity Expansion in Asia | Addresses concentrated demand from China's expanding food processing sector. |
| Precision Fermentation Investment | Secures access to bio-identical texturants with superior performance and clean-label credentials. |
| Integrated Taste & Texture System Development | Meets manufacturer demand for single-supplier solutions, improving speed-to-market for plant-based yogurts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase. Interviews with food technologists, R&D directors, procurement leads, and regulatory affairs specialists provided qualitative insights. Secondary validation drew from FDA GRAS notifications, EFSA E-number approvals, and national GB standards. This approach facilitated bottom-up market sizing and top-down cross-referencing.
Calibration of the forecast framework integrated qualitative insights with quantitative models across the analysis window. Market segmentation dimensions included product type, application, end-user, form, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical trend analysis and projected growth drivers. Key forecast inputs included consumer dietary shifts towards plant-based foods and regional food processing expansion rates.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or commodity prices would shift the trajectory. Forecasts reflect assumptions regarding consumer preferences and technological adoption. Geopolitical instability affecting raw material supply or rapid shifts in regulatory approval processes could also prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Global Zeaxanthin Market