
 Europe Food Preservatives Market | 2026-2036
Europe Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Preservatives Market Foresight
CE marking under EU Regulation 1333/2008 on food additives is reorganizing competitive access across the Europe Food Preservatives Market, forcing reformulation investments before products reach supermarket shelves. Kerry Group PLC leverages its clean-label fermentation-derived portfolio to anchor premium positioning in Western European dairy applications. BASF SE dominates synthetic antioxidant supply chains with manufacturing scale that sustains cost leadership across multiple benzoate grades.
Food preservatives comprise chemical or biological substances added to food matrices at concentrations typically ranging from 0.01% to 0.3% to inhibit microbial spoilage, enzymatic browning, or oxidative rancidity, thereby extending shelf stability and reducing food waste in commercial distribution. Sorbates maintain broad-spectrum antifungal efficacy in bakery applications where water activity supports mold proliferation, while sulfites face structural decline across the beverage segment due to consumer sensitivity concerns and tightening residual limits. Nitrates occupy a mature margin pool in cured meat processing where no viable alternative currently delivers equivalent color fixation and botulism inhibition at comparable cost.
EFSA, ECHA, and national regulators such as BfR in Germany enforce tiered toxicological reassessments that directly determine which preservative classes retain approved usage levels across EU member states. REACH compliance obligations for synthetic additive manufacturers create fixed-cost barriers that favor larger suppliers with dedicated regulatory affairs functions. Stakeholders must monitor EFSA's ongoing re-evaluations of benzoate exposure scenarios, as pending opinion revisions could force rapid substitution toward natural preservation systems before implementation deadlines crystallize.
Market Dynamics
EFSA's ongoing toxicological reassessments of benzoate and sorbate exposure thresholds are forcing European formulators to accelerate clean-label transitions ahead of implementation deadlines, restructuring procurement priorities across ready-to-eat and dairy processing clusters.
Growth Catalysts
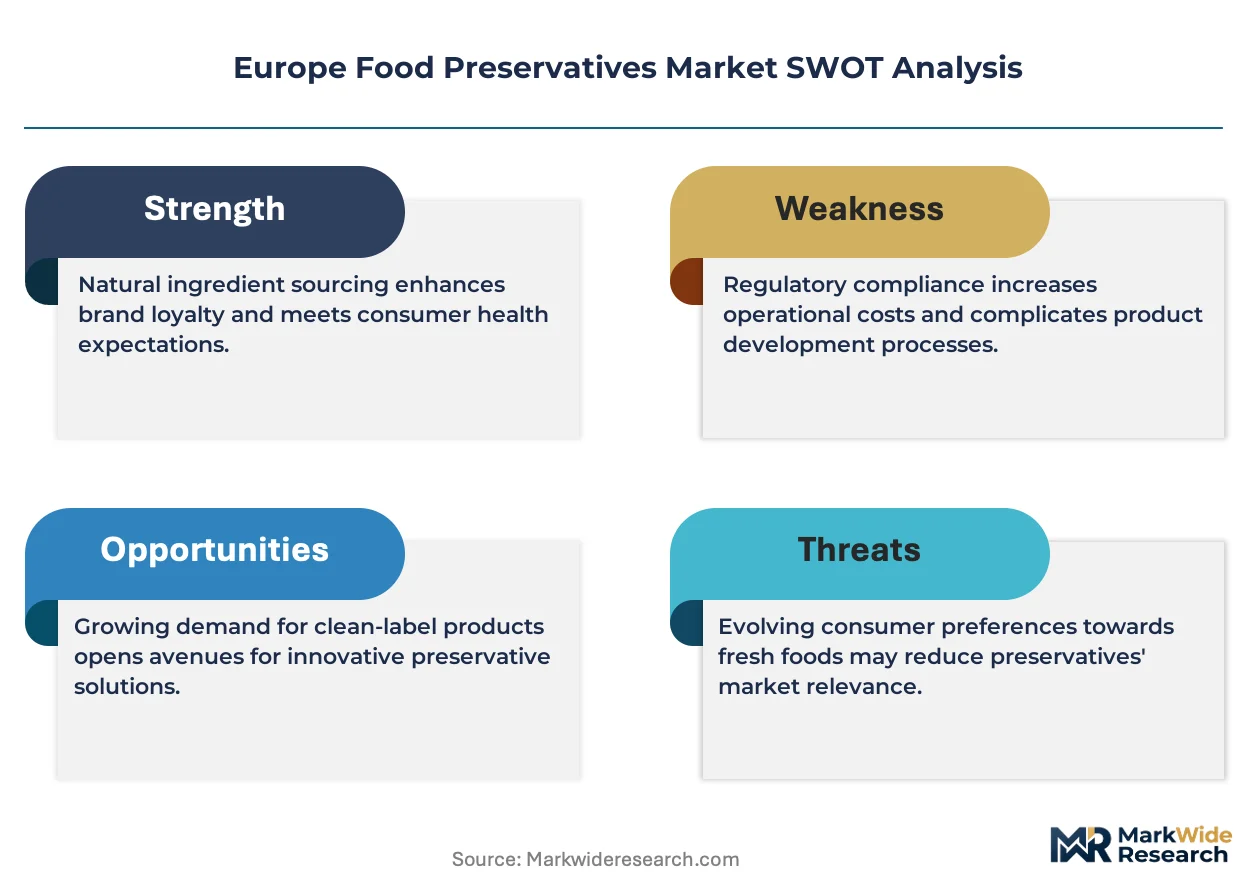
- Clean-label mandates from retail buyers:Supermarket chains in Germany and France now require preservative-free or natural-only formulations in private-label ready meals, compelling processors to source fermentation-derived alternatives.
- REACH compliance consolidation:Registration obligations for synthetic additive manufacturers favor larger suppliers with dedicated regulatory affairs functions, streamlining market access for compliant producers.
- Water activity challenges in bakery:Extended ambient distribution of sliced bread and pastries across Italy and Spain drives demand for mold-inhibiting solutions in high-moisture applications.
Market Restraints
- Natural preservative cost premiums:Fermentation-derived antimicrobials cost 3-5x synthetic equivalents, compressing margins for mid-tier processors serving price-sensitive retail channels.
- Sulfite residual limits under EFSA:Tightening maximum permitted levels in beverages and dried fruits eliminate certain applications and force costly reformulation or product line discontinuation.
- Technical performance gaps:No natural alternative currently matches nitrate efficacy for botulism inhibition and color fixation in cured meats, locking processors into declining ingredient categories.
Strategic Opportunities
- Poland and Romania processing expansion:Central and Eastern European meat and dairy production growth outpaces local preservative supply, creating entry points for Western European suppliers with regulatory expertise.
- Plant-based protein preservation:Emerging alt-meat formulations in the Netherlands and UK require novel antimicrobial systems adapted to neutral pH and high-protein matrices without traditional animal-processing preservatives.
- EU Green Deal packaging-waste linkages:Extended shelf life from optimized preservation directly supports reduction targets, positioning preservatives as enablers of circular economy compliance for food manufacturers.
Industry Challenges
- Reformulation timeline compression:EFSA opinion-to-implementation windows often allow less than 18 months for full product redevelopment, straining R&D capacity at mid-sized processors.
- Cross-border regulatory fragmentation:National derogations and divergent enforcement interpretations between BfR in Germany and ANSES in France create compliance complexity for pan-European product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Preservatives Market |
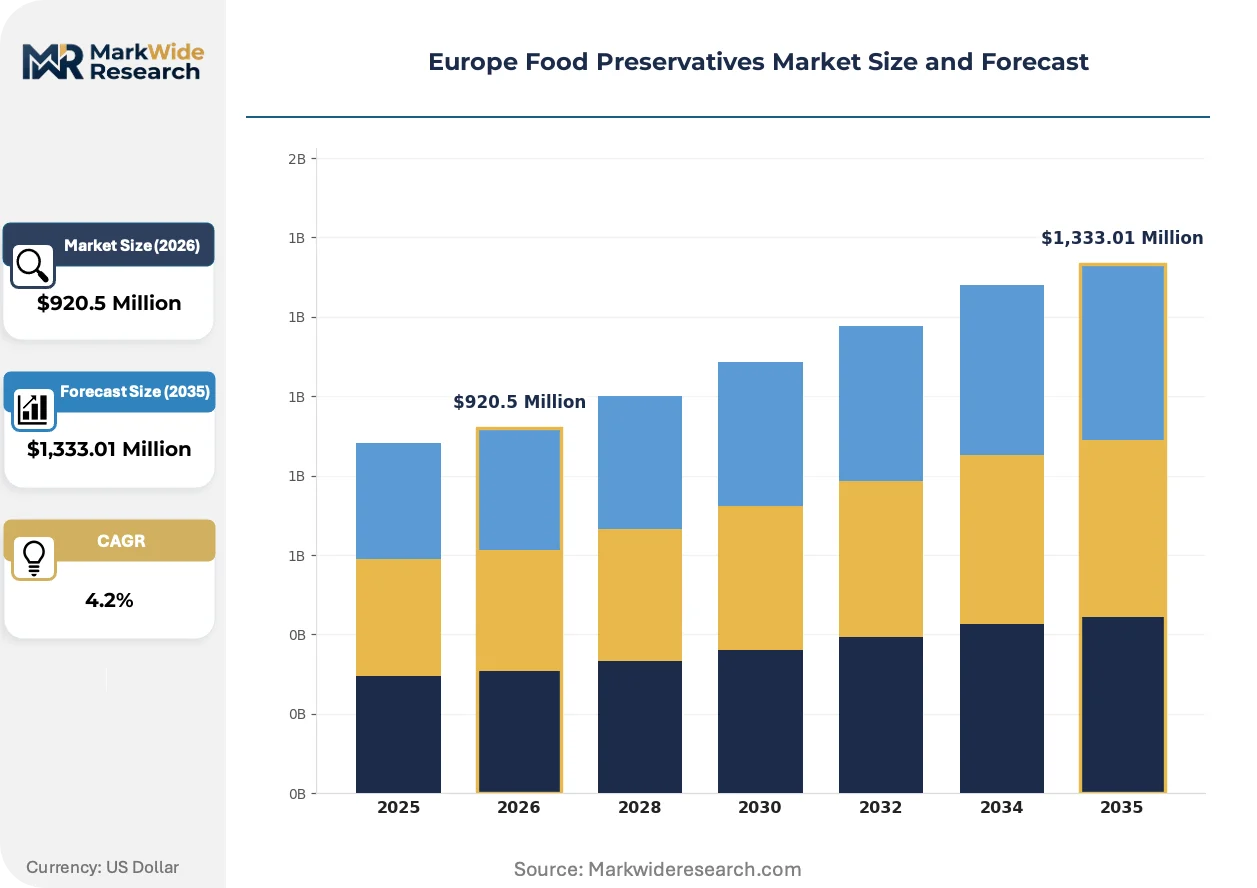
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,333.01 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Nitrates, Sulfites, Benzoates Application: Beverages, Bakery, Dairy, Snacks Form: Liquid, Powder, Granular, Crystal End User: Food Manufacturers, Retailers, Food Service, Households |
| Companies Covered | Kerry Group PLC, Koninklijke DSM N.V., DuPont de Nemours, Inc., Corbion NV, Tate & Lyle PLC, Cargill, Archer Daniels Midland Company, Jungbunzlauer Suisse AG, BASF SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Preservatives Market Shifts & Advancements
Preservation technology in Europe is pivoting from synthetic chemistry toward biological and fermentation-based systems, with regulatory pressure and retail procurement standards converging to accelerate adoption curves.
Cultured dextrose and fermented wheat flour are supplanting benzoates in sauce and dressing applications where processors previously relied on cost-optimized synthetic antimicrobials. German and French dairy manufacturers have moved fastest, converting 40-60% of relevant SKU portfolios within 24 months of retail buyer deadlines. This substitution is compressing demand for traditional synthetic grades while expanding contract manufacturing capacity for fermentation-derived alternatives.
EFSA's systematic re-evaluation of food additives under Regulation 1333/2008 is removing grandfathered status from legacy preservatives and demanding contemporary toxicological data packages. Manufacturers face capital allocation decisions between defending existing approvals and redirecting investment toward natural preservation R&D. The beverage sector bears disproportionate impact, with sulfite restrictions already triggering portfolio rationalization among sparkling wine and dried fruit processors.
Direct sourcing relationships between preservative suppliers and retail private-label developers are displacing traditional distributor-mediated procurement in Western Europe. Large supermarket chains now specify preservation systems at formulation stage, compressing the value chain and marginalizing regional ingredient distributors. This pattern is most pronounced in the UK and Netherlands, where concentrated retail consolidation enables centralized technical specification.
Europe Food Preservatives Market Segmentation
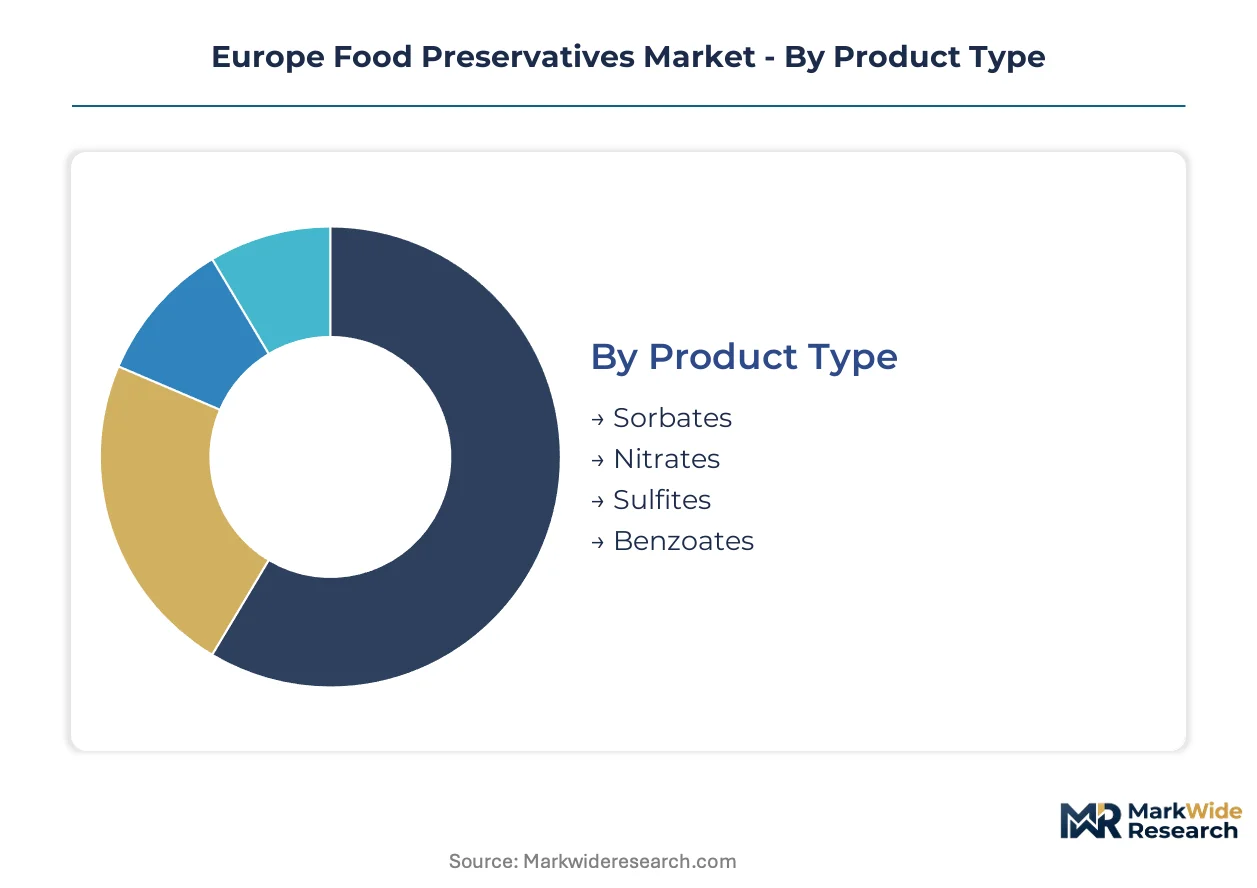
Preservative selection across Europe varies sharply by export destination requirements versus domestic-only production. EFSA's additive approvals create continent-wide baseline standards, yet national derogations and retail procurement codes fragment effective demand patterns across member states.
Product Type:
Domestic consumption of traditional synthetics dominates in Germany and France, while export-oriented processors in Poland and Spain prioritize EFSA-compliant grades with maximum residual flexibility for third-country shipments.
- Sorbates:Potassium and calcium salts deliver broad-spectrum antifungal activity effective at pH ranges below 6.5. German and Italian bakery clusters consume substantial volumes for sliced bread and ambient pastry distribution where water activity exceeds 0.85. Reformulation pressure from EFSA exposure reassessments is accelerating substitution toward fermented alternatives in sauce applications.
- Nitrates:Sodium and potassium nitrate/nitrite systems provide irreplaceable botulism inhibition and cured color fixation in processed meats. Demand concentrates in Polish, Spanish, and Italian charcuterie operations where no natural alternative matches performance at comparable cost. EFSA's ongoing additive re-evaluation under Regulation 1333/2008 threatens maximum permitted level reductions.
- Sulfites:Sulfur dioxide and metabisulfite salts function as antimicrobial and antioxidant agents in wine, dried fruits, and potato products. Residual sensitivity concerns and tightening EFSA maximum limits are eliminating certain beverage applications.
- Benzoates:Sodium and potassium benzoates inhibit yeast and mold in acidic foods including carbonated beverages and condiments. Pending EFSA toxicological opinions are forcing accelerated clean-label transitions ahead of implementation deadlines.
Sorbates hold the largest share; momentum sits with fermented alternatives displacing synthetic grades.
Application:
Cost tier stratification separates premium clean-label formulations in Western European retail from price-optimized synthetic preservation in Central and Eastern European food service channels.
- Beverages:Carbonated soft drinks, juices, and functional drinks require pH-specific antimicrobial systems. German and French bottlers are converting fastest to fermentation-derived preservation following retail buyer mandates.
- Bakery:Sliced bread, cakes, and pastries face severe mold spoilage risks during ambient distribution. Italian and Spanish processors drive bulk procurement of sorbate-based solutions for high-moisture formulations.
- Dairy:Yogurt, cheese, and cultured products demand selective antimicrobial targeting without probiotic inhibition. Clean-label fermentation systems are gaining share fastest in premium French and Dutch dairy portfolios.
- Snacks:Extruded products, nuts, and dried fruit applications balance oxidative rancidity prevention with shelf-life extension. Sulfite restrictions are forcing reformulation in dried fruit segments across multiple EU markets.
Bakery commands the largest volume base; dairy shows the steepest expansion trajectory for natural preservation systems.
Form:
Volume concentration favors liquid and powder formats in industrial-scale food manufacturing, while granular and crystal grades serve specialized applications requiring precise dosing control.
- Liquid:Ready-to-use aqueous solutions enable automated dosing in high-throughput beverage and sauce production lines. German processing clusters prefer liquid sorbate systems for continuous manufacturing efficiency.
- Powder:Free-flowing granular powders offer extended shelf stability and flexible reconstitution across bakery and dry-mix applications. French and Italian millers specify powder benzoates for premix formulations.
- Granular:Intermediate particle size balances dissolution speed with handling characteristics. Meat processors in Poland and Spain utilize granular nitrate blends for uniform curing brine preparation.
- Crystal:High-purity crystalline grades serve pharmaceutical-adjacent food applications and analytical standards. Limited demand concentrates in specialized Swiss and Dutch ingredient distribution.
Powder maintains the largest installed base; liquid formats are climbing the fastest on automation trends.
End User:
Customer type determines specification intensity, with multinational food manufacturers demanding full regulatory documentation while household segments prioritize convenience and price.
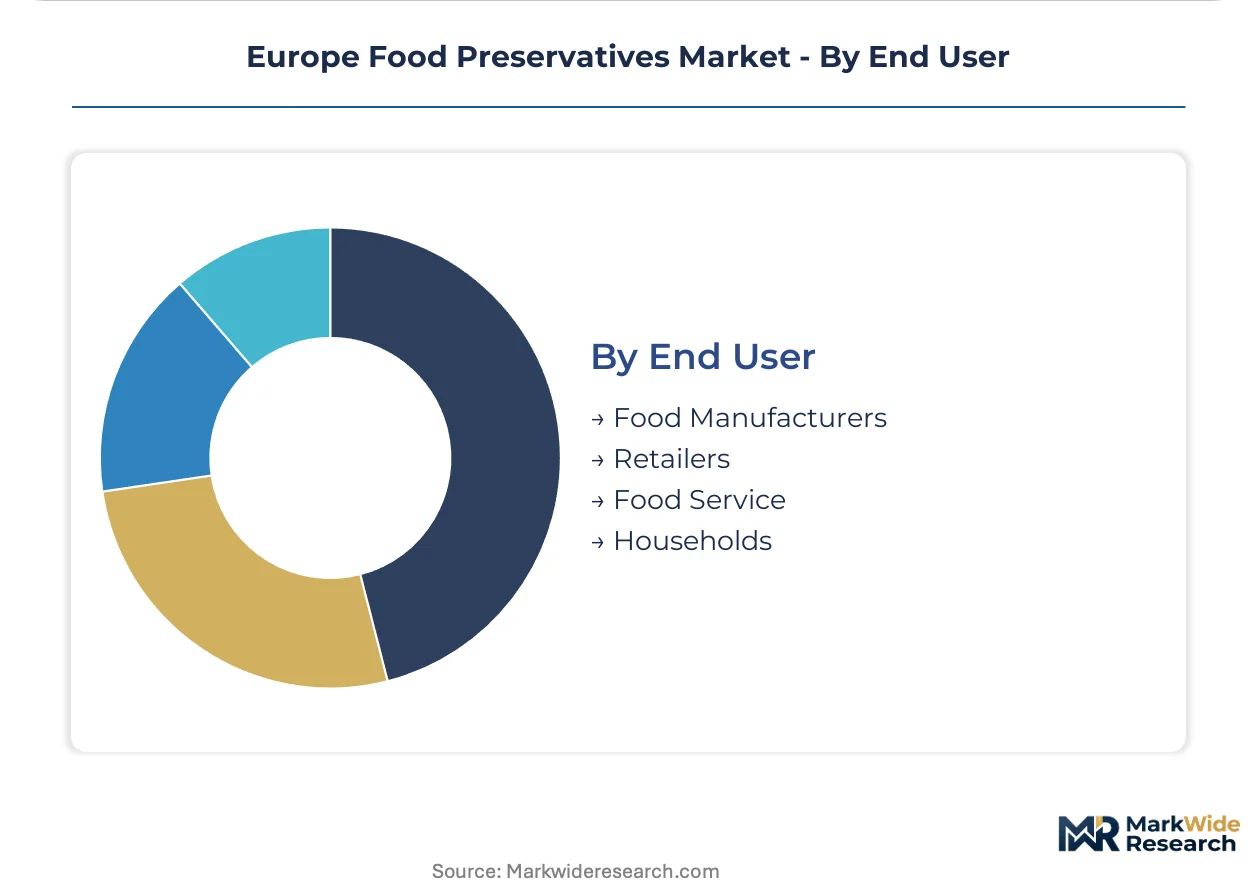
- Food Manufacturers:Industrial processors of meat, dairy, bakery, and beverage products drive bulk procurement through tender-based supply agreements. EFSA compliance documentation and REACH registration certificates are mandatory for supplier qualification.
- Retailers:Supermarket chains and private-label developers increasingly specify preservation systems at formulation stage, bypassing traditional distributor channels. UK and Netherlands retail consolidation enables centralized technical procurement.
- Food Service:Restaurant chains, catering operations, and institutional kitchens utilize preserved ingredients and prepared components rather than direct preservative purchasing. Cost pressure favors synthetic grades in price-sensitive Central European channels.
- Households:Consumer-facing preservative sales for home canning and preservation represent a marginal segment concentrated in traditional Southern European markets.
Food manufacturers dominate procurement volume; retailers are gaining specification authority fastest through private-label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Regulation 1333/2008 harmonizes food additive standards across member states, yet national enforcement variations and retail procurement codes create distinct operating environments. Germany, France, Italy, Poland, and Spain concentrate the continent's preservative demand through their food processing clusters.
Germany
Bakery and dairy manufacturers in Bavaria and North Rhine-Westphalia drive substantial sorbate consumption for sliced bread distribution. BfR enforces stricter-than-minimum benzoate exposure guidelines, accelerating clean-label transitions ahead of EFSA deadlines. The Munich-Stuttgart corridor hosts fermentation-derived preservative R&D facilities serving private-label retail chains.
France
Premium dairy and sauce formulators in the Île-de-France and Auvergne-Rhône-Alpes regions prioritize natural preservation systems for export positioning. ANSES maintains divergent enforcement interpretations on sulfite residual limits compared to German counterparts. Lyon-based processing clusters are converting 40-60% of relevant SKUs to fermented alternatives within compressed retail timelines.
Italy
Charcuterie operations in Emilia-Romagna and Lombardy sustain mature nitrate demand for cured meat color fixation and botulism inhibition. EFSA's ongoing additive re-evaluation threatens maximum permitted level reductions in traditional salami production. Parma and Modena processing hubs face reformulation pressures without viable natural alternatives at comparable cost.
Poland
Meat and dairy production growth in the Mazovia and Silesia regions outpaces local preservative supply capacity. REACH compliance obligations favor Western European suppliers with dedicated regulatory affairs functions. Warsaw and Łódź manufacturing zones create entry points for fermentation-derived antimicrobial systems as clean-label penetration accelerates.
Spain
Ambient pastry distribution across Catalonia and Andalusia sustains mold-inhibiting sorbate demand in high-water-activity applications. Tightening EFSA sulfite restrictions eliminate certain dried fruit and beverage applications, forcing portfolio rationalization. Barcelona processing clusters balance export compliance requirements with domestic price-sensitive food service channels.
Europe Food Preservatives Market Competitive Landscape
Player mix skews toward diversified ingredient conglomerates with fermentation capabilities and specialized chemical manufacturers with REACH-registered synthetic portfolios. Market structure exhibits tiered consolidation, with a handful of pan-European suppliers commanding bulk procurement relationships while regional specialists serve niche applications. Strategic archetypes include clean-label biotechnology platforms, cost-optimized synthetic antioxidant producers, and integrated food-ingredient conglomerates with formulation services. Competitive moves center on M&A to acquire fermentation-derived technology assets and capacity expansion in Central and Eastern European markets.
Among Irish and Dutch biotechnology platforms, Kerry Group PLC and Koninklijke DSM N.V. exemplify the clean-label archetype through fermentation-derived antimicrobial positioning. German chemical conglomerate BASF SE anchors the synthetic antioxidant tier with manufacturing scale across multiple benzoate grades. These three entities represent the dominant competitive vectors: biological preservation systems, synthetic chemistry cost leadership, and integrated formulation services spanning both categories.
| Leading Market Players |
|---|
| Kerry Group PLC |
| Koninklijke DSM N.V. |
| DuPont de Nemours, Inc. |
| Corbion NV |
| Tate & Lyle PLC |
| Cargill |
| Archer Daniels Midland Company |
| Jungbunzlauer Suisse AG |
| BASF SE |
| Others |
Supply & Pricing Matrix
Manufacturing scale at German and Dutch fermentation facilities anchors price floors for natural preservatives, concentrating supply among REACH-compliant producers while compressing margins for smaller synthetic suppliers facing reformulation-driven demand erosion.
Pricing Analysis
Certification level under EU Regulation 1333/2008 and REACH registration status creates the primary spread between premium fermentation-derived grades and commodity synthetics. Three-tier pricing structure across premium clean-label, standard EFSA-compliant, and economy unregistered tiers separates multinational food manufacturers from mid-tier processors and price-sensitive food service channels. Pricing pressure stems from natural preservative cost premiums running 3-5x above synthetic equivalents, compressing margins for processors serving private-label retail. Mid-tier bakery and sauce manufacturers exhibit highest price sensitivity, while premium dairy and ready-meal brands absorb premiums for clean-label positioning.
Supply Chain Analysis
Antwerp-Rotterdam port capacity constraints and Rhine barge availability intermittently choke preservative raw material flows into German and French processing clusters. Bulk chemical production concentrates in Germany, the Netherlands, and Belgium, with fermentation-derived capacity expanding fastest in Ireland and Denmark. Supply chains draw from petrochemical feedstocks for benzoate and sorbate synthesis, while natural alternatives hinge on agricultural substrate supply and bioreactor capacity utilization. Single-source vulnerability sits with concentrated fermentation capacity for clean-label alternatives. Distribution runs through integrated ingredient conglomerates with direct retail relationships displacing traditional distributor channels across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as retail procurement codes splinter demand into clean-label premium, EFSA-compliant standard, and residual synthetic tiers, creating niche entry points for specialized suppliers with regulatory expertise.
For Market Incumbents: Shield existing synthetic preservative revenues by accelerating backward integration into fermentation capacity before EFSA implementation deadlines crystallize. Prioritize certification investment for REACH-registered grades to maintain access to pan-European food manufacturer tenders. Vertical integration into bioreactor assets in Poland and Romania secures cost positioning against emerging biotechnology platforms.
For New Entrants and Emerging Players: Anchor in Central and Eastern European meat and dairy processing expansion where local clean-label supply lags demand growth. Target Polish and Romanian manufacturing zones with fermentation-derived antimicrobial systems tailored to high-moisture bakery and neutral-pH plant protein matrices. Pursue direct technical partnerships with retail private-label developers to bypass established distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology platforms with scalable fermentation infrastructure over legacy chemical synthesis assets. Long-term viability hinges on regulatory tailwinds accelerating natural preservatory substitution across the analysis window. Acquisition focus should center on Irish and Dutch fermentation specialists with retail-validated clean-label portfolios. Signal to monitor: EFSA opinion publication timelines for benzoate and sorbate exposure reassessments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures margin compression from natural preservative premiums while securing supply for EFSA-compliant reformulations. |
| REACH Registration Investment | Maintains market access for synthetic grades as regulatory barriers consolidate supplier base toward compliant producers. |
| Direct Retail Technical Partnerships | Bypasses distributor channel compression by embedding preservation specification at private-label formulation stage. |
| Central and Eastern European Capacity Expansion | Positions supply close to fastest-growing meat and dairy processing clusters in Poland and Romania. |
| Plant-Based Protein Preservation R&D | Develops antimicrobial systems for emerging alt-meat formulations requiring neutral pH compatibility without traditional animal-processing preservatives. |
Research Methodology
Desk research of EFSA additive re-evaluation dossiers, EU customs trade data, and REACH registration databases preceded structured interviews with regulatory affairs directors at preservative manufacturers, procurement leads at German and French food processors, and technical specification managers at UK and Netherlands retail chains. Primary fieldwork combined with secondary validation against industry association reports from FoodDrinkEurope and Cefic. Bottom-up segmentation modeling triangulated against top-down market sizing from production capacity and consumption intensity metrics.
Variance decomposition across product type, application, and end-user dimensions structured the analytical framework over the projection horizon. Modeled segmentation captured preservative chemistry class, food processing application, physical form factor, and customer procurement archetype. CAGRs derived from intensity-of-use coefficients applied to food production volume forecasts, cross-referenced with substitution elasticity parameters for natural versus synthetic preservatory systems. Forecast inputs incorporated EFSA regulatory timeline scenarios and retail clean-label penetration curves.
Material uncertainties — EFSA opinion revision timing, REACH enforcement intensity variations, and retail procurement code harmonization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and substitution cost thresholds. Practitioners should keep alternative scenarios live as EFSA toxicological reassessment conclusions and EU Green Deal packaging-waste linkages evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
North America Native Starch Market