
 Global Food Carbohydrase Market | 2026-2036
Global Food Carbohydrase Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Carbohydrase Market Analysis
Buyer concentration among industrial bakers is shifting as multinational bakery chains consolidate procurement while artisan and regional producers fragment demand across smaller enzyme formulators. Novozymes A/S anchors the premium liquid enzyme segment through specialized brewing and baking solutions. BASF SE leverages its global chemical distribution network to compete on formulation bundling and technical service. DSM-Firmenich AG differentiates through integrated nutrition-enzyme portfolios that span human and animal applications.
Food carbohydrases comprise a class of hydrolytic enzymes that cleave glycosidic bonds in starch, sucrose, and related polysaccharides, typically operating at temperatures between 50°C and 90°C and pH ranges of 4.0 to 7.0 depending on the specific enzyme variant and application. These biocatalysts serve industrial food processing by accelerating starch liquefaction, sugar inversion, and dextrinization without introducing chemical residues. Alpha-amylase dominates volume demand due to its foundational role in starch thinning across beverage and bakery operations, while pullulanase captures expanding share in high-glucose syrup production where debranching specificity commands technical premiums. The liquid form segment leads overall value owing to ease of dosing automation in continuous processing lines, though powder formats sustain relevance in dry-mix and distributed manufacturing settings.
Regulatory frameworks including EFSA safety evaluations, FDA GRAS notifications, and REACH compliance requirements govern enzyme approval pathways and labeling standards across major producing jurisdictions. These protocols directly shape product development timelines, manufacturing site qualifications, and cross-border market access for formulated enzyme products. Stakeholders must monitor evolving enzyme classification under the EU AI Act and emerging genome-editing disclosure rules, as regulatory clarity on novel production strains will determine competitive positioning in next-generation biocatalyst supply.
Market Dynamics
Industrial bakers are consolidating procurement around enzyme suppliers capable of delivering integrated dough-conditioning and shelf-life extension solutions, compressing vendor relationships from multi-source to dual-source arrangements across large-scale baking operations.
Growth Catalysts
- EU Green Deal biocatalytic mandates:The regulation accelerates substitution of chemical processing aids with enzyme-driven alternatives in starch modification and sugar inversion applications.
- Germany's baking cluster concentration:Overlapping enzyme production facilities and industrial-scale bakeries in the Rhineland region generate localized demand density for liquid alpha-amylase formulations.
- Continuous processing automation:Liquid enzyme dosing systems integrate with SCADA-controlled production lines, reducing manual handling and batch-to-batch variability in high-throughput facilities.
Market Restraints
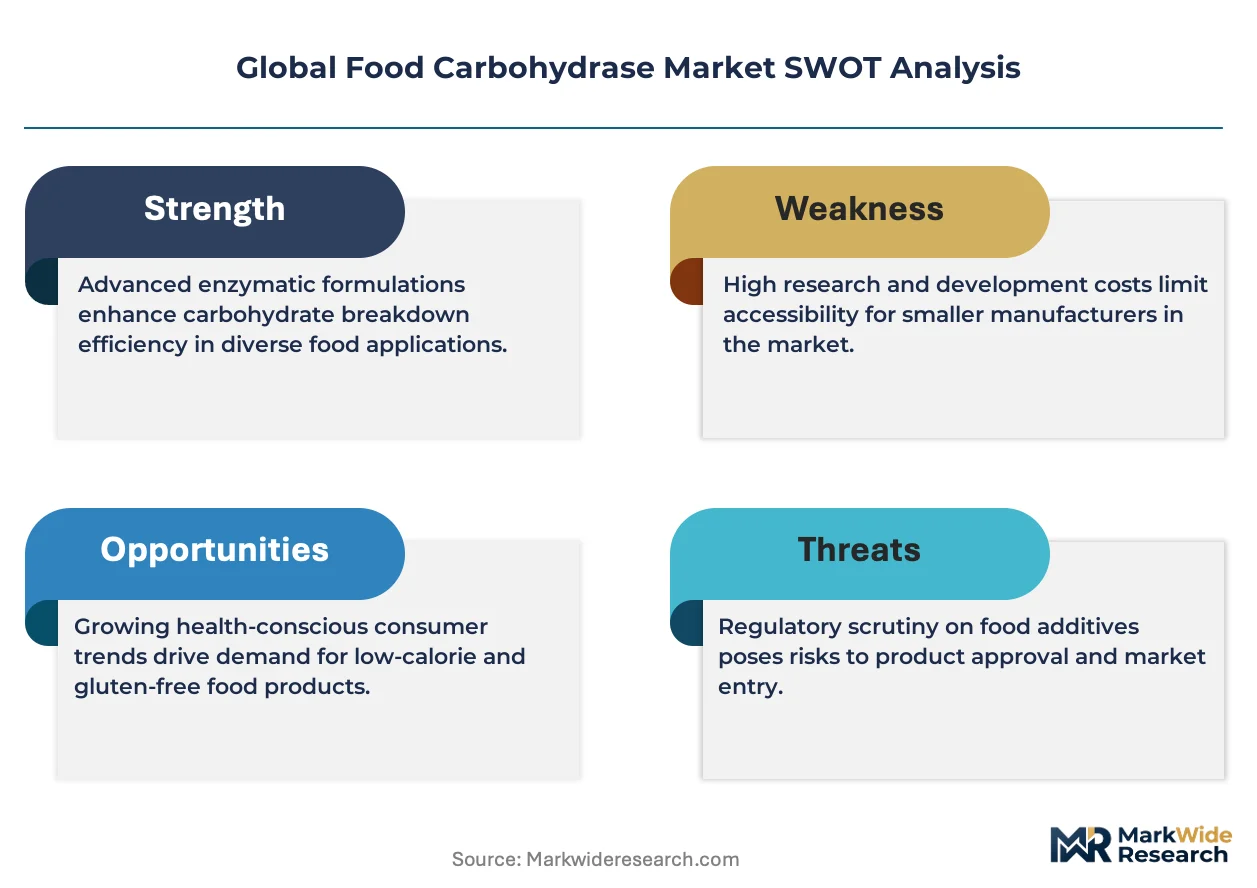
- Fermentation substrate cost volatility:Corn and wheat bran price swings directly impact enzyme production economics, squeezing margin buffers for formulators without captive carbohydrate supply.
- Strain development IP concentration:Patent thickets around CRISPR-optimized production organisms limit independent development of novel thermostable variants.
- REACH enzyme registration timelines:Extended ECHA evaluation periods delay market entry for new biocatalyst formulations, extending payback periods on R&D investment.
Strategic Opportunities
- India FSSAI clean-label acceleration:The regulator's push for reduced chemical additive declarations creates openings for enzyme-based texture and preservation solutions in packaged foods.
- Pulullanase-synergized high-glucose syrup production:Debranching enzyme cocktails enable 96%+ glucose yields from starch, capturing technical premiums in confectionery and fermentation feedstock applications.
- Direct-to-artisan distribution platforms:Digital procurement channels bypass traditional chemical distributor markups for small-batch enzyme buyers in regional baking cooperatives.
Industry Challenges
- Enzymologist talent scarcity:Specialized protein engineering expertise concentrates at research universities and incumbent producers, constraining startup scale-up capabilities.
- Legacy HTST system retrofit complexity:Integrating precision enzyme dosing into existing high-temperature short-time processing lines requires capital-intensive control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Carbohydrase Market |
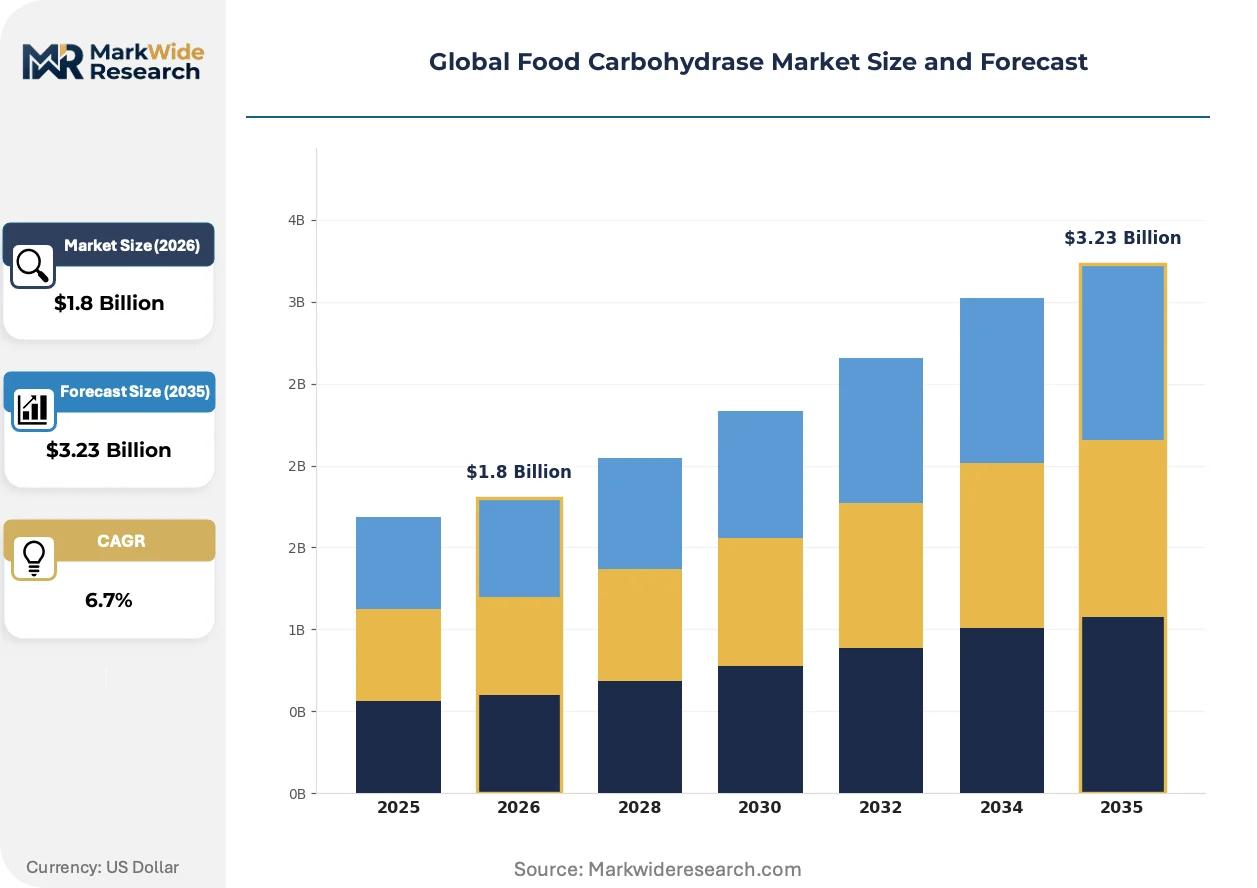
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Amylase, Glucoamylase, Invertase, Pullulanase Application: Beverages, Bakery, Dairy, Confectionery Form: Liquid, Powder, Granular, Concentrate End User: Food Processing, Beverage Industry, Confectionery Manufacturers, Industrial Bakers |
| Companies Covered | AB Enzymes, BASF SE, Novozymes A/S, Advanced Enzyme Technologies Ltd., Chr. Hansen Holding A/S, DuPont de Nemours, Inc., Amano Enzyme Inc., Archer Daniels Midland Company, DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Carbohydrase Market Emerging Trajectories
Enzyme engineering and regulatory disclosure requirements are restructuring competitive advantage around strain traceability and performance verification rather than commodity formulation supply.
Cell-free enzyme production is consolidating manufacturing flexibility for food-grade biocatalysts. This platform technology eliminates fermentation contamination risks while enabling rapid scale-up for seasonal demand spikes. Maltose syrup producers in Japan and beverage processors in Mexico are adopting cell-free systems to compress batch qualification timelines from months to weeks.
REACH disclosure requirements for genome-edited production strains are tightening supply chain documentation standards. The ECHA framework now mandates sequence-level traceability for enzymes derived from modified organisms, forcing reformulators to requalify legacy strain libraries. German and Dutch enzyme houses are responding by segregating edited and non-edited production lines to preserve market access flexibility.
Specification-driven buying is fragmenting procurement authority within multinational bakery chains. Central purchasing teams retain volume contracting for liquid alpha-amylase, while regional technical directors gain autonomy for specialty enzyme selection based on local flour protein profiles. This bifurcation is most pronounced in North American and Australian operations where wheat varietal diversity demands application-specific biocatalyst matching.
Global Food Carbohydrase Market Segmentation
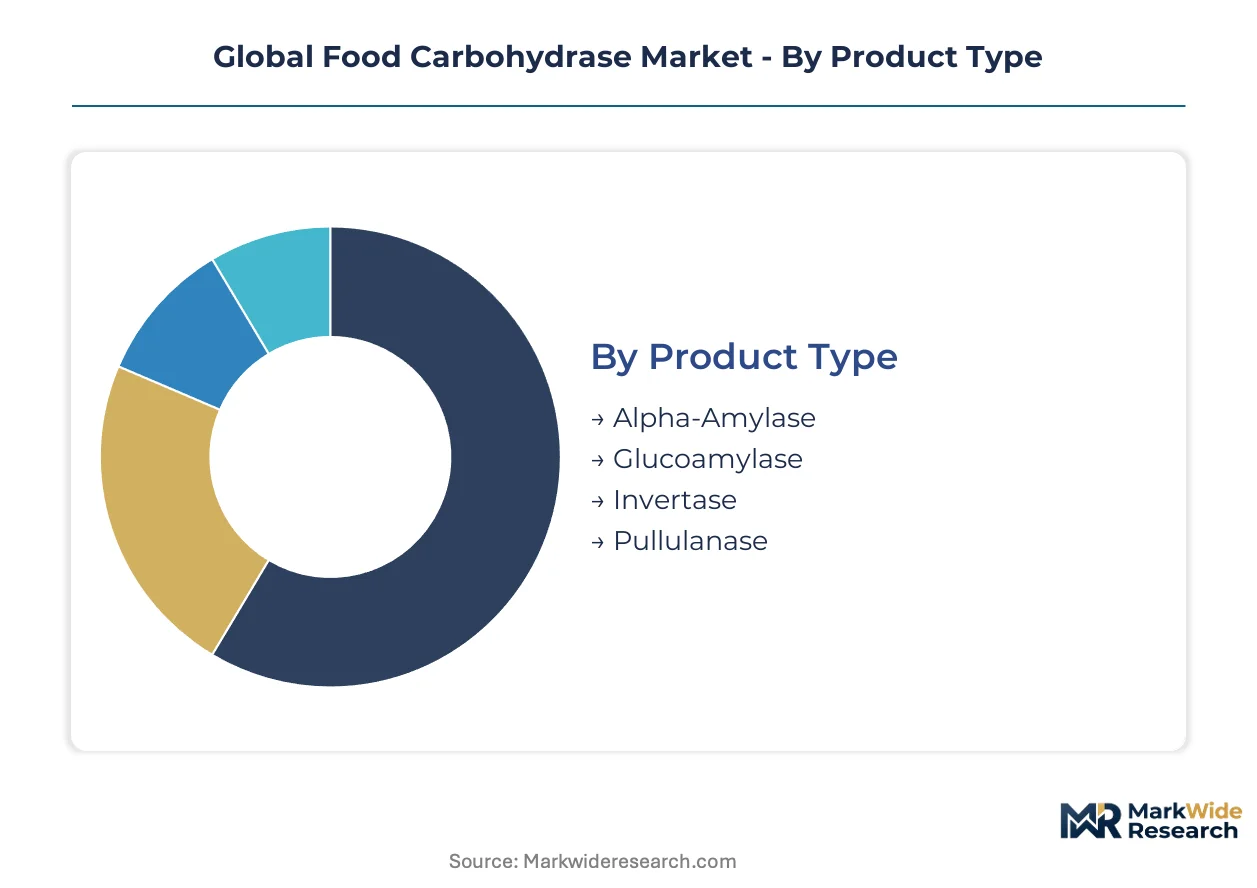
Enzyme segmentation in food carbohydrases determines regulatory pathway complexity and manufacturing qualification requirements. Each product type and application carries distinct EFSA safety evaluation and FDA GRAS notification burdens that shape commercial timelines.
Product Type:
Alpha-amylase and glucoamylase formulations require full EFSA feed additive assessments under Regulation 1831/2003, while pullulanase variants face extended ECHA REACH scrutiny for novel production strains.
- Alpha-Amylase:Random endoamylase that hydrolyzes internal alpha-1,4-glycosidic bonds in starch polymers, typically sourced from Bacillus licheniformis or Aspergillus oryzae. Industrial bakers in Germany's Rhineland cluster consume bulk volumes for dough conditioning and crumb softening, driven by continuous processing automation mandates. EFSA's 2023 updated guidance on allergenicity screening has extended approval timelines for new fungal-derived variants.
- Glucoamylase:Exoamylase releasing glucose monomers from non-reducing ends of starch chains, critical for high-dextrose syrup production. Beverage processors in Mexico and maltose syrup producers in Japan prioritize thermostable formulations for saccharification efficiency. FDA GRAS self-affirmation remains viable for traditional Aspergillus niger strains, though genome-edited variants trigger mandatory pre-market consultation.
- Invertase:Beta-fructofuranosidase catalyzing sucrose hydrolysis to glucose-fructose mixtures, essential for confectionery soft centers and fondant production. Confectionery manufacturers in Belgium and Switzerland source liquid formulations for precise dosage control in enrobing operations.
- Pullulanase:Debranching enzyme cleaving alpha-1,6 linkages in amylopectin, enabling 96%+ glucose yields in high-conversion starch processing. Technical premiums command attention from fermentation feedstock suppliers seeking maximum substrate utilization.
Alpha-amylase sits at the top of the volume ranking, with pullulanase climbing the fastest.
Application:
Application-driven demand fragments across processing temperature requirements and pH tolerance specifications, with bakery and beverage segments commanding divergent formulation portfolios.
- Beverages:Starch liquefaction and saccharification for brewing, distilling, and soft drink production. Alpha-amylase dominates mashing operations, while glucoamylase completes fermentable sugar release. German brewing clusters and Mexican agave processors drive regional specification diversity.
- Bakery:Dough conditioning, crumb softening, and shelf-life extension through anti-staling mechanisms. Industrial bakers consolidate procurement around dual-source suppliers capable of integrated enzyme-chemical solutions. EU Green Deal biocatalytic mandates accelerate substitution of chemical emulsifiers.
- Dairy:Lactose hydrolysis adjuncts and whey processing applications, though carbohydrase penetration lags protease and lipase adoption. Greek yogurt processors and Dutch whey refiners represent concentrated demand pockets for specialized formulations.
- Confectionery:Invertase for soft-center production, pullulanase for glucose syrup refinement, and amylase for gelling control. Belgian praline manufacturers and Turkish delight producers sustain powder format relevance for dry-mix operations.
Bakery commands the largest revenue pool, with beverages gaining share fastest on craft brewing expansion and alternative beverage fermentation.
Form:
Physical format selection hinges on dosing automation compatibility and supply chain stability requirements, with liquid formats demanding cold-chain integrity that powder alternatives circumvent.
- Liquid:Standard aqueous enzyme solutions with preservatives for microbial stability, designed for automated injection in continuous processing lines. SCADA-integrated dosing systems in German and Dutch industrial bakeries favor this format for batch-to-batch consistency. EFSA evaluations address preservative carryover into final food products.
- Powder:Spray-dried or lyophilized enzyme preparations with extended ambient storage stability. Artisan bakers and regional confectionery cooperatives in France and Italy prefer powder for distributed manufacturing without refrigeration infrastructure.
- Granular:Agglomerated formulations reducing dust exposure and improving flowability for manual handling operations. Small-batch food processors in India and Brazil adopt granular for FSSAI-aligned clean-label positioning.
- Concentrate:High-activity formulations requiring dilution prior to application, optimizing freight economics for long-distance supply. Southeast Asian starch processors leverage concentrates to minimize import volume and customs complexity.
Liquid holds the dominant position by value, with concentrate expanding most quickly on freight cost optimization in import-dependent markets.
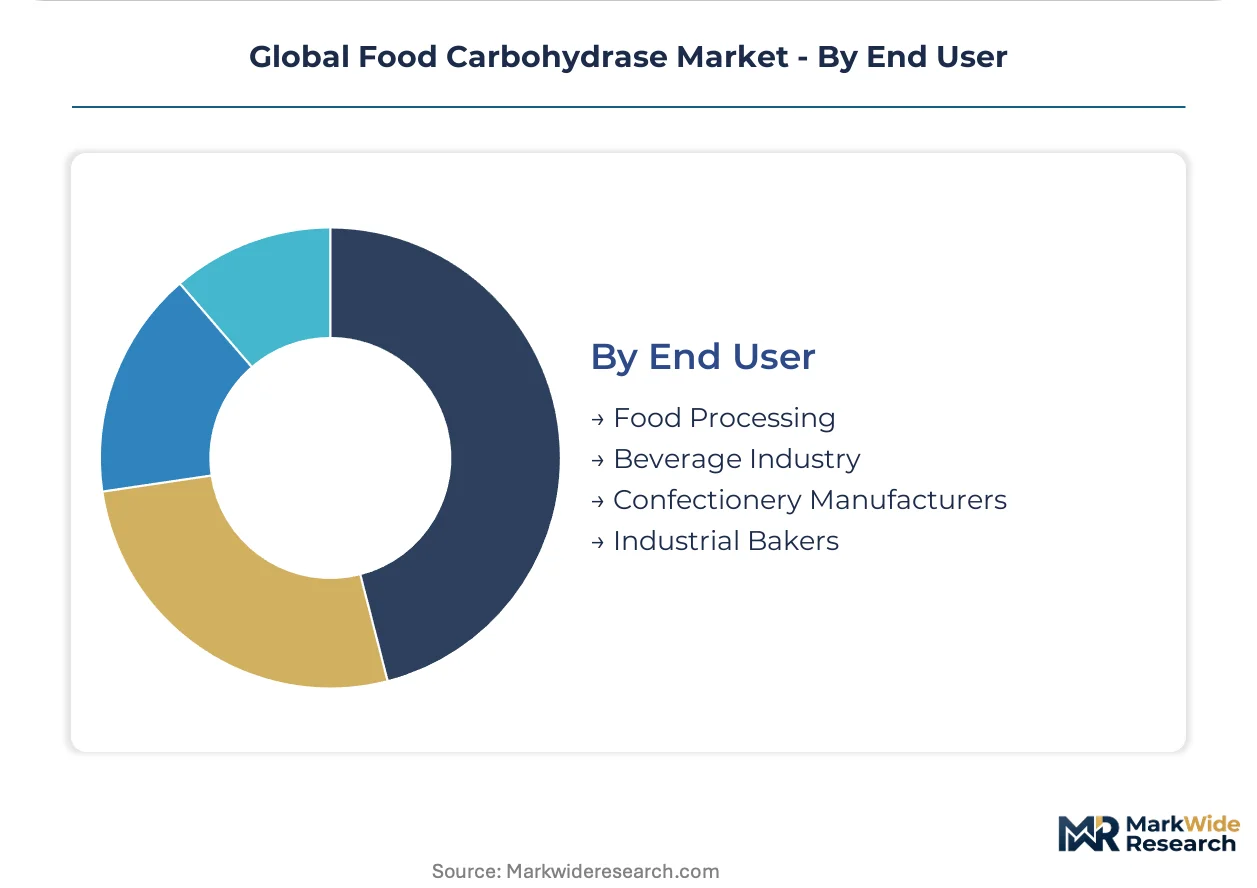
End User:
End-user scale determines procurement authority concentration, with multinational food processors enforcing centralized contracting while artisan segments fragment across digital distribution channels.
- Food Processing:Broad-category starch modification for ingredients, texturizers, and intermediate products. Cargill and ADM-scale operators demand genome-edited strain documentation for ECHA REACH compliance.
- Beverage Industry:Brewing, distilling, and non-alcoholic drink manufacturing with strict fermentation efficiency targets. Mexican tequila and Japanese sake producers maintain distinct pH and temperature specification requirements.
- Confectionery Manufacturers:Precision-dependent soft-center and fondant applications requiring invertase stability across shelf-life. Belgian and Swiss operations prioritize batch certification for luxury export positioning.
- Industrial Bakers:High-throughput bread and pastry operations consolidating around dual-source enzyme-chemical suppliers. Germany's large-scale baking cooperatives and Australian wheat-belt processors drive regional formulation customization.
Industrial bakers generate the highest volume demand, with confectionery manufacturers achieving the steepest margin capture on technical premium formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's enzyme production clusters generate denser demand concentration than India's fragmented procurement landscape, though both markets are expanding enzyme adoption at divergent rates driven by distinct regulatory pressures and industrial structures.
United States
Craft brewing proliferation and alternative beverage fermentation sustain glucoamylase consumption across Midwest malt houses and West Coast kombucha processors. FDA GRAS self-affirmation pathways accelerate formulation iterations for traditional Aspergillus-derived enzymes. Chicago-area industrial bakeries consolidate procurement around liquid alpha-amylase suppliers capable of SCADA-integrated dosing.
Germany
Rhineland baking cooperatives and Bavarian brewing operations overlap with enzyme manufacturing facilities near Frankfurt and Mannheim. EU Green Deal biocatalytic mandates compress chemical emulsifier substitution timelines for dough conditioning applications. North Rhine-Westphalia hosts the densest concentration of continuous processing automation retrofits in European bakery operations.
Japan
Maltose syrup refiners adopt cell-free enzyme production platforms to compress seasonal qualification timelines. METI guidelines on genome-edited strain disclosure shape documentation requirements for modified production organisms. Osaka-area starch processors prioritize thermostable glucoamylase formulations for saccharification efficiency.
Mexico
Tequila agave processors and soft drink bottlers drive divergent pH specification requirements for alpha-amylase liquefaction stages. The country's national food safety regulator enforces additive declaration standards that favor enzyme-based texture solutions. Jalisco distilling clusters source liquid formulations optimized for high-temperature mashing operations.
India
FSSAI clean-label acceleration creates procurement openings for enzyme-based shelf-life extension in packaged bread and confectionery. Maharashtra and Gujarat food processors trial granular enzyme formats to circumvent cold-chain infrastructure gaps. Mumbai-area industrial bakers fragment demand across regional formulators lacking national distribution scale.
Global Food Carbohydrase Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where chemical distribution networks clash with dedicated enzyme engineering capabilities. The vendor base concentrates around three strategic archetypes: integrated nutrition-biotech conglomerates, specialized enzyme houses, and agricultural commodity processors backward-integrating into biocatalyst supply. Competitive positioning hinges on strain development IP control and regulatory documentation depth rather than commodity volume leverage. M&A activity targets genome-edited strain libraries, while capacity expansion concentrates in cell-free production platforms.
Among European-anchored enzyme houses, Novozymes A/S and DSM-Firmenich AG occupy positions at opposite ends of the portfolio spectrum. Novozymes exemplifies the focused pure-play model with concentrated brewing and baking specialization. DSM-Firmenich represents the integrated conglomerate archetype, spanning human nutrition, animal feed, and food processing enzyme applications. BASF SE sits within the chemical distribution tier, leveraging formulation bundling and technical service reach to compete against dedicated biocatalyst suppliers.
| Leading Market Players |
|---|
| AB Enzymes |
| BASF SE |
| Novozymes A/S |
| Advanced Enzyme Technologies Ltd. |
| Chr. Hansen Holding A/S |
| DuPont de Nemours, Inc. |
| Amano Enzyme Inc. |
| Archer Daniels Midland Company |
| DSM-Firmenich AG |
| Others |
Supply Flow & Price Mechanics
Industrial baker procurement consolidation around dual-source enzyme suppliers is compressing vendor margins and forcing liquid alpha-amylase formulators to absorb fermentation substrate volatility rather than pass through cost swings. This buyer-driven restructuring concentrates pricing power with scale producers capable of integrated dough-conditioning and shelf-life extension bundling.
Pricing Analysis
Capacity additions in cell-free production platforms are reshaping price floors for food-grade carbohydrases by eliminating fermentation batch contamination risks and compressing seasonal qualification timelines. Three-tier pricing structure across premium genome-edited strain formulations, standard GRAS-affirmed variants, and economy bulk alpha-amylase separates technical documentation depth from commodity volume supply. Cost compression in economy-tier liquid formats is intensifying because corn and wheat bran price volatility squeezes margin buffers for non-integrated formulators. Artisan bakers and regional confectionery cooperatives exhibit highest price sensitivity, while multinational industrial bakers prioritize batch-to-batch consistency over per-unit cost.
Supply Chain Analysis
Direct-to-industrial-baker channels handle hyperscale procurement for Germany's Rhineland baking clusters and North American wheat-belt processors, while chemical distributors retain relevance for fragmented artisan segments. Manufacturing gravity centers on Denmark, Germany, and the Netherlands where enzyme production facilities overlap with brewing and baking demand density. Raw material feeds draw from corn wet-milling byproducts, wheat bran fermentation substrates, and preservative chemistries for liquid format stability. Single-source vulnerability concentrates in CRISPR-optimized production strain IP held by incumbent specialists. Distribution runs through technical service bundling for integrated solutions and digital procurement platforms for small-batch buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between India's FSSAI clean-label acceleration creating enzyme substitution openings and Germany's REACH registration timelines extending payback periods on novel biocatalyst R&D.
For Market Incumbents: Extend strain documentation depth to preempt ECHA genome-edited disclosure mandates by segregating edited and non-edited production lines now. Anchor capacity expansion in cell-free platforms to capture technical premiums from Japanese maltose syrup refiners and Mexican beverage processors seeking compressed batch qualification. Defensive positioning against patent-thicket constraints on thermostable variants requires captive protein engineering expertise acquisition. For New Entrants and Emerging Players: The premium-economy price-point gap in pullulanase-synergized high-glucose syrup production creates white-space entry at technical specification tiers below Novozymes-grade documentation depth. India's Maharashtra and Gujarat food processors represent the most penetrable geography given cold-chain infrastructure gaps favoring granular formats over liquid. A direct-to-artisan digital distribution angle bypasses established chemical distributor markups for regional baking cooperatives. For Investors and Strategic Acquirers: Asymmetric upside sits with cell-free production platform specialists holding manufacturing flexibility for seasonal demand spikes without fermentation contamination risk. Long-term viability across the analysis window favors acquisition targets with segregated genome-edited strain libraries preserving EU market access flexibility. Watch EFSA allergenicity screening guidance evolution as the inflection signal for extended approval timeline risk on fungal-derived variants.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Free Production Platform Scale-Up | Eliminates fermentation contamination risks for Japanese maltose syrup refiners seeking compressed qualification timelines. |
| Genome-Edited Strain Library Segregation | Preserves ECHA REACH market access flexibility by separating edited and non-edited production lines. |
| Direct-to-Artisan Digital Distribution | Bypasses chemical distributor markups for India's regional baking cooperatives lacking cold-chain infrastructure. |
| Integrated Dough-Chemical Bundling | Consolidates procurement authority among Germany's industrial baking cooperatives seeking dual-source suppliers. |
| Pullulanase-Synergized Formulation Development | Captures technical premiums from fermentation feedstock suppliers demanding 96%+ glucose yields. |
Methodological Framework
Bottom-up bakery and beverage end-use modeling reconciled against top-down enzyme production facility tracking forms the analytical core of this study. Primary interviews with industrial baking procurement directors, brewing technical officers, enzyme formulator R&D leads, and FSSAI regulatory affairs specialists combined with secondary validation against EFSA safety evaluations, FDA GRAS notifications, ECHA REACH registrations, and customs trade data for fermentation substrate flows. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity across product type, application, and format dimensions.
Input-output matrix framing connects alpha-amylase volume demand from Germany's Rhineland cluster to glucoamylase consumption patterns in Mexican agave processing and Japanese sake refining. Segmentation modeling spans enzyme variant thermostability, pH tolerance specifications, liquid versus powder format automation compatibility, and regional regulatory pathway complexity. CAGRs derive from production capacity utilization rates cross-referenced against EU Green Deal substitution mandates and FSSAI clean-label acceleration timelines. Forecast inputs include genome-edited strain approval velocity and continuous processing automation retrofit penetration.
Caveats apply where ECHA evaluation period extensions or EFSA allergenicity screening protocol changes could materially shift the outlook for novel biocatalyst market entry. Fermentation substrate cost volatility and CRISPR strain development IP concentration represent additional revision triggers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Modified Starch Market