
 China Packaged Food Products Market | 2026-2036
China Packaged Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
China Packaged Food Products Market Insights
Asset-light franchising and third-party logistics leasing is fragmenting competitive dynamics in China's packaged food sector. Tingyi Cayman Islands Holding Corp leverages its extensive noodle and beverage distribution network to sustain shelf dominance across lower-tier cities. COFCO Corporation anchors national grain and oil supply security through state-backed procurement channels. Inner Mongolia Yili Industrial Group Co. dominates dairy packaging innovation with cold-chain investments.
Packaged food products encompass shelf-stable and refrigerated consumables sealed in protective materials to extend viability, prevent contamination, and enable standardized retail distribution; primary specifications include moisture barriers, oxygen scavenging layers, and tamper-evident closures designed for mass-market scalability. Frozen meals lead volume throughput as urban households trade cooking time for convenience, while dairy products command premium positioning through aseptic carton technology and probiotic stability claims. Online retail channels are accelerating fastest among distribution segments, though supermarkets still capture the bulk of margin pools through private-label expansion and front-of-store placement fees.
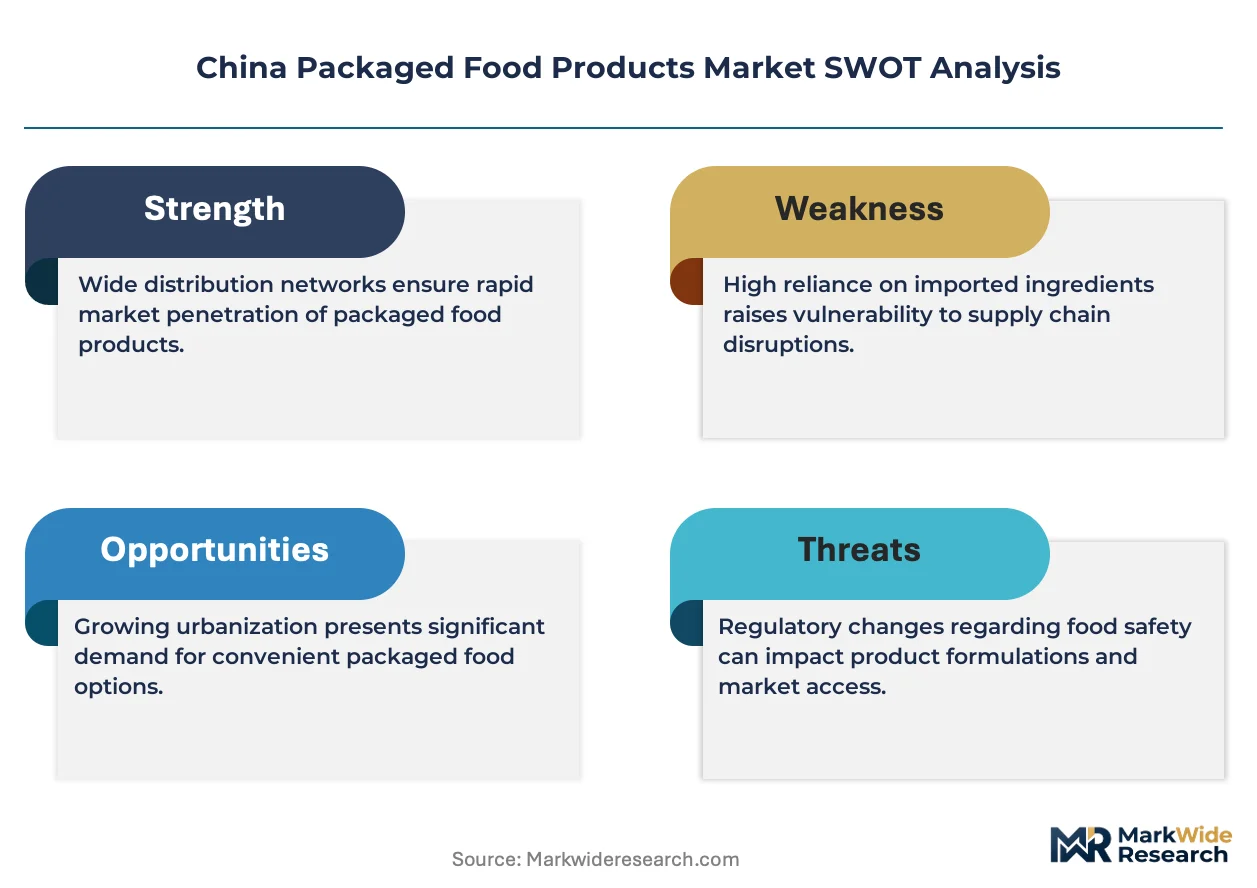
SAMR enforces GB standards for food contact materials and additive limits, compelling reformulation investments and packaging substrate shifts across domestic manufacturers. NMPA alignment with nutritional labeling rules tightens health claim substantiation, filtering smaller brands from premium positioning. Stakeholders must monitor regulatory tightening on plastic packaging reduction mandates and anticipate which compliance investments will become baseline market access requirements.
Market Dynamics
Urban household consolidation and SAMR's tightening GB standards on food contact materials are compressing product development cycles while forcing substrate upgrades across domestic manufacturing bases.
Growth Catalysts
- Dual carbon policy mandates:Beijing's 2030 carbon peak targets accelerate cold-chain electrification investments, expanding refrigerated packaged food penetration into Yangtze River Delta secondary cities.
- Urban professional time scarcity:Tier-one city households averaging sixty-plus hour workweeks trade cooking labor for ready-to-eat meal solutions, concentrating volume in convenience-oriented SKUs.
- Third-party logistics leasing:Asset-light distribution partnerships enable regional brands to achieve national refrigerated reach without captive fleet ownership.
Market Restraints
- Polypropylene substrate cost volatility:Crude-linked resin prices swing formulation economics for barrier-layer flexible packaging, squeezing mid-tier manufacturer margins.
- Single-supplier cold-chain dependence:Refrigerated last-mile capacity concentrates among three national logistics platforms, creating bottleneck vulnerability for dairy and frozen categories.
- GB 4806 additive compliance timelines:SAMR's phased migration limit reductions force twelve-to-eighteen month reformulation windows that freeze SKU innovation pipelines.
Strategic Opportunities
- Greater Bay Area integration:Hong Kong-Shenzhen-Guangzhou regulatory harmonization creates unified shelf-space access for cross-border packaged food certification.
- Aseptic carton probiotic extension:UHT-sterilized dairy with live culture stability claims opens premium positioning in inland provinces lacking cold-chain density.
- Community group buying channels:WeChat-enabled collective procurement aggregates rural demand into batch production runs, lowering unit economics for regional brands.
Industry Challenges
- Food safety auditor scarcity:Qualified GB 14881 implementation specialists command premium wages, delaying facility certification for second-tier manufacturers.
- Legacy MES integration friction:Paper-based production records dominate county-level plants, complicating SAMR-mandated traceability system upgrades.
- Cross-provincial label compliance:Municipal interpretation variance of nutritional claim thresholds forces redundant packaging runs for multi-region distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Packaged Food Products Market |
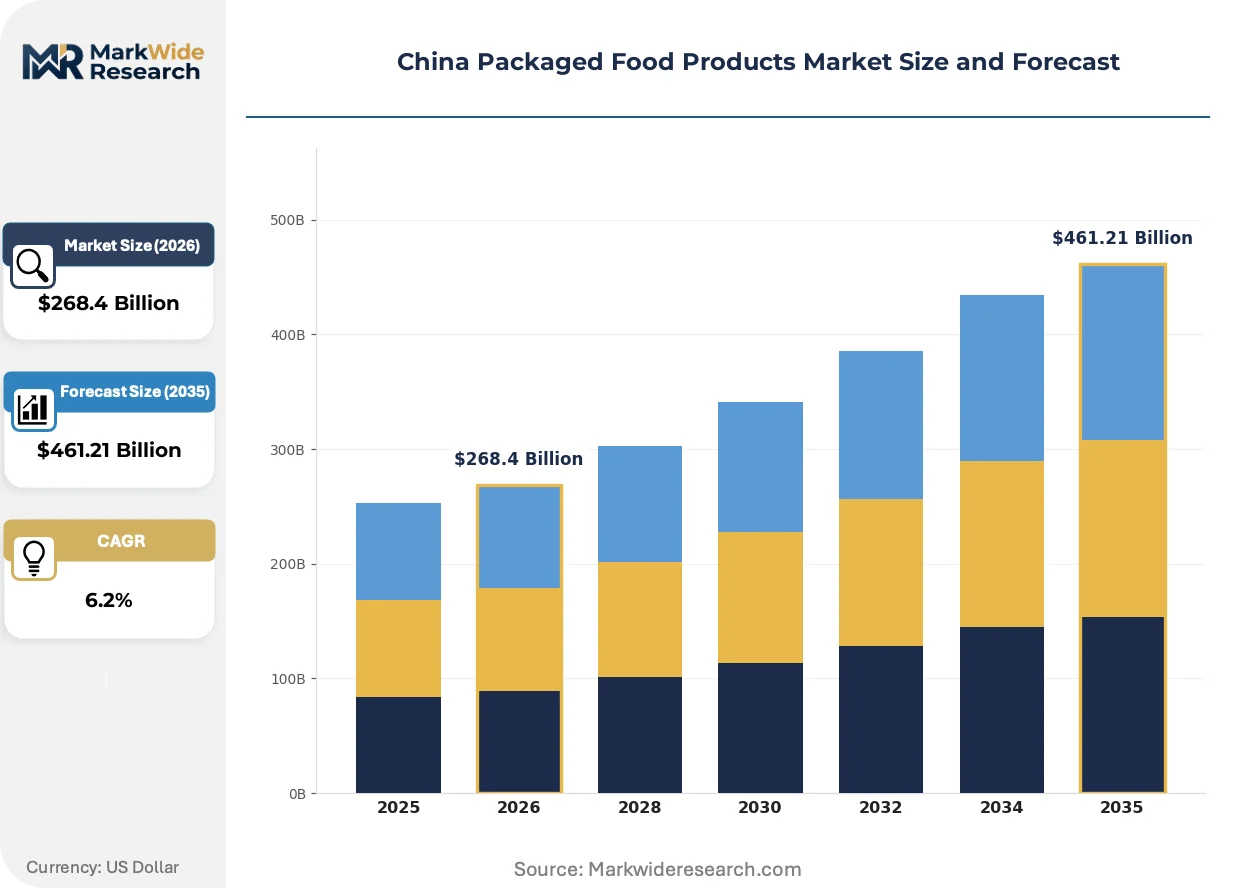
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $461.21 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Frozen Meals, Canned Goods, Dairy Products Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Consumer Demographics: Millennials, Working Professionals, Families, Seniors Packaging Type: Flexible Packs, Rigid Containers, Jars, Pouches |
| Companies Covered | Tingyi Cayman Islands Holding Corp, Happiness Development Group Limited, Foshan Haitian Flavouring and Food Company Ltd, SDIC Zhonglu Fruit Juice Co.,Ltd., YouYou Foods Co. Ltd, Inner Mongolia Yili Industrial Group Co., Guangdong Haid Group, COFCO Corporation, Yihai Kerry Arawana Holdings Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Packaged Food Products Market Trends and Innovations
Intelligent packaging and blockchain traceability systems are compressing quality verification timelines while SAMR tightens additive and substrate rules. Three forces dominate near-term competitive differentiation.
Smart labels embedding time-temperature indicators and NFC authentication chips are digitizing supply chain transparency for high-value dairy and meat categories. Premium supermarket chains in Shanghai and Beijing pilot shelf-edge consumer scanning to validate cold-chain integrity. This capability is digitizing trust premiums previously captured by multinational brands with established quality reputations.
SAMR's 2024 GB 23350 restriction on excessive packaging layers compels structural redesign of gift-oriented food sets, particularly mooncake and regional specialty categories. Manufacturers face forced migration from rigid boxes to flexible film solutions with equivalent premium perception. Tier-one city distributors now reject non-compliant SKUs, filtering traditional designs from front-of-store placement.
Direct-to-community subscription models displace traditional wholesale relationships for breakfast cereal and snack categories. Young professional households in Chengdu and Hangzhou prioritize curated monthly boxes over supermarket aisle browsing. This channel rotation compresses brand switching costs and elevates data-driven flavor innovation cycles over slotting-fee-dependent shelf dominance.
China Packaged Food Products Market Segmentation
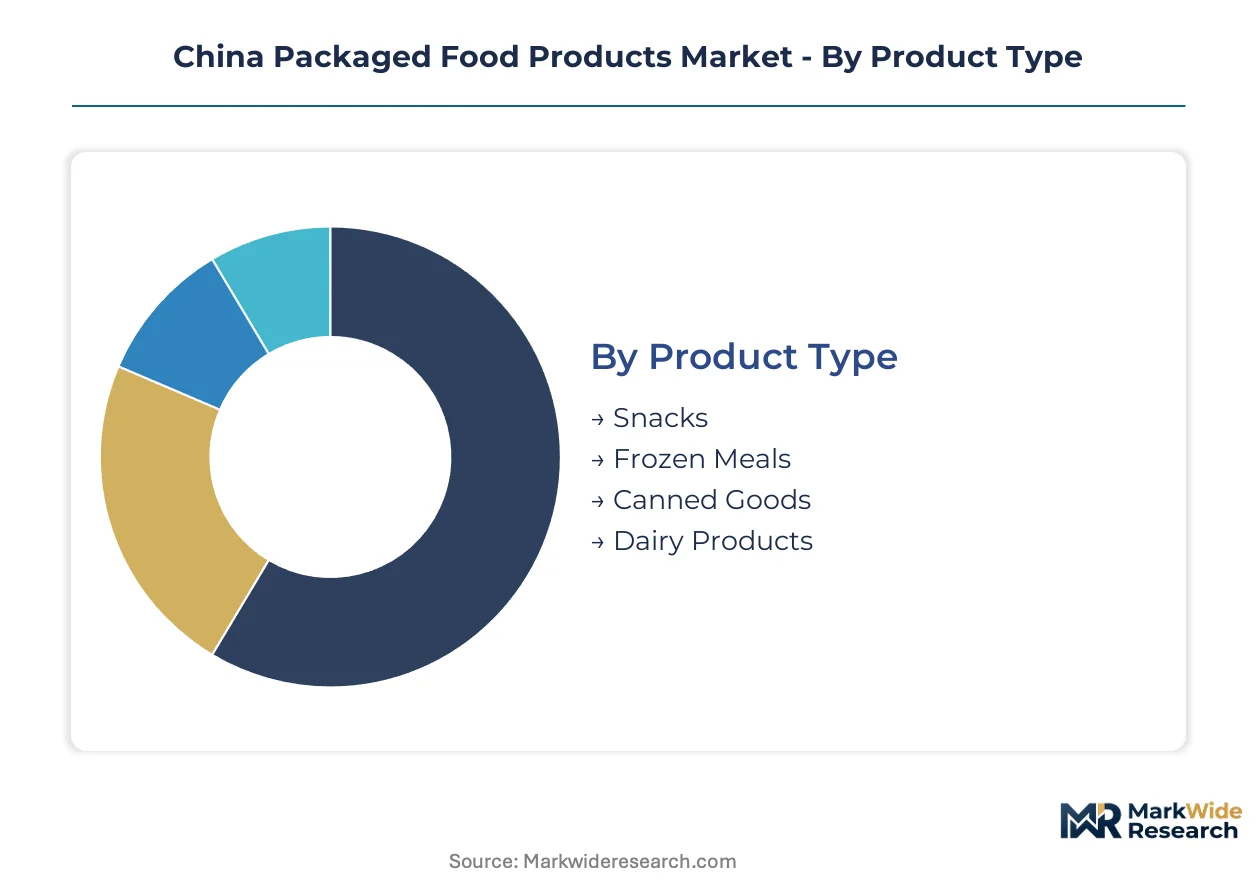
Segmentation in China's packaged food sector reveals how regulatory pressure and channel fragmentation reshape competitive priorities. SAMR's GB standards apply unevenly across product formats, while cold-chain density determines which packaging substrates penetrate inland provinces versus coastal clusters.
Product Type:
Cost tier stratification separates commodity staples from premium-positioned categories with formulation complexity and shelf-life engineering requirements.
- Frozen Meals:Blast-frozen proteins and starch-based substrates packaged in multi-layer barrier films withstand reheating cycles. Demand concentrates in Shanghai and Beijing where sixty-plus hour workweeks eliminate home cooking time; SAMR's GB 19295 microbiological limits force HACCP-certified production lines.
- Dairy Products:UHT-sterilized milk and probiotic yogurts deploy aseptic carton technology with aluminum oxygen barriers. Penetration tracks cold-chain electrification investments under Beijing's dual carbon policy; Inner Mongolia production bases supply Yangtze River Delta tier-one cities.
- Snacks:Nitrogen-flushed flexible packs preserve crispness in baked and puffed categories. Regional brands dominate through community group buying channels.
- Canned Goods:Retort-sterilized metal containers target emergency stockpiling and rural distribution. COFCO's state-backed procurement secures raw material cost advantages.
Frozen meals hold installed capacity. Dairy products are rotating up the share rankings.
Distribution Channel:
Application context determines packaging specifications and margin capture, with each channel imposing distinct cold-chain, labeling, and slotting-fee requirements.
- Online Retail:Direct-to-consumer fulfillment demands crush-resistant secondary packaging and time-temperature indicator integration. Chengdu and Hangzhou young professionals drive subscription box curation; third-party logistics leasing enables national refrigerated reach without captive fleet ownership.
- Supermarkets:Front-of-store placement fees and private-label expansion dominate margin pools. Tier-one city chains pilot NFC-enabled shelf-edge scanning for cold-chain validation.
- Convenience Stores:Limited shelf space favors single-serve SKUs with extended ambient stability. 24-hour urban coverage targets late-night professional consumption.
- Wholesale:Bulk format pricing serves institutional catering and county-level redistribution. Legacy paper-based inventory systems complicate SAMR traceability mandates.
Supermarkets hold installed capacity. Online retail is climbing the fastest.
Consumer Demographics:
Customer type dictates packaging communication strategies, with nutritional claim substantiation and portion sizing calibrated to life-stage priorities and regulatory literacy.
- Working Professionals:Time-scarce tier-one city households prioritize ready-to-eat solutions with minimal preparation steps. GB 28050 nutritional labeling compliance filters smaller brands from premium positioning.
- Millennials:Health-conscious cohorts scrutinize additive declarations and sustainability credentials. Direct-to-community subscription models displace traditional wholesale relationships.
- Families:Bulk purchasing and child-friendly portion controls drive value-format demand. Cross-provincial label compliance variance forces redundant packaging runs.
- Seniors:Digestive health claims and reduced-sodium formulations require NMPA-aligned substantiation. E-commerce penetration lags due to digital literacy gaps.
Working professionals hold installed capacity. Millennials are gaining share fastest.
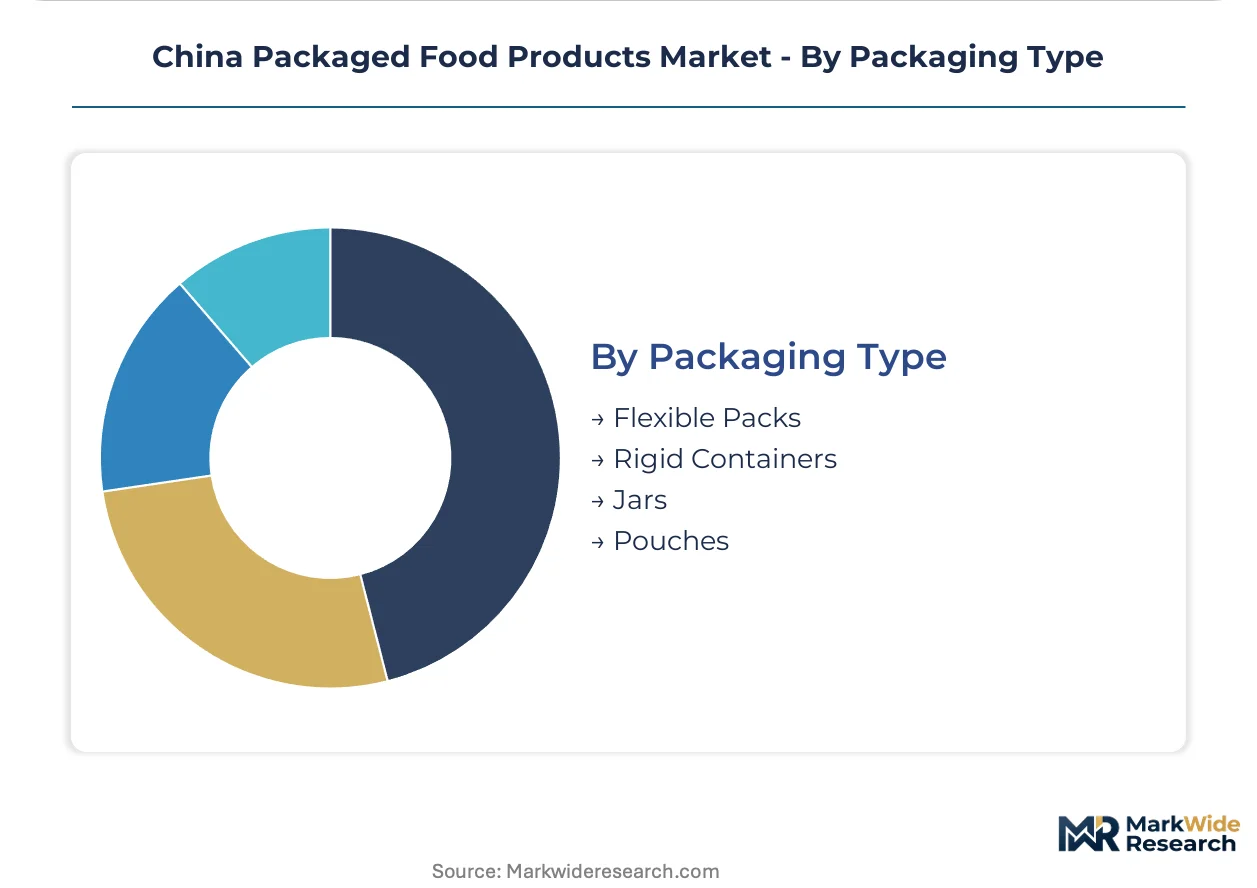
Packaging Type:
Volume throughput and substrate cost volatility differentiate structural approaches, with GB 4806 additive compliance timelines forcing twelve-to-eighteen month reformulation windows.
- Flexible Packs:Multi-layer polymer films with oxygen scavenging layers dominate snack and frozen vegetable categories. Polypropylene resin price swings squeeze mid-tier manufacturer margins.
- Pouches:Stand-up formats with resealable zippers penetrate liquid and semi-liquid dairy alternatives. SAMR's 2024 GB 23350 excessive packaging restrictions favor film over rigid solutions.
- Rigid Containers:Polypropylene and PET thermoformed trays serve ready-meal segments requiring microwave stability. Municipal recycling infrastructure gaps limit post-consumer recovery.
- Jars:Glass and high-barrier plastic containers preserve fermented and high-acid foods. Weight and fragility constrain e-commerce suitability.
Flexible packs hold installed capacity. Pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's packaged food trade balance tilts toward import dependency for premium dairy and specialty ingredients, while processed grain and beverage exports dominate outbound flows. Provincial consumption clusters diverge sharply by cold-chain maturity and urban income density.
Yangtze River Delta
Shanghai and Hangzhou households drive ready-to-eat meal demand through sixty-plus hour workweeks. SAMR's GB 19295 microbiological standards enforce HACCP certification for frozen food processors in Jiangsu and Zhejiang. Suzhou industrial parks host aseptic carton manufacturing for dairy distribution into Anhui and Jiangxi secondary cities.
Pearl River Delta
Shenzhen and Guangzhou professionals prioritize convenience-store single-serve SKUs for late-night consumption. Greater Bay Area regulatory harmonization accelerates cross-border shelf-space access for Hong Kong-certified packaged foods. Dongguan logistics hubs consolidate third-party cold-chain leasing for regional brand national expansion.
Beijing-Tianjin-Hebei
State-backed procurement channels through COFCO dominate grain and oil packaging volume in the capital corridor. Beijing's dual carbon policy mandates electrify cold-chain fleets serving Hebei dairy processors. Tianjin port facilities handle bulk ingredient imports for infant formula and probiotic yogurt substrates.
Sichuan-Chongqing
Chongqing's spicy flavor preference drives regional snack and instant noodle formulation differentiation. Community group buying channels aggregate rural demand across Sichuan basin counties for batch production economics. Chengdu subscription box curation displaces traditional wholesale for breakfast cereal categories.
Shandong Peninsula
Qingdao and Yantai seafood processing clusters export retort-sterilized canned goods through state-controlled procurement networks. Shandong's agricultural base supplies vegetable substrates for frozen meal processors in Jinan. GB 4806 additive compliance timelines force twelve-month reformulation windows for legacy condiment manufacturers.
China Packaged Food Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in packaging substrates and cold-chain equipment. The sector exhibits tiered consolidation with state-backed conglomerates anchoring grain security and private groups dominating beverage and dairy innovation. Three archetypes prevail: state-linked procurement platforms, private-label manufacturing specialists, and regional distribution aggregators. Competitive moves center on third-party logistics leasing partnerships and aseptic packaging technology licensing.
Among diversified holding structures, Tingyi Cayman Islands Holding Corp and Inner Mongolia Yili Industrial Group Co. occupy positions spanning beverage, dairy, and convenience food categories. COFCO Corporation exemplifies the state-backed archetype through national grain and oil supply security mandates. These three entities represent contrasting governance models—offshore-listed private capital, provincial industrial groups, and central state enterprise—each embedding distinct procurement and distribution logics.
| Leading Market Players |
|---|
| Tingyi Cayman Islands Holding Corp |
| Happiness Development Group Limited |
| Foshan Haitian Flavouring and Food Company Ltd |
| SDIC Zhonglu Fruit Juice Co.,Ltd. |
| YouYou Foods Co. Ltd |
| Inner Mongolia Yili Industrial Group Co. |
| Guangdong Haid Group |
| COFCO Corporation |
| Yihai Kerry Arawana Holdings Co. |
| Others |
Pricing and Supply Chain Analysis
Shandong Peninsula seafood processing clusters anchor national supply capacity for retort-sterilized canned goods, with Qingdao and Yantai facilities translating raw material proximity into downstream pricing power for COFCO's state-backed procurement networks. This concentration allows legacy manufacturers to resist margin compression even as polypropylene resin volatility squeezes flexible packaging economics elsewhere.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Certification tier under GB 19295 HACCP standards and volume scale differentiate frozen meal contracts, while brand premium captures shelf positioning fees in tier-one supermarkets. Pricing pressure stems from crude-linked resin swings in barrier-layer substrates, squeezing mid-tier manufacturers without captive polymer sourcing. County-level redistribution buyers exhibit highest price sensitivity; premium supermarket chains with private-label programs show least elasticity due to front-of-store placement revenue.
Supply Chain Analysis
Export-control regimes on advanced cold-chain equipment limit domestic fleet electrification timelines, constraining refrigerated last-mile expansion. Supply concentrates in China's Yangtze River Delta production bases, South Korean aseptic carton technology providers, and Inner Mongolian dairy raw material zones. Aluminum oxygen barriers, probiotic culture substrates, and blast-freezing equipment draw from concentrated international sources. Single-supplier cold-chain dependence among three national logistics platforms creates bottleneck vulnerability. Distribution runs through third-party logistics leasing partnerships enabling asset-light national reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh food delivery platforms and ghost kitchen operators threaten packaged meal incumbents by collapsing preparation time advantages; substitution defense requires locking in convenience-channel shelf dominance before habit formation shifts.
For Market Incumbents: Build cold-chain density moats through captive fleet electrification investments under Beijing's dual carbon mandates. Consolidate procurement position by securing long-term polypropylene supply agreements before resin volatility intensifies. Defend against regional snack brands by front-loading slotting fees in tier-one convenience stores where sixty-plus hour workweeks drive impulse purchases. For New Entrants and Emerging Players: Pursue community group buying channels in Sichuan-Chongqing basin counties where aggregated rural demand lowers batch production economics. Target probiotic yogurt segments in Anhui and Jiangxi secondary cities lacking cold-chain density for premium dairy penetration. Launch direct-to-community subscription models for breakfast cereal categories displacing traditional wholesale relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aseptic packaging technology licensors with multi-year dairy processor contracts. Five-to-ten year viability favors specialists with SAMR GB 4806 compliance capabilities already embedded. Monitor GB additive limit reduction timelines as inflection signal for reformulation investment cycles freezing competitor SKU pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Fleet Electrification | Beijing's dual carbon mandates expand refrigerated reach into Yangtze River Delta secondary cities. |
| Aseptic Carton Technology Licensing | UHT-sterilized probiotic stability claims open premium positioning in inland provinces. |
| Community Group Buying Channel Expansion | WeChat-enabled collective procurement aggregates rural Sichuan demand for batch production economics. |
| GB 4806 Compliance System Investment | SAMR-mandated traceability upgrades filter paper-based county-level plants from premium distribution. |
| Flexible Film Substrate Migration | GB 23350 excessive packaging restrictions force mooncake and gift set redesign toward film solutions. |
Research Methodology
Operator-level perspectives from plant managers at frozen meal processors, procurement leads at dairy packaging facilities, SAMR compliance officers, and third-party logistics fleet operators anchored the qualitative base. Secondary validation drew from customs records of polymer resin imports, GB standard publication archives, supermarket chain slotting-fee disclosures, and cold-chain electrification subsidy registries. Bottom-up production capacity estimates triangulated against top-down consumption surveys across tier-one and tier-two city households.
Scenario-bracketing framed volume and value outputs across the analysis window. Segmentation dimensions modeled include product format, distribution channel, consumer demographic cohort, and packaging substrate type. CAGRs derived from production capacity buildout timelines, regulatory compliance investment cycles, and channel penetration curves specific to online retail acceleration and convenience-store single-serve SKU expansion.
The forecast holds incumbent behavior within observed patterns; aggressive cold-chain fleet acquisitions by regional dairy processors would shift outcomes. Material shifts in SAMR additive limit reduction timelines or polypropylene resin price volatility spikes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Instant Ramen Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Eco Bowls Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Canned Food Market
Packaged Foods
Convenience Food Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Packaged Rice Market
Packaged Foods
Instant Noodles Market