
 Australia Food Hydrocolloids Market | 2026-2036
Australia Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Hydrocolloids Market Outlook
FSANZ Standard 1.3.1 is collapsing the supplier base for food additive imports into Australia, forcing reformulation cycles on smaller brands. Cargill Incorporated leverages its global sourcing network to maintain consistent pectin supply lines into Australian dairy processors. Hawkins Watts Limited anchors its position through deep distribution ties with domestic bakery and confectionery manufacturers. Kerry Group plc differentiates via tailored hydrocolloid blends for clean-label sauce applications.
Food hydrocolloids are high-molecular-weight hydrophilic polymers that hydrate in aqueous systems to form viscous dispersions or gels, with gelatin derived from partial collagen hydrolysis and xanthan gum produced through Xanthomonas campestris fermentation. These substances function primarily as stabilizers, thickeners, and texturizers across processed food matrices. Pectin dominates the premium segment owing to its plant-based positioning and strong alignment with vegan-label dairy alternatives in Australia. Xanthan gum captures growth in gluten-free bakery goods where its shear-thinning rheology proves irreplaceable. Powder form sustains the largest volume share due to superior shelf stability and ease of dry-blending in industrial-scale food production.
FSANZ, the Department of Agriculture, and the ACCC collectively govern additive safety, import biosecurity, and anti-competitive conduct across Australia's hydrocolloid trade. TGA cross-referencing on novel hydrocolloid health claims adds a secondary compliance layer for functional food positioning. Stakeholders must monitor pending FSANZ code revisions on microbial specification limits, as these will determine which offshore suppliers retain market access without costly re-certification.
Market Dynamics
FSANZ Standard 1.3.1 amendments on additive transparency are compressing import pathways and forcing domestic reformulation cycles across bakery and dairy processors in Sydney and Melbourne.
Growth Catalysts
- Clean-label bakery demand:Gelatin and pectin uptake accelerates in Sydney and Melbourne as consumers reject synthetic stabilizers in artisan bread and pastry applications.
- FSANZ code alignment:Tighter compliance thresholds for importers create first-mover advantages for domestic processors holding pre-certified supply lines.
- Queensland processing concentration:Bulk hydrocolloid manufacturing clusters in Queensland and Victoria reduce freight costs for eastern seaboard food manufacturers.
Market Restraints
- Collagen input volatility:Gelatin production faces cost pressure from bovine and porcine hide supply fluctuations tied to Australian meat processing cycles.
- Offshore pectin dependency:Citrus peel sourcing concentrates in Brazil and Mexico, exposing Australian dairy alternatives to currency and shipping risk.
- Fermentation capacity limits:Xanthan gum production requires specialized bioreactor infrastructure that remains underdeveloped domestically.
Strategic Opportunities
- Tasmanian seaweed cultivation:Carrageenan and alginate extraction from cold-water macroalgae offers plant-based positioning with shorter supply chains.
- Functional beverage positioning:TGA cross-referencing on novel hydrocolloid health claims opens premium pricing in sports nutrition and gut health segments.
- Direct-to-manufacturer platforms:Digital procurement channels bypass traditional ingredient distributors for mid-sized Queensland and Victorian processors.
Industry Challenges
- Microbial specification compliance:Pending FSANZ revisions on aerobic plate counts and yeast/mold limits demand costly re-certification for offshore suppliers.
- Clean-label formulation expertise:Shortage of food technologists skilled in hydrocolloid synergy mapping slows product development cycles for smaller brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Hydrocolloids Market |
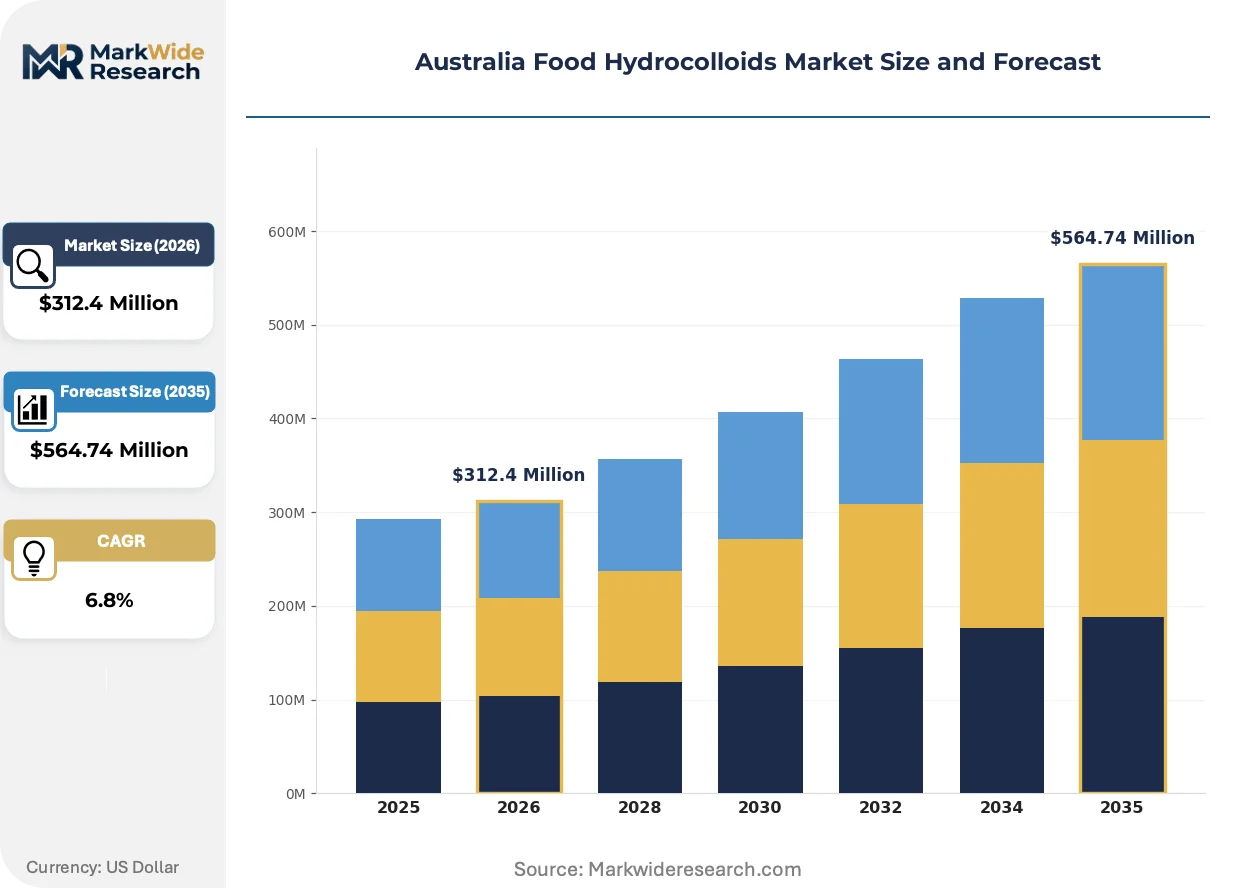
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Agar, Pectin, Xanthan Gum Application: Dairy Products, Bakery Goods, Confectionery, Sauces Form: Powder, Liquid, Granules, Sheets Source: Plant-Based, Animal-Based, Synthetic, Others |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, CP Kelco, Koninklijke DSM N.V., Hawkins Watts Limited, DuPont de Nemours, Inc., Kerry Group plc, Tate & Lyle PLC, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Hydrocolloids Market Strategic Shifts
Ingredient functionality is fragmenting across source types as processors balance clean-label mandates with textural performance requirements in gluten-free and vegan applications.
Precision fermentation for collagen-derived gelatin is decomposing traditional animal-sourced supply chains. Australian cultured-meat startups and pharmaceutical-grade gelatin buyers are piloting microbial collagen platforms at laboratory scale. This biotechnology is decomposing the historical link between meat processing volumes and hydrocolloid availability.
FSANZ microbial specification amendments are tightening import biosecurity protocols for hydrocolloid raw materials. The Department of Agriculture now requires enhanced documentation on fermentation substrate origins for xanthan gum shipments. Dairy alternative manufacturers in Victoria are accelerating domestic pectin trials to preempt certification delays.
Buyer consolidation among Australian contract manufacturers is compressing ingredient sourcing cycles. Mid-sized bakery and sauce processors now demand just-in-time hydrocolloid deliveries with embedded technical support. This procurement evolution is most visible in Melbourne's industrial food precincts where co-manufacturers serve multiple emerging brands simultaneously.
Australia Food Hydrocolloids Market Segmentation
Channel allocation across Australia's food hydrocolloid trade varies sharply by segment. Dairy processors in Victoria and Queensland source through established ingredient distributors, while Sydney's artisan bakeries increasingly procure direct from domestic blenders.
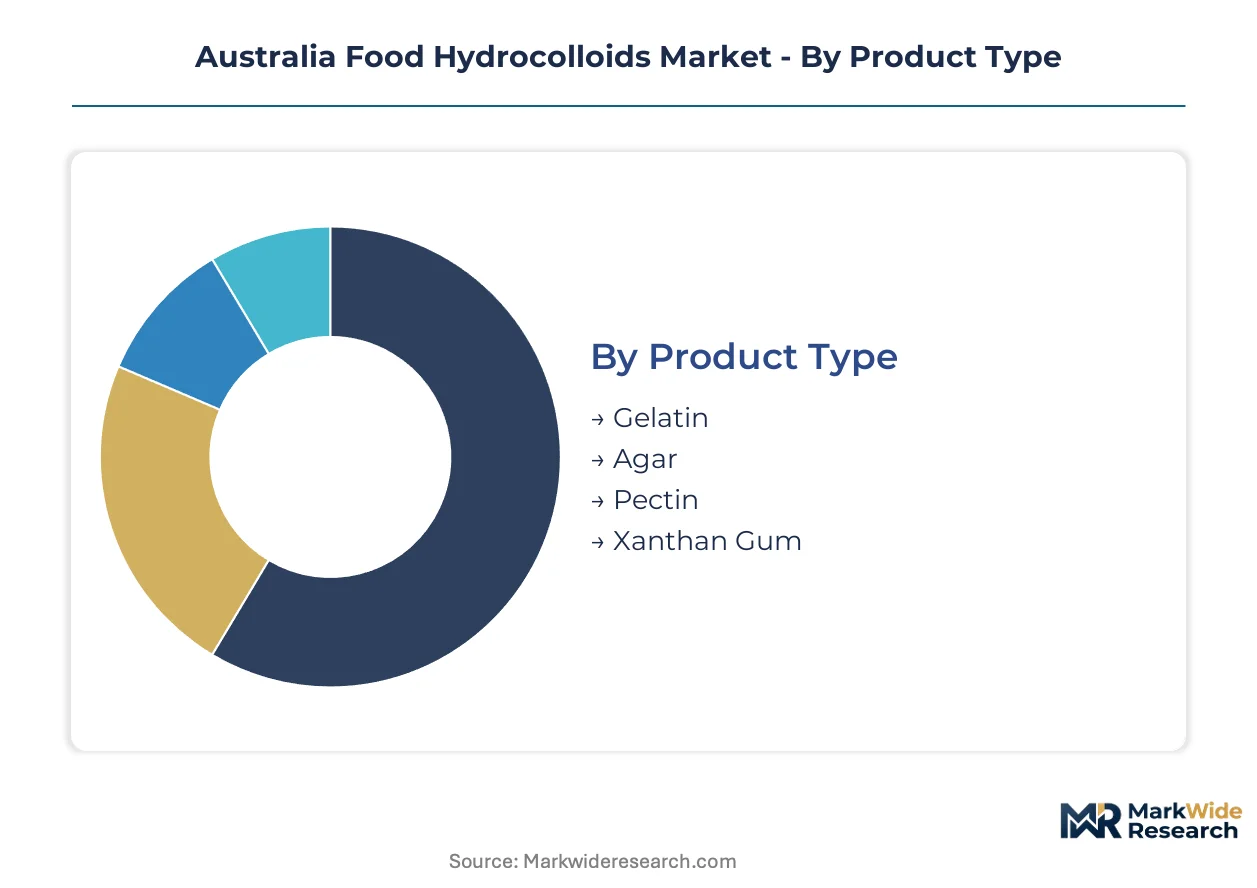
Product Type:
Distribution channels diverge sharply: gelatin and pectin flow through food-service wholesalers to industrial kitchens, while xanthan gum and agar serve specialized pharmaceutical and laboratory supply chains.
- Pectin:High-methoxyl and low-methoxyl grades extracted from citrus peel provide thermoreversible gelling essential for clean-label jam formulations. Victorian dairy alternative manufacturers in Melbourne's northern suburbs are accelerating pectin trials to preempt FSANZ certification delays for imported supplies.
- Gelatin:Type A (acid-processed) and Type B (alkali-processed) variants derived from bovine hides and porcine skins deliver melt-in-mouth textures for confectionery. Sydney and Melbourne clean-label bakeries reject synthetic stabilizers, driving uptake of premium-grade gelatin in artisan pastry applications.
- Xanthan Gum:Extracellular polysaccharide from Xanthomonas campestris fermentation delivers shear-thinning rheology critical for gluten-free dough stability.
- Agar:Red seaweed extract from Gracilaria and Gelidium species forms brittle gels at low concentrations for Asian dessert applications.
Pectin dominates installed base through dairy alternative penetration. Xanthan gum is where expansion concentrates in gluten-free bakery.
Application:
Cost tiering separates commodity-grade hydrocolloids for mass-market sauces from premium-certified grades commanding threefold pricing in functional beverages.
- Dairy Products:Yogurt stabilization and cream cheese texturization demand hydrocolloids with precise protein-hydration kinetics. Queensland's concentrated processing capacity supplies bulk pectin and gelatin to Fonterra's Australian operations and domestic alternative milk startups.
- Bakery Goods:Gluten-free bread and clean-label pastry require hydrocolloid synergies to replicate wheat gluten structure. Sydney's industrial food precincts in Marrickville and Alexandria host co-manufacturers demanding just-in-time hydrocolloid deliveries with embedded technical support.
- Confectionery:Gummy candy and marshmallow formulations leverage gelatin's thermoreversible gelation for controlled texture release.
- Sauces:Viscosity modification in pourable dressings and shelf-stable emulsions depends on xanthan gum's pseudoplastic flow behavior.
Dairy products anchor volume throughput. Bakery goods represent the steepest expansion trajectory as gluten-free and clean-label mandates intensify.
Form:
Volume economics favor powder for industrial-scale dry blending, while liquid concentrates reduce hydration time for mid-sized processors lacking high-shear mixing equipment.
- Powder:Spray-dried and drum-dried hydrocolloid powders with standardized particle size distribution enable uniform dispersion in flour premixes and dry beverage bases.
- Liquid:Pre-hydrated colloidal suspensions eliminate dust exposure and reduce batch cycle times for sauce manufacturers.
- Granules:Intermediate particle size grades balance dissolution speed with storage stability for medium-scale confectionery operations.
- Sheets:Standardized-thickness gelatin sheets provide portion-controlled hydration for premium restaurant and catering applications.
Powder commands installed base through shelf stability. Liquid concentrates gain share fastest among time-constrained contract manufacturers.
Source:
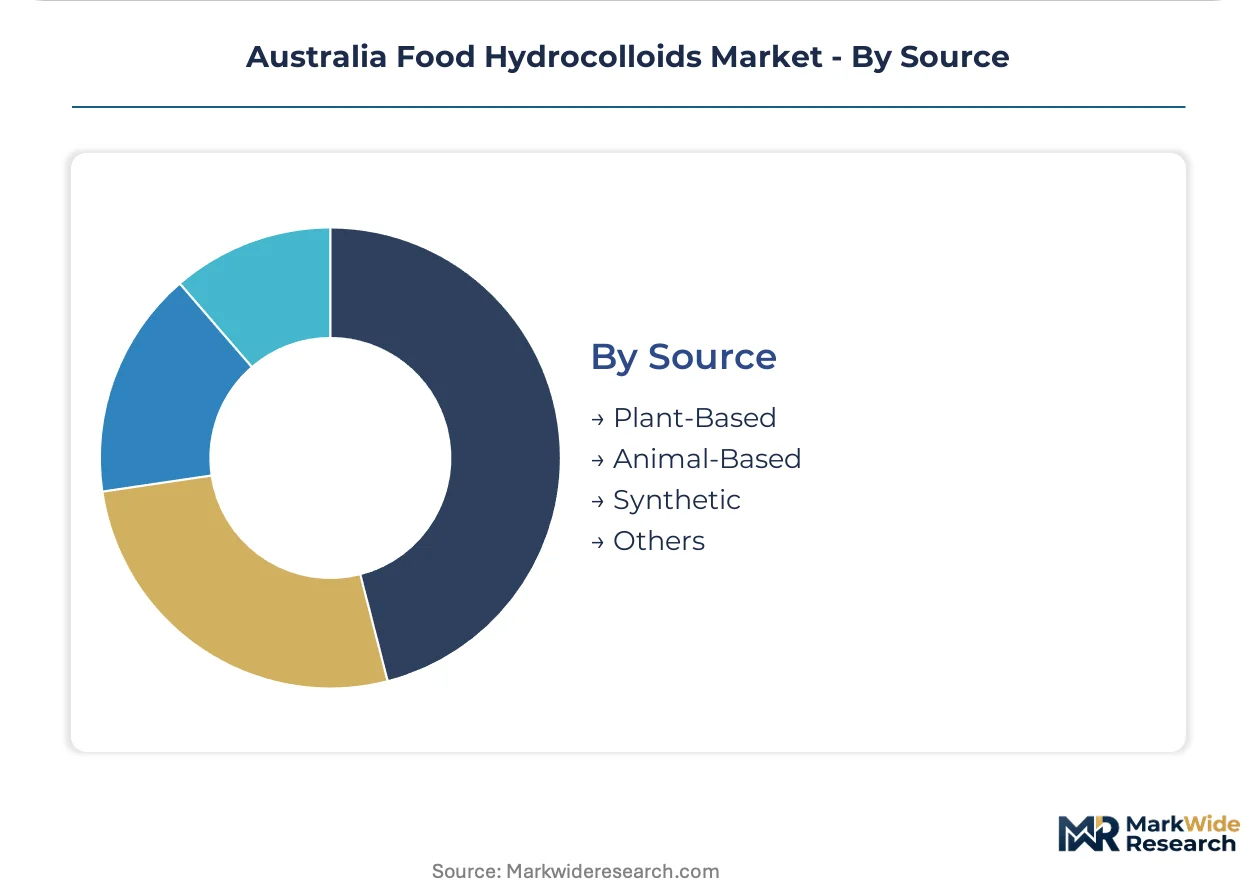
Plant-based positioning captures premium pricing in vegan-labeled products, while animal-based grades retain cost advantage in conventional applications.
- Plant-Based:Pectin from citrus peel, agar from red algae, and locust bean gum from carob seeds align with vegan certification requirements. Tasmanian seaweed cultivation trials for carrageenan and alginate extraction offer shorter supply chains than Brazilian citrus dependency.
- Animal-Based:Collagen-derived gelatin from Australian bovine and porcine processing provides unmatched mouthfeel in premium confectionery.
- Synthetic:Chemically modified cellulose derivatives serve industrial applications where label declarations are less restrictive.
- Others:Microbial fermentation products including xanthan gum and emerging precision-fermentation collagen occupy regulatory gray zones between natural and synthetic classifications.
Animal-based gelatin dominates installed base through cost-positioning. Plant-based sources concentrate expansion as vegan-label dairy alternatives multiply across Victoria and New South Wales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ code amendments on additive transparency are compressing import pathways and forcing domestic reformulation cycles across eastern seaboard food processors. State-level processing concentration in Queensland and Victoria creates freight advantages for hydrocolloid procurement. Regional demand patterns diverge sharply between industrial dairy corridors and artisan bakery clusters.
New South Wales
Sydney's clean-label bakery movement accelerates gelatin and pectin uptake in artisan bread and pastry applications. FSANZ Standard 1.3.1 compliance thresholds tighten import documentation requirements for additive shipments through Port Botany. Marrickville and Alexandria industrial food precincts host co-manufacturers demanding just-in-time hydrocolloid deliveries with embedded technical support.
Victoria
Melbourne's dairy alternative manufacturers accelerate domestic pectin trials to preempt certification delays for Brazilian citrus peel imports. The Department of Agriculture requires enhanced fermentation substrate documentation for xanthan gum shipments entering Victorian ports. Northern suburban processing zones concentrate bulk hydrocolloid blending capacity serving Fonterra's Australian operations and domestic milk alternative startups.
Queensland
Beef processing cycles generate collagen input volatility for gelatin production tied to Queensland's cattle industry. TGA cross-referencing on novel hydrocolloid health claims adds compliance layers for functional food positioning in Brisbane-based sports nutrition brands. Southeast Queensland hosts the bulk of domestic hydrocolloid manufacturing clusters reducing freight costs for eastern seaboard food manufacturers.
South Australia
Adelaide's mid-sized sauce processors seek pre-hydrated liquid hydrocolloid concentrates to eliminate dust exposure and reduce batch cycle times. FSANZ pending revisions on microbial specification limits threaten re-certification requirements for current offshore suppliers. The state's food technology institutes develop hydrocolloid synergy mapping capabilities to address clean-label formulation expertise shortages.
Tasmania
Cold-water macroalgae cultivation trials advance carrageenan and alginate extraction for plant-based hydrocolloid positioning. Shorter supply chains from Tasmanian seaweed farms bypass Brazilian citrus dependency and currency risk exposure. The island's marine biotechnology sector targets premium vegan-label dairy alternatives across Victoria and New South Wales.
Australia Food Hydrocolloids Market Competitive Environment
Listed leaders compete with private specialists across distribution depth and formulation customization capabilities. The supplier base compresses around three strategic tiers: global ingredient conglomerates with certified supply lines, regional distributors anchoring domestic bakery and confectionery relationships, and biotechnology ventures piloting precision-fermentation alternatives. Competitive moves concentrate on M&A for distribution network expansion and strategic partnerships for just-in-time technical service embedding.
Within the global conglomerate tier, Cargill Incorporated and Ingredion Incorporated occupy positions defined by cross-continental sourcing networks and pre-certified FSANZ compliance pathways. Kerry Group plc exemplifies the formulation-specialist archetype through tailored hydrocolloid blend capabilities. Hawkins Watts Limited anchors the regional distributor vector with established ties to domestic bakery and confectionery manufacturers. These three patterns represent the structural options available to processors navigating tightening import biosecurity protocols.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| CP Kelco |
| Koninklijke DSM N.V. |
| Hawkins Watts Limited |
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Tate & Lyle PLC |
| FMC Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for Brazilian citrus peel pectin expose Australian dairy processors to currency-driven cost spikes while compressing margin buffers for mid-sized bakery blenders. This lead-time vulnerability concentrates pricing power with pre-certified suppliers holding FSANZ-aligned documentation, forcing buyers to absorb premium tiers or reformulate around domestic gelatin alternatives.
Pricing Analysis
Certification level (FSANZ pre-certification versus pending import documentation) creates the primary spread between premium and standard hydrocolloid tiers. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade levels governs dairy and bakery procurement, with microbial specification compliance acting as the key price escalator. Cost compression in economy-grade gelatin is intensifying because Queensland cattle processing volatility feeds into hide supply uncertainty. Mid-sized sauce manufacturers in South Australia exhibit highest price sensitivity due to limited volume leverage, while Fonterra-linked dairy processors accept premium tiers for supply security.
Supply Chain Analysis
Brazil and Mexico anchor global citrus peel pectin extraction, while China dominates xanthan gum fermentation substrate production. Australian hydrocolloid procurement draws from Brazilian citrus dependency for clean-label gelling agents and Chinese bioreactor output for gluten-free bakery stabilizers. Single-source vulnerability concentrates in offshore pectin supply chains exposed to shipping lane congestion and currency fluctuation. Distribution runs through established ingredient distributors like Hawkins Watts Limited for industrial dairy and bakery accounts, with direct-to-manufacturer digital platforms emerging for mid-sized Victorian and Queensland processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydrocolloid synergy mapping expertise sits in critically short supply across Australian food technology institutes, constraining clean-label reformulation velocity for smaller brands and amplifying first-mover advantages for technical-service-embedded suppliers.
For Market Incumbents: Fortify pre-certified FSANZ supply lines through backward integration into Queensland gelatin processing or Tasmanian seaweed cultivation, defending against precision-fermentation collagen substitutes piloting at laboratory scale. Deepen technical service teams in Melbourne and Sydney industrial food precincts to embed just-in-time delivery capabilities that smaller competitors cannot replicate.
For New Entrants and Emerging Players: Anchor in Tasmanian cold-water macroalgae extraction for carrageenan and alginate supply to Victorian vegan-label dairy alternatives, bypassing Brazilian citrus dependency entirely. Target mid-sized South Australian sauce processors with pre-hydrated liquid concentrate formats that eliminate dust exposure and reduce batch cycle times without requiring high-shear mixing capital.
For Investors and Strategic Acquirers: Carve-out targets emerge from global ingredient conglomerates divesting non-core hydrocolloid distribution assets in Asia-Pacific. Long-term viability hinges on biotechnology transition readiness over the coming decade. Watch precision-fermentation collagen platform announcements from Australian cultured-meat startups as the signal indicating acceleration of animal-sourced gelatin displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Gelatin Processing | Queensland cattle industry linkages secure collagen input against hide supply volatility. |
| Tasmanian Seaweed Cultivation Scale-Up | Cold-water macroalgae extraction shortens plant-based hydrocolloid supply chains versus Brazilian citrus. |
| FSANZ Pre-Certification Investment | Early compliance with pending microbial specification amendments locks import pathway access. |
| Precision-Fermentation Collagen Pilot | Laboratory-scale platforms decompose historical meat-processing-volume dependency for gelatin. |
| Direct-to-Manufacturer Digital Platform Launch | Mid-sized Victorian and Queensland processors bypass traditional distributor markups. |
Study Parameters
Operator-level perspectives from food technology directors at Victorian dairy alternative manufacturers, procurement leads at Queensland bakery processors, and regulatory affairs specialists navigating FSANZ code amendments anchored the qualitative base. Secondary validation drew from FSANZ standard filings, Department of Agriculture biosecurity protocols, Australian Bureau of Statistics trade data, and TGA health claim cross-reference documentation. Bottom-up volume modeling across hydrocolloid product types, applications, and source categories triangulated against top-down market sizing from customs records and industry association estimates.
Sensitivity analysis tested forecast robustness against alternative scenarios for Brazilian citrus peel supply disruption, Queensland cattle processing cycle volatility, and precision-fermentation collagen commercialization timelines. Segmentation dimensions modeled include product type (pectin, gelatin, xanthan gum, agar), application (dairy, bakery, confectionery, sauces), form (powder, liquid, granules, sheets), and source (plant-based, animal-based, microbial fermentation). CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory inflection points and substitution elasticity parameters across the projection horizon.
Material uncertainties — FSANZ microbial specification amendments, currency fluctuations in Brazilian real-denominated pectin contracts, and precision-fermentation collagen scale-up viability — sit outside the modeled envelope. Forecasts reflect documented assumptions on clean-label mandate persistence and gluten-free bakery expansion trajectories. Recalibration cycles align with material shifts in regulatory enforcement intensity and biotechnology platform commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Global Food Carbohydrase Market