
 Europe Omega-3 for Food Application Market | 2026-2036
Europe Omega-3 for Food Application Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Omega-3 for Food Application Market Foresight
The EU Green Deal is restructuring how European food manufacturers source and label omega-3 ingredients across packaged goods categories. ADM leverages its integrated oilseed processing network to secure consistent EPA and DHA supply chains for continental bakery and dairy clients. GC Rieber Oils anchors its position through Norwegian marine oil refining capacity that sustains pharmaceutical-grade extraction standards for food application.
Europe Omega-3 for Food Application comprises long-chain polyunsaturated fatty acids—primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—extracted from marine biomass or microalgal fermentation and incorporated into food matrices at concentrations typically ranging from 32 mg to 500 mg per serving to support cardiovascular and cognitive health claims. Fish oil dominates value contribution due to established refining infrastructure and cost-efficient bulk supply, while algal oil captures accelerated growth among vegan-positioned functional foods and plant-based dairy alternatives where allergen-free and sustainable sourcing claims command price premiums. Powder forms lead manufacturing adoption for dry-mix beverages and bakery premixes, whereas liquid emulsions concentrate margin pools in premium infant nutrition and medical food segments.
EFSA maintains strict health claim substantiation protocols under EU Regulation 1924/2006, while REACH and the EU F-Gas Regulation govern solvent-based extraction chemistries and processing emissions that constrain conventional refining economics. EMA-aligned novel food approval pathways for algal and krill-derived ingredients extend development timelines but reward first-movers with protected market access. Stakeholders must monitor evolving EFSA opinions on daily intake thresholds and marine contaminant limits, as these will determine which extraction technologies and species sources retain commercial viability across European food manufacturing.
Market Dynamics
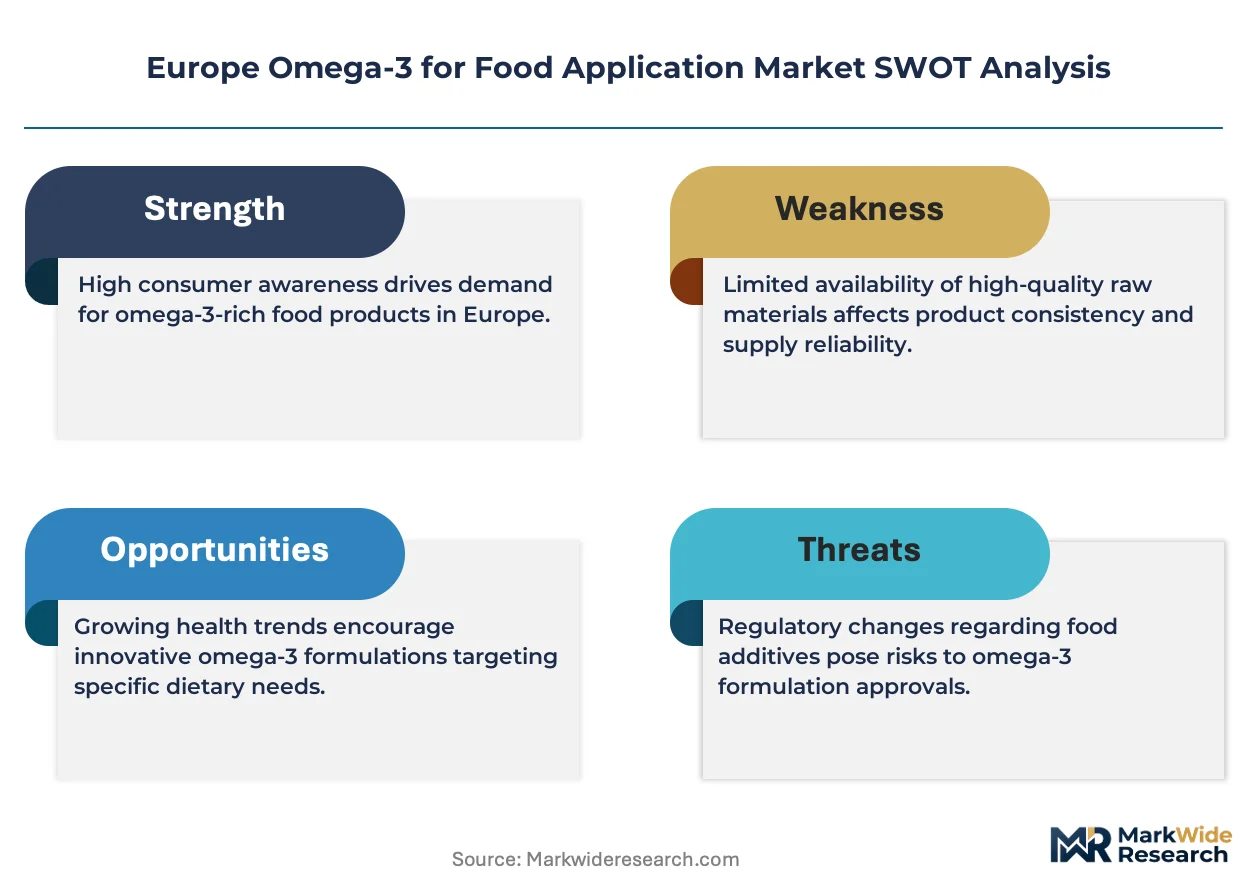
EU Green Deal nutritional labeling mandates and marine sustainability benchmarks are forcing European food manufacturers to restructure omega-3 procurement around certified sustainable sources and transparent supply chain documentation.
Growth Catalysts
- EFSA Health Claim Framework:Substantiated cardiovascular and cognitive health claims under EU Regulation 1924/2006 enable premium positioning for fortified dairy and bakery products.
- Scandinavian Aquaculture Expansion:Norwegian and Danish salmon farming operations drive concentrated demand for EPA-DHA enriched feed formulations with documented sustainability credentials.
- Algal Fermentation Scale-Up:Controlled-environment microalgal production systems eliminate marine contaminant risks while satisfying vegan-positioned functional food formulations.
Market Restraints
- Fish Oil Supply Concentration:North Atlantic and South American fishery dependencies expose processors to quota volatility and seasonal biomass fluctuations.
- REACH Solvent Constraints:Hexane and other extraction chemistries face escalating registration costs and emission controls under ECHA protocols.
- Plant-Based Omega-3 Competition:ALA-rich chia, flax, and hemp oils capture budget-conscious segments despite inferior EPA-DHA conversion efficiency.
Strategic Opportunities
- Mediterranean Functional Dairy:Greek and Italian yogurt manufacturers represent underpenetrated channels for DHA-fortified premium positioning.
- EU F-Gas Regulation Compliance:Supercritical CO2 extraction investments qualify for green transition financing while future-proofing refining assets.
- Medical Food Channel Development:Hospital and clinical nutrition procurement pathways offer insulated pricing for pharmaceutical-grade omega-3 emulsions.
Industry Challenges
- Novel Food Approval Timelines:EMA-aligned safety assessments for krill and alternative marine sources extend product development cycles.
- Cross-Contamination Protocols:Allergen management systems must segregate fish-derived and algal processing lines to maintain vegan certification integrity.
- Specialized Extraction Engineering:Supercritical and molecular distillation expertise remains concentrated among Nordic and German equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Omega-3 for Food Application Market |
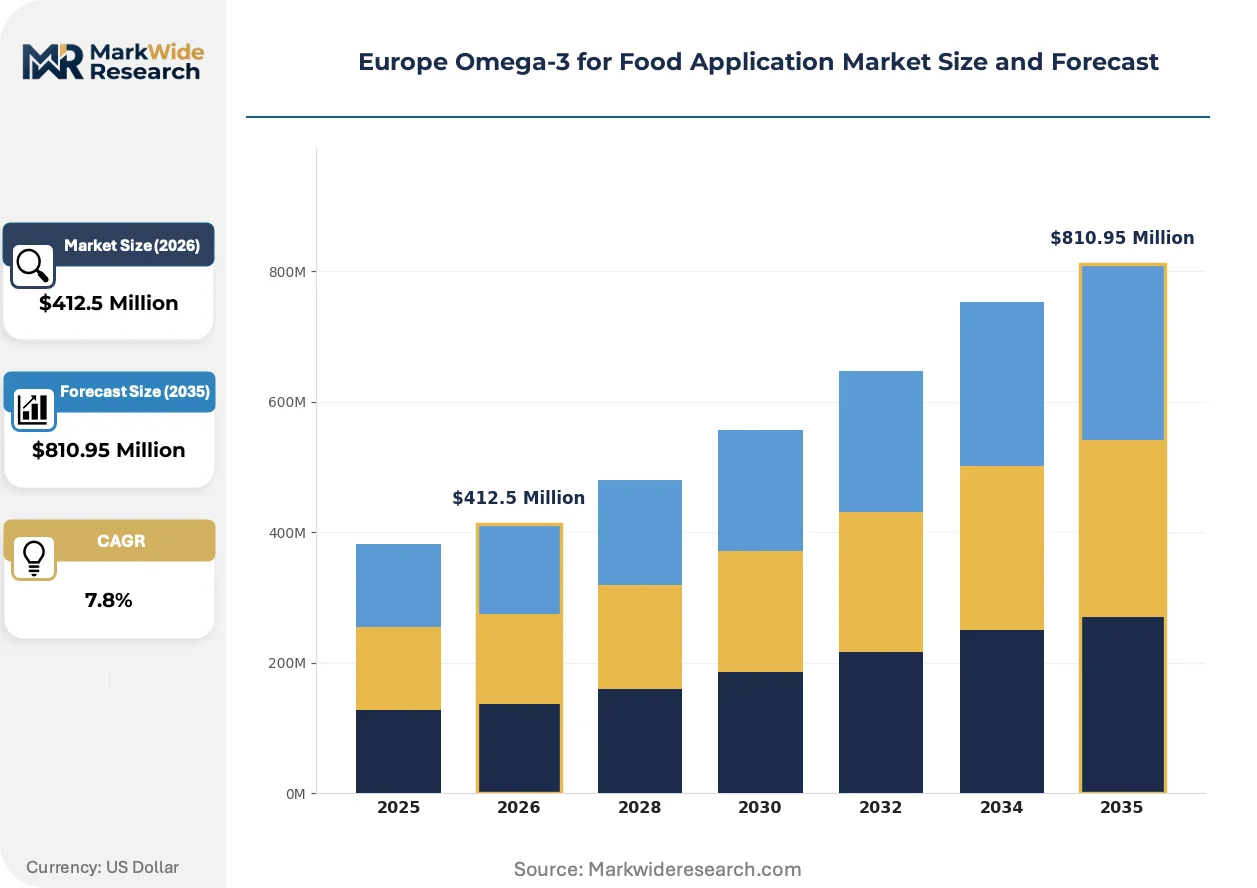
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Concentrates Use Case: Beverages, Functional Foods, Dairy Products, Bakery Form: Liquid, Powder, Emulsion, Capsules End User: Manufacturers, Retailers, Food Services, Distributors |
| Companies Covered | ADM, GC Rieber Oils, DSM Nutritional Products, KD Pharma Group, Polaris, BASF SE, Aker BioMarine, Cargill, Croda International Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Omega-3 for Food Application Market Shifts & Advancements
European omega-3 food applications are pivoting from commodity fish oil refining toward precision fermentation and carbon-accounted extraction systems that align with EU decarbonization targets.
Supercritical CO2 extraction technology is rewriting the competitive economics of EPA-DHA concentration by eliminating thermal degradation and solvent residues. German and Norwegian refiners are retrofitting batch plants with continuous-flow systems that recover 40% more bioactive fractions. This process intensification is compressing capital requirements for pharmaceutical-grade production while enabling smaller batch sizes for niche medical food contracts.
REACH and the EU F-Gas Regulation are tightening emission controls on conventional solvent-based refining, forcing processors to document carbon intensity across extraction, winterization, and molecular distillation stages. Facilities in the Netherlands and Denmark are installing closed-loop thermal systems to maintain operating licenses. Algal oil producers leveraging fermentation rather than wild harvest face lighter compliance burdens and faster novel food pathways.
Scandinavian aquaculture feed buyers are consolidating procurement around vertically integrated suppliers offering marine stewardship certification and blockchain-tracked origin documentation. Norwegian salmon farmers now require batch-level contaminant testing and carbon footprint declarations as standard contract terms. This specification escalation favors refiners with captive fleet partnerships and in-house analytical laboratories over merchant oil traders.
Europe Omega-3 for Food Application Market Segmentation
Omega-3 food applications demand precise technical matching between fatty acid profiles and processing constraints. Each segmentation dimension carries distinct capital requirements and margin structures that determine supplier viability.
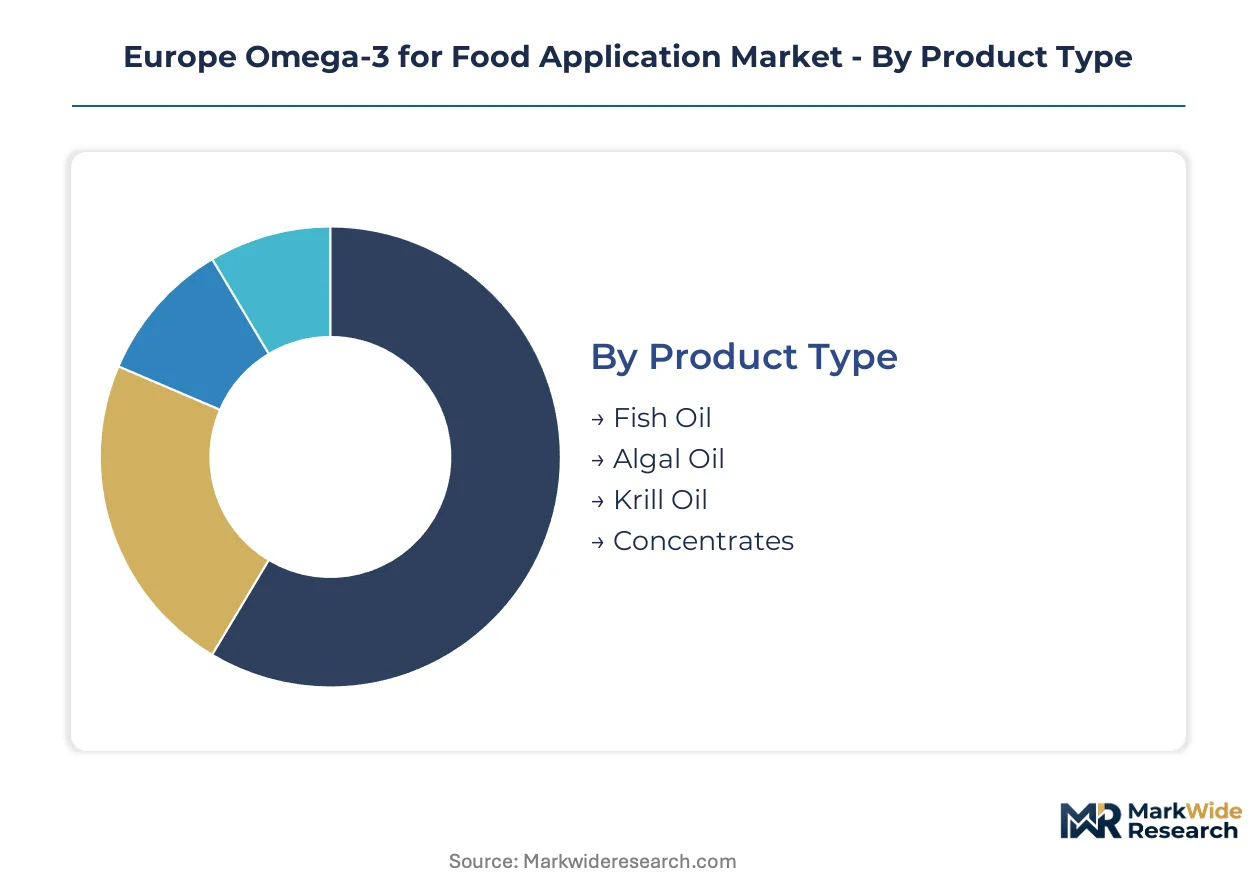
Product Type:
Capital intensity varies sharply across extraction and refinement technologies, with marine-derived sources requiring substantially higher upfront investment than fermentation-based alternatives.
- Fish Oil:Triglyceride and ethyl ester forms refined through molecular distillation and winterization. Norwegian and Danish salmon feed operations anchor volume demand, though North Atlantic quota volatility forces processors to maintain multi-origin sourcing networks.
- Algal Oil:Fermentation-derived EPA-DHA from Schizochytrium or Crypthecodinium strains eliminates marine contaminant concerns. German and Dutch biotech facilities are scaling photobioreactor capacity to serve vegan-positioned dairy alternatives.
- Krill Oil:Phospholipid-bound omega-3 extracted from Antarctic Euphausia superba.
- Concentrates:Ultra-purified EPA or DHA fractions exceeding 80% purity for medical food applications.
Most installed capacity flows through fish oil refining. Expansion is steepest in algal fermentation systems.
Use Case:
Application economics diverge based on oxidation stability requirements and serving-size constraints across liquid and solid food matrices.
- Beverages:Dry-mix powders and microencapsulated emulsions for shelf-stable omega-3 delivery. Scandinavian functional drink manufacturers are specifying batch-level TOTOX values below 10 meq/kg.
- Functional Foods:Cereals, nutrition bars, and spreads with cardiovascular health claims. Italian and Spanish producers dominate Mediterranean demand for DHA-fortified premium positioning.
- Dairy Products:Yogurt, milk, and cheese fortification requiring cold-chain stable emulsions.
- Bakery:Omega-3 enriched breads and pastries with heat-stable microencapsulation.
Volume concentrates in functional foods. Steepest expansion trajectory appears in dairy fortification.
Form:
Processing infrastructure investments scale with emulsion complexity and encapsulation technology sophistication.
- Liquid:Bulk triglyceride oils for industrial food manufacturing and direct consumer bottling.
- Powder:Spray-dried and fluid-bed agglomerated forms for dry premixes and instant beverages. German bakery premix suppliers specify powder formats for 18-month shelf life targets.
- Emulsion:Water-dispersible microencapsulated oils for transparent beverage fortification. French and Dutch infant nutrition specialists drive specification intensity for sub-500 nanometer particle sizes.
- Capsules:Softgel and hard-shell delivery systems crossing into supplement-channel distribution.
Most processing assets serve powder production. Emulsion capacity is climbing fastest.
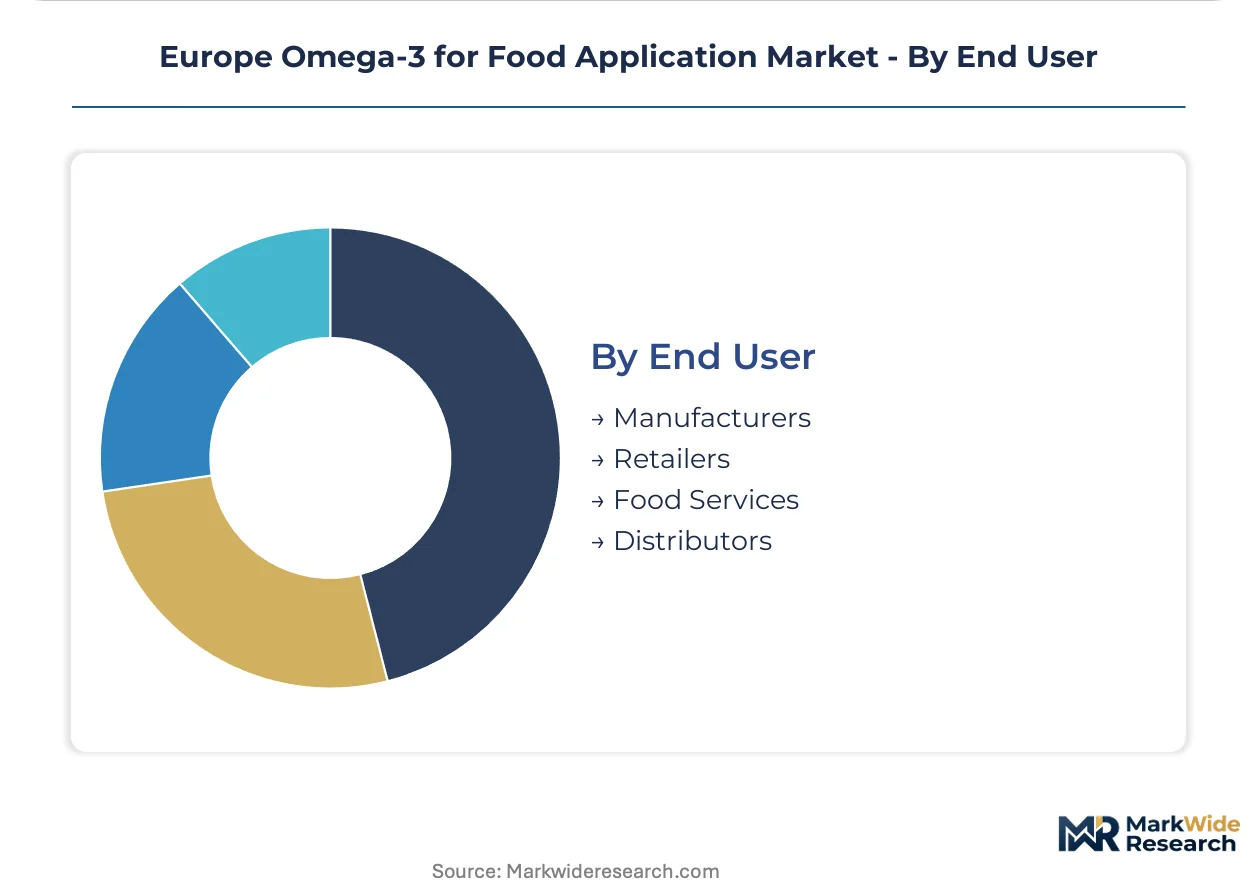
End User:
Customer-type economics reflect procurement scale, technical specification authority, and certification documentation requirements.
- Manufacturers:Branded food companies and private-label producers with in-house formulation capabilities. Scandinavian aquaculture feed compounders consolidate procurement around vertically integrated suppliers offering blockchain-tracked origin documentation.
- Retailers:Supermarket chains and health food stores with own-brand omega-3 product lines.
- Food Services:Institutional catering and restaurant chains with limited technical specification authority.
- Distributors:Ingredient traders and brokers serving mid-tier manufacturers without direct refiner relationships.
Transaction volume flows predominantly through manufacturers. Distributor channel share is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine biochemists and aquaculture engineers concentrate along Europe's North Atlantic and Mediterranean coastlines. Norwegian fjord communities host the densest clusters of omega-3 refining expertise. German and Dutch biotechnology centers anchor algal fermentation scale-up operations.
Germany
ADM operates integrated oilseed processing networks serving continental bakery and dairy clients with consistent EPA-DHA supply chains. EFSA health claim substantiation protocols under EU Regulation 1924/2006 govern all cardiovascular positioning claims. The Hamburg-Rotterdam corridor hosts supercritical CO2 extraction facilities retrofitting continuous-flow systems.
Norway
Salmon farming operations in Trøndelag and Vestland drive concentrated demand for feed-grade omega-3 with blockchain-tracked origin documentation. GC Rieber Oils maintains pharmaceutical-grade marine oil refining capacity in Kristiansund. Bergen anchors the Nordic marine stewardship certification ecosystem.
Netherlands
DSM Nutritional Products leverages fermentation-derived algal oil capacity for vegan-positioned dairy alternatives. REACH solvent constraints and EU F-Gas Regulation emission controls force processors to install closed-loop thermal systems. The Rotterdam port complex handles bulk triglyceride imports for European distribution.
France
Polaris and Mediterranean functional food manufacturers expand DHA-fortified yogurt positioning in Provence-Alpes-Côte d'Azur. ANSM-aligned novel food approval pathways extend development timelines for krill-derived ingredients. The Lyon biotech cluster incubates microencapsulation specialists serving infant nutrition formulators.
United Kingdom
Croda International Plc occupies specialty emulsion chemistry positions for medical food applications. Health England nutritional guidelines influence hospital procurement specifications for pharmaceutical-grade omega-3. The Cambridge-Norwich corridor hosts lipid research facilities advancing oxidation stability protocols.
Europe Omega-3 for Food Application Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across extraction technology tiers. The vendor base separates between marine harvesters with captive fleet partnerships and fermentation specialists with controlled-environment bioreactors. Three archetypes dominate: vertically integrated Nordic refiners, German-Dutch biotechnology platforms, and Swiss-French specialty emulsion houses. Competitive moves concentrate on supercritical extraction licensing and algal strain IP acquisition.
Within the integrated refiner tier, GC Rieber Oils and Aker BioMarine exemplify North Atlantic sourcing control. Among biotechnology platforms, DSM Nutritional Products and BASF SE occupy positions spanning fermentation scale-up to finished ingredient formulation. ADM represents the agribusiness archetype with oilseed processing infrastructure repurposed for omega-3 concentration. These anchors demonstrate how geographic proximity to biomass sources or pharmaceutical-grade standards determines viable competitive positioning.
| Leading Market Players |
|---|
| ADM |
| GC Rieber Oils |
| DSM Nutritional Products |
| KD Pharma Group |
| Polaris |
| BASF SE |
| Aker BioMarine |
| Cargill |
| Croda International Plc |
| Others |
Supply & Pricing Matrix
North Atlantic fish oil spot benchmarks cascade through European omega-3 supply chains into three distinct pricing tiers: pharmaceutical-grade concentrates for medical food contracts, food-grade emulsions for infant nutrition formulators, and commodity triglycerides for aquaculture feed compounders. EFSA certification tiers and REACH compliance documentation costs widen spreads between adjacent tiers, while Norwegian salmon farmers' blockchain-tracked origin requirements add premium qualification layers that resist commoditization.
Pricing Analysis
Bundled certification-and-testing packages versus unbundled raw-material supply splits the market into service-integrated and commodity-trading archetypes. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels reflects EFSA health claim substantiation depth and contaminant testing rigor. Cost compression in feed-grade concentrates is intensifying because Scandinavian aquaculture buyers are consolidating procurement around vertically integrated suppliers. Aquaculture feed compounders exhibit highest price sensitivity due to volume concentration and specification standardization, while medical food channels accept premium positioning for batch-level documentation.
Supply Chain Analysis
Dual-sourcing requirements mandated by major Scandinavian aquaculture buyers and German dairy manufacturers force processors to maintain qualified supplier networks across Norway, Peru, and Chile. Wild-caught anchovy and sardine biomass from South American fisheries, combined with Norwegian cod liver and North Atlantic krill, feeds European refining capacity. Single-source vulnerability concentrates in Antarctic krill harvesting where Aker BioMarine's proprietary fishing technology creates temporary exclusivity windows. Distribution runs through Rotterdam bulk terminals for triglyceride oils and direct-contract logistics for pharmaceutical-grade emulsions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European omega-3 procurement functions as a geographic-arbitrage play between Norwegian marine extraction economics and German-Dutch fermentation scale-up costs, with REACH solvent constraints and EU F-Gas Regulation emission controls widening the operating cost differential.
For Market Incumbents: Deepen backward integration into Antarctic krill harvesting and Norwegian cod liver supply through captive fleet partnerships or long-term offtake agreements with Nordmøre and Lofoten fishing cooperatives. Algal fermentation specialists in Germany and the Netherlands threaten feed-grade market share with carbon-accounted production systems; incumbents should accelerate supercritical CO2 extraction retrofitting to preserve pharmaceutical-grade margin pools against biotechnology platform competition.
For New Entrants and Emerging Players: Capture Mediterranean functional dairy white space in Greek strained yogurt and Italian fresh cheese categories where DHA fortification penetration lags Scandinavian benchmarks. Greek and Italian manufacturers lack technical formulation partnerships for cold-chain stable emulsions; entrants should lead with application-specific microencapsulation services rather than commodity oil supply.
For Investors and Strategic Acquirers: Asymmetric upside sits with algal fermentation platforms possessing EMA-aligned novel food approvals and pharmaceutical-grade extraction infrastructure. Long-term viability hinges on controlled-environment production economics displacing wild-harvest dependency within the next decade. Watch EFSA opinions on daily intake thresholds and marine contaminant limits as the critical inflection signal determining which extraction technologies retain commercial viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Retrofit | Eliminates REACH solvent compliance costs while recovering 40% more bioactive fractions for pharmaceutical contracts. |
| Antarctic Krill Harvesting License Acquisition | Secures phospholipid-bound omega-3 supply with marine stewardship certification for premium medical food positioning. |
| Algal Fermentation Scale-Up Partnership | DSM Nutritional Products and BASF SE demonstrate controlled-environment EPA-DHA production for vegan-certified dairy alternatives. |
| Mediterranean Dairy Application Laboratory | Proximate technical service to Greek and Italian yogurt manufacturers accelerates DHA fortification adoption curves. |
| Blockchain Origin Documentation System | Norwegian salmon farmers now require batch-level traceability as standard contract terms for feed procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with marine oil refinery operations managers, EFSA regulatory affairs specialists, Scandinavian aquaculture feed procurement directors, German dairy formulation technologists, and Dutch biotechnology R&D leads with secondary validation against EMA novel food submission databases, REACH registration filings, EU trade statistics for marine oil imports, and SEC disclosures from listed omega-3 ingredient suppliers. Bottom-up volume modeling and top-down value reconciliation anchored segment-level outputs.
Historical reference periods spanning pre-pandemic baseline, supply disruption window, and normalization phase structured the forecast anchor points across the projection horizon. Segmentation dimensions modeled include extraction technology tier, fatty acid concentration grade, application matrix requirements, end-user procurement scale, and regulatory compliance pathway. CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules, with EFSA opinion timelines and EU Green Deal implementation pacing as omega-3-specific forecast inputs.
EFSA health claim revision triggers, Antarctic krill quota volatility, and algal fermentation yield breakthroughs are the dominant revision risks to modeled outputs. Deviation in EFSA daily intake threshold determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Grade Antifoams Market