
 Healthy Fat-Free Snacks Market | 2026-2036
Healthy Fat-Free Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Fat-Free Snacks Market Foresight
The FDA Nutrition Facts Label modernization is shifting cost-of-entry calculus for new entrants by mandating stricter disclosure of fat content and serving sizes. PepsiCo leverages its distribution infrastructure to sustain shelf dominance across mass retail channels. Mondelez International anchors its position through specialized R&D facilities focused on fat-replacement technologies. General Mills competes by controlling grain supply chains that underpin cracker and bar formulations.
Healthy fat-free snacks are formulated food products containing less than 0.5 grams of fat per reference amount customarily consumed, achieved through mechanical separation, enzymatic modification, or alternative lipid mimetic systems. These products serve commercial purposes ranging from weight management support to cardiovascular health compliance in institutional foodservice. Bars and chips occupy the largest margin pools as consumers prioritize portable, single-serve formats with clean-label ingredient decks. Popcorn differentiates through air-popping processes that eliminate oil dependency while preserving texture. Online retail channels are extending fastest as direct-to-consumer subscription models bypass traditional slotting fee barriers.
The FDA, USDA, and FTC collectively govern labeling accuracy, health claim substantiation, and advertising practices for fat-free positioned products in the United States. EFSA and national regulators across Europe enforce comparable standards through the Nutrition and Health Claims Regulation, constraining permissible marketing language. Stakeholders must monitor evolving definitions of "healthy" across jurisdictions while deciding whether to pursue reformulation investments or portfolio divestment from legacy full-fat lines.
Market Dynamics
FDA nutrition label modernization is compressing formulation timelines as manufacturers must recalibrate fat-replacement systems to meet stricter disclosure thresholds for serving sizes and nutrient content claims.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States are expanding subsidized healthy snack programs, creating institutional procurement pull for fat-free options that satisfy cardiovascular health guidelines.
- Enzymatic lipid modification:Advances in lipase-catalyzed interesterification enable texture-matched fat reduction without sensory degradation, opening premium positioning for reformulated bars and chips.
- REACH chemical safety protocols:European manufacturers accelerating clean-label transitions to preempt ECHA scrutiny of artificial fat replacers, favoring natural hydrocolloid systems.
Market Restraints
- Input cost volatility:Tapioca-derived maltodextrin and modified food starch prices fluctuate with Brazilian and Thai harvest cycles, squeezing margin stability for air-popped popcorn and extruded snacks.
- Supply concentration risk:Three specialty ingredient houses control global supply of oleogel structuring agents, creating vulnerability for North American formulators dependent on imported lipid mimetics.
- Technical limitation:Current fat-replacement chemistry cannot replicate the mouthfeel of fried textures in shelf-stable formats, constraining chip segment innovation.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retail bypasses traditional slotting fees and enables personalized nutrition bundles targeting weight management consumers.
- India PLI scheme incentives:Domestic food processing infrastructure investments support localized production of millet-based fat-free bars for price-sensitive South Asian markets.
- Dual carbon goals alignment:China's SAMR is prioritizing low-carbon food manufacturing certifications, rewarding brands that demonstrate reduced oil processing emissions in supply chains.
Industry Challenges
- Clean-label formulation expertise scarcity:Food technologists skilled in natural hydrocolloid stabilization command premium compensation, constraining mid-tier manufacturer R&D staffing.
- Certification timeline compression:FDA substantiation requirements for "healthy" nutrient content claims now demand 12-18 month clinical validation cycles, delaying product launches.
- Legacy equipment retrofitting costs:Transitioning from oil-frying to air-popping or extrusion requires capital-intensive line modifications that strain private-label manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Fat-Free Snacks Market |
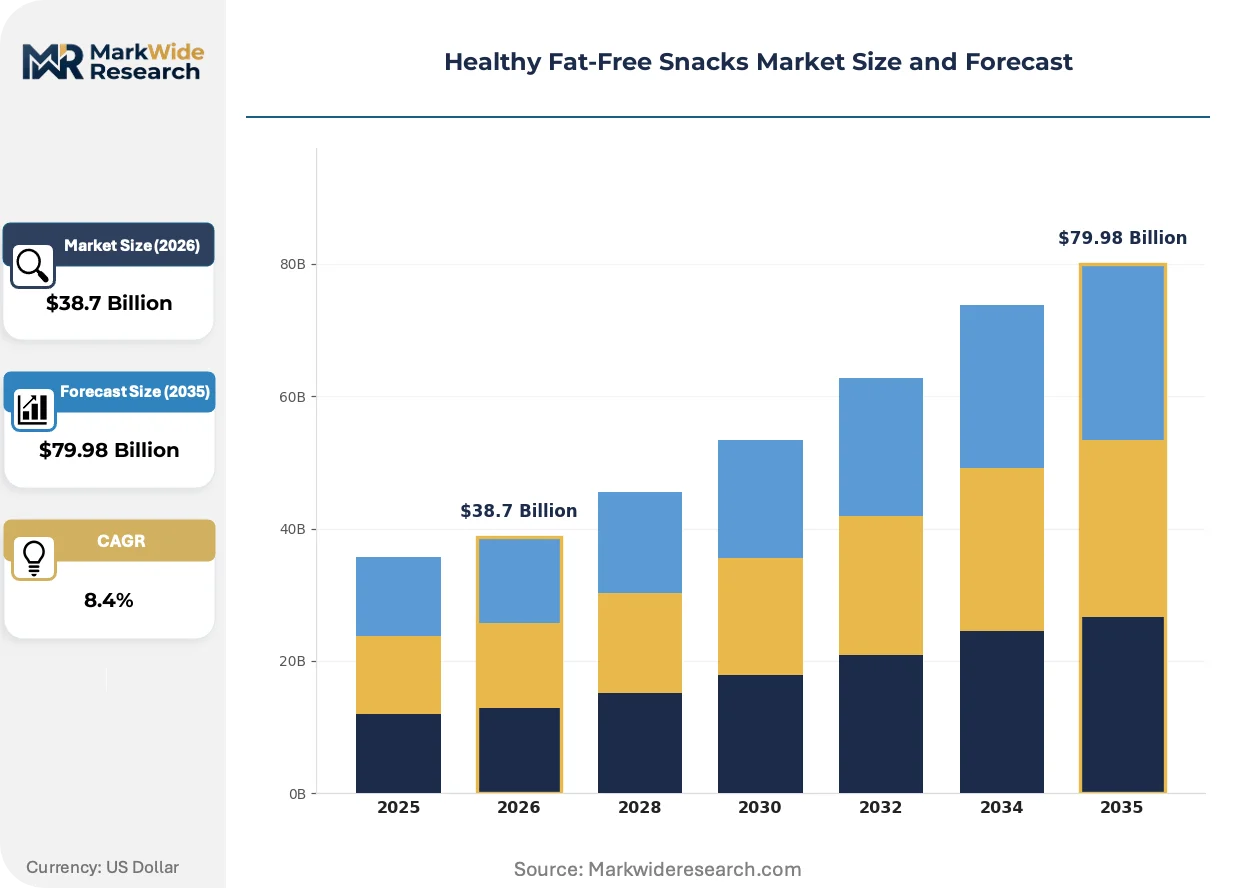
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Bars, Crackers, Popcorn Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops End User: Fitness Enthusiasts, Health-Conscious Consumers, Weight Watchers, Families Packaging Type: Bags, Boxes, Pouches, Bulk |
| Companies Covered | General Mills, Mondelez International, PepsiCo, Nestlé, Kellanova, Conagra Brands, Unilever, Danone, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Fat-Free Snacks Market Shifts & Advancements
Formulation science is converging with digital nutrition platforms to create personalized fat-free snacking protocols that align macro-nutrient profiles with individual metabolic markers.
Microencapsulated oleogel systems derived from ethylcellulose and sorbitan esters are rewriting texture engineering in baked snacks. Mid-size manufacturers in Germany and the Netherlands are piloting these lipid mimetics at commercial scale. The technology is rewriting competitive advantage by enabling fried-mouthfeel replication without oil absorption, collapsing the sensory gap between full-fat and fat-free positioning.
EFSA's updated guidance on nutrition and health claims substantiation is tightening evidentiary standards for cardiovascular benefit assertions. Manufacturers must now commission human intervention studies rather than relying on compositional data alone. European bar and chip producers are responding by reformulating around whole-food ingredient decks that qualify for generic health claims without proprietary substantiation burdens.
Corporate procurement departments are consolidating vendor relationships into single-source wellness platform contracts that bundle fat-free snacks with nutritional counseling services. Foodservice distributors serving technology sector campuses in California and Washington are losing share to specialized wellness integrators. This consolidation is most visible in the United States where self-insured employers face rising diabetes management costs and seek preventive nutrition interventions.
Healthy Fat-Free Snacks Market Segmentation
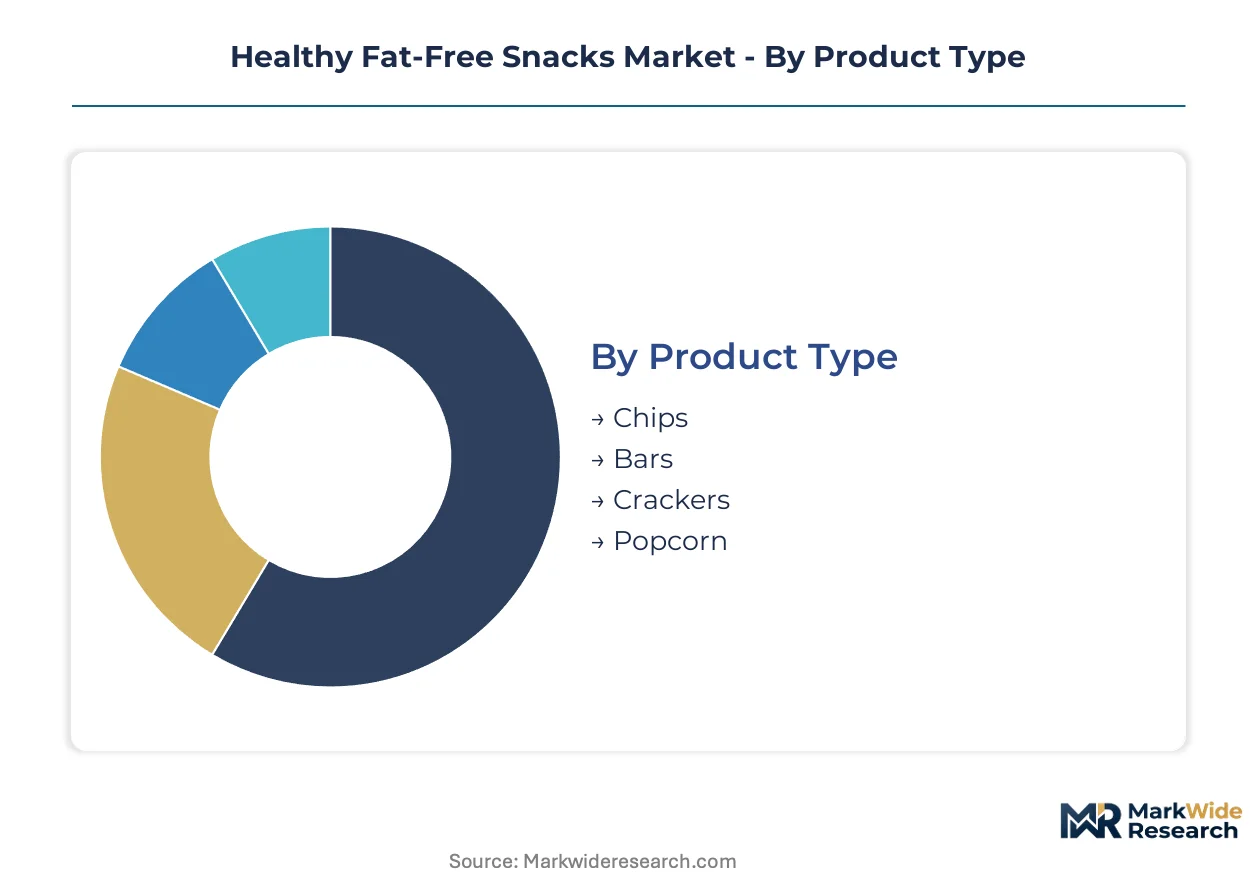
Consumer purchase decisions in the healthy fat-free snacks market pivot on portability requirements, ingredient transparency, and retail accessibility. Manufacturers calibrate formulation investments and packaging formats against these distinct preference clusters to capture margin pools across divergent usage occasions.
Product Type:
Texture fidelity and shelf stability drive buyer selection, with enzymatic fat-replacement capabilities determining premium positioning feasibility.
- Chips:Air-popped and extruded variants eliminate oil absorption while preserving crunch through modified starch matrices. Demand concentrates among corporate wellness programs in the United States seeking single-serve portions for breakroom distribution. Enzymatic lipid modification cannot yet replicate fried mouthfeel, constraining innovation in shelf-stable formats.
- Bars:Formulations rely on hydrocolloid binding systems and protein isolates to achieve structural integrity without lipid lubrication. Weight Watchers and fitness enthusiasts in Germany and the Netherlands pilot microencapsulated oleogel systems for texture enhancement. Clean-label ingredient decks qualify products for EFSA generic health claims without proprietary clinical substantiation.
- Crackers:Grain-based matrices use controlled hydration and steam injection to replace fat-dependent lamination processes.
- Popcorn:Air-popping technology eliminates oil dependency entirely, differentiating through carbon footprint reductions in supply chains serving China's SAMR certification priorities.
Volume sits with bars and chips; growth tilts toward popcorn as air-popping technology matures.
Distribution Channel:
Slotting fee structures and direct consumer relationships reshape margin capture across physical and digital touchpoints.
- Supermarkets:Dedicated better-for-you shelf space expansion in the United States concentrates procurement decisions among three national retail banners. PepsiCo leverages existing distribution infrastructure to defend facings against emerging brands.
- Online Retail:Subscription models bypass traditional slotting barriers and enable personalized nutrition bundles. Direct-to-consumer channels in California and Washington technology corridors are displacing conventional foodservice distributors through wellness platform consolidation.
- Convenience Stores:Impulse purchase dynamics favor portable single-serve formats with immediate consumption positioning.
- Health Food Shops:Curated assortments command premium pricing for certified organic and non-GMO positioned variants.
Revenue concentrates in supermarkets; expansion accelerates most quickly through online retail subscription infrastructure.
End User:
Metabolic health objectives and household composition determine formulation specifications and portion architecture.
- Fitness Enthusiasts:Macro-nutrient tracking demands precise protein-to-carbohydrate ratios with minimal fat interference. Digital nutrition platforms in the United States integrate barcode scanning for real-time dietary logging.
- Health-Conscious Consumers:Clean-label scrutiny extends to fat-replacement ingredient provenance, favoring natural hydrocolloid systems over artificial mimetic compounds.
- Weight Watchers:Portion-controlled packaging aligns with behavioral modification protocols emphasizing satiety signaling through volume rather than caloric density.
- Families:Multi-serve formats and child-friendly flavor profiles prioritize affordability and allergen management over premium positioning.
Procurement volume clusters with health-conscious consumers; demographic momentum favors fitness enthusiasts as wearable metabolic monitoring proliferates.
Packaging Type:
Shelf-life extension and sustainability credentials determine material selection against disposal regulation pressures.
- Bags:Flexible film structures with high oxygen barrier properties protect lipid-free formulations from oxidative degradation. European manufacturers accelerate transitions to comply with ECHA scrutiny of packaging chemistry under REACH protocols.
- Boxes:Rigid formats support premium gifting and subscription unboxing experiences in direct-to-consumer channels.
- Pouches:Stand-up configurations optimize warehouse cube utilization and retail shelf efficiency for bar and chip assortments.
- Bulk:Foodservice and institutional procurement favor reduced packaging overhead for corporate wellness program deployment.
Shipment volume aggregates in bags; sustainability-driven substitution pushes pouches toward fastest adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness program adoption concentrates demand in the United States, while enzymatic fat-replacement R&D clusters in Germany and the Netherlands reshape European formulation standards. India and China present divergent growth vectors through domestic processing incentives and low-carbon manufacturing certification priorities.
United States
Self-insured employers in California and Washington technology corridors drive institutional procurement through consolidated wellness platform contracts. FDA nutrition label modernization mandates stricter fat content disclosure thresholds, compressing manufacturer formulation timelines. Greater Boston hosts specialized foodservice distributors losing share to wellness integrators bundling snacks with nutritional counseling services.
Germany
Mid-size manufacturers pilot microencapsulated oleogel systems for commercial-scale texture engineering in baked snacks. EFSA tightened guidance on cardiovascular health claim substantiation, forcing human intervention studies rather than compositional data alone. The Cologne-Düsseldorf industrial corridor anchors clean-label R&D facilities responding to ECHA REACH protocol scrutiny of artificial fat replacers.
Netherlands
Fitness enthusiasts and weight management consumers generate premium demand for hydrocolloid-stabilized bar formulations. EFSA generic health claim qualifications favor whole-food ingredient decks over proprietary clinical substantiation. Rotterdam-Antwerp logistics hubs facilitate ingredient import for lipid mimetics dependent on specialty chemical houses.
India
Price-sensitive South Asian markets favor millet-based fat-free bars produced through domestic food processing infrastructure. The PLI scheme incentivizes localized manufacturing investments, reducing import dependency for modified food starches. Maharashtra and Gujarat processing clusters expand capacity for air-popped and extruded snack formats.
China
SAMR prioritizes low-carbon food manufacturing certifications, rewarding brands demonstrating reduced oil processing emissions. Yangtze River Delta metropolitan consumers demonstrate willingness to pay premiums for carbon-labeled snack alternatives. Shanghai-based retailers expand dedicated better-for-you shelf space mirroring United States merchandising strategies.
Healthy Fat-Free Snacks Market Competitive Landscape
United States producers anchor one tier through distribution infrastructure dominance; European specialists hold formulation technology advantages in enzymatic modification. The market structure consolidates around three national retail banners controlling supermarket facings, with mid-tier private-label manufacturers struggling against slotting fee barriers. Strategic archetypes include diversified CPG conglomerates, specialized wellness-focused subsidiaries, and contract manufacturing specialists. Competitive moves concentrate on portfolio divestment from legacy full-fat lines and direct-to-consumer subscription channel establishment.
Within the diversified conglomerate tier, PepsiCo and General Mills occupy positions defined by captive supply chain control and mass retail channel penetration. Mondelez International exemplifies the R&D-intensive archetype through specialized facilities targeting fat-replacement technology. These three entities represent distinct competitive vectors: distribution scale, upstream grain supply control, and formulation science investment.
| Leading Market Players |
|---|
| General Mills |
| Mondelez International |
| PepsiCo |
| Nestlé |
| Kellanova |
| Conagra Brands |
| Unilever |
| Danone |
| The Kraft Heinz Company |
| Others |
Supply & Pricing Matrix
Corporate wellness procurement consolidation in California and Washington technology corridors is forcing manufacturers to absorb slotting fee compression while maintaining clean-label ingredient standards, driving margin pressure back into supply chain restructuring decisions around tapioca maltodextrin sourcing and enzymatic fat-replacement investments.
Pricing Analysis
Volume concentrates in economy-tier private-label bars and chips serving institutional foodservice, while margin pools sit with premium-positioned microencapsulated oleogel formulations in Germany and the Netherlands. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and ingredient provenance, with EFSA generic health claim qualification commanding substantial premia. Cost compression in the economy tier is intensifying because Brazilian and Thai harvest volatility squeezes modified food starch input costs. Health-conscious consumers in direct-to-consumer channels demonstrate lowest price sensitivity, while family-oriented multi-serve formats face acute pressure from private-label substitution.
Supply Chain Analysis
Dual-sourcing requirements from North American formulators mandate qualification of alternative oleogel structuring agents beyond the three dominant specialty ingredient houses, fragmenting procurement leverage. Supply concentrates in Thailand and Brazil for tapioca-derived inputs, with Germany and the Netherlands anchoring enzymatic lipid modification R&D capabilities. Raw material dependencies rest on ethylcellulose microencapsulation compounds, sorbitan ester stabilizers, and millet flour for India-localized production. Single-source vulnerability in specialty lipid mimetics creates exposure to ECHA REACH protocol enforcement actions. Distribution runs through consolidated national retail banners in the United States, with direct-to-consumer subscription infrastructure displacing conventional foodservice distributors in technology corridor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA nutrition label modernization creates a cost-of-compliance moat where clinical substantiation investments and reformulation timelines filter out undercapitalized competitors, rewarding incumbent players with captive R&D infrastructure and established regulatory affairs capabilities.
For Market Incumbents: Extend formulation science leadership by accelerating microencapsulated oleogel commercialization ahead of EFSA tightened evidentiary standards, while consolidating vendor relationships into single-source wellness platform contracts that bundle fat-free snacks with nutritional counseling services to defend against emerging wellness integrators displacing conventional foodservice distributors in California and Washington.
For New Entrants and Emerging Players: Self-insured employers in Greater Boston seeking preventive nutrition interventions represent an underserved buyer archetype where specialized wellness integrators are gaining share from legacy foodservice distributors. White-space opportunity sits with personalized nutrition bundles targeting fitness enthusiasts through direct-to-consumer subscription channels, and with millet-based fat-free bars for price-sensitive South Asian markets leveraging India PLI scheme incentives. The most penetrable entry vector combines clean-label certification with carbon-labeled positioning for SAMR-aligned low-carbon manufacturing priorities in China.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-size European manufacturers possessing enzymatic fat-replacement capabilities given EFSA's shift toward human intervention study requirements that favor whole-food ingredient decks over proprietary clinical substantiation burdens. Long-term viability over the coming decade hinges on portfolio positioning away from legacy full-fat lines toward air-popping and extrusion infrastructure. The acquisition target archetype combines clean-label R&D facilities with established direct-to-consumer subscription infrastructure. Deviation in FDA "healthy" claim substantiation timelines would signal material inflection for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses slotting fee barriers and enables personalized nutrition bundles for weight management consumers. |
| Clean-Label R&D Facility Investment | Addresses formulation expertise scarcity while qualifying products for EFSA generic health claims without proprietary substantiation. |
| Backward Integration into Tapioca Sourcing | Stabilizes input cost volatility from Brazilian and Thai harvest cycles for air-popped popcorn and extruded snacks. |
| Air-Popping Equipment Retrofit | Transitions from oil-frying to eliminate oil dependency while preserving texture for SAMR carbon certification alignment. |
| Wellness Platform Partnership | Consolidates vendor relationships with corporate procurement departments bundling snacks with nutritional counseling services. |
Research Methodology
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone, supplemented by Nielsen retail audit data tracking better-for-you shelf space expansion. Primary interviews with brand managers at diversified CPG conglomerates, category buyers at national retail banners, supply planners managing tapioca-derived input procurement, and regulatory affairs leads navigating FDA substantiation requirements provided qualitative grounding. Bottom-up and top-down triangulation validated segmentation assumptions across product type, distribution channel, and end user dimensions.
Historical trendline analysis of air-popping technology adoption and enzymatic lipid modification deployment established baseline growth trajectories across the analysis window. The analytical framework modeled volume and value outputs by product type, distribution channel, end user archetype, and regional regulatory cluster. CAGRs derived from weighted average of segment-specific growth rates incorporated input cost volatility assumptions for modified food starches and oleogel structuring agents.
Revisions become necessary when FDA substantiation timelines extend beyond current clinical validation cycles, when ECHA REACH protocol enforcement disrupts specialty lipid mimetics availability, or when corporate wellness procurement consolidation accelerates faster than wellness integrator capacity expansion. Deviation in Brazilian and Thai harvest yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
UK Snack Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Snacks Market
Snacks
Savory Snack Products Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Nutritional Bar Market
Snacks
Organic Snacks Market
Snacks
Global Protein Snack Market
Snacks
Salty Puffed Snacks Market
Snacks
North America Fruit Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
Asia Pacific Tortilla Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
China Snack Bar Market
Snacks
North America Snack Food Market