
 France Food Preservatives Market | 2026-2036
France Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Preservatives Market Foresight
Modular preservative dosing is pivoting how French food processors configure shelf-life solutions, unbundling traditional bundled antioxidant-acidulant blends into single-function ingredients. Corbion NV leverages its lactic acid expertise to anchor clean-label positioning across dairy applications. Kerry Group competes through integrated taste-preservation platforms that extend formulation control to bakery clients. BASF SE dominates synthetic antioxidant supply with manufacturing scale that sustains cost discipline in commodity segments.
France food preservatives encompass chemical and natural substances added to food matrices to inhibit microbial spoilage, oxidative rancidity, and enzymatic degradation, typically dosed at 0.01% to 0.5% by weight depending on matrix water activity and pH. Their primary commercial purpose is to extend distribution reach for ambient and chilled packaged foods while meeting ANSES safety thresholds. Antimicrobials lead preservative type revenue due to bread and dairy spoilage risks that dominate French consumption patterns. Acidulants represent the fastest-expanding category as processors reformulate around vinegar-derived and citric acid systems to satisfy clean-label procurement criteria from retail chains. Chelating agents occupy a mature margin pool concentrated in beverage stabilization where EDTA alternatives face substitution pressure from consumer advocacy groups.
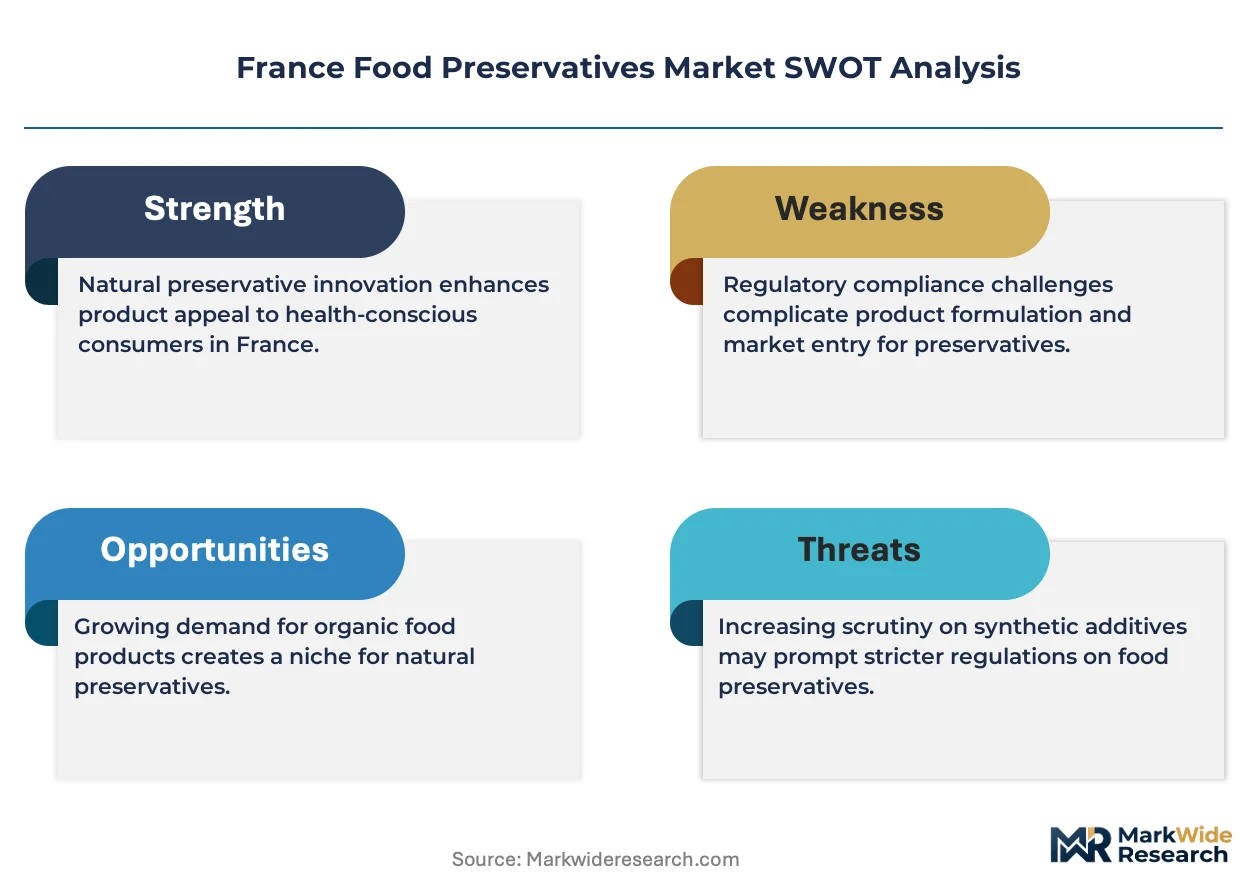
ANSES enforces additive maximum limits derived from EFSA scientific opinions, while EU REACH and the EU Green Deal chemical sustainability framework shape ingredient registration and bio-based substitution pathways. French processors navigate dual compliance pressure: EFSA re-evaluations of benzoates and sorbates trigger formulation redesign costs, and CSRD reporting obligations push supply chain chemical footprint transparency to downstream buyers. Stakeholders must monitor EFSA opinion timelines for pending preservative reclassifications and calibrate R&D allocation between synthetic efficiency and fermentation-derived natural alternatives before regulatory windows narrow.
Market Dynamics
ANSES additive re-evaluations under revised EFSA guidance are forcing French processors to accelerate reformulation cycles, compressing product development timelines and elevating R&D allocation toward fermentation-derived alternatives before regulatory windows narrow.
Growth Catalysts
- Paris-Île-de-France Processing Corridor:Concentrated bakery and dairy manufacturing clusters generate localized demand density for clean-label preservation systems, reducing logistics friction for ingredient suppliers.
- EU Green Deal Chemical Sustainability Framework:Bio-based substitution pathways receive preferential registration treatment, incentivizing processors to pivot from petroleum-derived synthetics toward fermentation-derived acidulants.
- Clean-Label Procurement Mandates:French retail chains enforce vinegar-derived and citric acid specifications, pulling reformulation investment into acidulant category expansion.
Market Restraints
- EDTA Substitution Pressure:Consumer advocacy groups target chelating agents in beverage stabilization, creating technical performance gaps that natural alternatives struggle to fill at equivalent cost points.
- EFSA Re-Evaluation Friction:Pending scientific opinions on benzoates and sorbates trigger anticipatory formulation redesign costs before final determinations, straining mid-cap processor budgets.
- Feedstock Volatility:Fermentation-derived natural preservatives depend on agricultural carbohydrate supply chains exposed to climate-driven yield fluctuations.
Strategic Opportunities
- Occitanie Wine Vinegar Acidulant Expansion:Proximity to grape processing waste streams enables vertical integration into acetic acid feedstocks for regional bakery applications.
- CSRD Chemical Footprint Transparency:Supply chain disclosure obligations create service-layer revenue for ingredient suppliers offering lifecycle documentation packages to downstream buyers.
- Modular Dosing System Adoption:Unbundled single-function ingredients enable processors to customize shelf-life solutions without locked antioxidant-acidulant bundle commitments.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial microbiology and bioprocess engineering expertise concentrates in pharmaceutical sectors, constraining food-grade natural preservative production expansion.
- Legacy Synthetic Inventory Stranding:Reformulation timelines compress faster than existing benzoate and sorbate stock depreciation schedules, forcing write-down decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Preservatives Market |
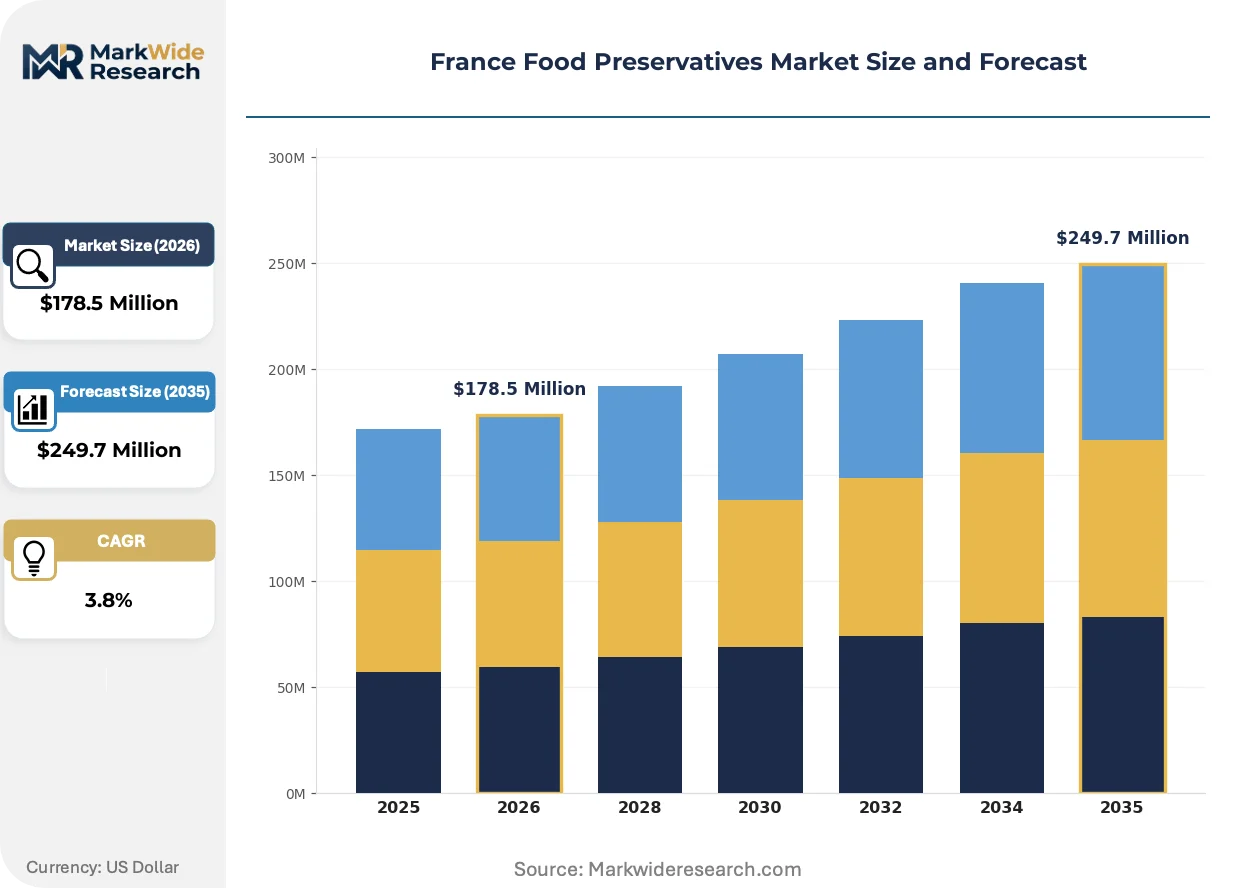
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $249.7 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Preservative Type: Antioxidants, Antimicrobials, Chelating Agents, Acidulants, Enzymes Food Application: Bakery, Confectionery, Dairy Products, Beverages, Snacks Packaging Type: Glass Bottles, Plastic Containers, Metal Cans, Flexible Pouches, Cartons End User Category: Food Processing Companies, Catering Services, Specialty Stores, Food Distributors |
| Companies Covered | Koninklijke DSM N.V, Barentz International B.V, DuPont de Nemours, Inc., Cargill, Kerry Group, Corbion NV, Ter Hell & Co. Gmbh, Jungbunzlauer AG, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Preservatives Market Shifts & Advancements
Bioprocessing advances and regulatory disclosure mandates are restructuring how French food manufacturers configure preservation architectures, shifting competitive advantage from chemical efficiency to supply chain transparency credentials.
Precision fermentation for lactic acid derivatives is decentralizing antimicrobial production away from centralized petrochemical facilities toward distributed bioreactor networks. Artisan dairy processors in Brittany and Normandy are adopting small-batch fermentation capacity to generate on-site preservative precursors. This distributed manufacturing model compresses transport emissions and enables batch-level traceability for clean-label claims.
EFSA scientific opinion timelines for pending preservative reclassifications are compressing formulation planning horizons across French bakery and dairy sectors. Processors must commit R&D resources to alternative pathways before final determinations, creating anticipatory compliance expenditure. The chilled dairy segment faces the steepest redesign pressure given sorbate dependency in current formulations.
Retail chain procurement departments are unbundling shelf-life guarantees from bundled ingredient supply agreements, demanding discrete performance accountability for each functional additive category. Hypermarket buyers in the Île-de-France region now specify minimum natural-derived content thresholds separate from overall preservation efficacy requirements. This specification fragmentation elevates supplier technical service intensity and rewards formulation flexibility over commodity scale.
France Food Preservatives Market Segmentation
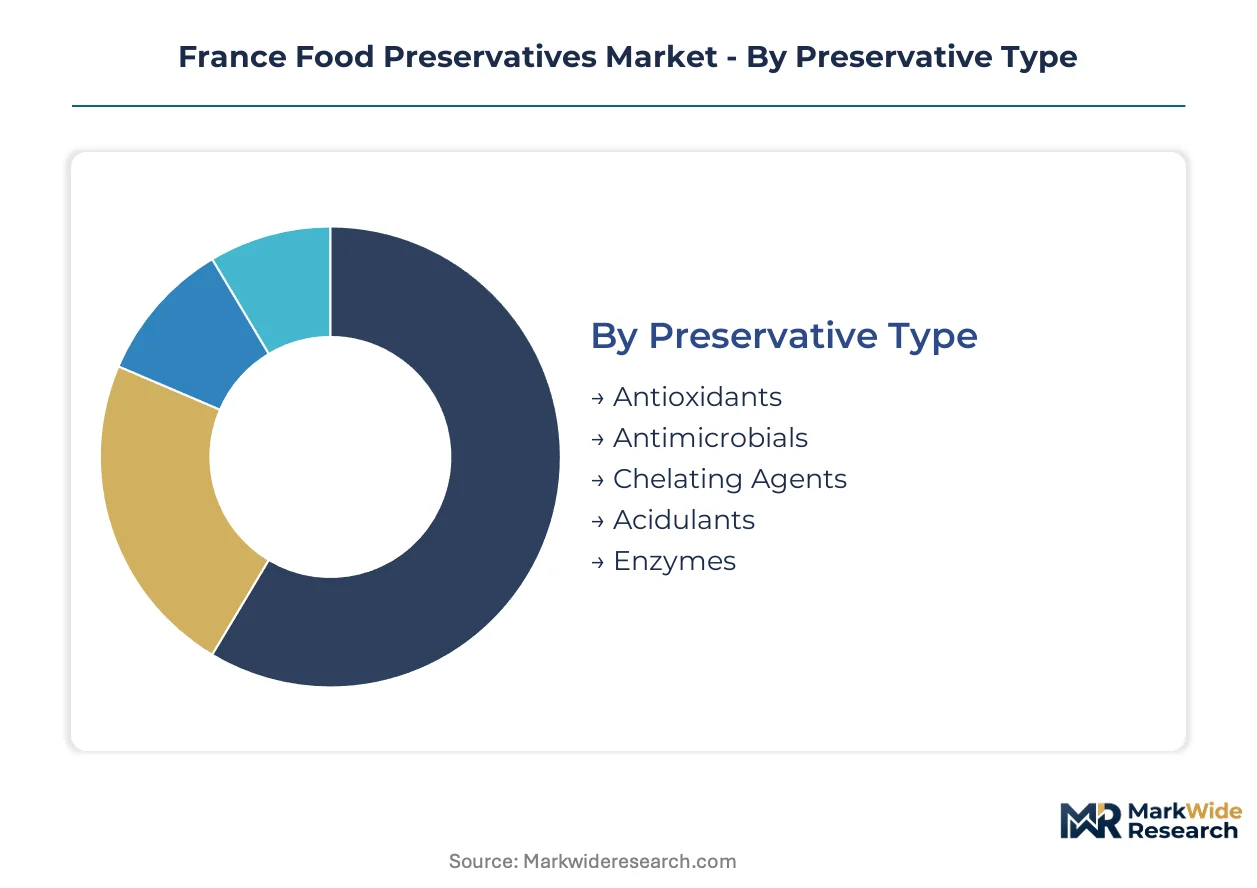
Preservative configuration in France varies sharply by integration depth. Standalone acidulants and antimicrobials dominate reformulation activity, while embedded antioxidant-acidulant bundles face unbundling pressure from retail procurement mandates.
Preservative Type:
Integration depth splits this category: antimicrobials and acidulants increasingly deploy as discrete functional ingredients, whereas antioxidants and chelating agents still circulate predominantly within bundled systems.
- Antimicrobials:These compounds inhibit bacterial and fungal proliferation through pH reduction or membrane disruption. Sorbates and benzoates face ANSES re-evaluation pressure, forcing Paris-Île-de-France dairy processors toward fermentation-derived alternatives like nisin and natamycin before regulatory windows narrow.
- Acidulants:Vinegar-derived acetic acid and citric acid systems serve as the primary clean-label replacement pathway for synthetic preservatives. Brittany and Normandy artisan producers leverage regional fermentation capacity to generate on-site acidulant precursors, compressing transport emissions while satisfying retail chain procurement thresholds.
- Antioxidants:Synthetic variants (BHA, BHT, TBHQ) and natural extracts (tocopherols, rosemary) prevent lipid oxidation in ambient packaged foods.
- Chelating Agents:EDTA dominates beverage stabilization despite consumer advocacy substitution pressure; natural alternatives struggle to match metal-ion sequestration efficiency at equivalent cost points.
- Enzymes:Glucose oxidase and lysozyme provide targeted antimicrobial action in specialized bakery and dairy applications with minimal label impact.
Volume placements concentrate in antimicrobials; the faster expansion belongs to acidulants.
Food Application:
Application segmentation tracks spoilage risk intensity and clean-label reformulation urgency, with chilled matrices commanding more preservative diversity than ambient-stable categories.
- Dairy Products:Yogurt, fresh cheese, and UHT milk formulations depend heavily on sorbate and natamycin combinations to suppress mold and yeast during extended cold-chain distribution. Reformulation costs bite hardest here given current sorbate dependency and EFSA re-evaluation uncertainty.
- Bakery:Bread and viennoiserie applications drive calcium propionate and cultured wheat vinegar demand, with Île-de-France industrial bakers specifying modular acidulant systems that unbundle traditional antioxidant-acidulant blends.
- Beverages:Fruit juices and soft drinks rely on benzoate-sorbate combinations and ascorbic acid for microbial and oxidative stability; EDTA substitution pressure is most acute in this segment.
- Confectionery:Chocolate and sugar-based products require minimal preservation due to low water activity, limiting additive penetration to fat-based antioxidant protection.
- Snacks:Savory extruded and fried products utilize tocopherol and rosemary extract systems to extend shelf life without synthetic antioxidant labeling.
Revenue gravity centers on dairy; reformulation velocity peaks in bakery.
Packaging Type:
Barrier properties determine preservative dosing intensity: high-oxygen-transmission formats demand more aggressive chemical protection, while modified-atmosphere and aseptic packaging enable preservative reduction.
- Flexible Pouches:Multilayer films with ethylene-vinyl alcohol barriers dominate ambient soup, sauce, and ready-meal applications where oxygen scavenging complements chemical preservation.
- Plastic Containers:Polyethylene terephthalate and high-density polyethylene bottles serve beverage and dairy segments with intermediate barrier performance, requiring acidulant and antimicrobial reinforcement.
- Metal Cans:Aseptic and retort canning provides intrinsic microbial lethality, reducing preservative dependence to antioxidant stabilization of lipid-rich contents.
- Glass Bottles:Premium positioning in sauces and beverages leverages inert material properties with minimal additive requirements.
- Cartons:Liquid packaging board with aluminum foil layers supports extended shelf life in UHT dairy and juice applications.
Preservative loading runs highest in flexible pouches; clean-label compatibility is strongest in glass and cartons.
End User Category:
Procurement sophistication varies by scale: industrial processors negotiate modular ingredient specifications, while smaller operators accept bundled supply agreements with limited formulation control.
- Food Processing Companies:Industrial bakeries and dairies in the Paris-Île-de-France corridor deploy dedicated R&D teams to configure preservative architectures around specific shelf-life targets and retail chain mandates.
- Food Distributors:Private-label suppliers face compressed reformulation timelines as retail procurement departments unbundle shelf-life guarantees from bundled ingredient agreements.
- Catering Services:Central kitchen operations prioritize cost-minimized preservation for high-volume prepared meals with short distribution cycles.
- Specialty Stores:Artisan producers in Occitanie and Provence-Alpes-Côte d'Azur emphasize natural-derived claims, accepting shorter shelf-life trade-offs for label transparency.
Formulation control concentrates in food processing companies; specialty stores drive natural-derived substitution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces preservatives at industrial scale yet concentrates consumption in its northern processing belt, creating a domestic supply-demand imbalance that shapes logistics networks and regional specialization patterns across the country.
Île-de-France
Paris anchors the densest food manufacturing corridor in France, with industrial bakeries and dairy processors driving acidulant and antimicrobial procurement volumes. ANSES headquarters proximity accelerates regulatory response cycles for reformulation mandates. The region's R&D facilities cluster around Saclay and Genopole, where fermentation-derived preservative startups secure pilot-scale capacity.
Auvergne-Rhône-Alpes
Lyon's chemical engineering heritage supports specialty acidulant production for clean-label applications, leveraging pharmaceutical-sector bioprocess expertise. The EU Green Deal chemical sustainability framework channels bio-based substitution investment into regional fermentation infrastructure. Saint-Étienne hosts contract manufacturing facilities that serve mid-cap processors seeking modular preservative dosing systems.
Occitanie
Proximity to Languedoc wine production generates acetic acid feedstock streams for vinegar-derived preservation systems. Regional artisan bakeries source localized acidulant supplies to satisfy retail chain natural-derived thresholds. Toulouse biotechnology institutes supply fermentation talent to food-grade preservative scale-up operations.
Provence-Alpes-Côte d'Azur
Specialty food producers in Nice and Marseille prioritize label transparency over extended shelf life, accepting shorter distribution radii for natural-claim positioning. The region's olive oil processing waste streams enable phenolic antioxidant extraction for niche applications. Aix-en-Provence hosts formulation service providers that configure clean-label architectures for export-oriented processors.
Brittany and Normandy
Dairy concentration in these western regions generates concentrated demand for natamycin and nisin in fresh cheese applications. Artisan producers deploy small-batch fermentation capacity for on-site preservative precursor generation. Rennes agri-food research clusters support distributed manufacturing models that compress transport emissions.
France Food Preservatives Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with fermentation expertise and synthetic chemical scale. Market participation splits between multinational suppliers offering integrated preservation platforms and regional specialists commanding vertical relationships with artisan processors. Strategic archetypes include fermentation-derived natural specialists, petrochemical-scale synthetic producers, and taste-preservation integrators. Capacity expansion and portfolio diversification toward clean-label alternatives dominate competitive maneuvering as regulatory windows narrow.
Among Netherlands-based ingredient conglomerates, Koninklijke DSM N.V. and Corbion NV exemplify the fermentation-specialist archetype with lactic acid and derivative positioning. Kerry Group occupies the integrated taste-preservation tier, while BASF SE anchors synthetic antioxidant supply through commodity-scale manufacturing discipline. German chemical conglomerates including Jungbunzlauer AG and Ter Hell & Co. GmbH sit within the acidulant and distribution intermediary segments respectively.
| Leading Market Players |
|---|
| Koninklijke DSM N.V |
| Barentz International B.V |
| DuPont de Nemours, Inc. |
| Cargill |
| Kerry Group |
| Corbion NV |
| Ter Hell & Co. Gmbh |
| Jungbunzlauer AG |
| BASF SE |
| Others |
Supply & Pricing Matrix
Industrial microbiology talent concentration in the Paris-Saclay biotech corridor feeds labor-cost differentials into pricing-tier spreads, with fermentation-derived preservative specialists commanding premium positioning against commodity synthetic suppliers.
Pricing Analysis
Cost-down pressure on mid-tier processors accelerates because EFSA re-evaluation uncertainty compresses reformulation timelines before regulatory windows narrow. Pricing stratifies across fermentation-derived premium tiers, synthetic standard tiers, and economy commodity spot markets. Price differentiation hinges on clean-label certification grade and volume scale commitments from Île-de-France industrial bakers. Small artisan producers in Brittany and Normandy exhibit highest price sensitivity; large dairy conglomerates anchored to long-term supply agreements show lowest sensitivity.
Supply Chain Analysis
Reverse-logistics flows for spent fermentation media and acidulant byproduct streams create circular feedstock circuits from Occitanie wine processing waste into Brittany bakery applications. Supply concentrates in France, Netherlands, and Germany for fermentation-derived inputs, with petrochemical synthetics sourcing from Belgium and German chemical complexes. Raw material dependencies include agricultural carbohydrate feedstocks, acetic acid precursors, and lactic acid cultures. Single-source vulnerability concentrates in pharmaceutical-grade fermentation capacity. Distribution runs through regional ingredient distributors serving the Paris-Île-de-France processing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANSES additive authorization reviews under revised EFSA guidance erect a compliance moat that rewards early-mover investment in fermentation-derived alternatives, stranding non-compliant synthetic inventory and elevating compliant players to premium pricing tiers.
For Market Incumbents: Lock in backward integration into Occitanie wine vinegar feedstocks to secure acetic acid supply against agricultural yield volatility. Expand pilot-scale bioreactor capacity at Saclay R&D clusters before fermentation talent scarcity worsens. Defend against modular dosing disruption by unbundling proprietary antioxidant-acidulant blends into discrete single-function ingredients with separate performance guarantees. For New Entrants and Emerging Players: The premium-to-economy price-point gap in clean-label acidulants offers white-space entry for regional fermentation startups serving Occitanie and Provence-Alpes-Côte d'Azur artisan bakeries. Target CSRD chemical footprint transparency services as the most penetrable segment, with lifecycle documentation packages for mid-cap processors lacking in-house compliance teams. Pursue joint development agreements with Brittany dairy cooperatives for on-site natamycin precursor generation. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-specialist mid-caps given EU Green Deal preferential registration treatment for bio-based substitution pathways. Long-term viability favors players with captive carbohydrate supply chains and pharmaceutical-sector bioprocess engineering transfer capabilities. Monitor EFSA scientific opinion publication timelines for benzoate and sorbate reclassifications as the critical inflection signal for synthetic inventory stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Builds bio-based acidulant supply security ahead of REACH registration deadlines under EU Green Deal frameworks. |
| Modular Dosing System Launch | Unbundles traditional antioxidant-acidulant blends to capture Île-de-France industrial bakery procurement mandates. |
| CSRD Documentation Service Layer | Captures recurring revenue from mid-cap processors facing supply chain chemical footprint disclosure obligations. |
| Regional Feedstock Integration | Secures Occitanie wine vinegar waste streams for vertical acetic acid control in clean-label bakery applications. |
| Pharmaceutical Talent Recruitment | Addresses industrial microbiology scarcity constraining food-grade natural preservative production scale-up. |
Research Methodology
Document review covered ANSES additive authorization databases, EFSA scientific opinion archives, and EU REACH registration filings, complemented by interviews with fermentation R&D directors at Paris-Saclay biotech clusters, procurement leads at Île-de-France industrial bakeries, regulatory affairs managers navigating CSRD disclosure obligations, and specialty acidulant distributors serving Occitanie artisan producers. Secondary validation drew from customs trade data, SEC 10-K filings of listed ingredient suppliers, and Cefic chemical industry reports. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Segment-level projections across preservative type, food application, packaging format, and end-user category fed into analytical framework outputs over the projection horizon. CAGRs derived from regression against historical reformulation investment cycles and regulatory timeline acceleration patterns. Industry-specific forecast inputs included EFSA re-evaluation schedule assumptions and retail chain clean-label procurement threshold adoption curves.
Inputs from ANSES and EFSA documentation were available through the study window; gaps in real-time processor inventory stranding data introduce uncertainty bands around synthetic-to-natural substitution velocity assumptions. Forecasts reflect documented regulatory timelines and disclosed corporate R&D allocation patterns. Practitioners should monitor EFSA opinion publication schedules and retail chain procurement specification releases for early signals of reformulation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market