
 United States Vitamin D Supplements Market | 2026-2036
United States Vitamin D Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
United States Vitamin D Supplements Market Analytics
Pharmaceutical-grade D3 potency certification is redrawing competitive boundaries in the United States Vitamin D Supplements Market. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital and pharmacy channels with prescription-adjacent positioning. Nestlé S.A. sustains mass-market dominance through backward integration into softgel manufacturing and private-label partnerships. Pfizer Inc. differentiates via pharmaceutical-grade quality signaling that commands shelf space in CVS and Walgreens.
United States Vitamin D Supplements comprise cholecalciferol (D3) and ergocalciferol (D2) compounds formulated in oil-based or dry powder matrices, typically standardized to potency claims measured in International Units and verified through USP dissolution testing for intestinal absorption performance. Softgel capsules lead product-type revenue pools due to superior bioavailability and consumer compliance, while liquid formats capture pediatric and senior segments where swallowing difficulties constrain tablet uptake. Online distribution channels register the fastest structural expansion as subscription models and telehealth referrals bypass traditional retail gatekeepers.
FDA cGMP enforcement and USP verification programs shape product quality thresholds, while FTC advertising scrutiny constrains unsubstantiated health claims that had previously inflated demand. The National Institutes of Health Office of Dietary Supplements coordinates federal research priorities that indirectly steer manufacturer R&D portfolios toward deficiency-prevention messaging. Stakeholders must monitor evolving FDA guidance on structure-function claims and state-level licensure requirements for compounded vitamin formulations.
Market Dynamics
FDA's New Dietary Ingredient notification requirements are compressing new entrant pipelines while concentrating market power among incumbent manufacturers with established compliance infrastructure. This regulatory tightening intersects with aging demographics to reshape competitive boundaries around clinical credibility.
Growth Catalysts
- Senior Demographic Expansion:Aging baby boomers in Florida and Arizona are prioritizing bone-density maintenance, expanding the addressable population for high-potency D3 formulations.
- USP Verification Programs:Third-party quality certification is elevating consumer trust thresholds and rewarding manufacturers with pharmaceutical-grade testing capabilities.
- Telehealth Integration:Remote physician consultations in the Northeast corridor are normalizing prescription-adjacent supplement recommendations that bypass retail gatekeepers.
Market Restraints
- Lanolin Supply Concentration:Australian and New Zealand sheep wool derivative sourcing creates input vulnerability for D3 manufacturers dependent on natural cholecalciferol.
- FTC Advertising Scrutiny:Unsubstantiated immune-health claims enforcement is constraining marketing vocabulary that previously inflated demand.
- Plant-Based D2 Efficacy Gap:Ergocalciferol's inferior bioavailability limits substitution potential for vegan-positioned products in performance-sensitive segments.
Strategic Opportunities
- Pediatric Liquid Formats:Underpenetrated swallowing-difficulty segments in Texas and California offer volume expansion beyond traditional softgel dominance.
- Subscription Direct-to-Consumer:Amazon and specialized health platforms enable recurring revenue models that reduce customer acquisition costs.
- Compounding Pharmacy Partnerships:State-level licensure for customized vitamin formulations creates service differentiation in functional medicine channels.
Industry Challenges
- cGMP Compliance Talent Scarcity:Quality assurance professionals with FDA audit experience command premium compensation that strains mid-tier manufacturer margins.
- Structure-Function Claim Documentation:Evolving FDA guidance on permissible health messaging requires continuous legal review and label revision cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Vitamin D Supplements Market |
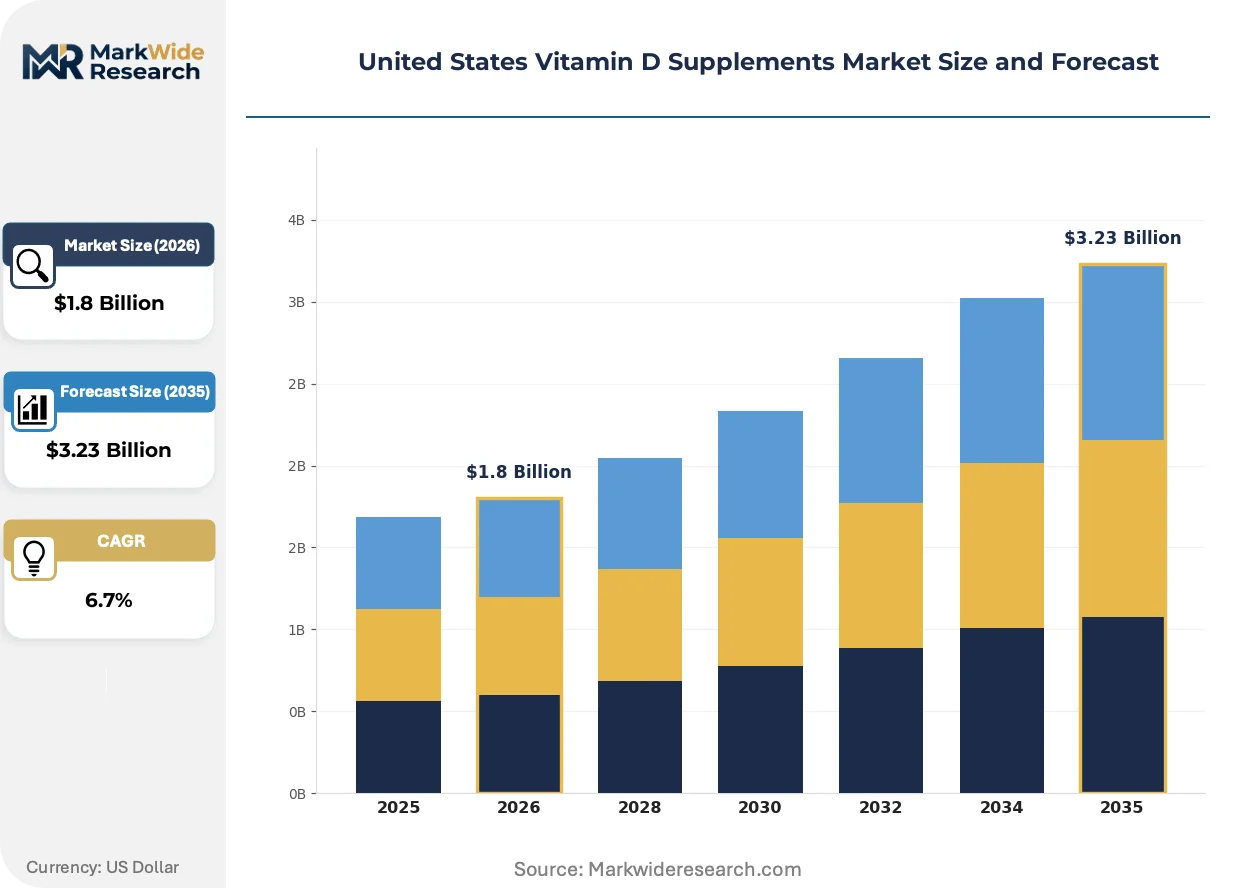
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Liquid, Powder End User: Adults, Seniors, Children, Athletes Distribution Channel: Retail Stores, Online, Pharmacies, Health Food Stores Formulation: Natural, Synthetic, Organic, Fortified |
| Companies Covered | Haleon PLC, Nestlé S.A., Pfizer Inc., GlaxoSmithKline plc, Abbott Laboratories, Amway Corporation, The Procter & Gamble Company, Nature Made, Solgar Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Vitamin D Supplements Market Evolving Landscape
Liposomal delivery technologies and precision-dosing formats are redrawing bioavailability benchmarks. Manufacturers now compete on absorption metrics rather than potency claims alone.
Nanoemulsion vitamin D3 suspensions are achieving lymphatic absorption pathways that bypass hepatic first-pass metabolism. Functional medicine practitioners in California are adopting these formats for deficiency-correction protocols. This delivery innovation is displacing traditional oil-based softgels in premium positioning.
FDA's draft guidance on substantiation for structure-function claims is tightening evidentiary requirements for immune-support messaging. Manufacturers must now maintain clinical trial documentation that withstands FTC challenge. The dietary supplement industry is responding by shifting marketing emphasis toward bone-health claims with established scientific consensus.
Telehealth-referred subscription models are consolidating purchase decisions away from retail shelf browsing. Consumers in the Northeast corridor now initiate supplement regimens through physician-adjacent digital platforms. This channel migration is most pronounced among seniors managing polypharmacy who value professional guidance over self-directed selection.
United States Vitamin D Supplements Market Segmentation
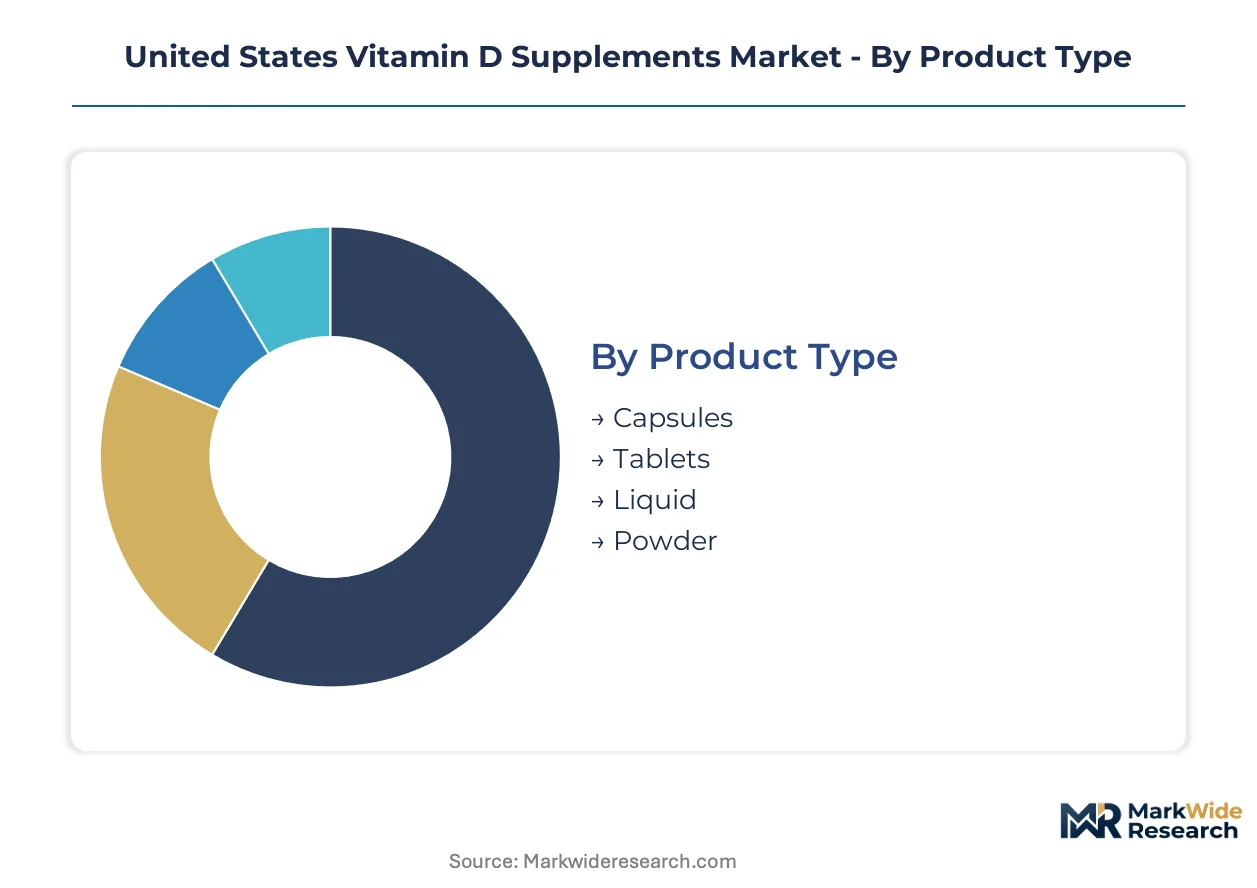
Segmentation in the United States Vitamin D Supplements Market reveals how formulation chemistry, delivery mechanics, and channel access determine competitive positioning. Substitution threats vary dramatically across categories, with some segments facing direct functional competition from fortified foods while others defend through bioavailability advantages.
Product Type:
Substitution pressure concentrates in solid oral formats where functional foods and beverages encroach on convenience positioning, while liquid and powder segments defend through dosing precision and swallowing-difficulty applications.
- Capsules:Softgel and hard-shell gelatin capsules encapsulate oil-based cholecalciferol suspensions with superior intestinal dissolution profiles validated through USP testing. Demand clusters in California and the Northeast corridor where pharmacy and health food channels emphasize quality verification.
- Tablets:Compressed dry powder matrices bind D2 or D3 with excipients for cost-efficient manufacturing, though inferior dissolution kinetics limit bioavailability in deficiency-correction protocols. Seniors in Florida and Arizona drive volume through Medicare-adjacent purchasing patterns.
- Liquid:Nanoemulsion and oil-drop formats enable precise titration for pediatric populations and polypharmacy patients with dysphagia.
- Powder:Bulk D3 isolates serve compounding pharmacies and functional medicine practitioners requiring customized dosing protocols.
Capsules retain volume leadership; liquid holds the steepest expansion curve.
End User:
Cost tier stratification separates premium clinical-positioned products from mass-market formulations, with reimbursement-adjacent channels capturing margin concentration.
- Adults:Working-age consumers aged 18-64 purchase primarily through self-directed retail and online channels, with demand driven by workplace wellness programs and preventive health consciousness in urban corridors.
- Seniors:Medicare-eligible populations prioritize bone-density maintenance and polypharmacy management, creating prescription-adjacent purchasing through telehealth referrals and pharmacy consultations. FDA cGMP verification commands premium tolerance in this cohort.
- Children:Pediatric dosing requirements and parental safety concerns concentrate demand in liquid formats with third-party purity certification.
- Athletes:Performance-oriented consumers seek rapid-absorption formats for muscle function and recovery protocols.
Seniors dominate value capture; athletes show the sharpest growth acceleration.
Distribution Channel:
Volume concentration in traditional retail faces structural pressure as telehealth integration and subscription mechanics disintermediate shelf-based discovery.
- Retail Stores:Mass merchandisers and grocery chains capture impulse purchases through prominent placement, though FTC advertising scrutiny constrains health claim differentiation at point-of-sale.
- Online:Amazon and specialized health platforms enable subscription models that reduce customer acquisition costs while telehealth referrals bypass traditional gatekeepers. The Northeast corridor shows highest penetration of physician-adjacent digital purchasing.
- Pharmacies:CVS and Walgreens leverage pharmacist consultation to anchor prescription-adjacent positioning with USP-verified products.
- Health Food Stores:Regional chains and independents serve organic and natural-positioned segments with educated staff consultation.
Retail stores maintain transaction volume leadership; online channels expand most quickly.
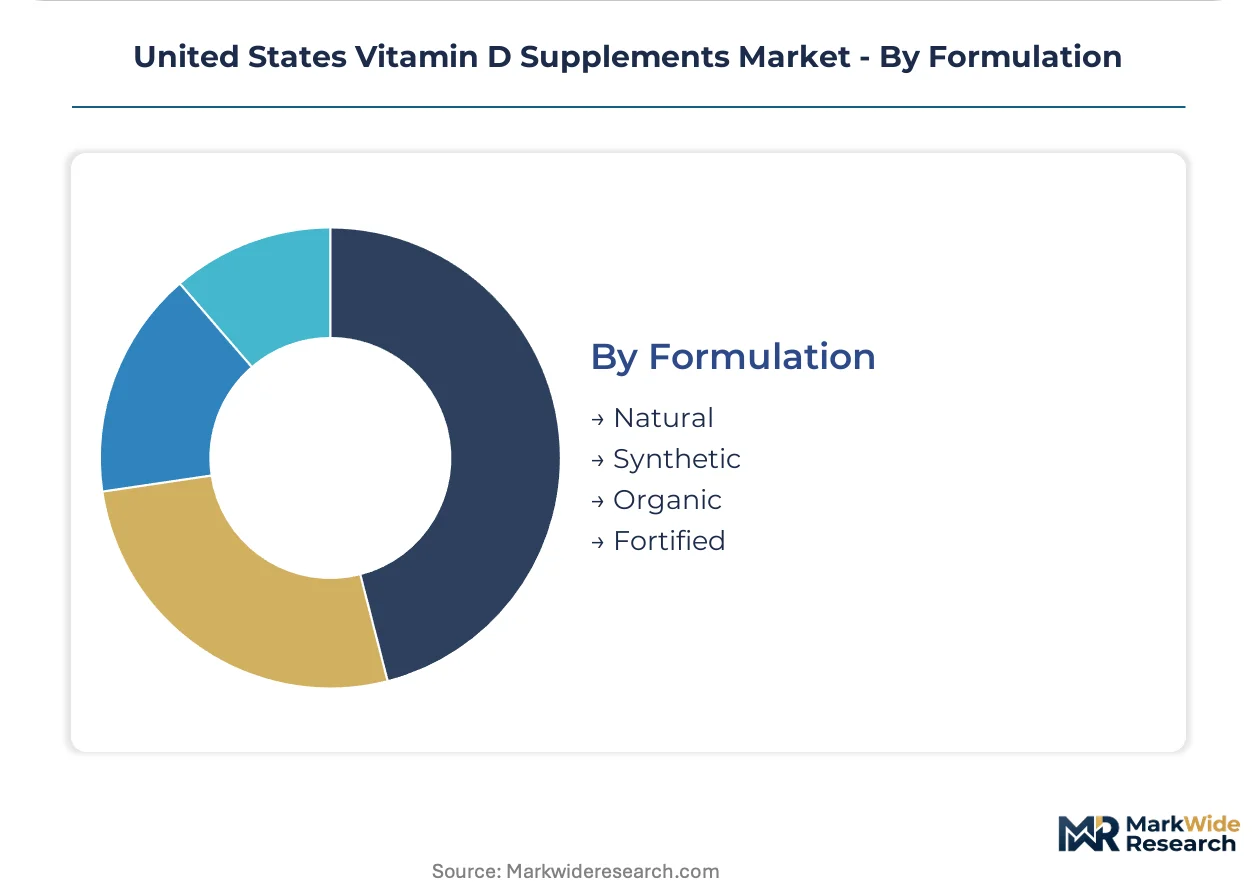
Formulation:
Supply concentration in natural D3 sourcing from Australian and New Zealand lanolin creates input vulnerability, while synthetic alternatives defend through price stability and vegan positioning.
- Natural:Lanolin-derived cholecalciferol commands premium positioning through perceived purity and bioavailability advantages, though supply chain concentration creates procurement risk.
- Synthetic:Laboratory-manufactured D3 and D2 compounds offer batch consistency and price predictability that appeals to institutional purchasers and cost-sensitive segments.
- Organic:Certified organic positioning captures health-conscious consumers in California and Pacific Northwest markets with strict input traceability requirements.
- Fortified:Pre-blended D3 in carrier oils or protein matrices serves functional food and beverage manufacturers seeking ingredient integration.
Natural formulations retain margin leadership; synthetic alternatives gain share fastest through price accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lanolin-derived D3 raw material concentrates in Australian and New Zealand sheep wool processing clusters, creating procurement bottlenecks for US manufacturers. Demand geography within the United States fragments across coastal health-conscious corridors and Sun Belt retirement destinations.
California
Preventive health consciousness and high disposable incomes drive premium D3 formulation demand in the San Francisco Bay Area and Los Angeles metro. FDA cGMP enforcement patterns here are stricter than national baselines, elevating compliance costs for entrants. Functional medicine practitioners in San Diego and Palo Alto are adopting nanoemulsion delivery formats for deficiency-correction protocols.
Northeast Corridor
Telehealth-referred subscription purchasing concentrates in Boston, New York, and Philadelphia metros where physician-adjacent digital platforms bypass retail gatekeepers. FTC advertising scrutiny operates with higher litigation risk in this jurisdiction, constraining immune-health claim vocabulary. Pharmacy consultation channels at CVS and Walgreens anchor prescription-adjacent positioning with USP-verified products.
Florida
Aging baby boomers prioritize bone-density maintenance, expanding addressable population for high-potency D3 formulations in Miami, Tampa, and Orlando metros. Medicare-adjacent purchasing patterns dominate, with seniors showing premium tolerance for FDA cGMP verification. Retail pharmacy chains capture volume through pharmacist consultation services.
Texas
Pediatric liquid format demand remains underpenetrated in Dallas-Fort Worth and Houston metros where swallowing-difficulty segments offer expansion beyond traditional softgel dominance. State-level compounding pharmacy licensure creates service differentiation opportunities in functional medicine channels. Direct-to-consumer subscription models via Amazon show accelerating penetration.
Arizona
Senior demographic expansion in Phoenix and Tucson metros mirrors Florida's retirement-driven demand profile. Sun Belt migration patterns concentrate Medicare-eligible populations seeking polypharmacy management solutions. Telehealth integration lags coastal corridors but shows fastest adoption velocity among rural seniors.
United States Vitamin D Supplements Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with pharmaceutical-grade testing capabilities separating premium positioning from mass-market penetration. The market exhibits tiered concentration around incumbent manufacturers with established FDA compliance infrastructure and private-label specialists serving retail channels. Three archetypes dominate: clinical-nutrition heritage players anchoring hospital and pharmacy channels, mass-market consumer health giants leveraging backward integration into softgel manufacturing, and specialized dietary supplement firms competing on third-party purity certification. Competitive moves concentrate on USP verification program enrollment and telehealth platform partnerships that disintermediate traditional retail discovery.
Among clinical-nutrition heritage players, Abbott Laboratories anchors prescription-adjacent positioning through hospital and pharmacy channel dominance. Nestlé S.A. exemplifies mass-market scale advantages through softgel manufacturing integration and private-label partnerships. Pfizer Inc. occupies a position within pharmaceutical-grade quality signaling that commands shelf space in major retail pharmacy chains. These three entities represent distinct competitive vectors: clinical credibility, manufacturing scale, and pharmaceutical-grade certification respectively.
| Leading Market Players |
|---|
| Haleon PLC |
| Nestlé S.A. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Amway Corporation |
| The Procter & Gamble Company |
| Nature Made |
| Solgar Inc. |
| Others |
Value Network & Pricing Analysis
Softgel manufacturing scale economies in Wisconsin and New Jersey shape both supply concentration and price floors for US vitamin D3 producers, as captive production capacity insulates incumbents from raw material volatility while forcing contract manufacturers into margin compression.
Pricing Analysis
FDA cGMP enforcement dictates the pricing tier structure across the United States Vitamin D Supplements Market. USP-verified pharmaceutical-grade products command premium positioning at CVS and Walgreens, while private-label formulations compete on volume scale through mass merchandisers. Price differentiation hinges on certification grade and channel control, with telehealth-referred subscription models reducing price sensitivity among seniors managing polypharmacy. Cost compression in economy-tier tablets is intensifying because excipient suppliers pass through input volatility.
Supply Chain Analysis
Strategic stockpiling of lanolin-derived cholecalciferol prevails among large manufacturers, while mid-tier players operate on just-in-time procurement exposed to Australian and New Zealand supply disruptions. Raw material sourcing draws from sheep wool processing clusters in Australia, New Zealand, and limited North American operations, with synthetic D3 alternatives anchored in Chinese and Indian chemical manufacturing. Single-source vulnerability concentrates in natural D3 extraction, where two suppliers dominate global lanolin derivative output. Distribution runs through pharmaceutical wholesalers McKesson and AmerisourceBergen to retail pharmacy chains, with direct-to-consumer platforms bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as telehealth integration disintermediates retail gatekeepers, creating niche openings for specialized formulations targeting swallowing-difficulty segments and precision-dosing protocols.
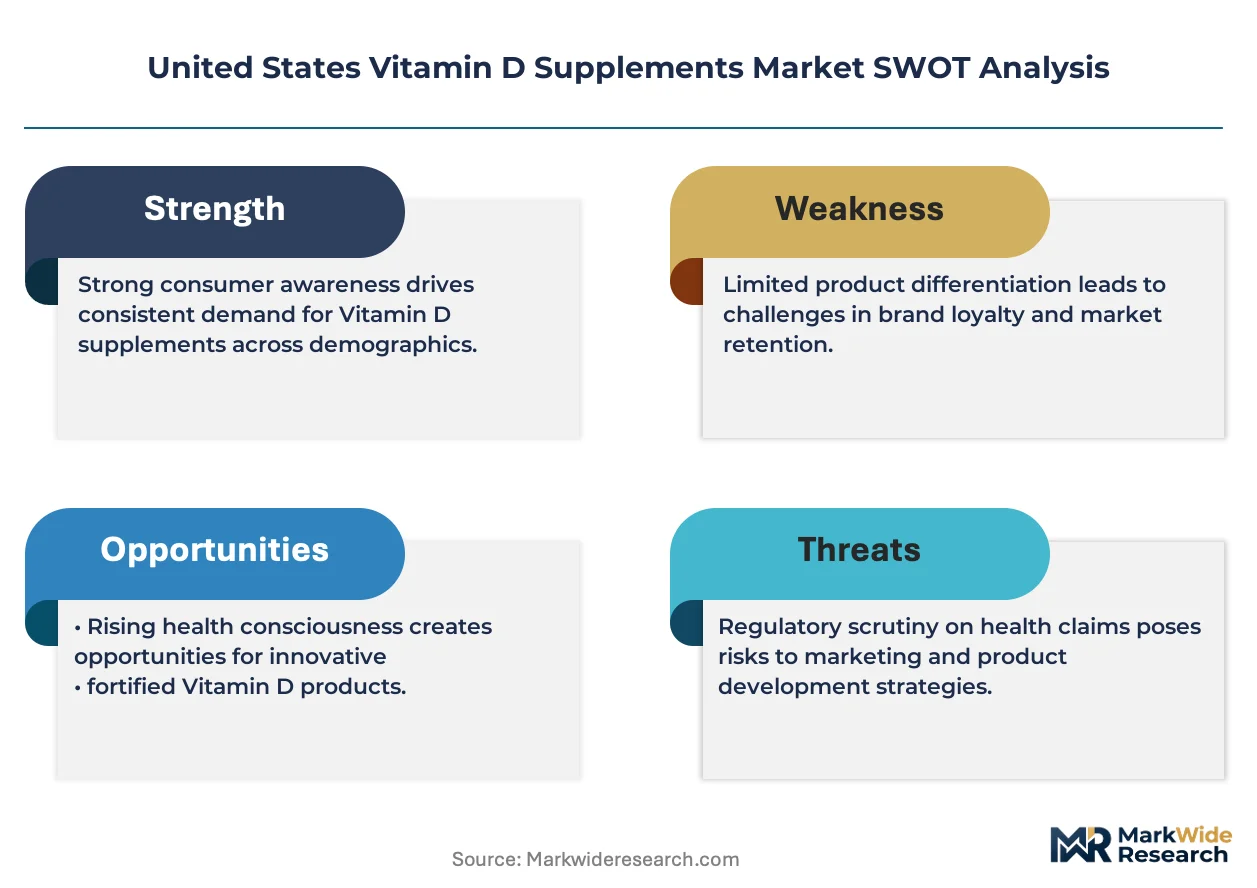
For Market Incumbents: Compound advantage through backward integration into nanoemulsion manufacturing and exclusive telehealth platform partnerships. Lock in lanolin supply through long-term offtake agreements with Australian processors before synthetic alternatives erode natural D3 premium positioning. Defend pharmacy channel shelf space by accelerating USP verification enrollment ahead of FDA guidance tightening. For New Entrants and Emerging Players: Lead with pediatric liquid formats in Texas and California metros where swallowing-difficulty segments remain underpenetrated by incumbent softgel dominance. Target compounding pharmacy partnerships in states with functional medicine licensure expansion, bypassing mass retail gatekeepers entirely. Anchor go-to-market through Amazon subscription mechanics with physician-adjacent digital referrals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors delivery-format specialists with liposomal and nanoemulsion capabilities over commodity softgel manufacturers. Five-to-ten year viability hinges on absorption-technology differentiation rather than potency competition. Monitor FDA structure-function claim enforcement intensity as the inflection signal; stricter evidentiary requirements will accelerate consolidation around clinical-trial-capable players.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Program Enrollment | Third-party certification commands shelf space at CVS and Walgreens amid FTC scrutiny tightening. |
| Telehealth Platform Partnership | Physician-adjacent digital referrals bypass retail discovery and reduce customer acquisition costs. |
| Nanoemulsion Manufacturing Scale-Up | Lymphatic absorption pathways displace traditional oil-based softgels in premium California positioning. |
| Lanolin Supply Agreement | Long-term offtake contracts with Australian processors hedge against natural D3 input concentration risk. |
| Compounding Pharmacy Network Expansion | State-level functional medicine licensure creates service differentiation beyond mass-market formulations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs directors at supplement manufacturers, pharmacy chain category managers, compounding pharmacists, and functional medicine practitioners; and secondary validation through FDA cGMP inspection databases, USP verification program enrollment records, and telehealth platform partnership disclosures. Bottom-up demand modeling triangulated against top-down channel revenue estimates.
Across the projection horizon, the analytical framework segmented volume and value by formulation chemistry, delivery mechanics, end-user demographics, and distribution channel access. CAGRs derived from regression analysis of historical prescription-adjacent supplement adoption curves, Medicare eligibility expansion trajectories, and online channel penetration rates. Forecast inputs incorporated FDA enforcement intensity indices and lanolin supply concentration metrics.
The analysis sits within stated boundaries; outcomes outside sustained telehealth reimbursement alignment and stable Australian wool production would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement continuity and raw material supply chain integrity. Revision becomes warranted when FTC structure-function claim litigation crosses enforcement intensity thresholds or when synthetic D3 bioavailability equivalence achieves clinical consensus.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Global Soluble Dietary Fibers Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Milk Powder for Pregnant Women Market