
 Global Fatty Acids Market | 2026-2036
Global Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fatty Acids Market Foresight
Specialized oleochemical engineering talent is redrawing competitive boundaries across the fatty acids value chain. BASF SE leverages its integrated Ludwigshafen complex to sustain captive feedstock security for high-purity fatty acid derivatives. Wilmar International anchors its position through plantation-to-oleochemical verticality across Southeast Asian operations. Croda International Plc differentiates via biotechnology-led specialty ester production targeting pharmaceutical and personal care grades.
Fatty acids comprise carboxylic acids with aliphatic chains typically ranging from four to twenty-eight carbon atoms, derived through hydrolysis of triglycerides in vegetable oils or animal fats and valued for their surfactant, emulsification, and lubricity properties. Saturated fatty acids dominate volume throughput in commodity soap and detergent applications where cost efficiency governs procurement decisions. Specialty fatty acids command disproportionate margin pools within cosmetic and pharmaceutical channels where functional performance and certification standards outweigh raw material expense.
REACH registration requirements in Europe, EPA biofuel mandates in the United States, and FSSAI labeling directives in India collectively elevate compliance costs while steering formulation choices toward traceable, sustainably sourced inputs. ECHA substance evaluation protocols increasingly restrict certain palm-derived supply routes, compelling reformulation investments across personal care and coatings segments. Stakeholders must monitor evolving feedstock certification schemes and regional renewable chemical incentives to secure long-term supply positions.
Market Dynamics
Pharmaceutical lipid excipient demand is compressing supply chains toward high-purity certification tiers, forcing oleochemical processors to retool for GMP compliance and segregated handling infrastructure.
Growth Catalysts
- EU Green Deal bio-based mandates:Renewable chemical quotas in Europe redirect capital toward enzymatic esterification plants and waste-oil feedstock processing.
- India FSSAI labeling directives:Trans-fat disclosure rules accelerate palm oil replacement with structured lipid alternatives in packaged food manufacturing.
- Pharmaceutical nanolipid carriers:mRNA vaccine formulation protocols sustain demand for ultra-pure stearic and oleic acid derivatives.
Market Restraints
- Indonesia-Malaysia supply concentration:Over 80% of palm kernel oil feedstock originates from Southeast Asian plantations exposed to El Niño yield volatility.
- REACH registration cost escalation:ECHA substance evaluation fees for novel fatty acid esters exceed €100,000 per registration, blocking SME market entry.
- Petrochemical surfactant substitution:Synthetic alkylbenzene sulfonates retain cost advantage in commodity detergent applications below premium price thresholds.
Strategic Opportunities
- Brazil ANVISA pharmaceutical-grade certification:Latin America's largest generics market lacks domestic oleochemical GMP capacity, creating import substitution potential.
- Algae oil biotechnology convergence:Fermentation-derived EPA/DHA omega-3 fatty acids bypass marine fishery constraints for nutraceutical encapsulation.
- Japan METI carbon accounting standards:Scope 3 disclosure requirements favor regional suppliers with verified deforestation-free palm supply chains.
Industry Challenges
- Specialized oleochemical engineering scarcity:Fractional distillation and hydrogenation process expertise concentrates in Ludwigshafen, Rotterdam, and Singapore hubs.
- RSPO-IP certification timeline compression:Segregated supply chain audits require 18-24 months for personal care brand compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fatty Acids Market |
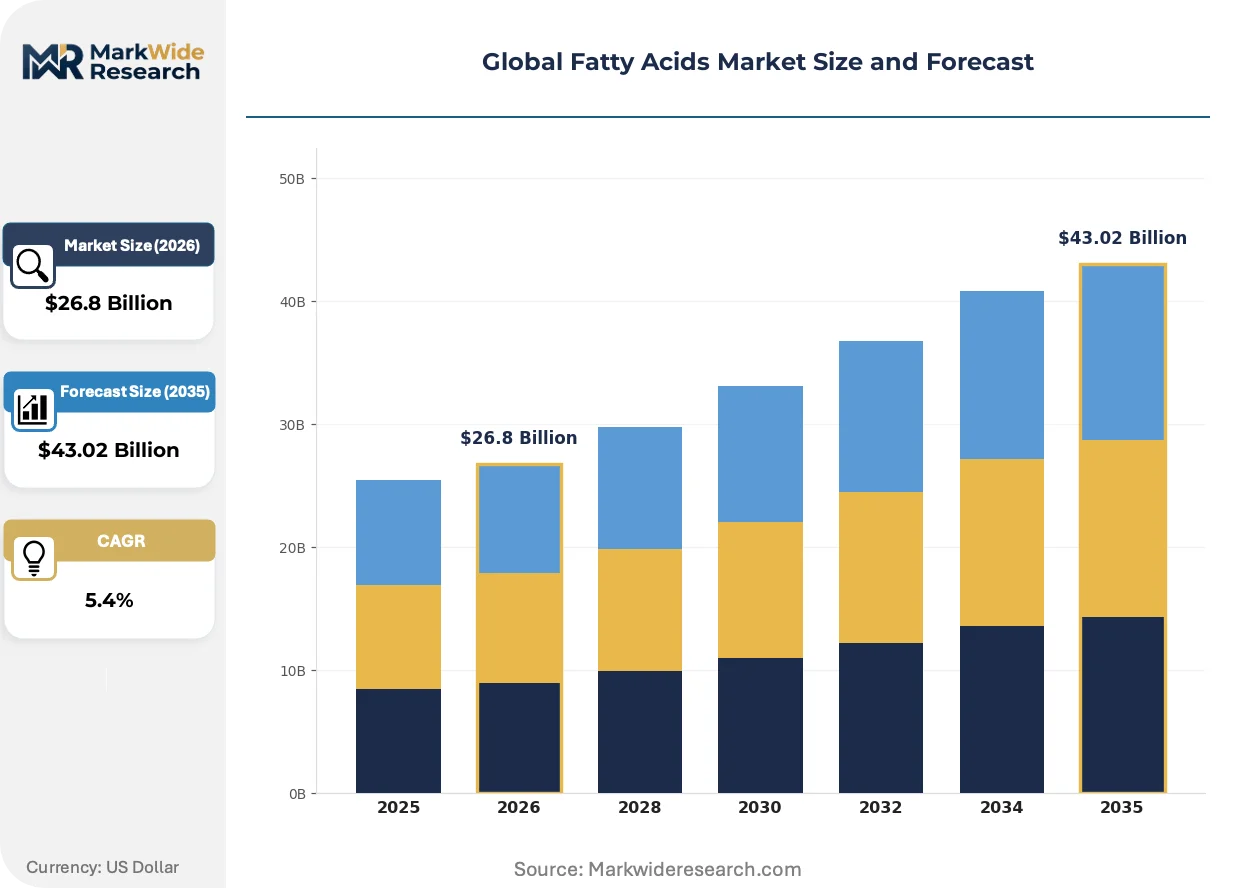
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saturated Fatty Acids, Unsaturated Fatty Acids, Trans Fatty Acids, Specialty Fatty Acids Application: Food & Beverage, Personal Care, Paints & Coatings, Lubricants Form: Liquid, Solid, Powder, Emulsified End User: Cosmetic Manufacturers, Chemical Processing Units, Pharmaceuticals, Animal Feed Producers |
| Companies Covered | BASF SE, VVF Ltd, Wilmar International Ltd, Croda International Plc, Godrej Industries, Musim Mas, Cargill Incorporated, DOW, KLK OLEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fatty Acids Market Shifts & Advancements
Biotechnology-enabled precision fermentation is disrupting traditional triglyceride hydrolysis, while regulatory carbon accounting forces supply chain visibility investments.
Enzymatic interesterification technology is miniaturizing. Small-batch biocatalytic reactors enable pharmaceutical contract manufacturers to produce site-specific lipid excipients without multi-tonne minimum orders. This compression of viable scale thresholds fragments volume concentration among integrated commodity processors.
ECHA REACH authorization protocols now restrict certain medium-chain chlorinated paraffin applications, redirecting metalworking fluid formulators toward fatty acid-derived corrosion inhibitors. German and Dutch lubricant blenders face reformulation deadlines accelerating bio-based ester adoption.
Brand-led deforestation-free procurement mandates now override traditional spot-market purchasing. Personal care multinationals in France and Germany require mass-balance certification traceable to plantation GPS coordinates, displacing book-and-claim credit systems. This verification burden concentrates supplier relationships toward vertically integrated plantation operators.
Global Fatty Acids Market Segmentation
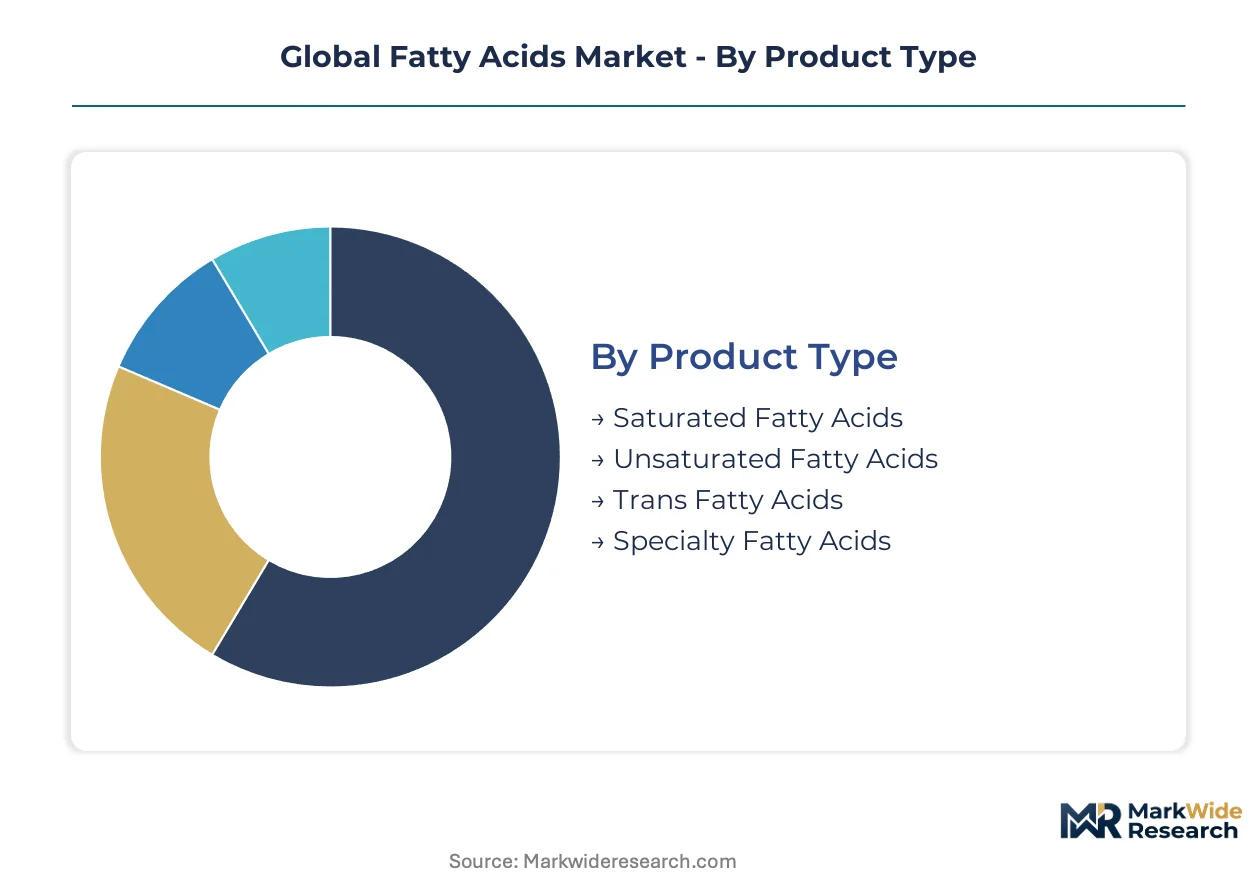
Channel configuration in the fatty acids market varies sharply by segment. Pharmaceutical and personal care grades flow through certified distributors with GMP documentation, while commodity saturated acids move via bulk tanker and spot contract mechanisms.
Product Type:
Channel-mix patterns diverge most dramatically across product chemistry, with saturated and unsaturated grades dominating commodity offtake while specialty and trans-fatty acid categories command premium distribution infrastructure.
- Saturated Fatty Acids:Straight-chain carboxylic acids with no double bonds, primarily lauric, myristic, palmitic, and stearic acid profiles. Soap and detergent manufacturers in Indonesia and Malaysia absorb the majority of volume through long-term offtake agreements tied to plantation processing cycles.
- Unsaturated Fatty Acids:Oleic, linoleic, and linolenic acid structures with one or more double bonds. Food manufacturers in India under FSSAI trans-fat labeling directives are accelerating procurement of high-oleic variants for packaged oil reformulation.
- Trans Fatty Acids:Partially hydrogenated oil derivatives facing regulatory phase-out across EU REACH jurisdictions and US FDA enforcement zones. Margarine and shortening applications in developing markets sustain residual demand.
- Specialty Fatty Acids:Ultra-purity grades with carbon chain specificity for pharmaceutical lipid excipients and cosmetic active delivery. GMP-certified processors in Germany and Singapore control segregated supply channels with 18-24 month RSPO-IP certification timelines.
Saturated fatty acids dominate installed base. Specialty fatty acids is where expansion concentrates.
Application:
Cost-tier stratification separates commodity surfactant applications from performance-critical pharmaceutical and personal care segments where certification overhead determines supplier eligibility.
- Food & Beverage:Emulsifiers, texturizers, and shelf-life extenders across bakery, confectionery, and dairy processing. Indian packaged food manufacturers under FSSAI disclosure mandates are restructuring procurement toward structured lipid alternatives.
- Personal Care:Surfactants, emollients, and conditioning agents in skin and hair formulations. EU-based brand owners now require mass-balance certification traceable to plantation GPS coordinates, displacing book-and-claim credit systems.
- Paints & Coatings:Alkyd resin modifiers and drying oil components. ECHA REACH restrictions on medium-chain chlorinated paraffins are redirecting metalworking fluid formulators toward fatty acid-derived corrosion inhibitors.
- Lubricants:Bio-based ester base stocks and friction modifiers. German and Dutch blenders face reformulation deadlines accelerating adoption of oleochemical alternatives to mineral oil derivatives.
Food & Beverage anchors volume throughput. Personal Care commands the steepest expansion trajectory.
Form:
Physical state dictates logistics infrastructure requirements, with liquid and bulk solid forms dominating commodity movement while powder and emulsified variants require specialized handling for pharmaceutical and food-grade compliance.
- Liquid:Unfractionated or partially refined fatty acid streams delivered via heated tanker transport. Bulk chemical processors in Rotterdam and Singapore hubs prefer liquid form for continuous hydrogenation and esterification operations.
- Solid:Fractionally distilled and flaked products with defined melting point specifications. Soap manufacturers favor solid flake delivery for direct saponification without intermediate processing.
- Powder:Spray-dried or micronized grades for dry-blend food and pharmaceutical applications. Encapsulation and tableting operations require powder flow characteristics certified to pharmacopeial standards.
- Emulsified:Pre-dispersed aqueous or oil-phase preparations for direct formulation integration. Cosmetic contract manufacturers leverage emulsified inputs to bypass in-house high-shear processing equipment.
Liquid form dominates installed base. Powder form is where expansion concentrates.
End User:
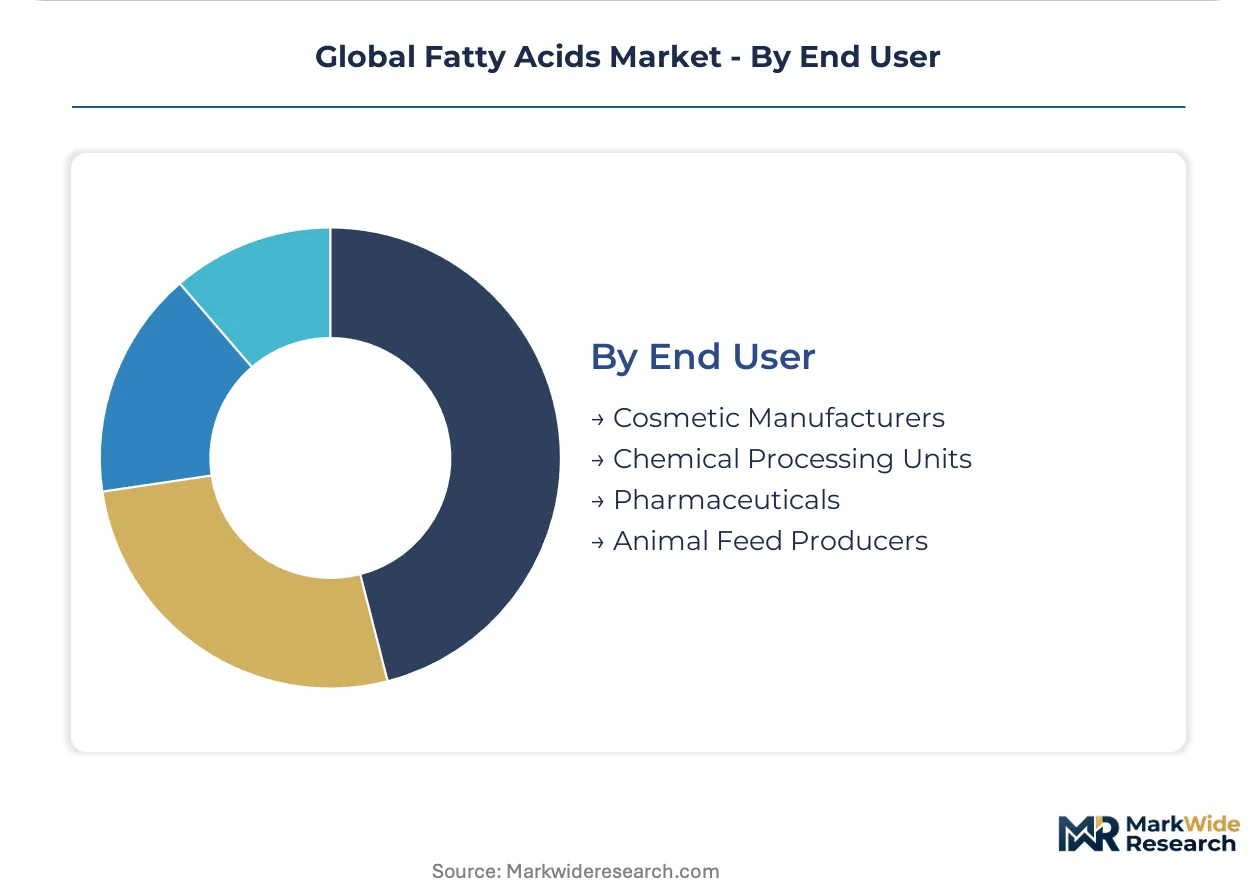
Customer-type concentration reveals divergent procurement sophistication, with pharmaceutical and cosmetic manufacturers imposing certification burdens that commodity chemical processors rarely encounter.
- Cosmetic Manufacturers:Formulators of skin, hair, and color cosmetic products requiring RSPO-IP or mass-balance certification for brand compliance. French and German personal care multinationals now mandate plantation GPS traceability.
- Chemical Processing Units:Oleochemical refiners and downstream derivative producers operating continuous hydrogenation, sulfonation, and esterification trains. Ludwigshafen and Rotterdam clusters concentrate fractional distillation expertise.
- Pharmaceuticals:Lipid excipient formulators for oral, parenteral, and mRNA delivery systems. mRNA vaccine protocols sustain demand for ultra-pure stearic and oleic acid derivatives with GMP-segregated handling.
- Animal Feed Producers:Energy-dense lipid supplement formulators for aquaculture and livestock nutrition. Algae-derived EPA/DHA omega-3 sources are bypassing marine fishery constraints for nutraceutical encapsulation.
Chemical Processing Units dominate installed base. Pharmaceuticals is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH authorization protocols and EU Green Deal bio-based mandates anchor European demand redirection, while plantation-to-oleochemical verticality in Southeast Asia and pharmaceutical-grade GMP requirements in North America reshape investment flows across the value chain.
United States
FDA enforcement of trans-fat labeling and EPA biofuel mandates drive oleochemical substitution in food and lubricant applications. The agency's mRNA vaccine formulation protocols sustain procurement of ultra-pure stearic acid derivatives. New Jersey and Pennsylvania chemical corridors concentrate hydrogenation and esterification capacity for pharmaceutical lipid excipient production.
Germany
ECHA substance evaluation fees exceeding €100,000 per registration block SME market entry while favoring integrated processors with captive compliance infrastructure. The Ludwigshafen chemical complex anchors fractional distillation expertise for high-purity fatty acid derivatives. Metalworking fluid formulators face REACH-mandated reformulation deadlines redirecting demand toward bio-based corrosion inhibitors.
Indonesia
Plantation-to-oleochemical verticality controls over 40% of global palm kernel oil feedstock throughput. El Niño yield volatility exposes concentrated supply chains to price disruption. Riau and North Sumatra provinces host integrated processing clusters serving commodity soap and detergent manufacturers through long-term offtake agreements.
India
FSSAI trans-fat disclosure rules accelerate palm oil replacement with structured lipid alternatives in packaged food manufacturing. The regulator's labeling directives restructure procurement patterns among bakery and confectionery processors. Gujarat and Maharashtra industrial zones concentrate mid-stream oleochemical refining for domestic surfactant and emulsifier production.
Japan
METI carbon accounting standards and Scope 3 disclosure requirements favor regional suppliers with verified deforestation-free palm supply chains. Cosmetic and personal care brand owners mandate mass-balance certification traceable to plantation GPS coordinates. Osaka-Kobe chemical corridor hosts segregated handling infrastructure for pharmaceutical-grade specialty ester production.
Global Fatty Acids Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated structure where scale-driven commodity processors coexist with biotechnology-enabled precision manufacturers. The upper tier commands captive feedstock security and GMP-certified infrastructure, while mid-scale operators compete on certification velocity and regional proximity. Three archetypes dominate: plantation-integrated oleochemical refiners, pharmaceutical-grade specialty ester producers, and diversified chemical conglomerates with backward integration into bio-based feedstock processing. Competitive moves concentrate on segregated supply chain certification timelines and enzymatic esterification capacity expansion.
Within the integrated refiner archetype, Wilmar International Ltd and KLK OLEO exemplify plantation-to-oleochemical verticality across Southeast Asian operations. BASF SE anchors the diversified chemical conglomerate tier through its Ludwigshafen complex, representing captive feedstock security for high-purity derivative production. Croda International Plc occupies a position within the specialty ester tier, exemplifying biotechnology-led manufacturing targeting pharmaceutical and personal care certification grades.
| Leading Market Players |
|---|
| BASF SE |
| VVF Ltd |
| Wilmar International Ltd |
| Croda International Plc |
| Godrej Industries |
| Musim Mas |
| Cargill Incorporated |
| DOW |
| KLK OLEO |
| Others |
Supply & Pricing Matrix
Structured lipid substitution for palm oil in Indian packaged food manufacturing simultaneously redraws feedstock sourcing geography and compresses margin structures across the fatty acids value chain. FSSAI trans-fat disclosure mandates force reformulation investments that elevate procurement costs while redirecting volume toward certified alternative supply channels.
Pricing Analysis
Rotterdam-Singapore-Jakarta price spreads widen during El Niño episodes as Indonesian plantation yield volatility disrupts spot market liquidity. Three-tier pricing structure across pharmaceutical-grade, personal care-certified, and commodity soap-grade tiers separates buyers by certification burden and volume scale. Pricing pressure stems from REACH registration cost escalation exceeding €100,000 per novel ester, squeezing mid-scale processors without captive compliance infrastructure. Commodity soap manufacturers exhibit acute price sensitivity, while pharmaceutical formulators prioritize GMP-segregated supply security over unit cost.
Supply Chain Analysis
Indonesia and Malaysia anchor global palm kernel oil feedstock production, collectively controlling over 80% of upstream throughput. Oleochemical processors draw from crude palm oil, palm kernel oil, and waste-oil feedstocks to sustain hydrogenation and esterification operations. Single-source vulnerability concentrates in Riau and North Sumatra plantation clusters exposed to climate-induced yield disruption. Distribution runs through Rotterdam and Singapore hub terminals for commodity grades, while pharmaceutical-certified channels require segregated GMP handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among personal care multinationals that now mandate mass-balance certification traceable to plantation GPS coordinates, fragmenting supplier relationships toward vertically integrated plantation operators.
For Market Incumbents: Compound captive feedstock security through backward integration into certified plantation operations or long-term offtake agreements with RSPO-IP verified sources. Accelerate enzymatic esterification capacity expansion to capture pharmaceutical lipid excipient demand as synthetic alkylbenzene sulfonate substitution threatens commodity surfactant margins.
For New Entrants and Emerging Players: RSPO-IP certification fast-track for Brazilian ANVISA pharmaceutical-grade oleochemical production addresses Latin America's largest generics market lacking domestic GMP capacity. Algae oil biotechnology convergence for EPA/DHA omega-3 nutraceutical encapsulation bypasses marine fishery constraints. Target enzymatic interesterification miniaturization for pharmaceutical contract manufacturing as a go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale oleochemical refiners lacking certification velocity to serve personal care brand compliance timelines. Long-term viability hinges on segregated supply chain infrastructure and enzymatic production capabilities. Watch for ECHA substance evaluation protocol expansions restricting additional palm-derived supply routes as an inflection indicator for bio-based feedstock processing investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Plantations | Secures RSPO-IP mass-balance traceability required by French and German personal care multinationals. |
| Enzymatic Esterification Capacity Expansion | Captures pharmaceutical lipid excipient demand from mRNA vaccine formulation protocols. |
| GMP-Segregated Handling Infrastructure | Enables compliance with FDA and EMA pharmaceutical-grade certification requirements. |
| Algae Oil Fermentation Platform Development | Bypasses marine fishery constraints for EPA/DHA omega-3 nutraceutical encapsulation. |
| Waste-Oil Feedstock Processing Investment | Aligns with EU Green Deal bio-based mandates and carbon accounting disclosure requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oleochemical plant managers, procurement leads at downstream personal care manufacturers, pharmaceutical formulation scientists, and RSPO certification auditors; and secondary validation through customs trade data, ECHA REACH registration databases, SEC 10-K filings of listed processors, and FSSAI regulatory directives. Bottom-up volume modeling across product grades and applications triangulated against top-down value estimates derived from trade flow analysis.
Across the analysis window, forecasts incorporate segmentation by saturated versus unsaturated chemistry, pharmaceutical versus commodity application tiers, and liquid versus solid physical forms. CAGRs emerge from trend extrapolation of feedstock cost trajectories, regulatory compliance cost escalations, and substitution elasticity between oleochemical and petrochemical surfactants. Industry-specific inputs include El Niño yield volatility patterns and enzymatic biocatalysis adoption curves in pharmaceutical contract manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal mandate enforcement or accelerated FDA trans-fat phase-out timelines would require recalibration. Forecasts reflect assumptions regarding plantation productivity stability and REACH authorization protocol scope. Recalibration cycles align with material shifts in ECHA substance evaluation expansions and brand-led deforestation-free procurement mandate adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Food Protein Ingredient Market