
 United Kingdom Food Additives Market | 2026-2036
United Kingdom Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Additives Market Analytics
The capability gap between integrated multinationals and domestic specialists is collapsing as clean-label mandates force uniform capital deployment. Tate & Lyle PLC leverages its British heritage and deep reformulation partnerships with domestic beverage brands to sustain regional relevance. Kerry Group PLC anchors its position through applied nutrition labs in Ireland and England that specialize in natural preservation systems. Corbion NV competes on fermentation-derived ingredient platforms, differentiating from petroleum-based rivals in emulsifier categories.
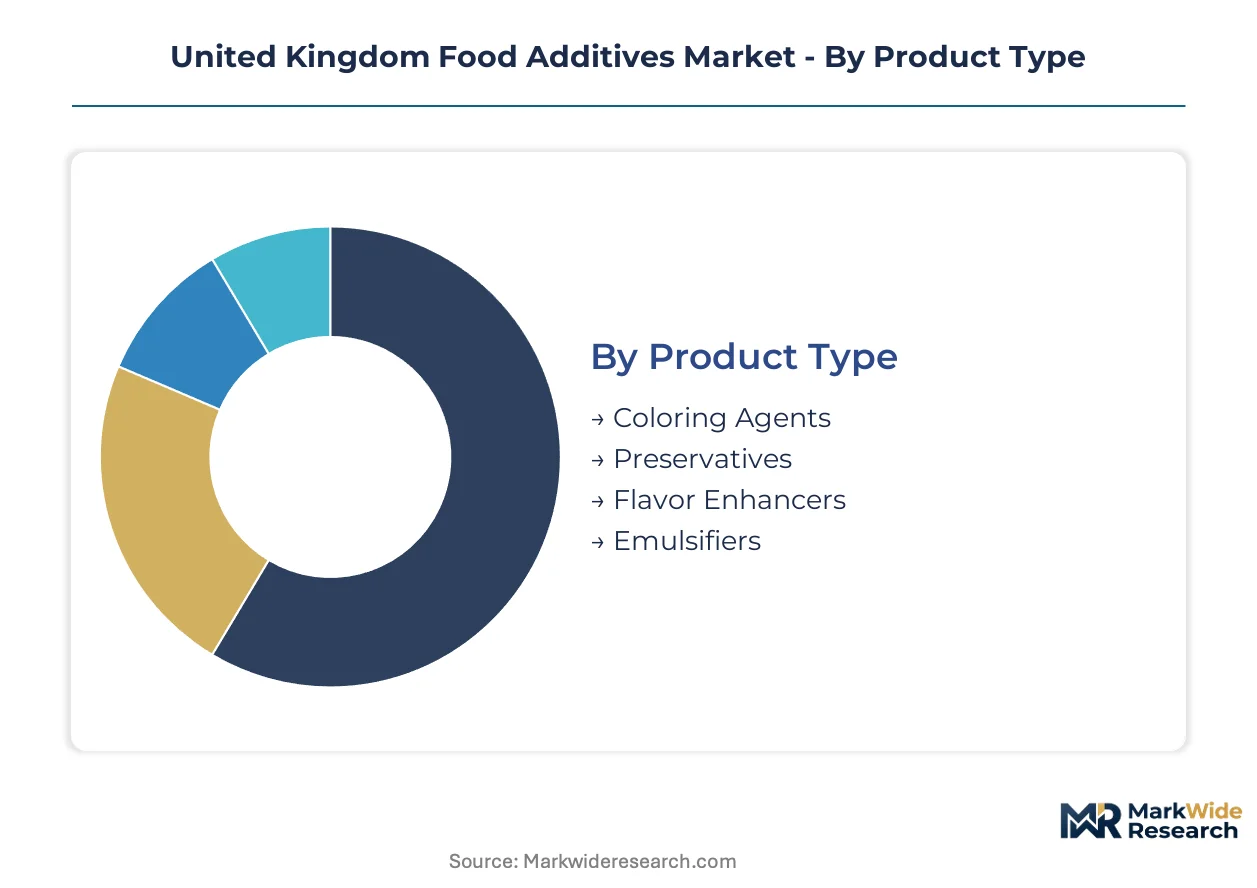
Food additives comprise substances incorporated into food products to enhance stability, sensory properties, or shelf life, typically used at concentrations below one percent by weight and governed by E-number classification systems. These compounds serve industrial food production by enabling standardized quality, extended distribution reach, and consistent consumer experience across batch scales. Preservatives command the largest current value share within product type segments as mold inhibition remains non-negotiable for ambient retail distribution, though coloring agents represent the fastest structural shift as brands replace synthetic azo dyes with anthocyanin and curcumin extracts. Among applications, dairy products absorb disproportionate additive innovation investment due to clean-label yogurt and plant-based alternative launches, while confectionery maintains mature demand patterns with limited reformulation urgency.
The Food Standards Agency enforces retained EU regulation through the Food Safety Act framework, while EFSA registrations remain valid for cross-border ingredient acceptance into Northern Ireland under Windsor Agreement provisions. BSI ISO 22000 certification increasingly functions as a procurement gate for British retailers consolidating supplier bases. Manufacturers must monitor divergence between UK-specific novel food approvals and retained EU safety assessments, as asynchronous timelines threaten ingredient portfolio synchronization across British and European production networks.
Market Dynamics
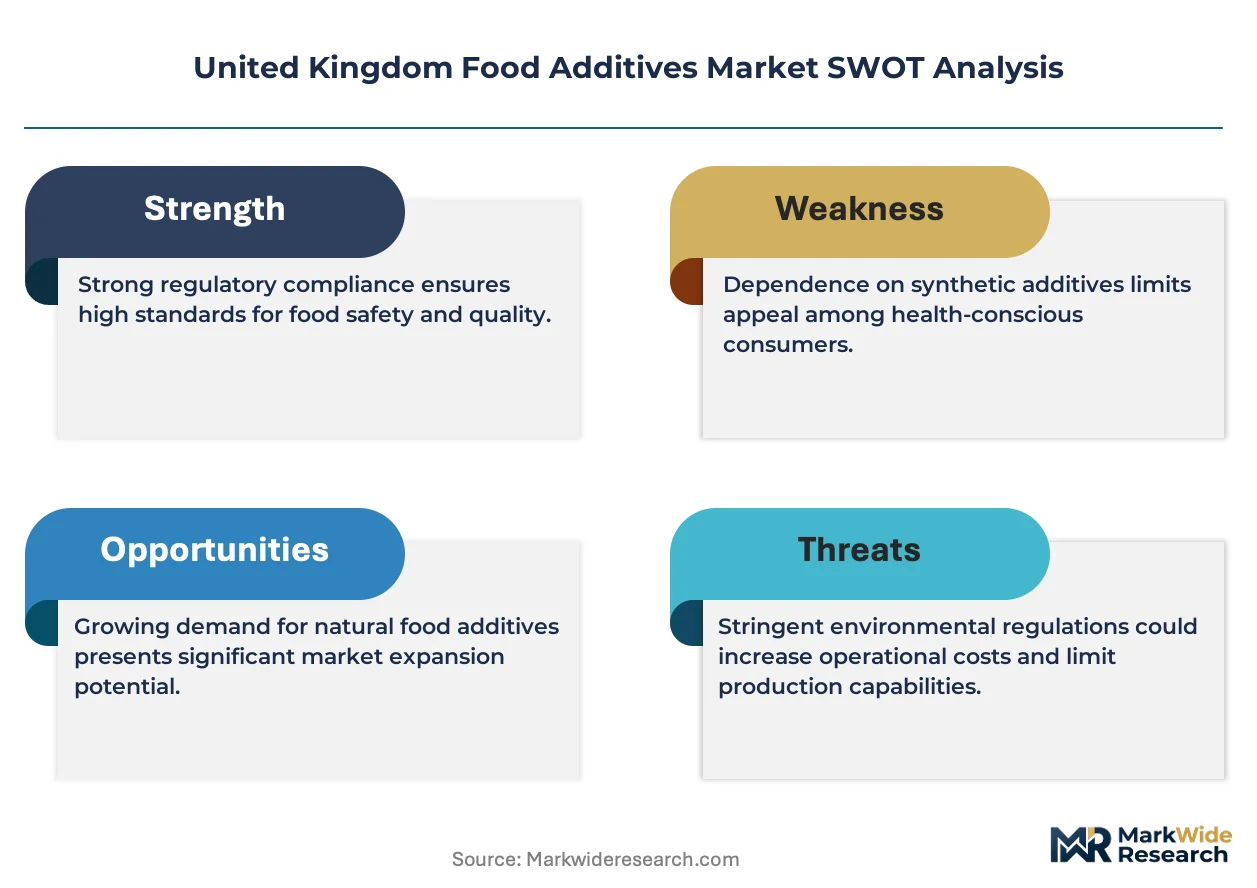
Clean-label mandates from British retailers are compressing formulation cycles and forcing additive suppliers to rebuild portfolios around natural extraction methods rather than petroleum-derived chemistry.
Growth Catalysts
- Food Standards Agency novel food guidance:Accelerated approval pathways for fermentation-derived ingredients redirect R&D budgets toward bioprocessing capabilities.
- Plant-based dairy alternatives:Functional ingredient demand concentrates in oat and almond milk formulations requiring emulsifier and stabilizer innovation.
- Yorkshire-to-East Midlands manufacturing corridor:Proximity clustering of food manufacturers enables rapid co-development partnerships between additive suppliers and finished goods producers.
Market Restraints
- Natural extract input volatility:Anthocyanin and curcumin supply depends on agricultural harvest cycles and climate variability in sourcing regions.
- Single-source fermentation capacity:Specialized bioreactor infrastructure for clean-label preservatives concentrates among limited European contract manufacturers.
- Retained EU regulatory divergence:Asynchronous safety assessments between UK-specific approvals and EFSA evaluations fragment portfolio planning for cross-border producers.
Strategic Opportunities
- Northern Ireland dual-market access:Windsor Agreement provisions enable simultaneous EFSA-registered and UK-approved ingredient distribution into EU and British supply chains.
- BSI ISO 22000 procurement consolidation:Retailer supplier-base rationalization creates certification-driven consolidation opportunities for accredited additive providers.
- Precision fermentation platforms:Convergence of synthetic biology with food-grade bioprocessing opens novel preservative categories beyond traditional chemical synthesis.
Industry Challenges
- Reformulation technical talent scarcity:Clean-label transition requires food scientists skilled in natural ingredient functionality mapping, a capability pool concentrated among retiring industry veterans.
- Dual-approval compliance timelines:Parallel UK and EU novel food submissions extend time-to-market for innovative additives by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Additives Market |
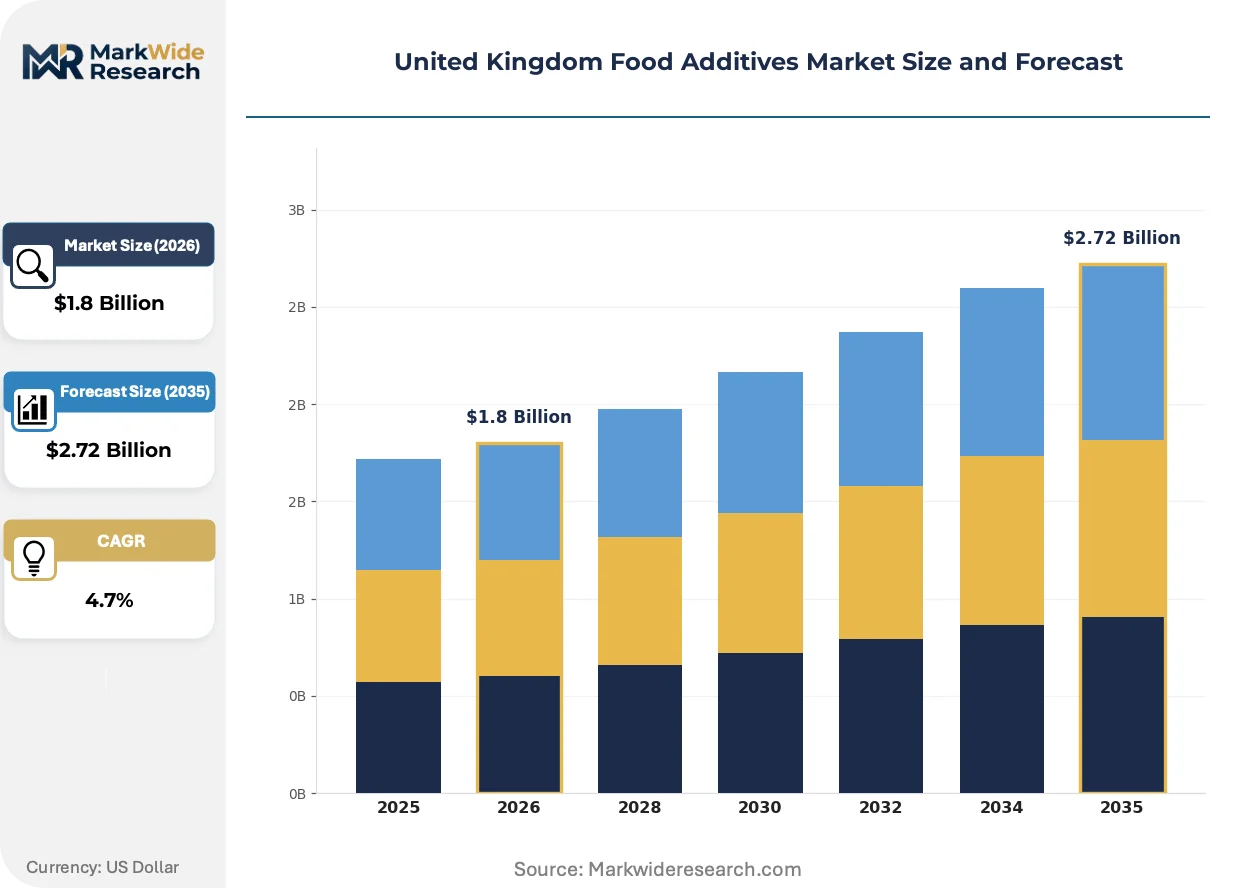
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coloring Agents, Preservatives, Flavor Enhancers, Emulsifiers Application: Beverages, Dairy Products, Snacks, Confectionery End User: Food Manufacturers, Catering Services, Retailers, Bakeries Regulatory Compliance: FDA Approved, EFSA Registered, ISO Certified, Others |
| Companies Covered | BASF SE, Cargill Incorporated, Tate & Lyle PLC, Kerry Group PLC, Ingredion Incorporated, Archer Daniels Midland Company, International Flavors & Fragrances Inc, Corbion NV, Givaudan SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Additives Market Evolving Landscape
Bioprocessing technologies and procurement model evolution are restructuring how British food manufacturers source functional ingredients, compressing supplier relationships toward integrated partnership structures.
Fermentation-derived emulsifiers are displacing petroleum-based alternatives in clean-label formulations. Major British dairy and plant-based beverage manufacturers adopted these bioprocessed ingredients between 2023 and 2025. This displacement collapses the traditional cost premium for natural alternatives and pressures synthetic additive margins across ambient retail categories.
Retained EU regulation through the Food Safety Act framework maintains E-number classification systems while permitting UK-specific divergence. The Food Standards Agency's evolving stance on precision fermentation ingredients creates regulatory uncertainty for novel preservative categories. Northern Ireland-based suppliers leverage Windsor Agreement provisions to maintain EFSA registration validity while accessing British formulation partnerships.
Retailer-driven certification requirements concentrate procurement decisions among BSI ISO 22000-accredited suppliers. British supermarket chains consolidated approved vendor lists from forty-plus additive providers to under fifteen certified partners. This concentration shifts supplier relationships from transactional spot purchasing toward multi-year co-development agreements with guaranteed volume commitments.
United Kingdom Food Additives Market Segmentation
Segmentation in the United Kingdom Food Additives Market reveals how clean-label mandates and regulatory divergence reshape procurement priorities across British food manufacturing. Understanding these divides exposes where capital concentrates and which supplier capabilities command premium positioning.
Product Type:
Domestic demand for natural-derived additives concentrates in England's Yorkshire-to-East Midlands corridor, while export-oriented production favors standardized synthetic formulations for cost-sensitive markets.
- Coloring Agents:Anthocyanin and curcumin extracts displace synthetic azo dyes in clean-label formulations. Reformulation partnerships with British beverage and dairy brands concentrate demand in premium retail channels where visual appeal drives purchase decisions.
- Preservatives:Mold inhibition remains non-negotiable for ambient distribution, with fermentation-derived alternatives gaining share against petroleum-based chemistry. The Food Standards Agency's accelerated approval pathways for bioprocessed preservatives redirect R&D investment toward specialized bioreactor capacity.
- Flavor Enhancers:Yeast extracts and natural nucleotides replace synthetic MSG in reduced-sodium applications across British ready-meal manufacturing.
- Emulsifiers:Fermentation-derived alternatives displace petroleum-based lecithin in plant-based dairy formulations, with Yorkshire-based co-development partnerships driving adoption velocity.
Preservatives command the established base. The steepest expansion runs through Coloring Agents.
Application:
Cost-tier stratification separates premium clean-label investments from mature categories with limited reformulation urgency.
- Beverages:Plant-based milk alternatives require emulsifier and stabilizer innovation at functional performance levels matching dairy benchmarks. Oat and almond milk launches concentrate additive demand among British beverage startups and dairy incumbents.
- Dairy Products:Yogurt and plant-based alternative launches absorb disproportionate innovation investment. Clean-label positioning in British retail chains mandates natural preservation systems for extended shelf-life claims.
- Snacks:Seasoning adhesion and oxidation control dominate additive requirements, with mid-tier British snack manufacturers prioritizing cost stability over natural transitions.
- Confectionery:Mature demand patterns persist with limited reformulation urgency, as British chocolate and sugar confectionery brands maintain established E-number portfolios.
Dairy Products anchor premium pricing tiers. Beverages climb the fastest as plant-based alternatives scale production.
End User:
Volume concentration among large-scale manufacturers contrasts with fragmented demand from artisanal and service-sector buyers.
- Food Manufacturers:Integrated reformulation partnerships with additive suppliers dominate procurement, with multi-year co-development agreements replacing transactional spot purchasing among British supermarket-approved vendors.
- Catering Services:Cost-driven procurement favors standardized additive portfolios with minimal clean-label premiums, concentrated in institutional and contract foodservice channels.
- Retailers:Own-label clean-label mandates cascade through consolidated supplier bases, with BSI ISO 22000 certification functioning as a procurement gate.
- Bakeries:Artisanal and industrial segments diverge sharply, with premium British craft bakeries accepting natural ingredient cost premiums while commodity baking prioritizes functional consistency.
Food Manufacturers absorb the dominant volume share. Retailers gain influence fastest through supplier-base rationalization mandates.
Regulatory Compliance:
Dual-market access requirements concentrate premium positioning among suppliers navigating asynchronous UK-EU approval timelines.
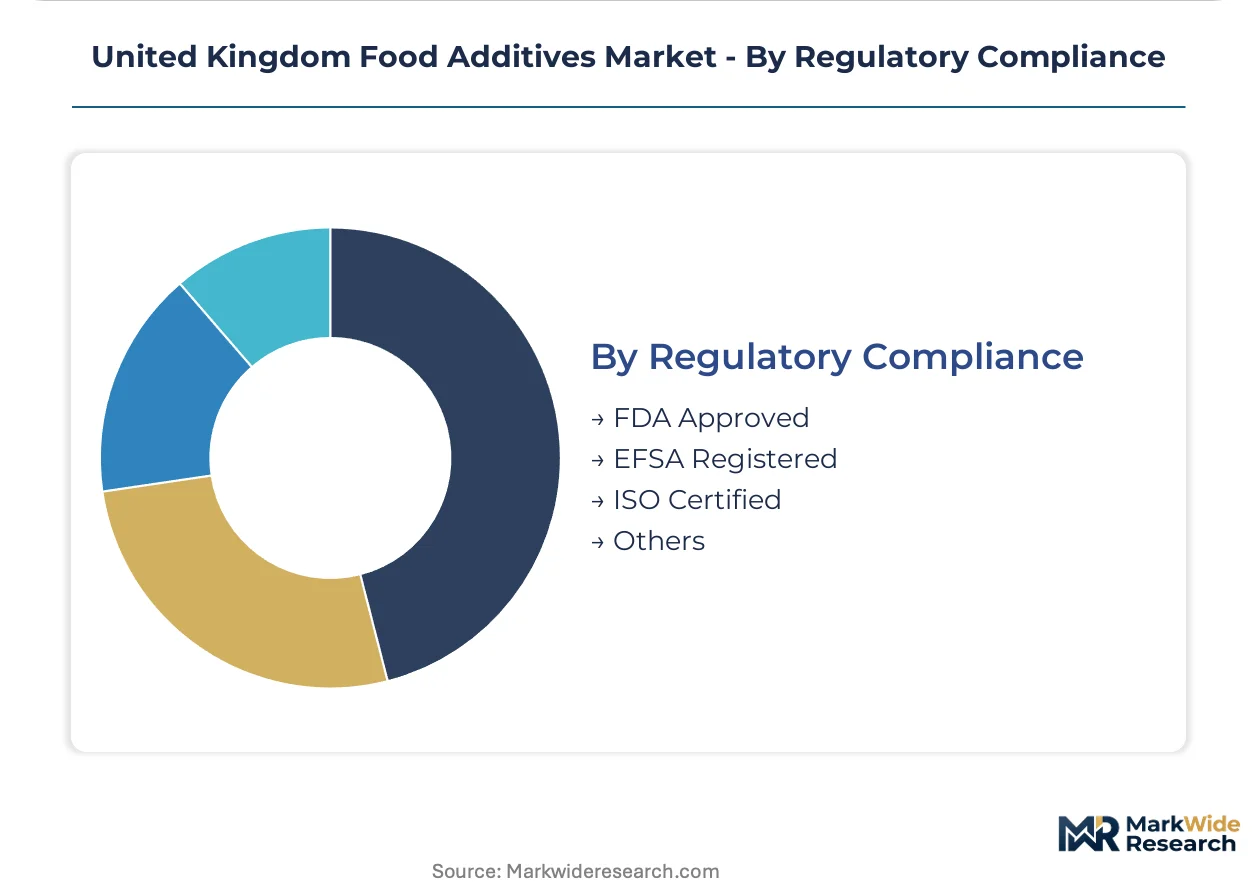
- EFSA Registered:Cross-border ingredient acceptance into Northern Ireland under Windsor Agreement provisions maintains validity for European production networks. British manufacturers with EU export exposure prioritize EFSA-registered portfolios.
- ISO Certified:BSI ISO 22000 certification increasingly functions as a procurement gate for British retailers consolidating approved vendor lists from forty-plus providers to under fifteen certified partners.
- FDA Approved:Limited direct relevance for domestic British demand, though multinational suppliers maintain FDA-registered portfolios for North American market access.
- Others:UK-specific novel food approvals diverge from retained EU safety assessments, fragmenting portfolio planning for cross-border producers.
EFSA Registered credentials secure dual-market positioning. ISO Certified status expands fastest through retailer procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's Yorkshire-to-East Midlands corridor commands premium additive pricing against Northern Ireland's dual-market access advantage. Scottish and Welsh manufacturing clusters operate at cost parity with English regions but lack equivalent reformulation partnership density. Regional specialization patterns concentrate natural extraction R&D in southern England while fermentation capacity clusters in the Irish Sea corridor.
England
Yorkshire-based dairy manufacturers drive emulsifier demand for oat and almond milk formulations. The Food Standards Agency's novel food guidance accelerates approval pathways for fermentation-derived ingredients. The East Midlands manufacturing corridor hosts rapid co-development partnerships between additive suppliers and finished goods producers seeking clean-label reformulation.
Northern Ireland
Windsor Agreement provisions enable simultaneous EFSA-registered and UK-approved ingredient distribution. Dual-market access attracts precision fermentation investments from cross-border producers. Belfast and Londonderry host suppliers leveraging retained EU registration validity while accessing British formulation partnerships.
Scotland
Scottish beverage manufacturers concentrate demand for natural coloring agents in premium whisky and soft drink launches. The Food Safety Act framework governs retained EU regulation enforcement. Edinburgh and Glasgow clusters specialize in yeast extract and natural nucleotide production for reduced-sodium applications.
Wales
Welsh food manufacturers prioritize cost-stable synthetic additive portfolios for commodity baking and institutional catering. BSI ISO 22000 certification functions as a procurement gate for British retailers consolidating approved vendor lists. The Cardiff-Newport corridor lacks equivalent clean-label reformulation urgency seen in English manufacturing hubs.
United Kingdom Food Additives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom Food Additives Market. Integrated multinationals with fermentation-derived platforms command premium positioning in clean-label segments, while petroleum-based specialists defend volume through cost-optimized synthetic portfolios. Three archetypes dominate: bioprocessing technology leaders, heritage British reformulation partners, and diversified global ingredient suppliers. Competitive moves concentrate on multi-year co-development agreements with supermarket-approved vendors and specialized bioreactor capacity expansion for natural preservation systems.
Among heritage British specialists, Tate & Lyle PLC occupies a position exemplifying deep reformulation partnerships with domestic beverage brands. Kerry Group PLC represents the applied nutrition laboratory archetype with facilities spanning Ireland and England. Corbion NV anchors the fermentation-derived platform segment, differentiating from petroleum-based rivals in emulsifier categories through bioprocessing capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Tate & Lyle PLC |
| Kerry Group PLC |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc |
| Corbion NV |
| Givaudan SA |
| Others |
Value Network & Pricing Analysis
BSI ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, concentrating procurement decisions among accredited additive providers while creating tiered cost structures across certified and non-certified production networks.
Pricing Analysis
Configured-to-order pricing for fermentation-derived clean-label additives commands substantial premiums against standardized petroleum-based alternatives. Three-tier pricing structure across premium, standard, and economy levels separates BSI ISO 22000-certified natural extracts from commodity synthetic formulations, with certification grade and volume scale as primary price differentiation drivers. Cost compression in synthetic emulsifier tiers is intensifying because fermentation-derived alternatives achieved cost parity through Yorkshire-based bioreactor scale-up. Small-scale artisanal bakeries exhibit highest price sensitivity, while supermarket own-label manufacturers absorb premium natural ingredient costs to maintain clean-label positioning.
Supply Chain Analysis
Inventory lead times for anthocyanin and curcumin extracts stretch across agricultural harvest cycles, creating seasonal procurement windows that constrain just-in-time manufacturing. Supply draws from China, India, and Peru for natural colorant raw materials, while fermentation capacity clusters in Ireland, Netherlands, and domestic British bioreactor facilities. Specialized bioreactor infrastructure for clean-label preservatives represents single-source vulnerability, as European contract manufacturers concentrate precision fermentation capacity. Distribution runs through consolidated retailer-approved vendor networks, with multi-year co-development agreements replacing spot purchasing among Yorkshire-to-East Midlands manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label mandates from British retailers constitute a high-growth disruption, with precision fermentation technology inflecting ingredient economics toward bioprocessed alternatives and collapsing traditional petroleum-based cost advantages.
For Market Incumbents: Fortify market position through backward integration into specialized bioreactor capacity for fermentation-derived preservatives, neutralizing single-source contract manufacturing risk. Tate & Lyle PLC and Kerry Group PLC should accelerate co-development partnerships with Yorkshire-based dairy manufacturers to lock in multi-year volume commitments before synthetic additive margins erode further.
For New Entrants and Emerging Players: Anchor in Northern Ireland's dual-market access corridor under Windsor Agreement provisions, leveraging simultaneous EFSA-registered and UK-approved ingredient distribution to serve cross-border production networks. The most penetrable white-space sits in precision fermentation platforms for novel preservative categories, with go-to-market through BSI ISO 22000 certification investment enabling retailer procurement consolidation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure, favoring scaled players with captive bioprocessing capabilities over asset-light formulation specialists. Acquisition targets should exhibit applied nutrition laboratory assets spanning England and Ireland, with fermentation-derived platform differentiation from petroleum-based rivals. The signal to watch is Food Standards Agency novel food approval velocity for bioprocessed ingredients, as accelerated pathways would validate premium valuations for fermentation-capable suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captures clean-label preservative demand from Yorkshire dairy and plant-based beverage manufacturers. |
| BSI ISO 22000 Certification Investment | Secures procurement gate access as British retailers consolidate approved vendor lists below fifteen partners. |
| Multi-Year Co-Development Agreements | Locks in volume commitments with supermarket own-label manufacturers seeking reformulation partnerships. |
| Natural Extraction Supply Security | Hedges anthocyanin and curcumin input volatility through diversified agricultural sourcing from Peru and India. |
| Northern Ireland Dual-Market Positioning | Leverages Windsor Agreement provisions for simultaneous EFSA-registered and UK-approved ingredient distribution. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Food Standards Agency guidance documents, EFSA safety assessments, BSI certification registers, and British Retail Consortium procurement disclosures. Primary interviews engaged food manufacturing R&D directors, supermarket category buyers, additive supplier technical sales leads, and precision fermentation facility operators across England, Northern Ireland, and Ireland. Secondary validation incorporated trade customs data, retained EU regulation frameworks, and Windsor Agreement implementation protocols. Bottom-up demand modeling triangulated against top-down market sizing across product type and application segments.
Segmentation dimensions modeled span product type, application, end user, and regulatory compliance tier across the projection horizon. Analytical framework derived CAGRs through trend extrapolation of clean-label adoption rates, natural ingredient cost parity trajectories, and retailer procurement consolidation velocity. Industry-specific forecast inputs incorporated Food Standards Agency novel food approval pipeline assessments and fermentation capacity expansion announcements from European contract manufacturers.
Decision-makers should treat outputs as directional under assumptions of continued clean-label mandate enforcement and stable Windsor Agreement provisions; material divergence in regulatory timelines or bioprocessing cost curves would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Microencapsulation Market