
 Food Grade Iron Powder Market | 2026-2036
Food Grade Iron Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Iron Powder Market Analysis
Modular dosing formats are restructuring buyer choice in food grade iron powder, as premix manufacturers unbundle bulk shipments into sachet-compatible micro-doses for rural fortification programs. Industrial Metal Powders India Pvt. Ltd. anchors South Asian supply through electrolytic production lines calibrated to FSSAI micronutrient standards. BASF SE leverages its premix formulation expertise to control European nutraceutical channels. American Elements specializes in high-purity spherical grades for research lab applications demanding tight particle-size distribution.
Food grade iron powder consists of reduced or electrolytic iron with particle sizes typically ranging from 5 to 50 microns and iron content exceeding 96%, manufactured through hydrogen reduction of iron oxide or electrodeposition processes to meet digestibility and bioavailability requirements for human consumption. Powder and spherical grades dominate volume in food fortification applications where dissolution rates determine nutrient uptake efficiency, while flake iron occupies premium positions in dietary supplement tablets where compressibility governs manufacturing yields. Nutraceutical companies and feed producers represent the fastest-growing end user channels as functional food positioning displaces commodity ingredient purchasing.
FDA food additive regulations and FSSAI fortification standards shape product purity thresholds and market access requirements for imported iron powders across North America and South Asia. WHO guidelines on iron supplementation in staple foods create procurement templates that national programs in India, Nigeria, and Indonesia adopt with local adaptations. EFSA evaluations of novel iron compounds influence reformulation decisions among European premix suppliers seeking approved status. Stakeholders must monitor evolving bioavailability testing protocols as regulators weigh dissolution metrics against traditional purity specifications.
Market Dynamics
Government-mandated fortification programs are compressing procurement timelines and forcing electrolytic iron powder suppliers to reconfigure production schedules around public sector tender cycles rather than private commercial orders.
Growth Catalysts
- WHO iron supplementation guidelines:Tightening purity thresholds for staple food fortification are filtering into national procurement standards across Nigeria, Indonesia, and India, expanding addressable demand for certified-grade suppliers.
- Rice fortification mandates:India's FSSAI-driven compulsory rice fortification program is creating predictable offtake volumes that de-risk capacity expansion decisions for domestic electrolytic iron producers.
- Electrolytic particle refinement:Sub-10-micron production capabilities are improving dissolution rates in low-moisture flour matrices, opening formulation access to premix manufacturers previously limited to reduced iron alternatives.
Market Restraints
- Scrap iron feedstock volatility:Hydrogen-reduced iron powder production faces margin compression when ferrous scrap prices spike, disproportionately affecting smaller mills without long-term scrap supply contracts.
- Electrolytic capacity concentration:South Asian supply chains depend heavily on Mumbai-Ahmedabad production clusters, creating single-point vulnerability to regional power grid instability or environmental compliance shutdowns.
- Bioavailability testing bottlenecks:EFSA's pending evaluation protocols for novel iron compounds are freezing reformulation pipelines, locking European premix suppliers into legacy ferrous sulfate formulations.
Strategic Opportunities
- West African milling cooperatives:Underpenetrated fortification infrastructure in Ghana and Senegal offers first-mover positioning for suppliers capable of delivering sachet-compatible micro-dose formats.
- Dual-fortification premix convergence:Iron-zinc and iron-folic acid combination formulations are electrifying R&D investment as national programs seek cost efficiencies through single-intervention delivery.
- Direct-to-mill digital procurement:Platform-based tender aggregation is emerging in Indian states, enabling smaller electrolytic iron suppliers to bypass traditional distributor markups and access government rice mill networks.
Industry Challenges
- Electrochemical engineering talent scarcity:Electrolytic cell optimization and particle-size distribution control require specialized metallurgical expertise that competes with battery materials and hydrogen economy sectors for limited graduate pipelines.
- Multi-jurisdiction certification complexity:Simultaneous FSSAI, FDA, and EFSA compliance for global premix suppliers extends product qualification timelines and fragments quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Iron Powder Market |
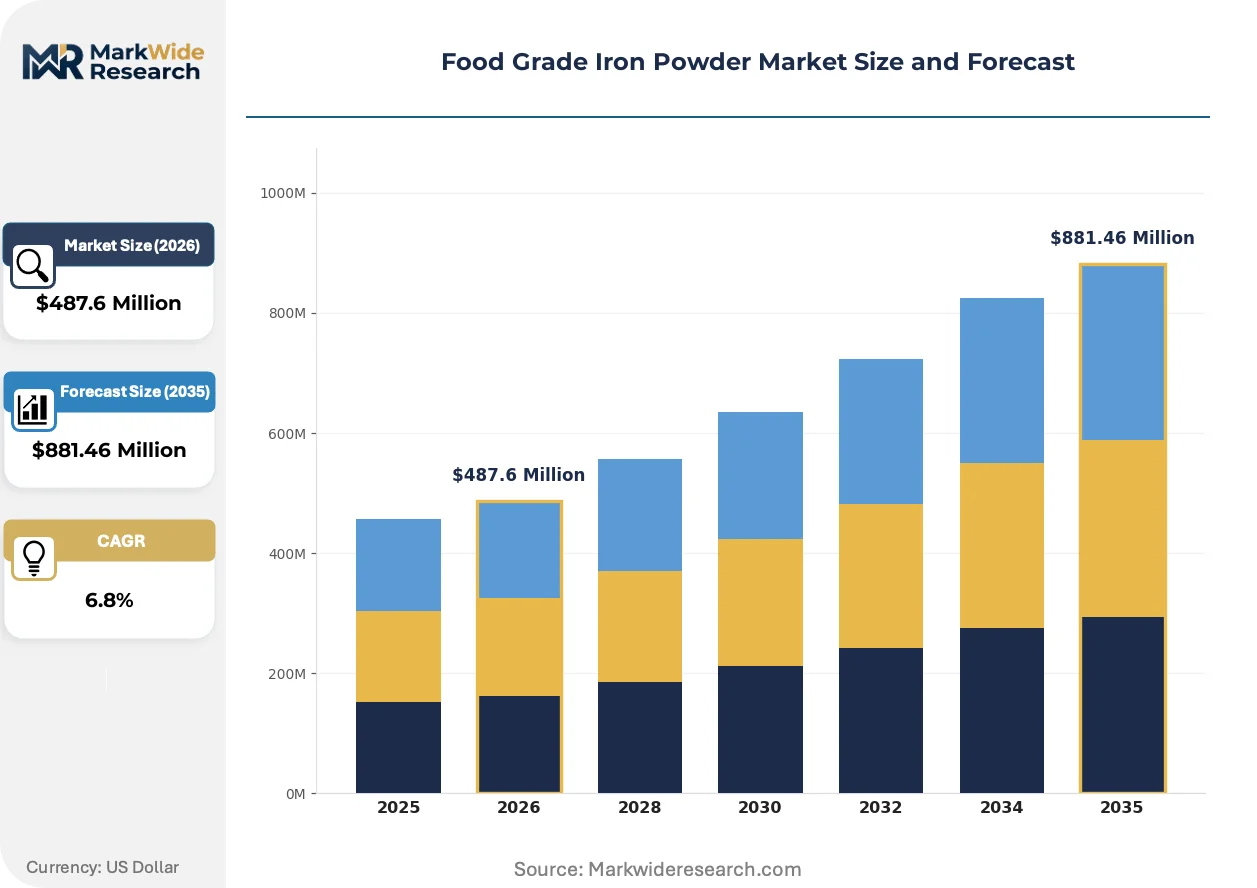
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spherical, Flake, Granule, Powder Application: Nutraceuticals, Food Fortification, Dietary Supplements, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Nutraceutical Companies, Research Labs, Feed Producers |
| Companies Covered | Industrial Metal Powders India Pvt. Ltd., Ashland Inc., American Elements, Rio Tinto Metal Powders, Belmont Metals Inc., BASF SE, Cathay Industries Group, Iron Powder Corporation, Spectrum Chemical Mfg. Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Iron Powder Market Emerging Trajectories
Particle engineering and regulatory harmonization are converging to redefine competitive advantage in food grade iron powder, with dissolution performance metrics displacing traditional purity specifications as the primary procurement filter.
Electrolytic atomization is electrifying the production landscape by enabling spherical particle morphologies with tightly controlled 5-25 micron distributions. Premix manufacturers in India and Nigeria are accelerating adoption of these grades for rice and wheat flour applications. This technology is compressing the performance gap between premium electrolytic and commodity reduced iron, forcing hydrogen-reduction suppliers to defend position through cost rather than functionality.
REACH authorization requirements for nickel catalyst residues in hydrogen-reduced iron are tightening trace metal thresholds for European market access. Industrial consequence includes accelerated migration toward electrodeposition routes that bypass nickel catalysis entirely. German and Dutch premix blenders are responding by dual-sourcing electrolytic grades from Indian suppliers while awaiting EFSA clarity on novel reduced iron process variants.
Consolidated national procurement is displacing fragmented private-sector purchasing as the dominant demand channel. India's state food corporations and Nigeria's Federal Ministry of Health are aggregating previously dispersed mill-level buying into centralized tender structures. This concentration is most visible in Indian states implementing compulsory rice fortification, where single-state contracts now exceed annual volumes previously distributed across hundreds of independent flour millers.
Food Grade Iron Powder Market Segmentation
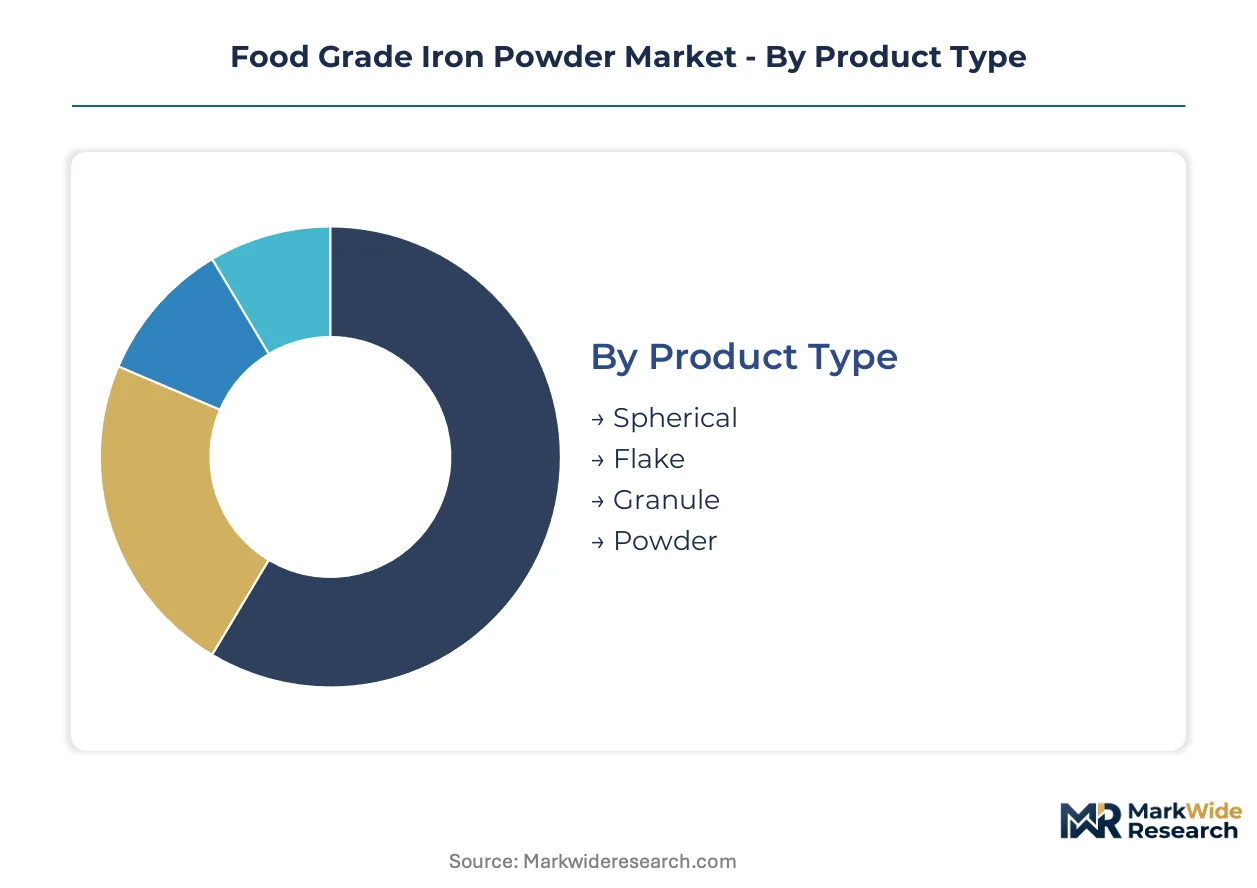
Segmentation in food grade iron powder reveals divergent technical requirements across fortification applications. Particle morphology and distribution channel selection directly determine bioavailability performance and procurement economics for premix manufacturers.
Product Type:
Spherical and powder grades command volume leadership in staple food fortification, while flake iron occupies premium positioning in pharmaceutical-compressible applications.
- Spherical:Electrolytic atomization produces tightly controlled 5-25 micron distributions with superior dissolution rates in low-moisture rice matrices. Indian state food corporations are consolidating procurement around these grades for compulsory rice fortification programs.
- Powder:Hydrogen-reduced iron with 5-50 micron particle sizes dominates wheat flour applications where cost efficiency outweighs dissolution speed requirements. Nigerian milling cooperatives are accelerating adoption as WHO purity thresholds tighten.
- Flake:Compressible morphology optimized for tablet manufacturing yields in dietary supplement production.
- Granule:Intermediate particle size for specialized premix applications requiring controlled dispersion.
Mature deployment sits with Powder. Newer deployment is concentrated in Spherical.
Application:
Food fortification generates predictable offtake through government tenders, while nutraceutical channels reward formulation flexibility with premium pricing.
- Food Fortification:Mandatory rice and wheat flour programs in India, Nigeria, and Indonesia create consolidated procurement volumes. FSSAI standards and WHO guidelines shape supplier qualification requirements.
- Nutraceuticals:Functional food positioning demands sub-10-micron electrolytic grades with documented bioavailability data. European premix blenders are expanding R&D investment as EFSA evaluates novel iron compounds.
- Dietary Supplements:Tablet compressibility requirements favor flake iron grades with specific surface area characteristics.
- Animal Feed:Lower purity tolerances and price-sensitive procurement distinguish this channel from human food applications.
Procurement scale concentrates in Food Fortification. Margin expansion is steepest in Nutraceuticals.
Distribution Channel:
Channel selection tracks customer scale, with bulk wholesale serving national programs and online retail penetrating small-batch nutraceutical formulators.
- Wholesale:Direct mill relationships and tender aggregation platforms enable electrolytic iron suppliers to bypass distributor markups in Indian state procurement systems.
- Specialty Stores:Technical consultation and sample provision support research laboratory and small premix manufacturer purchasing decisions.
- Supermarkets:Limited relevance for industrial-grade iron powder; primarily serves consumer-facing fortified food products.
- Online Retail:Emerging channel for micro-dose sachet formats targeting West African milling cooperatives with underpenetrated fortification infrastructure.
Volume flows through Wholesale. Digital penetration is climbing fastest in Online Retail.
End User:
End user type determines specification stringency, from research-grade purity demands to feed-grade cost optimization.
- Food Manufacturers:State rice mills and industrial flour producers drive electrolytic iron demand through centralized tender structures in India and Nigeria.
- Nutraceutical Companies:Dual-fortification premix formulations combining iron with zinc or folic acid are electrifying R&D investment among European and North American formulators.
- Feed Producers:Price-sensitive procurement with relaxed purity standards compared to human food applications.
- Research Labs:American Elements and comparable suppliers serve high-purity spherical grade demand for bioavailability studies and novel compound evaluation.
Contract scale peaks with Food Manufacturers. Specification intensity is highest among Research Labs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolytic iron powder production clusters in South Asia and North America while consumption concentrates in fortification-mandate jurisdictions across India, Nigeria, and Indonesia. This geographic mismatch shapes freight economics and tariff exposure for premix suppliers.
India
FSSAI-mandated rice fortification drives consolidated state-level procurement through Food Corporation of India tenders. The Mumbai-Ahmedabad industrial corridor hosts electrolytic production capacity calibrated to micronutrient standards. Domestic suppliers reconfigure batch schedules around public sector tender cycles rather than private commercial orders.
United States
FDA food additive regulations shape purity thresholds for imported iron powders entering nutraceutical and supplement channels. Research-grade spherical iron demand concentrates around American Elements and specialty chemical distributors serving bioavailability studies. Feed-grade applications maintain separate procurement streams with relaxed specification intensity.
Germany
REACH authorization requirements for nickel catalyst residues accelerate migration toward electrodeposition routes bypassing hydrogen-reduction entirely. EFSA evaluation protocols for novel iron compounds freeze reformulation pipelines among premix blenders. BASF SE anchors European premix formulation expertise through Ludwigshafen-based operations.
Nigeria
WHO iron supplementation guidelines filter into Federal Ministry of Health procurement standards for wheat flour fortification. West African milling cooperatives accelerate adoption of sachet-compatible micro-dose formats. Lagos-Kano distribution corridors channel electrolytic iron shipments from Indian suppliers into northern flour mill networks.
China
SAMR food additive standards govern import eligibility for electrolytic iron powders entering domestic fortification programs. Yangtze River Delta chemical clusters host reduced iron production serving regional feed and industrial applications. Cathay Industries Group exemplifies pigment-specialist diversification into food-grade mineral processing.
Food Grade Iron Powder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The vendor base stratifies into three tiers: electrolytic production specialists, premix formulation integrators, and research-grade purity suppliers. Consolidation pressure concentrates among mid-scale hydrogen-reduction mills facing scrap feedstock volatility. Dominant competitive moves include geographic expansion into underpenetrated West African markets and portfolio diversification toward dual-fortification premix combinations.
Within the electrolytic specialization tier, Industrial Metal Powders India Pvt. Ltd. and Rio Tinto Metal Powders exemplify production-scale anchoring in South Asian and North American supply bases respectively. BASF SE occupies the formulation-integrator position, leveraging premix expertise to control European nutraceutical channels. American Elements represents the research-grade purity archetype, serving bioavailability study demands with documented particle-size distribution control.
| Leading Market Players |
|---|
| Industrial Metal Powders India Pvt. Ltd. |
| Ashland Inc. |
| American Elements |
| Rio Tinto Metal Powders |
| Belmont Metals Inc. |
| BASF SE |
| Cathay Industries Group |
| Iron Powder Corporation |
| Spectrum Chemical Mfg. Corp. |
| Others |
Supply Flow & Price Mechanics
Electrolytic-spherical grade divergence from hydrogen-reduced powder manifests in parallel pricing tiers and supply chain architectures across India, Germany, and Nigeria. Premium electrolytic grades command contract-based long-term offtake structures tied to FSSAI and WHO certification ladders, while commodity reduced iron trades on spot-indexed ferrous scrap feedstock costs. This bifurcation concentrates procurement power among certified electrolytic suppliers serving government rice fortification tenders, while scrap-dependent mills face margin volatility without channel differentiation.
Pricing Analysis
Margin tightening in hydrogen-reduced powder reflects ferrous scrap price spikes and nickel catalyst residue compliance costs under REACH authorization requirements. Three-tier pricing structure across premium electrolytic, standard reduced, and economy feed-grade levels tracks certification intensity and particle-size distribution control. Cost-down pressure on reduced iron accelerates because Nigerian and Indonesian milling cooperatives prioritize WHO-aligned purity thresholds over dissolution performance. State food corporations in India exhibit lowest price sensitivity due to consolidated tender volumes, while West African cooperative buyers demonstrate highest elasticity to per-kilogram premix costs.
Supply Chain Analysis
Regional distribution centers in Mumbai-Ahmedabad, Ludwigshafen, and Lagos-Kano form hub-and-spoke patterns channeling electrolytic iron into government mill networks. Supply concentrates in India, Germany, and China as primary production nodes, with secondary processing in Nigeria and Indonesia. Raw material dependencies span ferrous scrap feedstock, nickel catalyst systems, and electrolytic cell anode materials. Single-source vulnerability sits with South Asian electrolytic capacity clusters exposed to regional power grid instability. Distribution runs through wholesale tender aggregation platforms and specialty chemical distributors serving premix manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI-mandated rice fortification creates a cost-of-compliance moat that rewards certified electrolytic suppliers with predictable offtake volumes and defensible margin structures against uncertified competitors.
For Market Incumbents: Anticipate scrap feedstock volatility and REACH nickel residue restrictions by securing long-term ferrous scrap contracts and accelerating electrodeposition capacity expansion in Maharashtra and Gujarat. Dual-fortification premix R&D investment in iron-zinc combinations offers channel control against BASF SE's European formulation dominance. Electrochemical engineering talent scarcity from battery materials sector competition threatens production optimization capabilities. For New Entrants and Emerging Players: West African milling cooperatives in Ghana and Senegal represent the most penetrable buyer archetype, with underpenetrated fortification infrastructure and sachet-compatible micro-dose format demand unmet by incumbent bulk suppliers. Direct-to-mill digital procurement platforms bypass traditional distributor markups in Indian state tender systems. Online retail channel penetration for rural cooperative access offers lowest competitive density entry path. For Investors and Strategic Acquirers: Re-rating potential sits with electrolytic production specialists possessing FSSAI and WHO dual certification given India's compulsory rice fortification program expansion. Five-to-ten year viability favors electrodeposition technology holders over hydrogen-reduction legacy assets facing feedstock and regulatory headwinds. EFSA novel iron compound evaluation protocol resolution signals inflection timing for European premix supplier consolidation targets.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolytic Capacity Expansion | Mumbai-Ahmedabad production clusters scale to meet FSSAI tender volume commitments. |
| Backward Integration into Scrap Supply | Long-term ferrous scrap contracts insulate hydrogen-reduced mills from price volatility. |
| Dual-Fortification Premix Development | Iron-zinc combinations reduce Nigerian government program delivery costs. |
| Digital Procurement Platform Launch | Direct state rice mill access bypasses distributor markups for smaller electrolytic suppliers. |
| EFSA Novel Compound Certification | European premix blender qualification unlocks reformulation pipeline frozen by pending protocols. |
Methodological Framework
SEC 10-K filings, FSSAI fortification standard documents, and WHO iron supplementation guidelines formed the secondary backbone for supply-side capacity and regulatory requirement mapping. Primary interviews with electrolytic plant managers, premix manufacturer procurement leads, and state food corporation tender officers validated production batch scheduling and contract structure assumptions. Customs trade data and Indian state tender aggregation records supported bottom-up volume triangulation against top-down market sizing across the analysis window.
Historical trendline analysis of electrolytic and hydrogen-reduced iron powder shipment patterns informed growth trajectory modeling across product type, application, and end user segmentation dimensions. CAGRs were derived through regression analysis of procurement volume expansion in government-mandated fortification programs and dissolution rate improvement curves from particle engineering advances. Forecast inputs incorporated FSSAI rice fortification rollout timelines and EFSA novel compound evaluation status.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ferrous scrap price cycles, regional power grid reliability in South Asia, and EFSA protocol finalization timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Food Texture Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
India Food Hydrocolloids Market