
 Linoleic Acid Market | 2026-2036
Linoleic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Linoleic Acid Market Analysis
Personal care and nutraceuticals is realigning the linoleic acid value chain as cosmetic formulators prioritize barrier-repair lipids. BASF SE leverages its oleochemicals platform to sustain European supply leadership. Cargill, Incorporated anchors North American feedstock security through its oilseed processing network. Kerry Group plc differentiates via encapsulation technologies for functional food applications.
Linoleic acid is an omega-6 polyunsaturated fatty acid with an 18-carbon chain and two cis double bonds at positions 9 and 12, typically derived from safflower, sunflower, or corn oil through hydrolysis and fractional distillation; its primary industrial purpose centers on emollient functionality in topical formulations and as an essential fatty acid precursor in nutritional products. Refined linoleic acid commands premium positioning in pharmaceutical-grade applications where oxidation stability and peroxide value thresholds determine qualification. Dietary supplements represent the fastest-expanding application segment as consumers shift toward lipid-based wellness protocols. The food industry end-user channel maintains volume dominance through bulk procurement of crude and distilled grades for fortification programs.
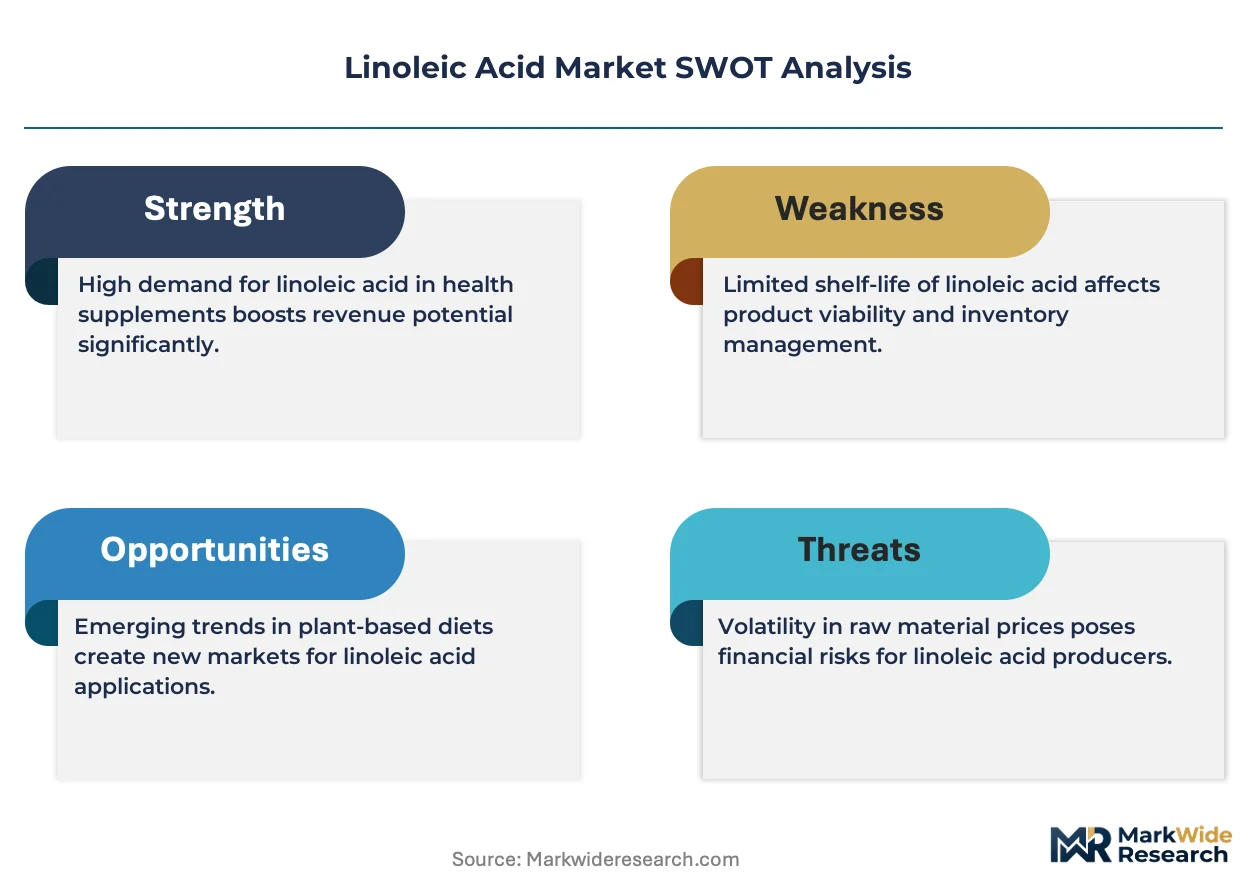
REACH registration requirements in Europe, FDA food additive regulations in the United States, and FSSAI labeling mandates in India collectively elevate compliance costs while screening out non-certified suppliers. The EU Green Deal's bio-based content targets are redirecting capital toward enzymatic interesterification platforms that reduce solvent dependence. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation requirements and certification timelines.
Market Dynamics
Enzymatic interesterification platforms are displacing solvent-based extraction systems as the EU Green Deal's bio-based content targets force capital reallocation across European oleochemical infrastructure.
Growth Catalysts
- Nutraceuticals demand surge:Functional food formulators in Germany and India are expanding encapsulation capacity for omega-6 fortified products. Dietary supplement manufacturers prioritize lipid-based wellness protocols.
- REACH registration compliance:The EU framework tightens purity specifications for pharmaceutical-grade applications. Certified suppliers capture premium positioning as non-registered competitors exit.
- Plant-based oil extraction advances:Fractional distillation improvements in safflower and sunflower processing raise yield rates. Corn oil hydrolysis refiners in China deploy continuous processing systems.
Market Restraints
- Feedstock price volatility:Sunflower and safflower oil costs fluctuate with agricultural yield cycles in Ukraine and Argentina. Processors lack long-term hedging mechanisms for oilseed procurement.
- Supply concentration risk:North American feedstock security depends on a limited number of oilseed crushing networks. Regional weather events disrupt seed availability.
- Peroxide stability limitations:Refined linoleic acid degrades under oxidative stress, restricting shelf-life for cosmetic formulations. Stabilizer additives raise formulation costs.
Strategic Opportunities
- Indian functional food penetration:FSSAI labeling mandates create certification barriers that favor organized suppliers. Local encapsulation partnerships unlock distribution through Ayurvedic wellness channels.
- Cosmeceutical barrier-repair applications:Dermatology-grade emollient demand from South Korean and Japanese formulators outpaces domestic supply. Lipid matrix technologies enable premium positioning.
- EU Green Deal bio-mandates:Enzymatic processing incentives redirect R&D budgets toward solvent-free platforms. Early adopters secure preferential access to carbon credit markets.
Industry Challenges
- Fractional distillation talent scarcity:Specialized process engineers with oleochemical purification expertise command premium compensation. Technical training programs lag industry expansion timelines.
- Multi-jurisdiction certification complexity:Simultaneous FDA food additive, REACH registration, and FSSAI compliance extends product launch cycles. Documentation requirements strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linoleic Acid Market |
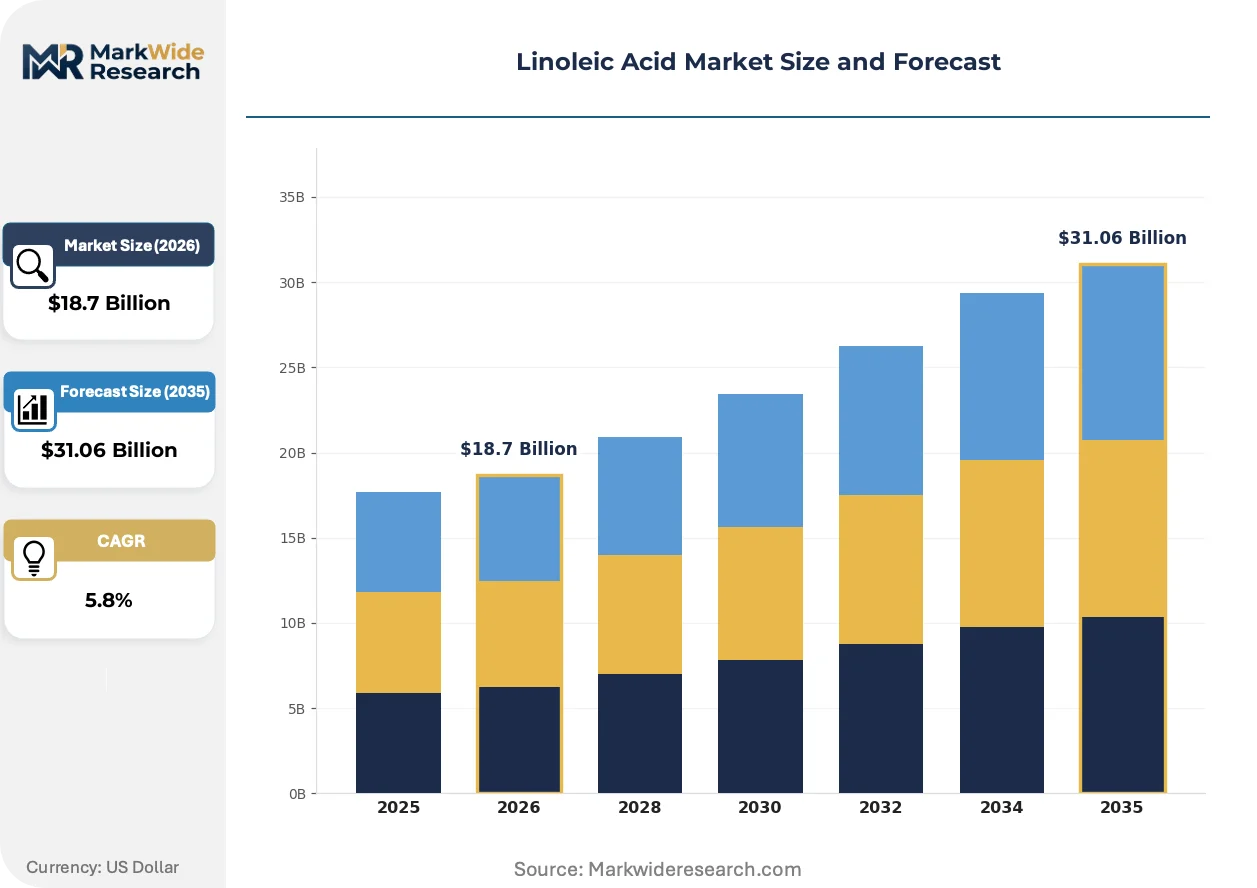
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Linoleic Acid, Crude Linoleic Acid, Distilled Linoleic Acid, Linoleic Acid Ethyl Ester Application: Cosmetics, Functional Foods, Dietary Supplements, Pharmaceuticals End User: Food Industry, Personal Care, Nutraceuticals, Healthcare Form: Liquid, Powder,Emulsion, Capsules |
| Companies Covered | Wilmar International Limited, Nutrien Ltd., BASF SE, Cayman Chemical Company, KANTO CHEMICAL CO.,INC., Cargill, Incorporated, Kerry Group plc, Junsei Chemical Co.,Ltd., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linoleic Acid Market Emerging Trajectories
Biocatalytic processing methods and precision fermentation routes are reshaping how manufacturers secure omega-6 purity grades. Formulation science advances enable novel delivery mechanisms for sensitive lipid matrices.
Enzymatic interesterification technology enables solvent-free linoleic acid production with reduced thermal degradation. Cosmetic formulators in France and Germany adopt these biocatalytic routes to meet EU Green Deal bio-content thresholds. The technology is converging with carbon accounting platforms that verify supply chain emissions for premium cosmetic certifications.
REACH registration requirements now mandate full toxicological dossiers for imported linoleic acid derivatives entering EU cosmetic and pharmaceutical channels. Small-scale Asian exporters face documentation costs that exceed annual revenue. Pharmaceutical-grade suppliers in Switzerland and Germany consolidate market position through pre-registered substance portfolios.
Direct procurement contracts between nutraceutical brands and oilseed processors are replacing multi-tier distributor networks. Bulk buyers in China and India negotiate specification-locked supply agreements with crushing facilities. This disintermediation concentrates volume with vertically integrated processors capable of certifying chain-of-custody from seed to refined acid.
Linoleic Acid Market Segmentation
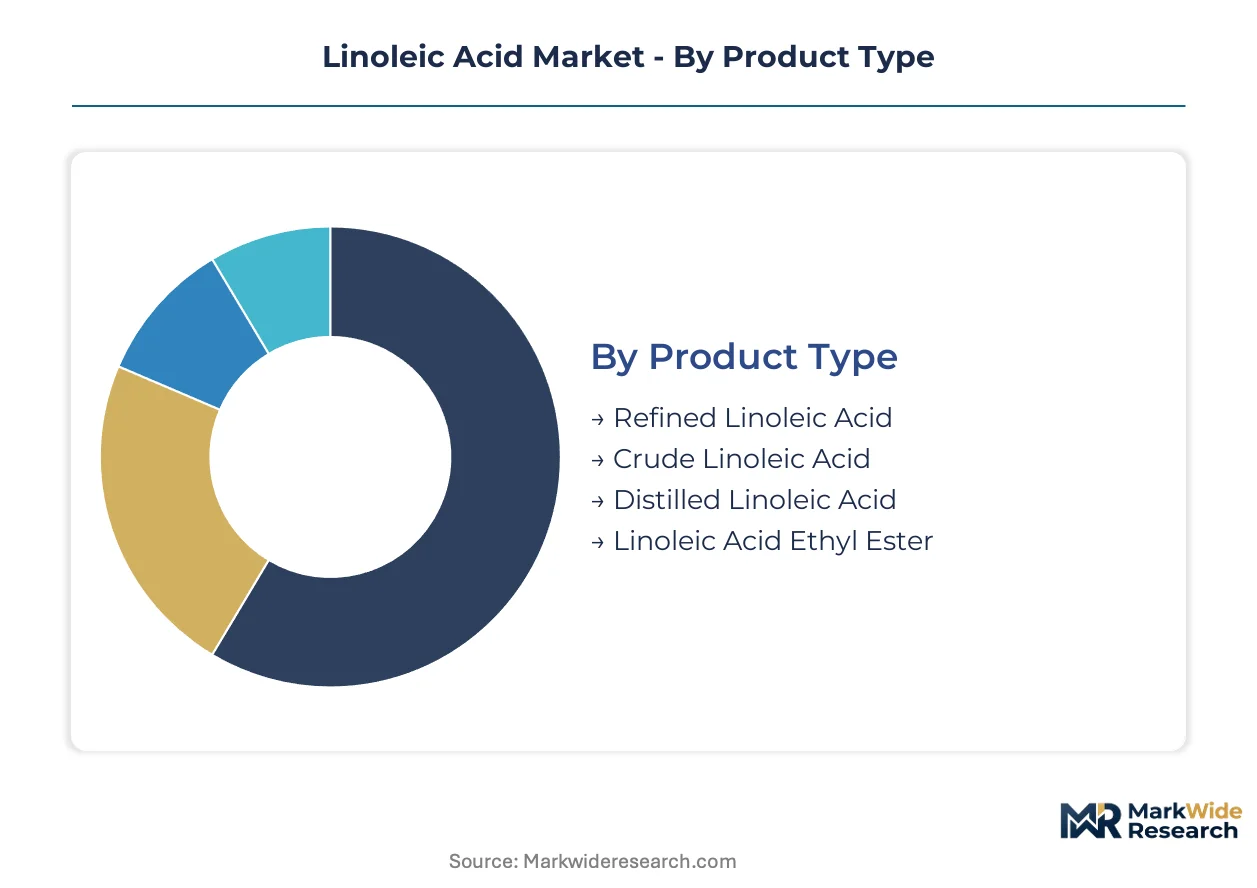
Linoleic acid procurement patterns diverge sharply across purity grades and delivery formats. Pharmaceutical and cosmetic formulators enforce specification-locked supply agreements that reshape competitive positioning within each tier.
Product Type:
Customization intensity spans from commodity crude streams to pharmaceutical-grade refined specifications, with certification thresholds determining supplier eligibility.
- Refined Linoleic Acid:Pharmaceutical-grade purity with peroxide value thresholds below industry baselines. Cosmetic formulators in Germany and Switzerland specify this grade for barrier-repair emulsions where oxidation stability determines shelf-life performance.
- Crude Linoleic Acid:Unfractionated hydrolysis output containing phospholipids and sterol contaminants. Bulk food fortification programs in India and China absorb volume through direct crushing facility contracts that bypass distillation costs.
- Distilled Linoleic Acid:Intermediate purity achieved through fractional separation without full refinement. Mid-tier nutraceutical encapsulators specify this grade for cost-sensitive omega-6 supplements.
- Linoleic Acid Ethyl Ester:Esterified derivative with enhanced oxidative stability for specialized pharmaceutical delivery systems. Lipid matrix technologies in Japan and South Korea utilize this form for controlled-release formulations.
Most installed capacity flows through Crude Linoleic Acid. Expansion is steepest in Refined Linoleic Acid as REACH registration requirements screen out uncertified suppliers.
Application:
End-use differentiation tracks regulatory burden and formulation complexity, with cosmetic and pharmaceutical channels commanding premium positioning against bulk food additives.
- Cosmetics:Emollient functionality in dermatology-grade barrier-repair products. South Korean and Japanese formulators specify high-oleic sunflower-derived grades for K-beauty lipid matrix technologies.
- Functional Foods:Omega-6 fortification of dairy alternatives and infant nutrition. FSSAI labeling mandates in India create certification barriers favoring organized suppliers with documentation bandwidth.
- Dietary Supplements:Encapsulated softgels and lipid-based wellness protocols. German and Indian manufacturers expand encapsulation capacity to capture consumer shifts toward essential fatty acid supplementation.
- Pharmaceuticals:Active pharmaceutical ingredient precursor and parenteral emulsion component. Swissmedic and EMA requirements enforce full toxicological dossiers that consolidate supply among pre-registered European producers.
Volume concentration sits with Functional Foods. Value expansion concentrates fastest in Pharmaceuticals as regulatory compliance costs elevate pricing power.
End User:
Customer archetypes range from price-sensitive commodity processors to specification-intensive formulators with locked supply agreements and chain-of-custody requirements.
- Food Industry:Bulk procurement of crude and distilled grades for edible oil fortification and bakery applications. Processors in China negotiate long-term crushing contracts that secure sunflower and safflower seed flows.
- Personal Care:Cosmetic manufacturers prioritizing barrier-repair lipids and clean-label emollient positioning. French and German formulators adopt enzymatic interesterification routes to meet EU Green Deal bio-content thresholds.
- Nutraceuticals:Functional food and supplement brands requiring encapsulation-ready specifications with oxidation stability guarantees. Direct procurement contracts displace distributor networks as brands seek verified chain-of-custody documentation.
- Healthcare:Hospital and clinical nutrition suppliers demanding pharmaceutical-grade purity for parenteral and enteral applications. REACH-registered suppliers capture this channel as non-compliant competitors exit.
Food Industry maintains volume dominance. Nutraceuticals climbs the fastest as encapsulation partnerships unlock Ayurvedic and direct-to-consumer distribution channels.
Form:
Physical state selection reflects stability requirements, dosing precision, and integration complexity across topical, oral, and parenteral delivery pathways.
- Liquid:Bulk oil format for food fortification and cosmetic oil-phase incorporation. Corn and safflower processors in China deploy continuous liquid handling systems for industrial-scale customers.
- Powder:Microencapsulated or spray-dried formats for dry blend integration and extended shelf-life. Functional food manufacturers specify powder forms for beverage and bakery applications where oil-phase mixing is impractical.
- Emulsion:Aqueous-dispersible lipid delivery systems for cosmetic serums and pharmaceutical parenterals. Lipid matrix technologies enable premium positioning in dermatology-grade formulations.
- Capsules:Pre-dosed softgel and hard-shell formats for dietary supplement retail channels. Encapsulation technology providers in India and Germany differentiate through enteric coating and controlled-release capabilities.
Liquid commands installed capacity share. Capsules gain share fastest as direct-to-consumer supplement brands scale encapsulated product portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting linoleic acid production toward jurisdictions where REACH-equivalent compliance costs remain lower, while EU-registered suppliers capture premium pharmaceutical-grade positioning through pre-certified substance portfolios.
China
Sunflower and corn oil processors in Shandong and Hebei provinces deploy continuous hydrolysis systems to supply crude grades for Indian nutraceutical encapsulators. SAMR food additive standards govern domestic fortification programs. Tianjin's oleochemical cluster hosts fractional distillation facilities serving Japanese cosmetic formulators with intermediate-purity outputs.
Germany
REACH-registered suppliers in North Rhine-Westphalia consolidate pharmaceutical-grade market access as non-compliant Asian exporters face documentation cost barriers. ECHA registration requirements enforce full toxicological dossiers for cosmetic and parenteral applications. BASF SE's Ludwigshafen oleochemicals platform anchors European supply leadership through enzymatic interesterification capacity.
India
Functional food manufacturers in Maharashtra and Gujarat expand encapsulation partnerships with Ayurvedic wellness distributors following FSSAI labeling mandate implementation. CDSCO pharmaceutical regulations govern active ingredient precursor qualifications. Hyderabad's lipid technology cluster develops microencapsulation formats for dry-blend beverage applications.
United States
Midwest oilseed crushing networks in Iowa and Illinois secure long-term supply contracts with dietary supplement brands seeking verified chain-of-custody documentation. FDA food additive regulations and GRAS self-affirmation pathways structure compliance requirements. Cargill's Minnesota processing infrastructure anchors North American feedstock security through backward integration into safflower and sunflower procurement.
Japan
Cosmetic formulators in Osaka and Tokyo specify high-oleic sunflower-derived grades for K-beauty-influenced lipid matrix technologies. PMDA pharmaceutical regulations enforce purity thresholds for parenteral emulsion components. Kanto region biocatalysis specialists partner with German enzymatic technology providers to meet domestic clean-label emollient demand.
Linoleic Acid Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade channels consolidating around REACH-registered European suppliers while crude and distilled grades fragment across Asian oilseed processors. Three archetypes dominate: vertically integrated agribusiness conglomerates controlling seed-to-acid supply chains; specialty oleochemical houses with enzymatic purification capabilities; and regional crushing cooperatives serving bulk food fortification through direct procurement contracts. Competitive moves center on backward integration into oilseed origination and certification-driven portfolio rationalization.
Among Asia-Pacific agribusiness conglomerates, Wilmar International Limited exemplifies scale-driven seed crushing and fractionation capabilities. Specialty chemical positioning is represented by Cayman Chemical Company and KANTO CHEMICAL CO.,INC., which occupy roles within analytical-grade and reagent-tier supply channels. These three entities represent distinct competitive vectors without implying specific strategic coordination or market share claims.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Nutrien Ltd. |
| BASF SE |
| Cayman Chemical Company |
| KANTO CHEMICAL CO.,INC. |
| Cargill, Incorporated |
| Kerry Group plc |
| Junsei Chemical Co.,Ltd. |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal bio-content thresholds gate qualified supply and premium-tier pricing access, as enzymatic interesterification platforms displace solvent-based systems and carbon credit verification becomes a cost of market entry. REACH-registered suppliers in Germany and Switzerland capture pharmaceutical-grade premiums while non-compliant Asian exporters face documentation barriers that compress their pricing power.
Pricing Analysis
Distributor margin layers have compressed as direct procurement contracts between nutraceutical brands and oilseed processors displace multi-tier networks. Three-tier pricing structure across pharmaceutical-grade refined, intermediate distilled, and commodity crude levels reflects certification burden and oxidation stability guarantees. Cost compression in crude grades intensifies because Indian and Chinese bulk buyers negotiate specification-locked supply agreements that bypass traditional markups. Food industry processors exhibit highest price sensitivity, while cosmetic formulators in South Korea and Japan accept premiums for dermatology-grade emollient specifications.
Supply Chain Analysis
Refurbishment and reprocessing flows remain minimal given linoleic acid's oxidative degradation profile, though spent oil recovery from food processing is gaining traction in EU circular economy pilots. Supply concentrates in China, India, and Germany, with Shandong province crushing networks and North Rhine-Westphalia oleochemical platforms anchoring regional output. Feedstock draws from Ukrainian and Argentine sunflower seed flows, Chinese corn oil streams, and safflower origination networks. Single-source vulnerability runs through Black Sea agricultural corridors where weather and geopolitical disruptions constrain seed availability. Distribution runs through vertically integrated processors capable of certifying chain-of-custody from seed to refined acid.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on enzymatic processing cost curves flattening as scale economies emerge, while premium-tier shifts toward pharmaceutical-grade and cosmeceutical applications elevate average selling prices for qualified suppliers.
For Market Incumbents: Hedge feedstock exposure through long-term crushing contracts with Ukrainian and Argentine origination networks before planting season volatility escalates. Expand enzymatic interesterification capacity in Ludwigshafen or comparable European hubs to capture EU Green Deal carbon credit premiums. Defend against Asian encapsulation technology challengers by locking multi-year supply agreements with German and Indian nutraceutical brands. For New Entrants and Emerging Players: Launch via direct-to-Ayurvedic-wellness-channel partnerships in Maharashtra and Gujarat, bypassing established distributor networks that incumbents control. Target Indian functional food penetration where FSSAI labeling mandates have screened out uncertified competitors and created white-space for organized suppliers with documentation bandwidth. Lead with microencapsulation format differentiation for dry-blend beverage applications. For Investors and Strategic Acquirers: Roll-up economics work for specialty oleochemical houses with enzymatic purification capabilities because REACH registration costs have stranded non-compliant Asian exporters and created acquisition targets at compressed multiples. Five-to-ten year viability favors pre-registered substance portfolios with toxicological dossiers already filed. Watch enzymatic technology licensing velocity as the inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Origination | Cargill's Minnesota infrastructure demonstrates how crushing network control secures feedstock against Black Sea supply shocks. |
| Enzymatic Interesterification Scale-Up | BASF's Ludwigshafen platform validates solvent-free production routes that qualify for EU Green Deal carbon credits. |
| REACH Registration Portfolio Buildout | Swissmedic and EMA requirements consolidate pharmaceutical-grade supply among pre-registered European producers. |
| Encapsulation Technology Partnership | Kerry Group's functional food applications show how lipid matrix differentiation unlocks Ayurvedic distribution channels. |
| Direct Procurement Contract Structuring | Chinese and Indian bulk buyers now negotiate specification-locked agreements that displace multi-tier distributor networks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oleochemical plant managers, nutraceutical procurement leads, cosmetic formulation R&D directors, and oilseed crushing facility operators with secondary validation. Customs and trade data, ECHA registration databases, FSSAI labeling compliance records, and SEC filings from listed agribusiness conglomerates anchored supply-side estimates. Bottom-up capacity assessments and top-down demand aggregation triangulated market sizing.
Historical reference periods anchored the projection horizon to observed capacity utilization trends and regulatory implementation timelines across the analysis window. Segmentation modeling spanned purity grade tiers, application channels, end-user archetypes, and physical delivery formats. CAGRs derived from installed capacity expansion schedules, feedstock yield projections, and encapsulation technology adoption curves. Oxidative stability specifications and peroxide value thresholds informed pharmaceutical-grade demand elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Black Sea agricultural disruption or accelerated EU Green Deal bio-mandate enforcement. Periodic stress-testing of base assumptions is recommended, particularly regarding enzymatic processing cost trajectories and REACH-equivalent regulation diffusion beyond European jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market