
 Europe Food Hydrocolloids Market | 2026-2036
Europe Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Hydrocolloids Market Foresight
Direct procurement channels between hydrocolloid suppliers and European food manufacturers is reconfiguring as scale buyers bypass traditional distributors for contracted volumes. Cargill, Incorporated leverages its integrated agricultural supply chain to secure raw material streams for pectin and xanthan gum production across the continent. Kerry Group PLC anchors its position through specialized texture systems tailored to clean-label bakery and dairy reformulations. DuPont de Nemours competes via microbial fermentation expertise that sustains consistent xanthan gum output independent of seasonal crop variability.
Europe food hydrocolloids encompass water-soluble biopolymers—predominantly polysaccharides and proteins—that hydrate in aqueous systems to modify viscosity, gelation, and mouthfeel at concentrations typically ranging from 0.1% to 2.0% by weight. These functional ingredients serve primarily as stabilizers, thickeners, and emulsifiers in processed foods where texture consistency and shelf-life extension determine commercial viability. Gelatin retains mature volume leadership across dairy and confectionery applications despite sustained substitution pressure from plant-derived alternatives. Pectin captures accelerated growth trajectories within beverage and sauce segments where low-sugar formulations require rebuilt rheological profiles. Xanthan gum occupies defensive margin pools in gluten-free bakery systems where its shear-thinning behavior proves technically irreplaceable.
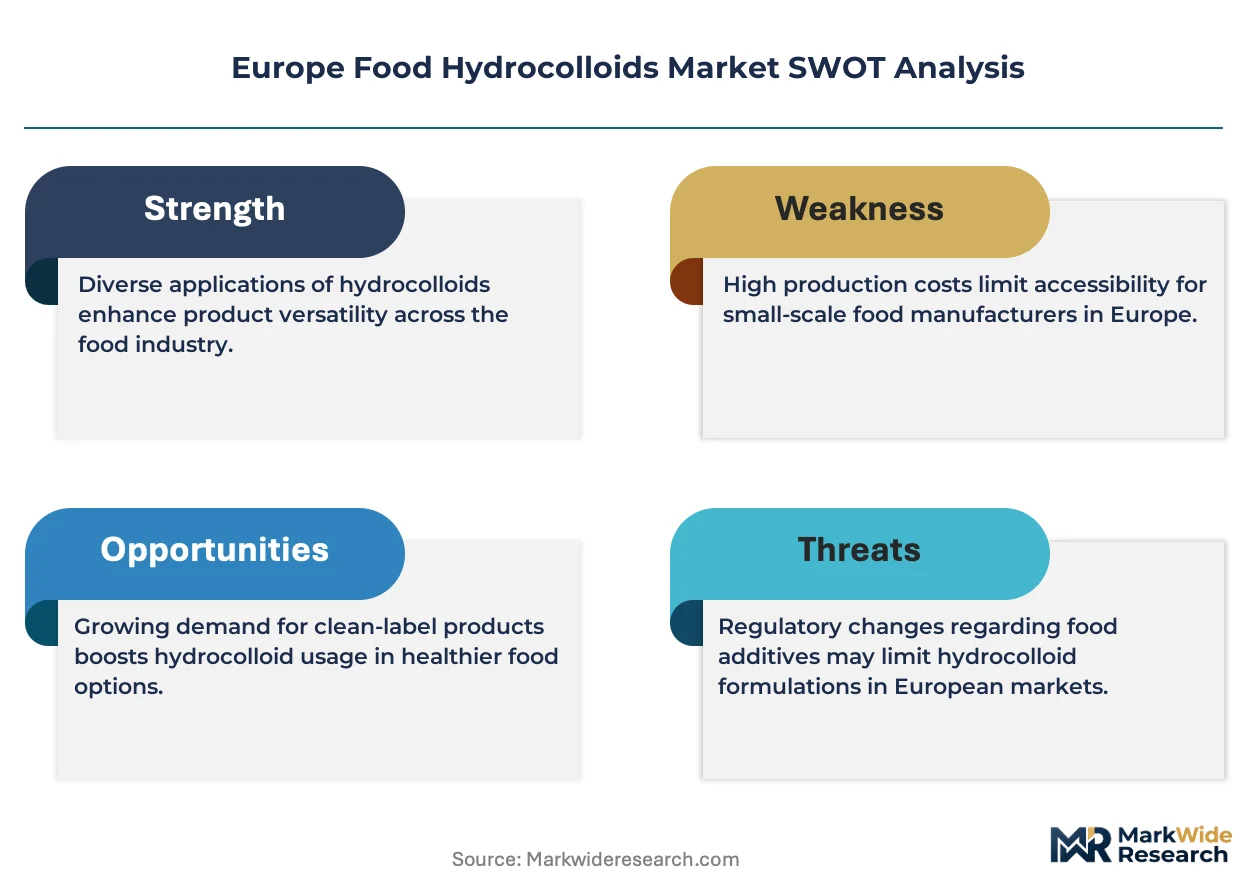
EFSA's re-evaluated food additive safety protocols and the EU Green Deal's biopolymer sourcing mandates collectively reshape formulation roadmaps and raw material qualification pathways for hydrocolloid suppliers. REACH compliance obligations and CE-marked processing equipment standards further filter market access, favoring producers with documented supply chain traceability and controlled substance management systems. Stakeholders must monitor evolving EFSA opinions on carrageenan and modified cellulose classifications while calibrating R&D portfolios toward label-friendly alternatives that preempt regulatory displacement.
Market Dynamics
EFSA's additive re-evaluations and the EU Green Deal's biopolymer mandates are forcing simultaneous reformulation of texture systems and raw material qualification pathways across European food manufacturing.
Growth Catalysts
- EU Green Deal biopolymer incentives:Direct procurement subsidies for plant-derived stabilizers redirect supply chains toward pectin and cellulose derivatives sourced from European agricultural waste streams.
- Clean-label dairy reformulations:German and French processors rebuild viscosity profiles in reduced-fat yogurts using refined carrageenan and pectin blends that replace modified starches.
- Gluten-free bakery expansion:Xanthan gum demand concentrates in Belgian and Dutch industrial bakery clusters where shear-thinning behavior proves technically irreplaceable in wheat-free dough systems.
Market Restraints
- Seaweed supply concentration:Carrageenan raw material dependence on Southeast Asian harvesting regions exposes European formulators to climate-driven harvest volatility and shipping cost spikes.
- EFSA regulatory friction:Pending safety opinions on degraded carrageenan classifications force preemptive reformulation investments before final determinations, compressing R&D timelines.
- Gelatin substitution ceiling:Plant-based alternatives fail to replicate the specific melt-profile and foaming behavior required in premium European confectionery applications, limiting displacement rates.
Strategic Opportunities
- Eastern European penetration gap:Polish and Romanian food processors remain underpenetrated by specialized texture system suppliers, presenting first-mover expansion potential for hydrocolloid blend providers.
- Fermentation-derived pectin:Microbial production methods bypass seasonal citrus peel supply constraints, enabling consistent output for beverage stabilizer contracts.
- Direct supplier-manufacturer contracting:Scale buyers in the Netherlands and Belgium bypass traditional ingredient distributors, creating margin capture opportunities for hydrocolloid producers with integrated logistics capabilities.
Industry Challenges
- REACH compliance complexity:Registration dossiers for novel biopolymer modifications require 18-24 month evaluation windows, delaying product launches and tying up regulatory affairs personnel.
- Application-specific formulation expertise:Shortages of food rheologists who understand hydrocolloid synergies in low-sugar systems constrain technical service capacity for clean-label reformulation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Hydrocolloids Market |
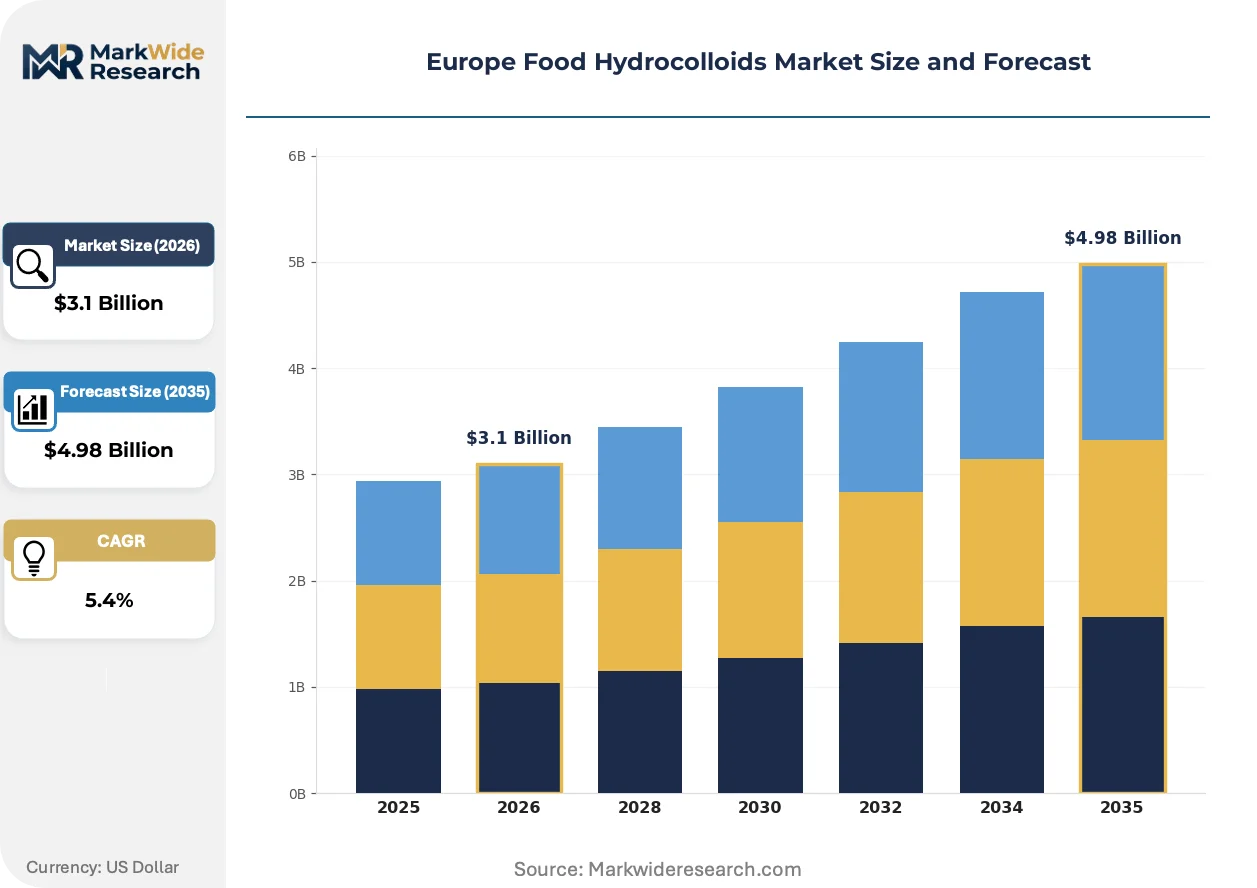
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Agar, Xanthan Gum, Pectin Application: Dairy Products, Bakery, Beverages, Sauces End User: Food Manufacturers, Restaurants, Retail, Catering Services Form: Powder, Liquid, Granules, Paste |
| Companies Covered | Cargill, Incorporated, CP Kelco, DuPont de Nemours, Koninklijke DSM N.V., Kerry Group PLC, Rousselot, Archer-Daniels-Midland Company, Tate & Lyle PLC, Ingredion Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Hydrocolloids Market Shifts & Advancements
Digital formulation platforms and precision fermentation are compressing development cycles for texture systems while regulatory pressure accelerates substitution away from animal-derived stabilizers.
Precision fermentation for xanthan gum production is virtualizing the traditional agricultural input model. Industrial biotechnology firms now cultivate Xanthomonas campestris in controlled bioreactors, eliminating dependence on corn or wheat feedstock availability. This shift decouples hydrocolloid output from commodity crop price cycles and regional harvest variability.
EFSA's ongoing additive re-evaluation program is compressing the approved substance list for processed foods. The regulator's tightened safety assessment protocols for modified cellulose derivatives force manufacturers to pre-qualify alternative stabilizers. Dairy and sauce segments respond fastest, accelerating trials of native starch and citrus fiber blends.
Buyer concentration among European retail private-label manufacturers is shortening ingredient qualification cycles. Large-scale processors in Germany and France now demand 90-day formulation turnaround from hydrocolloid suppliers, replacing traditional 12-month development partnerships. This compression favors suppliers with in-house pilot-scale application labs located near customer R&D centers.
Europe Food Hydrocolloids Market Segmentation
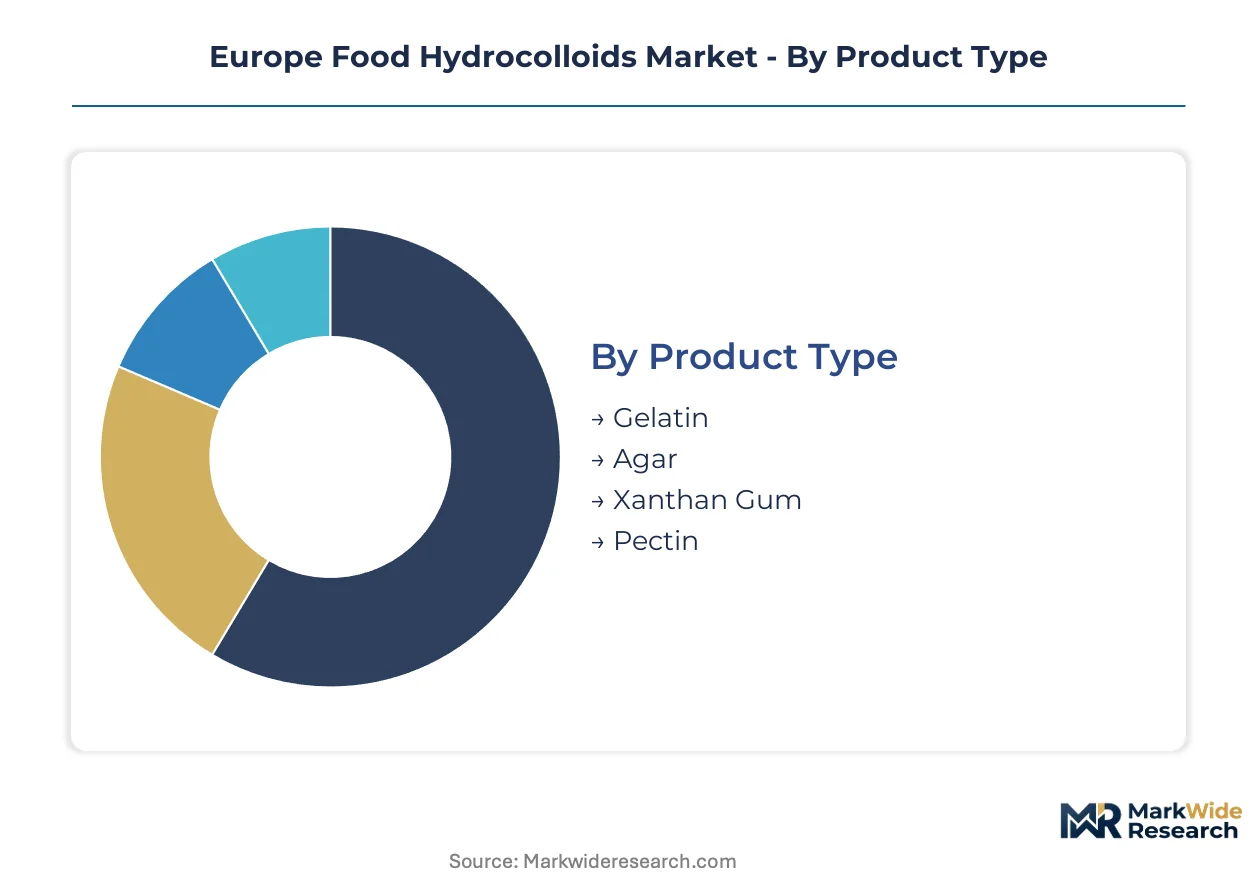
Europe food hydrocolloids segment across four functional dimensions that determine procurement patterns and formulation priorities. Product chemistry dictates performance ceilings in specific applications, while end-user scale shapes volume contracting structures and technical service intensity.
Product Type:
Use-case spectra range from thermoreversible gels in confectionery to shear-thinning stabilizers in beverage emulsions, with each hydrocolloid occupying distinct rheological niches.
- Gelatin:Collagen-derived protein forms thermoreversible gels with unique melt-in-mouth profiles. German and French confectionery houses anchor mature demand despite plant-based substitution pressure from pectin in gummy candies.
- Pectin:Citrus peel and apple pomace polysaccharides build viscosity in low-sugar beverage systems where reduced solids require rebuilt mouthfeel. Dutch juice processors and French sauce manufacturers drive fastest adoption curves amid clean-label reformulations.
- Xanthan Gum:Microbial fermentation polysaccharide delivers pseudoplastic flow behavior critical for gluten-free bakery doughs in Belgian industrial clusters.
- Agar:Seaweed-extracted galactan serves niche vegetarian gel applications in premium Spanish and Italian foodservice channels.
The dominant share belongs to Gelatin, while Pectin is closing the gap fastest.
Application:
Cost tier stratification separates commodity texture systems from specialized stabilizer blends commanding formulation service premiums.
- Dairy Products:Yogurt and processed cheese applications demand refined carrageenan-pectin synergies for fat replacement and syneresis control. German dairy cooperatives and French industrial processors concentrate procurement volumes.
- Bakery:Gluten-free bread and cake systems rely on xanthan gum-cellulose gum combinations for dough elasticity and crumb structure. Belgian and Dutch industrial bakeries represent the densest customer cluster.
- Beverages:Pulp suspension and cloud stability in fruit juices and flavored drinks employ low-methoxyl pectin and modified cellulose derivatives.
- Sauces:Emulsion stability in mayonnaise and dressings uses xanthan gum and propylene glycol alginate for freeze-thaw tolerance.
Dairy Products captures the largest volume commitment, though Bakery demonstrates the steepest expansion trajectory as wheat-free formulations proliferate.
End User:
Customer type determines contract structure complexity, with scale manufacturers demanding integrated technical service while fragmented foodservice channels favor distributor intermediaries.
- Food Manufacturers:Industrial processors in Germany, France, and the Netherlands negotiate direct supply agreements with documented traceability and quarterly volume commitments. These buyers command application laboratory support and rapid formulation turnaround.
- Restaurants:High-end European dining establishments and chain operators source specialized hydrocolloid blends for molecular gastronomy and consistent sauce textures.
- Retail:Private-label packaged food producers across Poland and Romania represent underpenetrated growth territory for standard-grade stabilizer suppliers.
- Catering Services:Institutional foodservice operators in Scandinavian markets prioritize cost-optimized powder blends for large-batch preparation.
Food Manufacturers command the dominant procurement volume, with Retail emerging as the fastest-closing segment as Eastern European private-label expansion accelerates.
Form:
Supply concentration in powder processing favors producers with spray-drying and milling capabilities located near raw material sources.
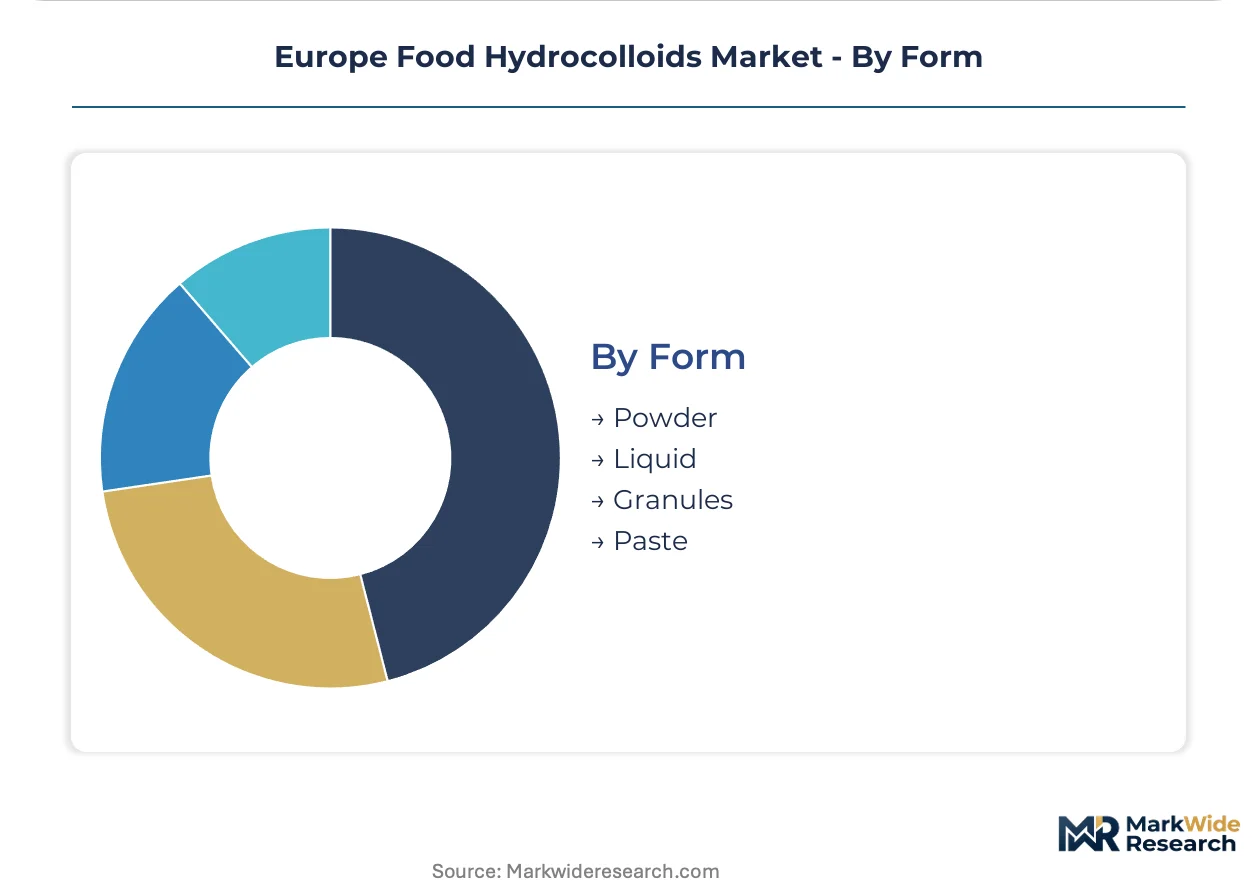
- Powder:Standardized particle size distributions enable precise dosing in automated manufacturing lines. This form dominates dairy and bakery applications across Western European production facilities.
- Liquid:Pre-hydrated colloidal dispersions eliminate dust handling and hydration time for high-throughput beverage processors.
- Granules:Low-dust agglomerated particles improve flowability in manual weighing operations common in smaller food manufacturers.
- Paste:High-solids preparations serve specialized confectionery and sauce applications requiring immediate functionality without hydration delays.
Powder retains the volume leadership position, while Liquid is gaining share fastest among large-scale beverage processors seeking operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dutch and Belgian procurement clusters while Eastern European processors absorb cost premiums for specialized texture systems. German dairy cooperatives leverage direct supplier contracts to compress ingredient qualification cycles. Polish and Romanian food manufacturers remain exposed to distributor markups due to fragmented demand aggregation.
Germany
Dairy cooperatives in Bavaria and Lower Saxony drive refined carrageenan-pectin procurement for reduced-fat yogurt reformulations. EFSA's additive re-evaluation protocols force preemptive reformulation investments ahead of final safety determinations. The Ingredient Innovation Hub around Frankfurt anchors technical service capacity for clean-label texture system development.
France
Sauce manufacturers in Île-de-France and confectionery houses across Hauts-de-France rebuild viscosity profiles using low-methoxyl pectin for low-sugar formulations. The EU Green Deal's biopolymer sourcing mandates redirect procurement toward citrus fiber derivatives from European agricultural waste streams. Lyon-based food processing clusters concentrate demand for thermoreversible gel systems in premium applications.
Netherlands
Industrial bakery and beverage processors in the Randstad region command 90-day formulation turnaround requirements from hydrocolloid suppliers. REACH compliance obligations filter market access, favoring producers with documented supply chain traceability systems. Wageningen University's food innovation ecosystem anchors pilot-scale application laboratory partnerships.
Belgium
Gluten-free bakery manufacturers in Flanders rely on xanthan gum-cellulose gum combinations for wheat-free dough elasticity. CE-marked processing equipment standards constrain production line modifications, locking in stabilizer specifications across multi-year contracts. The Port of Antwerp logistics corridor enables just-in-time powder delivery to high-throughput production facilities.
Poland
Private-label packaged food producers in the Masovian and Silesian regions represent underpenetrated territory for standard-grade stabilizer suppliers. Polish food processors remain dependent on distributor intermediaries due to fragmented demand volumes below direct contracting thresholds. Warsaw-based retail chains accelerate ingredient qualification cycles as Eastern European private-label expansion gathers momentum.
Europe Food Hydrocolloids Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying refined biopolymers to formulation houses. The vendor base stratifies across three tiers: multinational agricultural processors with captive raw material streams, specialized hydrocolloid refiners with fermentation capabilities, and regional blenders serving fragmented foodservice channels. Two strategic archetypes dominate: integrated supply chain operators securing feedstock independence, and application-focused formulators embedding technical service into customer relationships. Competitive intensity concentrates on M&A activity targeting Eastern European distribution networks and capacity expansion in precision fermentation facilities.
Within the integrated agricultural processor archetype, Cargill, Incorporated and Archer-Daniels-Midland Company represent scale-driven positions anchored to continental commodity flows. Kerry Group PLC occupies a specialized formulation tier, embedding application expertise into customer partnerships. DuPont de Nemours exemplifies the microbial fermentation vector, decoupling hydrocolloid output from seasonal crop variability through controlled bioreactor production.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| CP Kelco |
| DuPont de Nemours |
| Koninklijke DSM N.V. |
| Kerry Group PLC |
| Rousselot |
| Archer-Daniels-Midland Company |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
The Randstad industrial corridor concentrates hydrocolloid formulation capacity within a 100-kilometer radius of Wageningen, creating localized pricing power for Dutch and Belgian processors who negotiate direct supplier contracts with documented traceability systems. This geographic clustering enables just-in-time powder delivery to high-throughput dairy and bakery facilities, compressing logistics premiums that Eastern European buyers absorb through distributor intermediaries.
Pricing Analysis
The customization-premium spread separates configured-to-order texture systems from standard-grade powders, with formulation service premiums reflecting rheologist labor costs and pilot-scale testing cycles. Price differentiation hinges on certification grade (REACH-compliant vs. standard documentation) and volume scale, with quarterly volume commitments unlocking contracted rates. Pricing pressure stems from carrageenan raw material volatility in Southeast Asian harvesting regions, compressing margins on seaweed-derived stabilizers. Food manufacturers in the Netherlands and Belgium demonstrate lowest price sensitivity due to integrated technical service requirements, while Polish and Romanian retail private-label producers operate at highest sensitivity thresholds.
Supply Chain Analysis
Export-control regimes on dual-use fermentation technology constrain precision xanthan gum production capacity expansion outside established biotechnology corridors. Geographic supply concentration centers on Germany, France, and the Netherlands for refined pectin and carrageenan processing, with raw material dependencies drawing from Spanish citrus peel streams, Irish seaweed harvesting cooperatives, and Belgian microbial fermentation facilities. Single-source vulnerability runs through Southeast Asian carrageenan raw material channels exposed to climate-driven harvest disruption. Distribution runs through direct supplier-manufacturer contracting for scale buyers above volume thresholds, with fragmented Eastern European demand aggregating through distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise scarcity defines competitive positioning in this market, with shortages of food rheologists who understand hydrocolloid synergies in low-sugar systems constraining technical service capacity for clean-label reformulation projects.
For Market Incumbents: Build captive supply moats through backward integration into citrus peel processing and microbial fermentation capacity. Secure raw material streams for pectin and xanthan gum production across continental agricultural waste streams to defend against commodity crop price cycles. Anchor technical service capacity through pilot-scale application laboratories located near customer R&D centers in Frankfurt and Wageningen clusters. For New Entrants and Emerging Players: Pursue Eastern European penetration gaps in Polish and Romanian private-label packaged food segments where fragmented demand volumes sit below incumbent direct contracting thresholds. Target standard-grade stabilizer supply to Warsaw-based retail chains accelerating ingredient qualification cycles. Lead with cost-optimized powder blends and rapid formulation turnaround capabilities to bypass entrenched technical service relationships. For Investors and Strategic Acquirers: Long-term, this sits as a biopolymer transition play because EU Green Deal mandates and EFSA additive re-evaluations are structurally redirecting procurement toward plant-derived stabilizers with documented supply chain traceability. Acquisition targets should profile as precision fermentation specialists with controlled bioreactor production decoupled from seasonal crop variability. The signal to watch is EFSA's final determinations on degraded carrageenan classifications, which would force preemptive reformulation investments and accelerate displacement toward pectin and cellulose derivatives.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Microbial xanthan gum production eliminates dependence on corn feedstock availability and price cycles. |
| Direct Supplier-Manufacturer Contracting | Bypassing distributors captures margin pools in Dutch and Belgian procurement clusters with integrated logistics. |
| Eastern European Distribution Network Acquisition | Polish and Romanian private-label expansion accelerates demand aggregation above direct contracting thresholds. |
| Application Laboratory Proximity Investment | Pilot-scale facilities near Frankfurt and Wageningen enable 90-day formulation turnaround requirements. |
| Citrus Peel Processing Backward Integration | Captive supply from Spanish agricultural waste streams secures pectin raw material against seasonal constraints. |
Research Methodology
A spread of perspectives from hydrocolloid procurement managers at German dairy cooperatives, formulation scientists at French sauce manufacturers, regulatory affairs leads navigating EFSA additive protocols, and distribution channel partners across Polish foodservice networks converged on the working assumptions underlying demand projections. Primary interview intelligence combined with secondary validation from REACH registration dossiers, EFSA scientific opinions, EU Green Deal policy documentation, and customs trade data on biopolymer imports. Bottom-up volume modeling across product chemistry segments triangulated against top-down macroeconomic indicators for European food manufacturing output.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type (gelatin, pectin, xanthan gum, agar), application (dairy, bakery, beverages, sauces), end user scale (food manufacturers, retail, foodservice), and geographic procurement cluster. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and clean-label substitution elasticities. Industry-specific forecast inputs incorporated EFSA re-evaluation timelines and EU biopolymer incentive disbursement schedules.
Sensitivities concentrate around EFSA final determinations on carrageenan safety classifications, EU Green Deal subsidy allocation shifts, and precision fermentation technology licensing access. Forecasts reflect documented assumptions on regulatory trajectory and raw material supply stability. Material shifts in EFSA additive protocols or Southeast Asian seaweed harvest conditions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market