
 Edible Oil Co-Products and by-Products Market | 2026-2036
Edible Oil Co-Products and by-Products Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Oil Co-Products and by-Products Market Foresight
Specialty ingredient distribution channels are rewriting procurement relationships between oilseed processors and downstream buyers. Cargill Incorporated leverages its crushing network to secure captive supply of lecithin and acid oils across North American and European facilities. Wilmar International Limited anchors Asia-Pacific volume through integrated palm oil complexes that generate glycerin and fatty acid distillates at scale.
Edible oil co-products and by-products comprise residual streams from oilseed crushing and vegetable oil refining, including meals with protein content ranging from 40% to 50%, crude glycerin at 80% purity, and phospholipid-rich lecithin slurries. These materials serve as feedstock for animal nutrition, oleochemical synthesis, and renewable fuel production. Meal and cake categories dominate tonnage due to structural demand from compound feed operations, while glycerin commands premium pricing differentials tied to refined grades for pharmaceutical and personal care applications. Lecithin occupies a narrower but higher-margin position in food emulsification and nutraceutical encapsulation.
REACH compliance in Europe, FDA food-contact regulations in the United States, and BIS certification requirements in India collectively determine market access thresholds for glycerin and lecithin exporters. The EU Green Deal's renewable energy directives are redirecting crude glycerin streams from traditional oleochemical outlets toward advanced biofuel refineries. Stakeholders must monitor evolving grade specifications across food, feed, and industrial segments as regulatory boundaries between applications harden.
Market Dynamics
EU Green Deal mandates and India's PLI scheme incentives are rerouting glycerin and lecithin streams toward biofuel and pharmaceutical-grade applications, compressing traditional oleochemical supply windows.
Growth Catalysts
- EU F-Gas Regulation:Tightening sustainability requirements for biofuel-derived glycerin are redirecting refinery investment toward pharmaceutical-grade purification capacity.
- Oilseed meal protein substitution:Compound feed manufacturers across Germany and the Netherlands are displacing fishmeal with rapeseed and soybean cakes in aquaculture diets.
- India's BIS certification push:Domestic processing capacity expansion under PLI scheme incentives is capturing glycerin volumes previously imported from Southeast Asian refiners.
Market Restraints
- Crude glycerin price volatility:Biodiesel production fluctuations in Argentina and Indonesia create feedstock cost instability for European oleochemical processors.
- REACH compliance burden:Registration requirements for phospholipid derivatives impose documentation costs that disadvantage small-scale lecithin exporters.
- Enzymatic degumming substitution:Wet-physical refining technologies are displacing acid degumming processes, reducing acid oil by-product availability.
Strategic Opportunities
- Brazilian biodiesel expansion:Proalcool program extensions and RenovaBio mandates are generating crude glycerin surpluses ripe for pharmaceutical-grade upgrading.
- Cell-culture media applications:Lecithin phospholipid fractions are penetrating biopharmaceutical manufacturing as serum-free culture media components.
- Direct-to-feedmill distribution:Oilseed processors are bypassing traditional traders to contract directly with integrated poultry operations in Vietnam and Thailand.
Industry Challenges
- Multi-grade certification timelines:Simultaneous pursuit of USP-grade glycerin, FSSC 22000, and feed GMP+ accreditations stretches quality assurance resources.
- Legacy ERP integration:Batch traceability requirements for EU deforestation regulation compliance clash with decades-old refinery management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Oil Co-Products and by-Products Market |
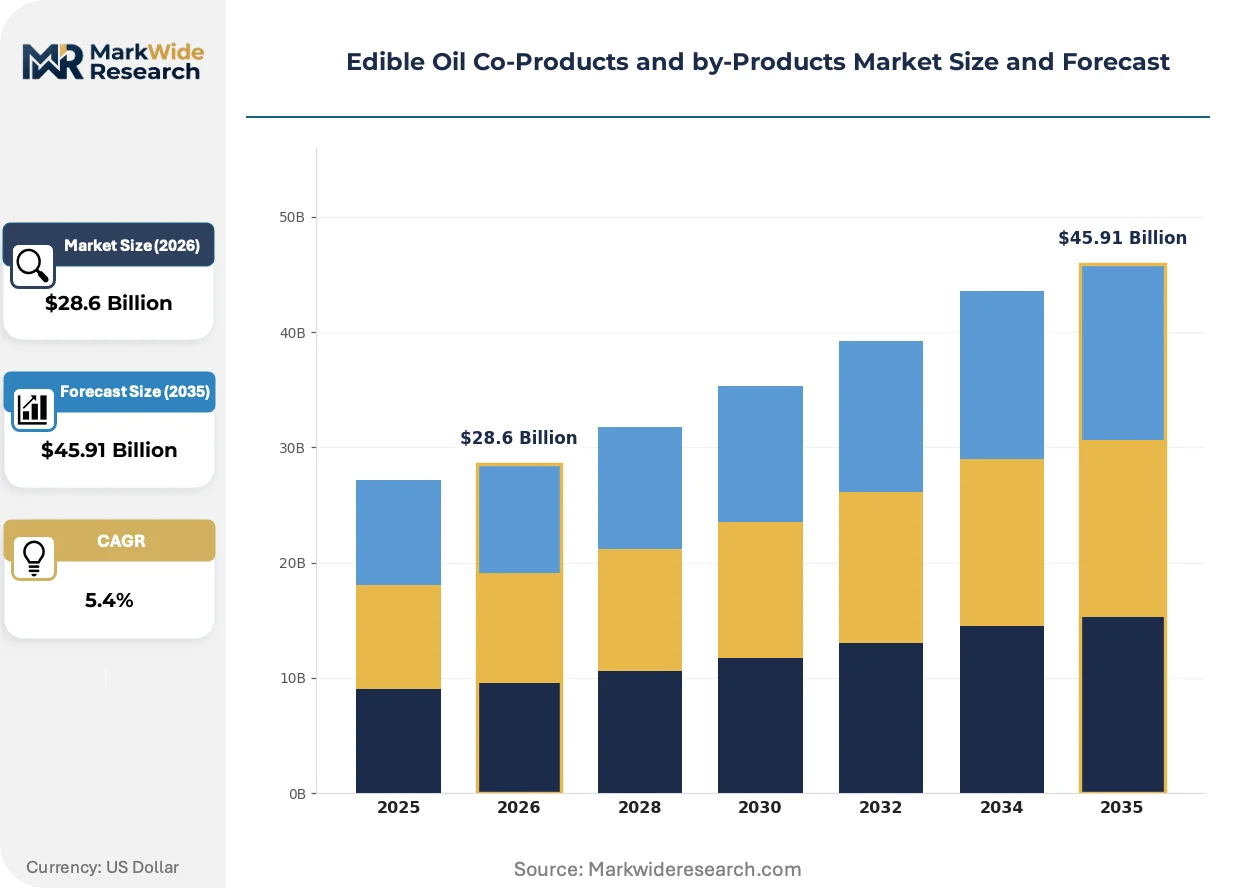
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal, Cake, Glycerin, Lecithin End Use Industry: Food, Feed, Personal Care, Biofuel Grade: Food Grade, Feed Grade, Industrial Grade, Technical Grade Packaging Type: Bags, Drums, Bulk, Cans |
| Companies Covered | Cargill Incorporated, Archer-Daniels-Midland Company, Bunge Limited, Wilmar International Limited, IOI Corporation Berhad, Oleo Misr, Rade Chemicals, A & B Chemical Corporation, Cayman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Oil Co-Products and by-Products Market Shifts & Advancements
Processing technologies and regulatory boundaries are converging to fragment the traditional commodity-trading model for oilseed residuals, favoring integrated processors with captive upgrading capabilities.
Membrane filtration systems for lecithin de-oiling and fractionation are hybridizing solvent extraction with ceramic microfiltration to yield higher-purity phosphatidylcholine concentrates. Nutraceutical encapsulation houses in Switzerland and Japan are adopting these systems to secure IP-protected phospholipid grades. The technology is hybridizing commodity lecithin streams into differentiated nutraceutical feedstocks, compressing margins for standard fluid lecithin traders.
REACH authorization requirements for certain glycerin process catalysts are forcing refiners to revalidate purification protocols ahead of 2026 sunset dates. German and Dutch oleochemical clusters are consolidating crude glycerin procurement to amortize compliance costs across larger volume bases. Pharmaceutical-grade glycerin certification is becoming the primary competitive filter, with USP-grade holders capturing contract manufacturing organization volumes.
Compound feed buyers are consolidating procurement decisions at the integrator level, displacing decentralized mill purchasing. Brazilian and Thai poultry giants are mandating certified-sustainable soy meal with full traceability documentation. This concentration is most visible in Southeast Asia, where Wilmar and Cargill crushing networks are capturing long-term offtake agreements at the expense of spot-market traders.
Edible Oil Co-Products and by-Products Market Segmentation
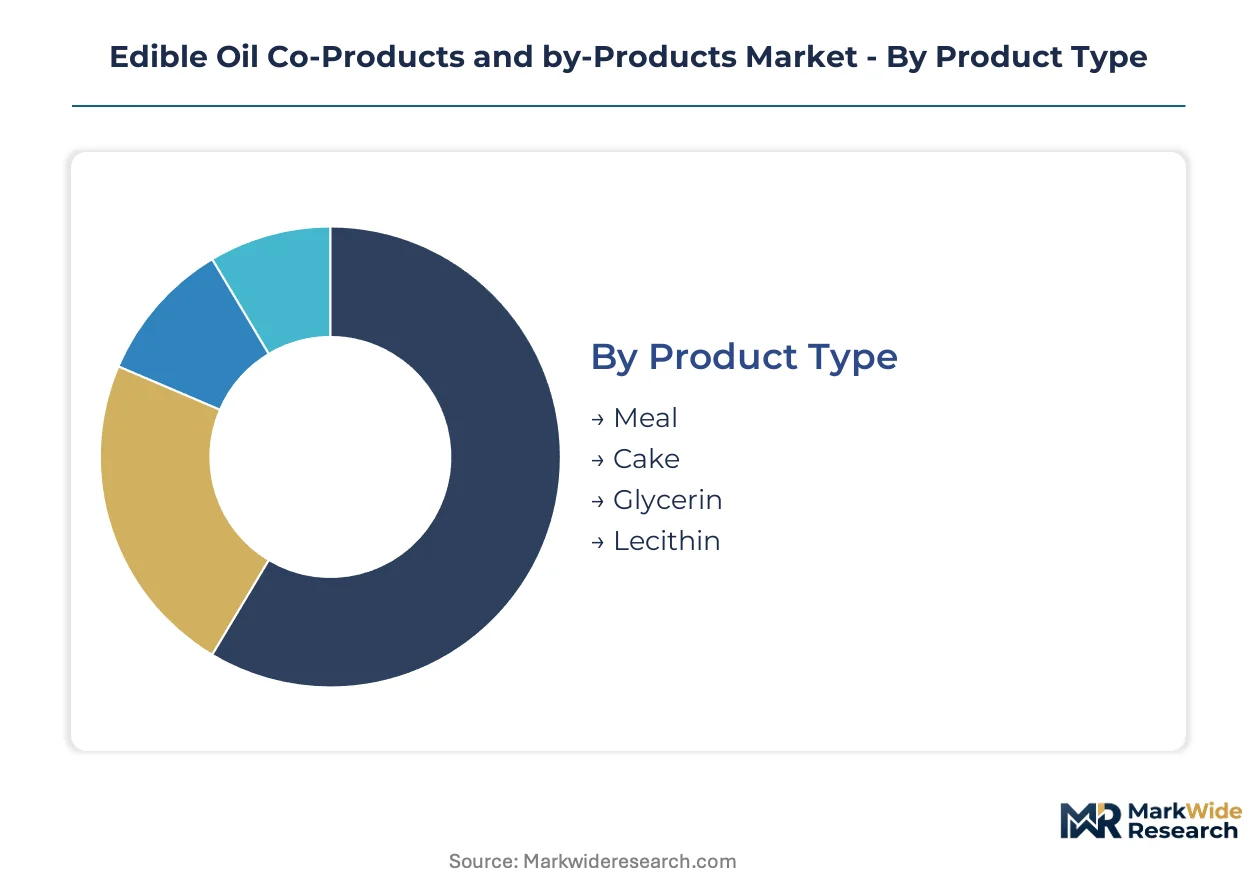
Co-product economics hinge on grade arbitrage and end-use certification pathways. Segmentation reveals how identical feedstock streams command divergent valuations based on purification investment and regulatory clearance.
Product Type:
Cost tier determines margin capture, with purification intensity separating commodity tonnage from specialty premiums.
- Meal:Protein-rich residues from solvent extraction of soybeans, rapeseed, and sunflower seeds, typically containing 40-50% crude protein. Compound feed manufacturers in Germany and the Netherlands are displacing fishmeal with certified-sustainable soy meal in aquaculture diets, driven by marine stewardship certification requirements. Meal holds installed capacity. Glycerin is rotating up the share rankings.
- Cake:Mechanical-press residues retaining higher oil content than solvent-extracted meal, valued in ruminant feed formulations for bypass protein characteristics. Brazilian poultry integrators are contracting directly with crushers for full-traceability soy cake under RenovaBio compliance protocols.
- Glycerin:Crude streams from biodiesel transesterification, refined through distillation and ion exchange to USP or technical grades. Pharmaceutical-grade holders are capturing contract manufacturing organization volumes as REACH authorization deadlines approach.
- Lecithin:Phospholipid concentrates from water degumming of crude vegetable oils, fractionated into fluid, de-oiled, and modified grades. Nutraceutical encapsulation houses in Switzerland and Japan are adopting membrane filtration systems to secure IP-protected phosphatidylcholine concentrates.
Meal holds installed capacity. Glycerin is rotating up the share rankings.
End Use Industry:
Application boundaries are hardening as regulators erect stricter grade specifications between food, feed, and fuel destinations.
- Food:Lecithin emulsifiers in chocolate and bakery applications, plus refined glycerin as humectants and solvents. FDA food-contact regulations and FSSC 22000 certification determine market access for phospholipid suppliers.
- Feed:Oilseed meals and cakes as protein substitutes in poultry, swine, and aquaculture diets. EU deforestation regulation compliance is mandating batch traceability from farm to feedmill.
- Personal Care:USP-grade glycerin for moisturizers and toothpaste, plus lecithin-derived liposomes for cosmetic delivery systems. REACH registration requirements for phospholipid derivatives impose documentation costs on small-scale exporters.
- Biofuel:Crude glycerin as feedstock for advanced biofuel refineries and renewable diesel hydrotreatment. EU F-Gas Regulation and renewable energy directives are redirecting streams from traditional oleochemical outlets.
Feed commands volume leadership. Personal Care is climbing the fastest on value per kilogram.
Grade:
Certification tier functions as the primary competitive filter, with multi-grade accreditation stretching quality assurance resources.
- Food Grade:Meets pharmacopeial and food safety standards for direct human consumption, including USP, FCC, and JECFA specifications. Simultaneous pursuit of USP-grade glycerin and FSSC 22000 accreditations is consolidating supplier bases.
- Feed Grade:Complies with GMP+ and FAMI-QS standards for compound feed inclusion, with mycotoxin and contaminant thresholds below food-grade tolerances. Brazilian and Thai poultry giants are mandating certified-sustainable meal with full traceability documentation.
- Industrial Grade:Technical specifications for oleochemical synthesis, polymer production, and antifreeze formulations. Price volatility in Argentine and Indonesian biodiesel output creates feedstock cost instability for European processors.
- Technical Grade:Intermediate purity for non-critical applications, often blended or reprocessed before final use. German and Dutch oleochemical clusters are consolidating procurement to amortize compliance costs across larger volume bases.
Food Grade captures premium positioning. Feed Grade maintains volume dominance.
Packaging Type:
Customer scale and supply chain configuration dictate format selection, with bulk displacing packaged units at the integrator level.
- Bags:Multi-wall paper or woven polypropylene for meal and cake distribution to decentralized feed mills. Direct-to-feedmill contracting is bypassing traditional trader networks in Vietnam and Thailand.
- Drums:Standard 200-liter steel or plastic containers for liquid glycerin and lecithin in chemical and pharmaceutical procurement. REACH documentation requirements favor drum-level batch traceability.
- Bulk:Tanker truck, railcar, and vessel shipments for high-volume glycerin and meal movements between integrated processors. Wilmar and Cargill crushing networks are capturing long-term offtake agreements at the expense of spot-market traders.
- Cans:Retail and small-batch formats for specialty lecithin and pharmaceutical glycerin in personal care and nutraceutical channels. Membrane filtration upgrades are hybridizing commodity streams into differentiated feedstocks.
Bulk commands procurement economics. Drums retain specification-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European glycerin flows, while Indian rail corridors from Kandla to Delhi-NCR channel oilseed meal toward compound feed operations.
Germany
Rapeseed meal demand from aquaculture feed formulators in Schleswig-Holstein is displacing fishmeal imports. REACH authorization deadlines for glycerin process catalysts are forcing Hamburg refiners to revalidate purification protocols. The Ruhr oleochemical cluster consolidates crude glycerin procurement to amortize compliance costs across larger volume bases.
India
Soybean meal consumption by poultry integrators in Haryana and Telangana is accelerating under PLI scheme incentives. BIS certification requirements are redirecting glycerin volumes previously imported from Southeast Asian refiners toward domestic processing capacity. The Kandla Special Economic Zone hosts expanding solvent extraction complexes serving northwestern feedmill networks.
Brazil
Soy cake offtake from RenovaBio-compliant poultry operations in São Paulo state is bypassing traditional trader networks. Proalcool program extensions are generating crude glycerin surpluses from biodiesel transesterification. The Santos port complex channels pharmaceutical-grade upgrading investments toward captive oleochemical output.
United States
Crude glycerin from Midwest biodiesel plants is feeding Gulf Coast renewable diesel hydrotreatment facilities. FDA food-contact regulations determine market access for lecithin suppliers to chocolate and bakery manufacturers. The Iowa-Illinois crushing corridor anchors Cargill's captive supply networks for acid oils and phospholipid streams.
Netherlands
Rapeseed and sunflower meal exports to German and Belgian compound feed operations are consolidating under EU deforestation regulation batch traceability mandates. The Rotterdam refining hub processes crude glycerin from Argentine biodiesel fluctuations into pharmaceutical-grade output. Wageningen research clusters pilot membrane filtration systems for lecithin fractionation.
Edible Oil Co-Products and by-Products Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agribusiness conglomerates with captive crushing and refining infrastructure. Mid-scale regional processors occupy specialized niches in pharmaceutical-grade glycerin or certified-sustainable meal certification. Three archetypes dominate: multinational traders with global origination networks, Asian palm oil conglomerates with integrated downstream complexes, and regional specialists in high-purity phospholipid or glycerin grades. Competitive moves center on backward integration into oilseed crushing and strategic partnerships with biofuel refineries for crude glycerin offtake.
Within the multinational trader archetype, Cargill Incorporated and Archer-Daniels-Midland Company represent integrated origination-to-processing models with North American and European crushing networks. Wilmar International Limited anchors Asia-Pacific volume through Malaysian and Indonesian palm oil complexes. These three exemplify how scale and geographic diversification compress margins for spot-market traders while capturing long-term offtake agreements with compound feed and renewable fuel customers.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer-Daniels-Midland Company |
| Bunge Limited |
| Wilmar International Limited |
| IOI Corporation Berhad |
| Oleo Misr |
| Rade Chemicals |
| A & B Chemical Corporation |
| Cayman Chemical Company |
| Others |
Supply & Pricing Matrix
Argentine biodiesel production volatility determines both margin compression in European oleochemical processing and the geographic reconfiguration of crude glycerin procurement networks. This commodity price instability feeds directly into three-tier pricing stratification across pharmaceutical, technical, and industrial glycerin grades while forcing supply chain consolidation around larger volume bases.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade USP glycerin from technical and industrial grades based on purification investment and certification burden. Price differentiation hinges on REACH compliance documentation and FDA food-contact clearance, with multi-grade accreditation stretching quality assurance resources. Cost compression in standard fluid lecithin intensifies because membrane filtration upgrades hybridize commodity streams into IP-protected nutraceutical feedstocks. Compound feed manufacturers show highest price sensitivity due to protein substitution economics, while pharmaceutical contract manufacturers accept premium positioning for batch traceability assurance.
Supply Chain Analysis
Tariff exposure between Argentina and European Union member states dominates supply chain risk calculus for crude glycerin-dependent refiners. Geographic supply concentration centers on Argentina, Indonesia, and Brazil for biodiesel-derived feedstock, with German and Dutch oleochemical clusters drawing from consolidated procurement pools. Raw material dependencies rest on soybean and rapeseed crushing volumes, biodiesel transesterification output, and palm oil refining residuals. Distribution runs through Rotterdam liquid bulk terminals for European flows and Kandla port complexes for Indian domestic absorption, with bulk tanker movements displacing packaged units at the integrator level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation mandates and India's PLI scheme acceleration constitute a dual regulatory inflection rerouting glycerin and lecithin streams toward biofuel and pharmaceutical-grade applications. This redirection fragments traditional commodity-trading models and compresses supply windows for non-integrated processors.
For Market Incumbents: Entrench captive supply networks through backward integration into oilseed crushing in Iowa-Illinois and Hamburg-Ruhr corridors. Expand pharmaceutical-grade purification capacity ahead of REACH authorization deadlines to defend against membrane filtration substitution in lecithin fractionation. Lock long-term offtake agreements with Brazilian RenovaBio-compliant poultry integrators to preempt direct-to-feedmill contracting by regional competitors.
For New Entrants and Emerging Players: Vietnamese and Thai feedmill markets offer underpenetrated white-space for certified-sustainable soy meal with full traceability documentation. Cell-culture media applications for lecithin phospholipid fractions present a second penetrable entry point given serum-free manufacturing adoption by Swiss and Japanese encapsulation houses. Pursue specialty distribution partnerships with nutraceutical contract manufacturers rather than competing on commodity tonnage.
For Investors and Strategic Acquirers: Regional specialists in high-purity phospholipid grades represent the acquisition target archetype with defensible IP positions and limited scale-up capital requirements. Long-term viability across the analysis window favors processors with integrated palm oil complexes or crushing-to-refining infrastructure. Monitor Brazilian biodiesel output fluctuations as the signal to watch for crude glycerin surplus availability and downstream upgrading investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's Iowa-Illinois corridor anchors captive acid oil and phospholipid supply security. |
| Pharmaceutical-Grade Purification Capacity Expansion | Hamburg refiners revalidate protocols ahead of REACH catalyst authorization sunset dates. |
| Direct-to-Feedmill Distribution Bypass | Brazilian poultry integrators contract directly with crushers under RenovaBio compliance protocols. |
| Membrane Filtration Technology Adoption | Wageningen research clusters pilot ceramic microfiltration for phosphatidylcholine concentrate yields. |
| Long-Term Crude Glycerin Offtake Agreements | Rotterdam terminals consolidate Argentine and Indonesian biodiesel output for European upgrading. |
Research Methodology
A spread of perspectives from oilseed crushing plant managers, compound feed procurement leads at poultry integrators, oleochemical refinery technical directors, and pharmaceutical contract manufacturing officers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings, EU ECHA registration databases, and BIS certification records established the evidentiary foundation. Bottom-up volume modeling across meal, cake, glycerin, and lecithin categories triangulated against top-down macroeconomic indicators.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, end-use industry, grade tier, and regional production hub. CAGRs derived from historical volume trajectories adjusted for regulatory intervention timing and technology substitution curves. Industry-specific forecast inputs incorporated biodiesel production fluctuations in Argentina and Indonesia, plus PLI scheme capacity expansion timelines in Indian solvent extraction complexes.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian palm oil conglomerates or accelerated membrane filtration adoption by Swiss nutraceutical encapsulation houses would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Food Coating Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
China Food Hydrocolloids Market