
 Edible Films and Coating Market | 2026-2036
Edible Films and Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Films and Coating Market Intelligence
A shift from outsourced biopolymer supply toward captive in-house extraction is hardening across the industry. Cargill Incorporated leverages its corn-processing infrastructure to control polysaccharide feedstock costs. Tate & Lyle PLC anchors European supply through its specialty starch operations. DuPont de Nemours Inc. competes on protein-based film formulations for high-barrier pharmaceutical packaging.
Edible films and coatings are thin, consumable layers applied to food surfaces or formed as standalone wraps, typically composed of polysaccharides, proteins, or lipid complexes with thickness ranging from 0.05 to 0.5 millimeters, designed to extend shelf life, reduce moisture migration, and replace synthetic packaging. Polysaccharide films dominate current volume due to established supply chains for cellulose derivatives and alginates, while protein-based films command premium positioning in pharmaceutical blister applications where oxygen barrier requirements are stringent. Plant-based films are gaining traction as vegan-label demand from confectionery manufacturers reshapes formulation priorities across Europe and North America.
The FDA governs food-contact substances under 21 CFR, while the EU Green Deal and REACH framework restrict petroleum-derived packaging migration into food streams, collectively elevating compliance costs for synthetic incumbents and opening procurement channels for certified biopolymer alternatives. Food manufacturers must now verify coating digestibility and allergen profiles alongside traditional performance metrics. Stakeholders should monitor evolving compostability certifications, as these labels are becoming gatekeepers to retail shelf placement in regulated jurisdictions.
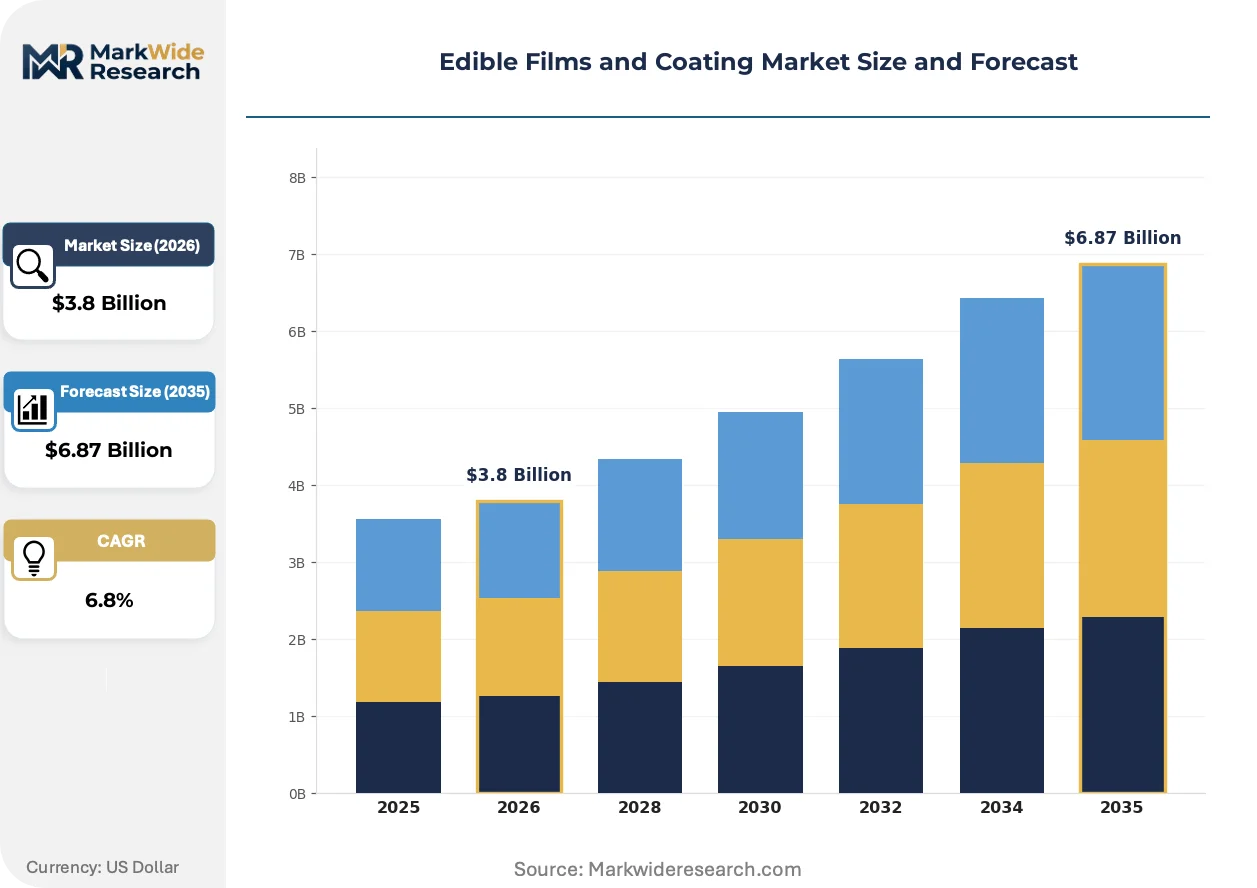
Market Dynamics
The EU Green Deal's packaging waste directives are compressing synthetic wrap viability while biopolymer extraction capabilities concentrate among corn and starch processors with captive feedstock infrastructure.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal and REACH framework restrict petroleum-derived packaging migration, opening procurement channels for certified biopolymer alternatives across European retail shelves.
- Fresh produce shelf-life extension:Polysaccharide coatings reduce post-harvest moisture loss in tropical fruit supply chains, with Latin American processors scaling adoption to cut spoilage rates.
- Pharmaceutical oxygen-barrier specifications:Protein-based films meet stringent blister-pack requirements for moisture-sensitive therapeutics, commanding premium positioning in high-barrier pharmaceutical applications.
Market Restraints
- Feedstock cost volatility:Corn and potato starch prices fluctuate with agricultural commodity cycles, squeezing margin stability for polysaccharide film manufacturers without captive crop processing.
- Supply concentration in Midwest corn belt:North American polysaccharide feedstock refining clusters in Iowa and Illinois, creating geographic single-point vulnerability for coating formulators elsewhere.
- Moisture barrier limitations:Unmodified protein films exhibit hydrophilic swelling above 75% relative humidity, restricting their deployment in high-moisture food applications without lipid lamination.
Strategic Opportunities
- Brazilian citrus export coating demand:São Paulo and Minas Gerais fruit processors seek alginate-based coatings to replace waxes for EU-bound organic citrus, creating unmet formulation service demand.
- Active packaging convergence:Antimicrobial essential oil infusion into edible matrices is integrating with intelligent freshness indicators, opening premium-priced smart-coating categories.
- Compostability certification retail gatekeeping:TÜV Austria and BPI labels are becoming mandatory for shelf placement in German and California retail chains, rewarding early certifiers with preferential listing.
Industry Challenges
- Food-contact toxicologist scarcity:Digestibility and allergen profile validation requires specialized toxicology expertise that coating formulators struggle to recruit against pharmaceutical and cosmetic sectors.
- Legacy extrusion line retrofit costs:Converting synthetic film equipment for biopolymer processing demands capital outlays for humidity-controlled drying sections and modified screw geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Films and Coating Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Films, Protein-Based Films, Polysaccharide Films, Lipid-Based Coatings Application: Food Preservation, Packaging, Nutritional Supplements, Coating for Fruits End User: Food Industry, Pharmaceutical Sector, Beverage Sector, Confectionery Manufacturers Form: Spray, Dip, Sheet, Gel |
| Companies Covered | Cargill Incorporated, DuPont de Nemours Inc., Tate & Lyle PLC, Koninklijke DSM N.V., Kerry Group plc, Ingredion Incorporated, BASF SE, Evonik Industries AG, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Films and Coating Market Strategic Shifts & Innovations
Biopolymer extraction technology is hardening around in-house feedstock control, while regulatory migration limits and pharmaceutical barrier specifications reshape formulation priorities across end-use verticals.
Nanolaminate deposition technology is integrating lipid-polysaccharide bilayers at sub-micron precision to overcome moisture permeability limits in protein-based matrices. Pharmaceutical blister manufacturers in Switzerland and Germany are piloting these structures for oxygen-sensitive oncology therapeutics. The technology is compressing the performance gap between edible films and metallized synthetic barriers in high-value packaging segments.
REACH framework amendments on microplastic migration are forcing synthetic wrap incumbents to document biodegradability timelines or exit food-contact applications. Coating formulators with existing compostability certifications are capturing displaced volume in French and Dutch retail supply chains. Protein-based film specialists are accelerating allergen documentation protocols to preempt regulatory friction.
Confectionery procurement teams are mandating vegan-label compliance in coating specifications, displacing shellac and beeswax alternatives in European premium chocolate segments. Ingredient suppliers with plant-based certification chains are securing multi-year supply agreements with Swiss and Belgian manufacturers. This specification tightening is most visible in private-label contract manufacturing, where retailer sustainability scorecards determine supplier retention.
Edible Films and Coating Market Segmentation
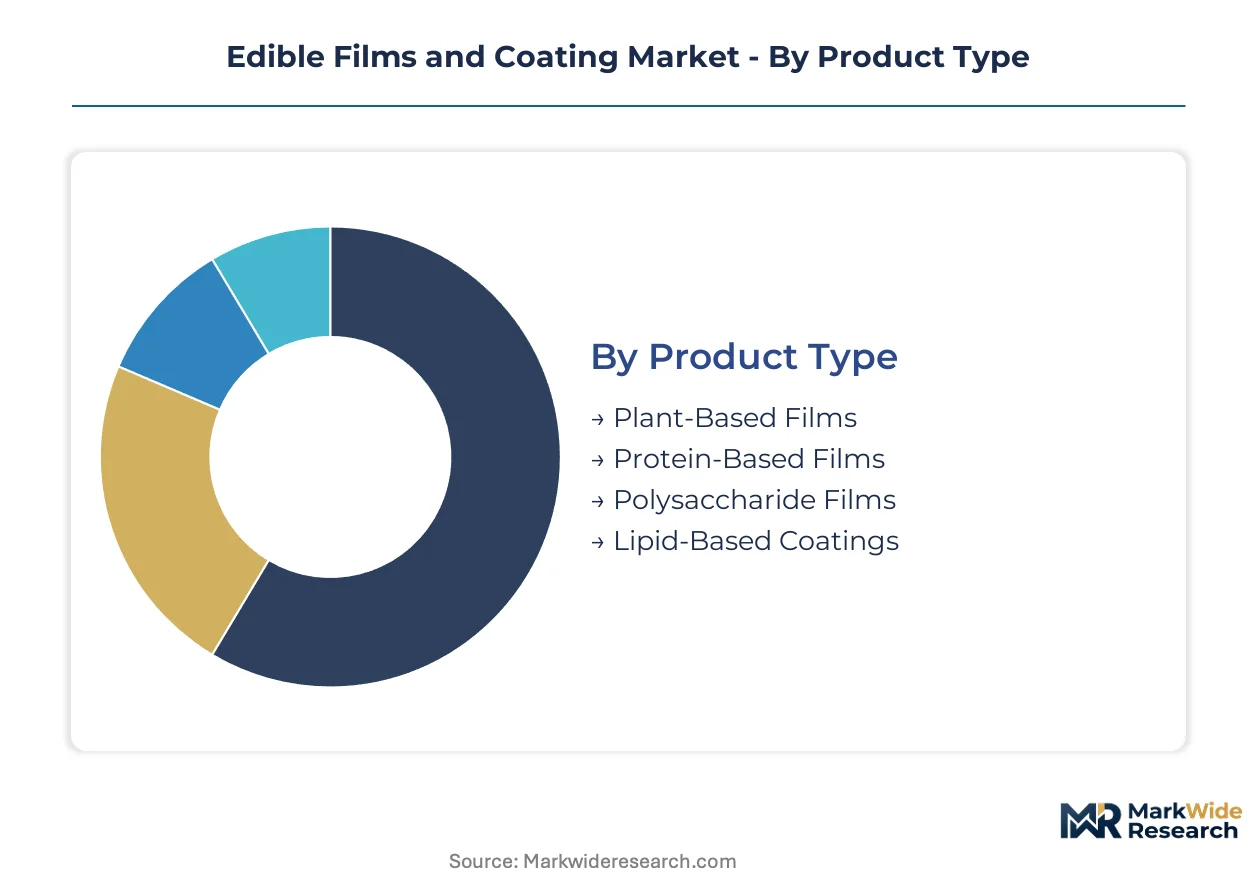
Edible film formulations diverge sharply in barrier performance and cost structure, forcing procurement teams to match material chemistry against shelf-life requirements and regulatory constraints. Segmentation clarity determines whether coating investments align with specific end-use oxygen permeability targets and compostability certification timelines.
Product Type:
Cost tier dictates buyer selection between commodity polysaccharides and premium protein barriers.
- Polysaccharide Films:Cellulose derivatives and alginates constitute the volume base, leveraging established corn and tapioca supply chains for cost-efficient moisture management in tropical fruit exports. Demand clusters in Brazil and Mexico where processors seek EU-compliant alternatives to synthetic waxes for organic citrus shipments.
- Protein-Based Films:Whey and zein formulations deliver sub-1 cc/m²/day oxygen permeability required for pharmaceutical blister packs. Swiss and German oncology drug manufacturers pilot these structures for moisture-sensitive therapeutics, paying premium multiples over polysaccharide alternatives.
- Plant-Based Films:Starches and pectins from non-GMO sources satisfy vegan-label procurement mandates from Belgian and Swiss confectionery contract manufacturers.
- Lipid-Based Coatings:Beeswax and carnauba alternatives face displacement pressure as plant-based certification tightens across European retail scorecards.
Volume sits with Polysaccharide Films; growth tilts toward Protein-Based Films.
Application:
Application selection tracks moisture sensitivity of the protected substrate and distribution channel length.
- Food Preservation:Polysaccharide coatings reduce post-harvest moisture loss in mango and avocado supply chains. Latin American processors scale alginate dipping lines to cut spoilage rates in export-bound produce.
- Packaging:Standalone edible wraps for portion-controlled snacks attract investment from Japanese convenience food manufacturers seeking single-use plastic elimination pathways.
- Coating for Fruits:São Paulo citrus processors specify coating thickness between 0.1-0.3 millimeters to satisfy EU organic import standards while maintaining gas exchange for respiratory climacteric fruits.
- Nutritional Supplements:Protein film encapsulation of probiotics commands niche positioning in German functional food segments requiring gastric resistance.
Revenue concentrates in Food Preservation; Packaging applications are climbing the fastest.
End User:
End-user procurement sophistication varies from commodity volume purchasing to specification-driven pharmaceutical qualification.
- Food Industry:Fresh produce processors dominate volume, with Brazilian and Mexican fruit packers driving alginate coating adoption for export compliance.
- Pharmaceutical Sector:Oxygen-barrier specifications above 0.1 cc/m²/day trigger protein film procurement for oncology and biologic drug blister packs in Switzerland and Germany.
- Confectionery Manufacturers:Vegan-label mandates from Swiss and Belgian premium chocolate brands displace shellac glazing with plant-based alternatives.
- Beverage Sector:Edible coatings for probiotic encapsulation in functional drinks attract limited pilot investment from Japanese and South Korean fermentation companies.
Procurement volume flows to the Food Industry; specification complexity peaks in the Pharmaceutical Sector.
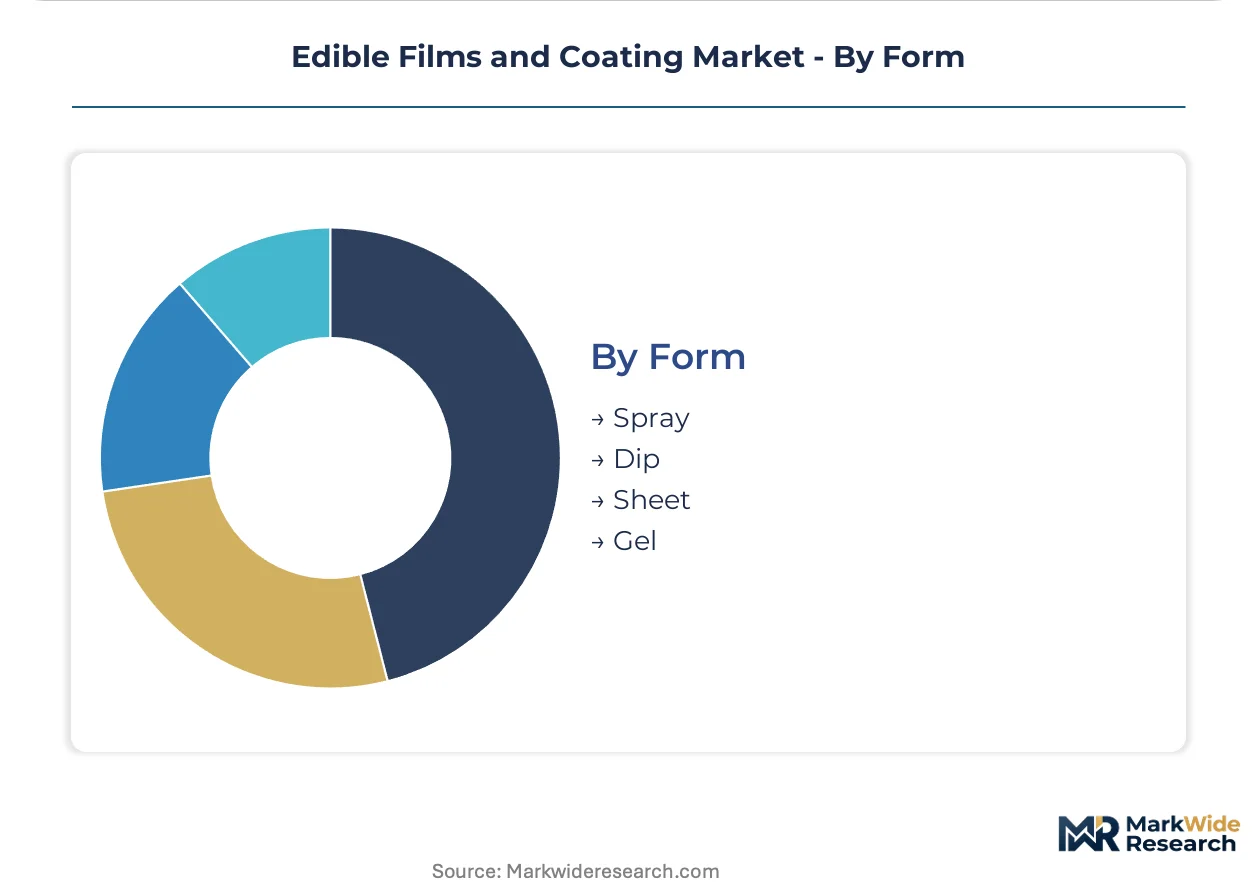
Form:
Form selection determines capital equipment requirements and coating uniformity control.
- Dip:Submersion systems achieve complete fruit coverage for citrus and apple processors in Brazil and Mexico, with coating thickness controlled by solids concentration and withdrawal speed.
- Spray:Aqueous polysaccharide suspensions suit irregular surface geometries in fresh-cut salad applications where dip tanks risk cross-contamination.
- Sheet:Pre-formed wraps for portion-controlled snacks require humidity-controlled forming lines, constraining adoption to capital-rich Japanese and German manufacturers.
- Gel:High-viscosity protein matrices enable localized application for pharmaceutical tablet coating, with Swiss manufacturers piloting precision deposition for moisture-sensitive actives.
Equipment utilization concentrates in Dip and Spray; Gel applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresh produce export corridors and pharmaceutical packaging clusters concentrate edible film demand across five distinct national markets. Brazil and Mexico drive volume through citrus and avocado coating adoption, while Germany and Switzerland anchor high-barrier pharmaceutical specifications. The United States maintains feedstock refining dominance through Midwest corn processing infrastructure.
Brazil
São Paulo and Minas Gerais fruit processors scale alginate coating lines to cut post-harvest losses in EU-bound organic citrus shipments. ANVISA aligns food-contact substance regulations with Mercosur standards, streamlining cross-border certification for export-oriented coating formulators. The São Paulo state citrus belt concentrates dipping line installations as processors replace synthetic waxes ahead of EU Green Deal compliance deadlines.
Germany
Pharmaceutical blister manufacturers in Baden-Württemberg pilot protein-based films for moisture-sensitive oncology therapeutics requiring sub-1 cc/m²/day oxygen permeability. The EU Green Deal packaging waste directives accelerate substitution of petroleum-derived wraps with compostable alternatives across retail supply chains. The Rhine-Main industrial corridor hosts formulation R&D facilities serving Swiss and German drug packaging qualification programs.
Mexico
Jalisco and Michoacán avocado packers deploy polysaccharide coatings to extend shelf life through extended North American distribution channels. COFEPRIS harmonizes edible coating approvals with FDA food-contact substance frameworks under USMCA alignment protocols. The Bajío Region emerges as a coating application equipment hub serving Central American fresh-cut produce processors.
Switzerland
Swissmedic qualification requirements for pharmaceutical packaging materials drive premium protein film procurement from domestic and German suppliers. The country's national chemical regulator enforces stringent migration limits that favor certified biopolymer alternatives over conventional synthetic barriers. The Basel pharmaceutical cluster concentrates blister-pack innovation programs integrating edible oxygen barriers for biologic drug stability.
United States
Midwest corn processors leverage captive starch refining infrastructure to control polysaccharide feedstock costs for domestic coating formulators. FDA 21 CFR food-contact substance regulations govern coating digestibility and allergen profile validation requirements. Iowa and Illinois refining clusters create geographic concentration for North American biopolymer supply, with formulation facilities co-locating to minimize logistics exposure.
Edible Films and Coating Market Key Industry Players
Backward integration into captive feedstock supply dominates the current landscape as margin pressure intensifies from agricultural commodity volatility. The vendor base stratifies between integrated agribusiness conglomerates with corn processing infrastructure and specialized biopolymer formulators serving pharmaceutical qualification programs. Three archetypes define positioning: captive feedstock controllers, high-barrier pharmaceutical specialists, and regional fresh produce coating service providers. M&A activity targets alginate and protein extraction capabilities, while capacity expansion concentrates in Brazilian and Mexican fruit processing corridors.
Within the integrated agribusiness tier, Cargill Incorporated and Tate & Lyle PLC exemplify feedstock-controlled positioning through Midwest and European corn processing infrastructure respectively. DuPont de Nemours Inc. occupies a position representing high-barrier pharmaceutical specialization, anchoring protein-based film development for oxygen-sensitive drug packaging applications. These three entities illustrate the competitive divergence between commodity-scale polysaccharide supply and premium protein barrier qualification.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| Tate & Lyle PLC |
| Koninklijke DSM N.V. |
| Kerry Group plc |
| Ingredion Incorporated |
| BASF SE |
| Evonik Industries AG |
| Amcor plc |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in Brazilian citrus processing and Iowa corn refining anchor supply discipline through generational capital allocation patterns that resist short-term margin compression. These ownership structures buffer pricing volatility by prioritizing captive feedstock control over quarterly yield optimization, creating asymmetric bargaining power against coating formulators lacking upstream integration.
Pricing Analysis
Volume concentrates in commodity polysaccharide tiers where contract-based long-term offtake dominates, while protein-based pharmaceutical barriers command premium positioning through TÜV Austria and BPI certification tiers. Price differentiation rests on oxygen permeability performance and compostability documentation rather than brand equity. Cost compression in standard polysaccharide grades is intensifying because corn starch price volatility squeezes non-integrated formulators. Fresh produce processors in Latin America exhibit highest price sensitivity, whereas Swiss oncology drug manufacturers accept premium multiples for sub-1 cc/m²/day barrier specifications.
Supply Chain Analysis
Dual-sourcing requirements from German pharmaceutical blister manufacturers mandate multi-supplier qualification for protein film feedstock, forcing procurement teams to validate both domestic and Dutch alginate sources. Geographic supply concentration clusters in the United States, Brazil, and Germany where corn processing, citrus coating application, and pharmaceutical formulation R&D anchor respective tiers. Raw material dependencies center on corn starch, whey protein isolate, and sodium alginate harvests. Single-source vulnerability runs through Midwest corn belt refining where Iowa and Illinois infrastructure creates geographic chokepoints. Distribution runs through regional formulation facilities co-located with downstream fruit processing and drug packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible films sector sits in a material-transition phase where nanolaminate deposition technology displaces unmodified protein matrices in high-barrier pharmaceutical applications. This substitution wave rewards early movers with Swissmedic qualification pipelines while stranding legacy extrusion assets.
For Market Incumbents: Deepen backward integration into captive alginate harvesting operations along Brazil's northeastern coastline to secure supply continuity ahead of EU Green Deal compliance deadlines. Accelerate TÜV Austria compostability certification investment to preempt retail gatekeeping in German and California supply chains, defending position against emerging regional coating service providers with lower regulatory overhead.
For New Entrants and Emerging Players: Begin with Brazilian citrus export corridors where São Paulo processors seek formulation services for EU-bound organic shipments, a segment incumbent agribusiness conglomerates underserve due to pharmaceutical margin prioritization. Target active packaging convergence opportunities integrating antimicrobial essential oil infusion with intelligent freshness indicators, leveraging technical partnerships with Japanese convenience food manufacturers as the go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor protein extraction specialists with existing pharmaceutical toxicology documentation in the Rhine-Main corridor, where feedstock cost volatility has compressed valuations for mid-caps lacking corn-processing infrastructure. Long-term viability across the analysis window hinges on certification moats rather than scale economies. Monitor REACH framework amendment timing on microplastic migration documentation as the inflection signal for displaced synthetic wrap volume capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alginate Harvesting | Captive supply from Brazil's northeastern coastline secures feedstock continuity against agricultural commodity cycles. |
| Compostability Certification Investment | TÜV Austria and BPI labels unlock shelf placement in German and California retail chains. |
| Nanolaminate Deposition Scale-Up | Sub-micron precision lipid-polysaccharide bilayers close the performance gap with metallized synthetic barriers. |
| Pharmaceutical Toxicology Documentation | Swissmedic qualification protocols create defensible moats in oncology drug blister packaging segments. |
| Active Packaging Convergence Development | Antimicrobial essential oil integration with freshness indicators opens premium-priced smart-coating categories. |
Research Approach
SEC 10-K filings, EU REACH registration databases, and Brazilian customs export records formed the secondary backbone, cross-referenced against primary interviews with coating formulation chemists, pharmaceutical packaging procurement leads, and fresh produce processing plant managers. Bottom-up and top-down triangulation validated volume estimates across polysaccharide, protein-based, and plant-based film segments.
Bottom-up modeling anchored demand-side projections while top-down macroeconomic frameworks captured regulatory displacement effects across the projection horizon. Segmentation dimensions included material chemistry, barrier performance tier, compostability certification status, and end-use vertical. CAGRs were derived from installed coating line capacity expansion trajectories and pharmaceutical qualification pipeline velocity, with corn starch price volatility and EU Green Deal implementation pace as key forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical oxygen-barrier specifications carry tighter precision than commodity fruit coating volumes due to documented Swissmedic qualification protocols. Forecasts reflect assumptions on regulatory timeline adherence and feedstock price normalization. Deviation in REACH framework enforcement intensity or Midwest corn belt harvest yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
South America Food Hydrocolloids Market