
 Food Antioxidant Market | 2026-2036
Food Antioxidant Market Size, Share, and Industry Trends Forecast 2026-2036
Food Antioxidant Market Analysis
Specialized formulation chemists with dual expertise in natural extract stabilization and food matrix compatibility is collapsing across European and North American labor markets. BASF SE leverages its integrated petrochemical feedstock position to sustain cost advantages in synthetic antioxidant production. Kemin Industries anchors its competitive stance through vertically controlled botanical sourcing for clean-label applications. Archer Daniels Midland Company dominates grain-derived tocopherol supply chains that feed both food and animal feed channels.
Food antioxidants comprise molecular species that inhibit lipid oxidation and rancidity through free-radical scavenging or metal chelation, typically incorporated at concentrations between 0.01% and 0.5% by weight depending on substrate fat content and storage conditions. Their primary commercial purpose centers on extending shelf life while preserving sensory and nutritional integrity in lipid-rich food matrices. Natural antioxidants derived from rosemary, green tea, and mixed tocopherols command premium positioning as clean-label alternatives, though synthetic butylated hydroxyanisole and butylated hydroxytoluene still occupy volume leadership in cost-sensitive animal feed applications. Powder formulations lead across industrial food manufacturing due to handling efficiency and dosing precision, while liquid carriers gain traction in beverage antioxidant systems where homogeneous dispersion proves critical.
The European Food Safety Authority enforces stringent re-evaluation protocols for synthetic antioxidants under EU Regulation 1333/2008, directly constraining butylated hydroxyanisole approvals and redirecting R&D investment toward botanical extract validation. The FDA maintains Generally Recognized As Safe listings for synthetic antioxidants while accelerating natural ingredient notification reviews through its Food Ingredient Contact Notification pathway. China's National Health Commission periodically revises approved additive lists under GB 2760 standards, creating compliance complexity for exporters targeting food manufacturers in Asia-Pacific markets. Stakeholders must monitor regulatory divergence between jurisdictions where natural claim permissibility and maximum usage levels increasingly determine formulation strategy and market access viability.
Market Dynamics
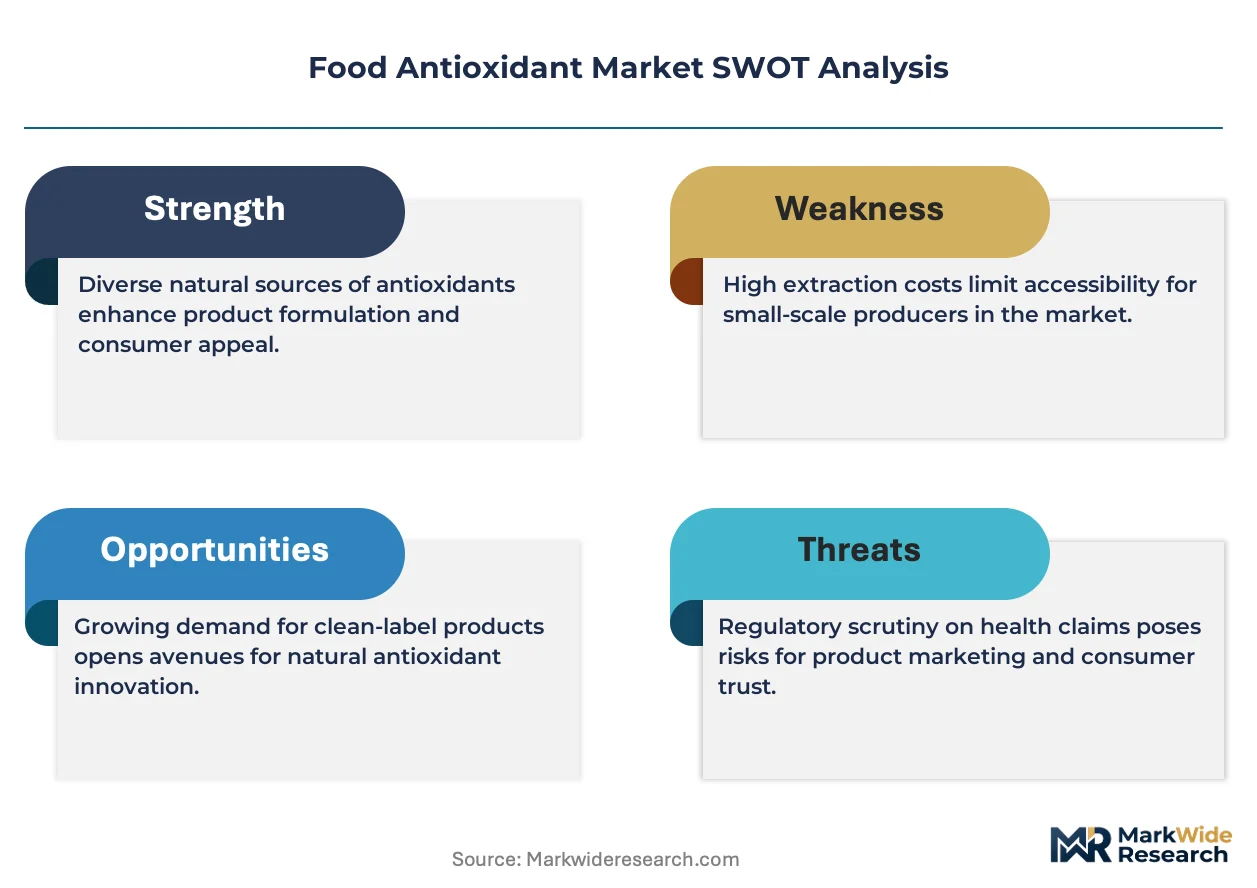
Clean-label reformulation mandates from EFSA under EU Regulation 1333/2008 are forcing accelerated R&D investment toward botanical extract stabilization, collapsing the synthetic antioxidant cost advantage that BASF SE has sustained through captive petrochemical feedstock access.
Growth Catalysts
- REACH restrictions:The EU Green Deal's chemical hazard reclassification is redirecting formulation budgets from butylated hydroxyanisole toward rosemary and green tea extract alternatives. Meat processors in Germany face the tightest compliance timelines.
- Processed meat sector:Poultry manufacturers are expanding antioxidant procurement to replace synthetic preservatives across chilled and frozen product lines. Dual-extraction protocols for tocopherol recovery are gaining traction.
- Botanical sourcing infrastructure:Vertically controlled cultivation networks in Mediterranean climates are securing supply continuity for clean-label applications. Kemin Industries anchors this upstream consolidation.
Market Restraints
- Specialized labor scarcity:Formulation chemists with dual expertise in natural extract stabilization and food matrix compatibility are collapsing across European and North American labor markets. Recruitment cycles now exceed eighteen months.
- Input cost volatility:Rosemary oleoresin prices fluctuate with harvest yields in Spain and Morocco. Weather-driven supply interruptions compress margin structures for extract-dependent formulators.
- Technical performance gaps:Natural antioxidants exhibit shorter efficacy windows in high-temperature processing environments compared to synthetic alternatives. Thermal stability limitations constrain adoption in fried snack applications.
Strategic Opportunities
- Beverage dispersion systems:Liquid antioxidant carriers are gaining traction where homogeneous distribution proves critical. Nanoemulsion technologies enable clear-label incorporation into functional drinks.
- Animal feed channel expansion:Grain-derived tocopherol supply chains feed both food and feed applications. Archer Daniels Midland Company dominates this dual-channel infrastructure.
- GB 2760 compliance services:China's National Health Commission periodically revises approved additive lists. Exporters targeting Asia-Pacific food manufacturers require dedicated regulatory navigation support.
Industry Challenges
- Extract standardization protocols:Batch-to-batch variability in polyphenol content complicates dosing precision. Analytical method harmonization across EFSA and FDA notification pathways remains incomplete.
- Legacy equipment retrofitting:Powder handling systems dominate industrial food manufacturing. Liquid injection infrastructure for beverage applications demands capital redeployment that mid-tier processors resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Antioxidant Market |
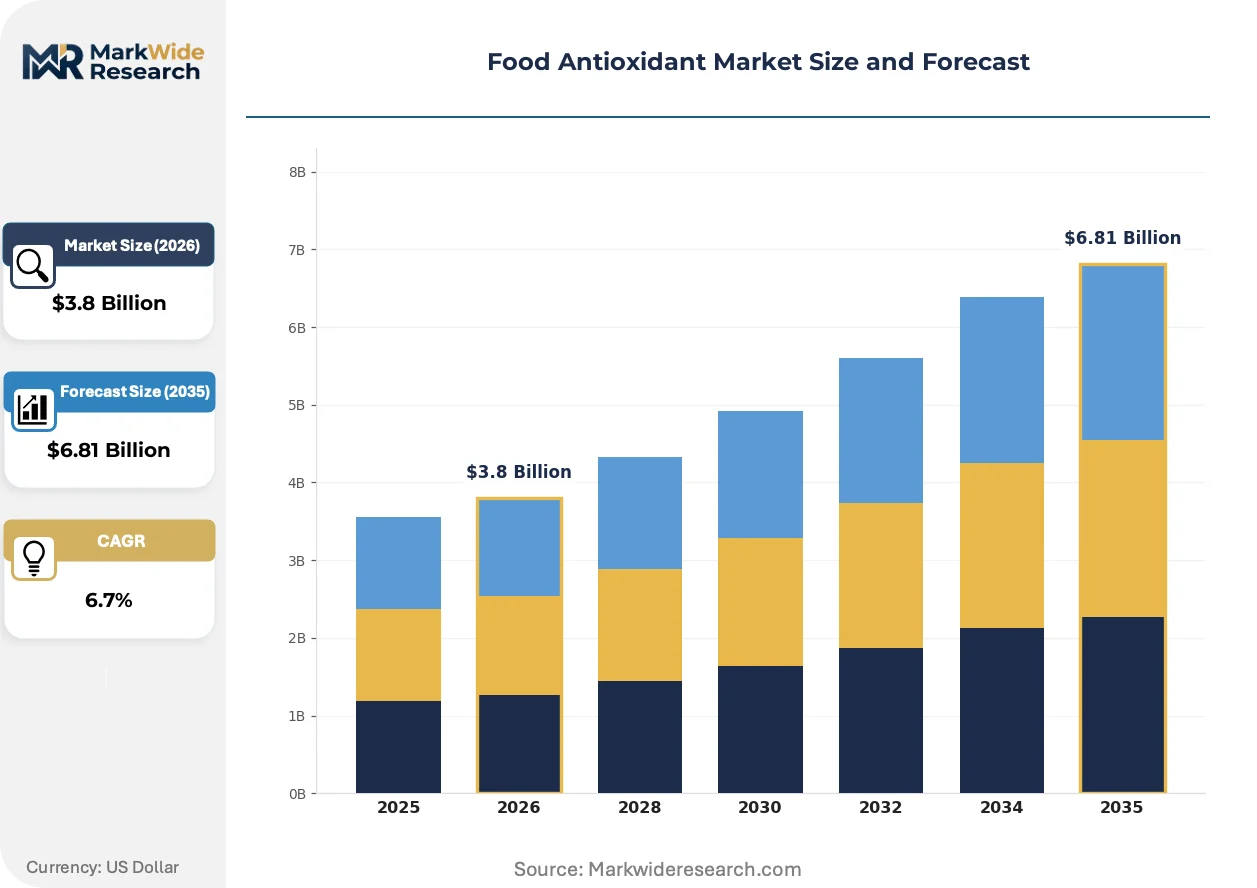
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Botanical Extracts, Vitamins Application: Food Preservation, Nutraceuticals, Beverages, Animal Feed Form: Powder, Liquid, Granules, Capsules End User: Food Manufacturers, Beverage Companies, Dietary Supplement Firms, Retailers |
| Companies Covered | BASF SE, Archer Daniels Midland Company, DuPont, Kemin Industries, Cargill Incorporated, Kalsec Inc., Eastman Chemical Company, Camlin Fine Sciences, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Antioxidant Market Emerging Trajectories
Antioxidant delivery formats are diverging sharply between powder systems optimized for handling efficiency and liquid carriers engineered for dispersion uniformity. This bifurcation is compressing the middle tier of formulation suppliers.
Encapsulation technologies using modified starch and lipid matrices are fragmenting the traditional antioxidant market. Bakery and confectionery manufacturers are adopting these systems to mask bitter polyphenol notes. The structural consequence is a collapse in demand for uncoated extract powders that previously dominated commodity procurement.
EFSA's systematic re-evaluation of synthetic antioxidants under EU Regulation 1333/2008 is constraining butylated hydroxyanisole approvals. Industrial consequence includes redirected investment toward toxicological validation of rosemary and green tea extracts. German meat processors face the most compressed transition timelines as clean-label standards tighten fastest in this jurisdiction.
Ingredient buyers are consolidating supplier relationships around vertically integrated extract producers. Direct contracting with botanical cultivation operations is displacing spot-market purchasing. This concentration is most visible in Germany, where meat manufacturers seek supply security against EFSA-driven formulation disruptions.
Food Antioxidant Market Segmentation
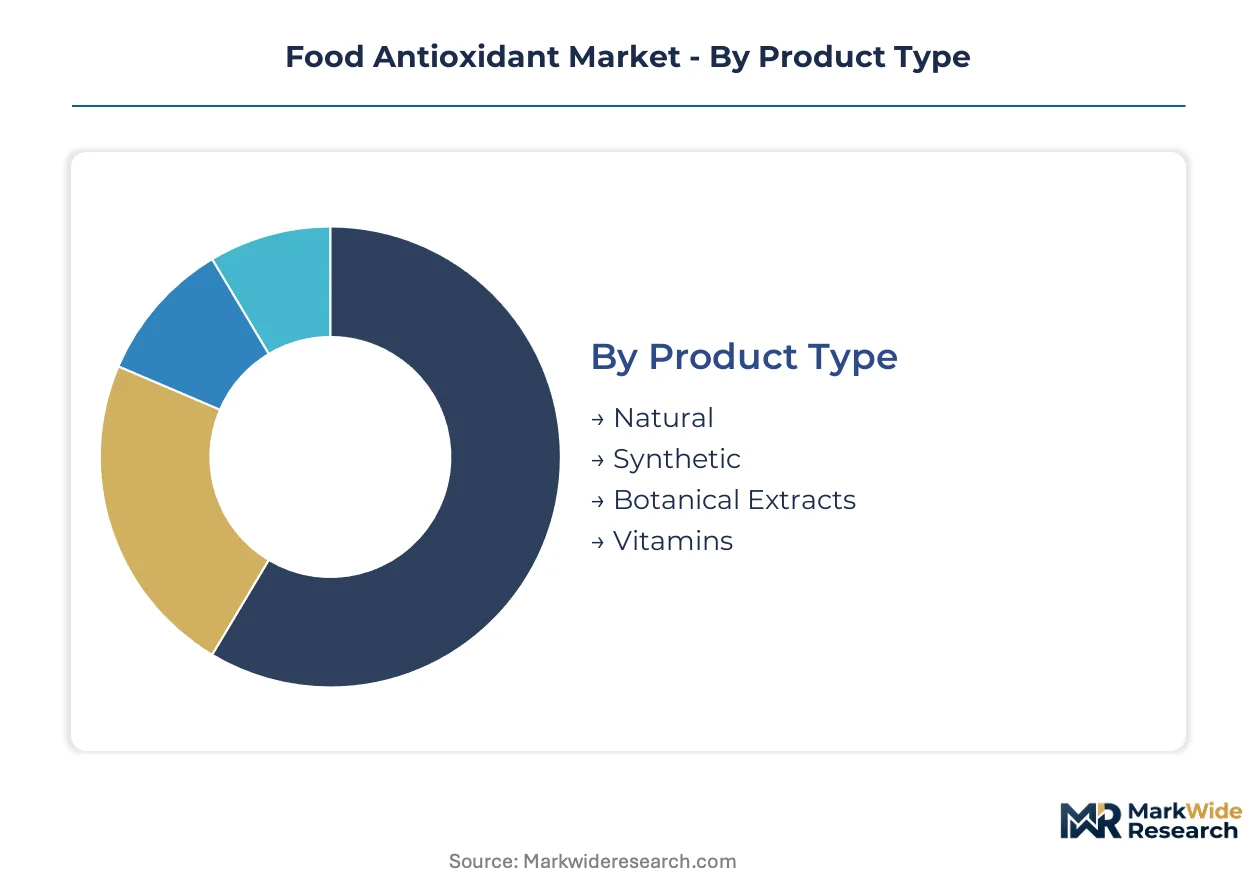
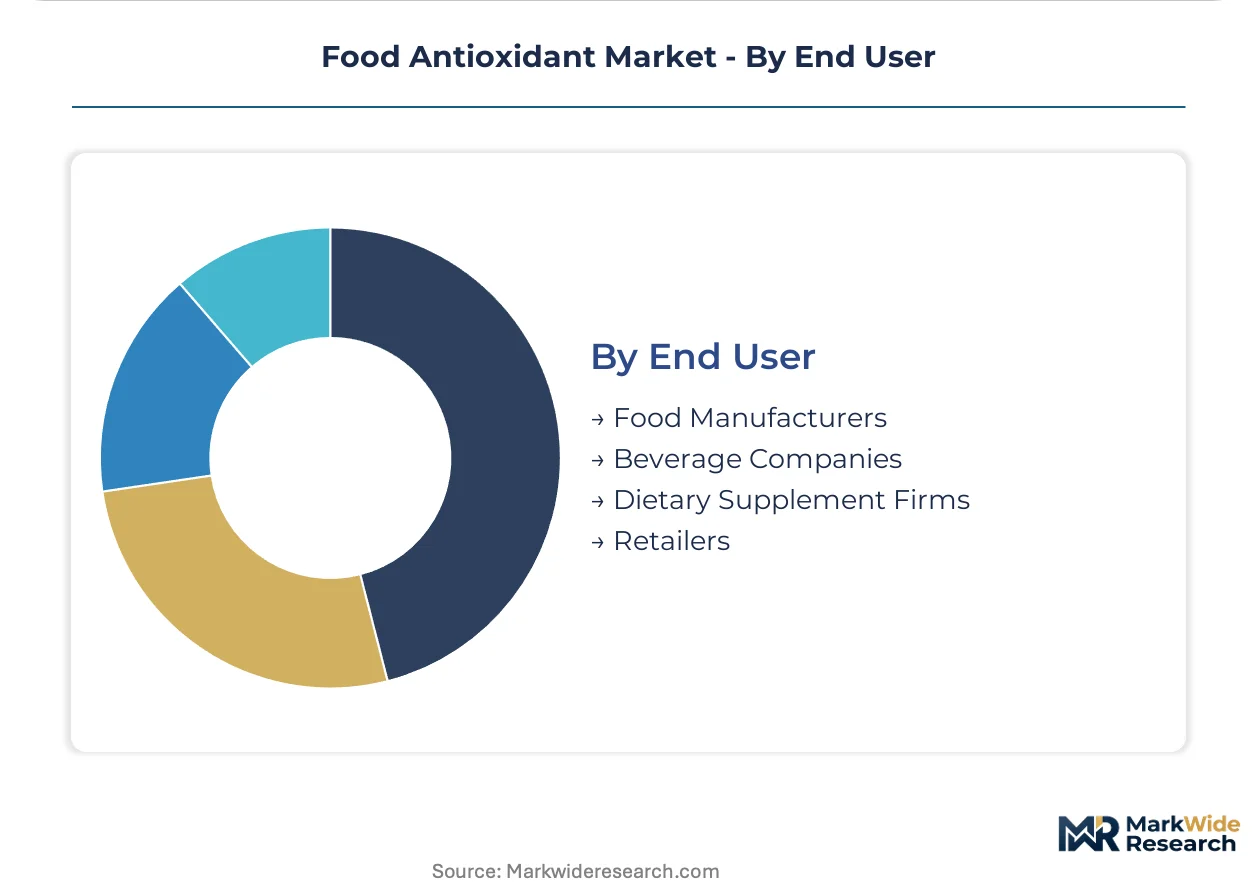
Antioxidant procurement patterns diverge sharply across product origins and application matrices, with margin capture concentrating in segments that solve clean-label compliance challenges. Formulation complexity and regulatory fragmentation are reshaping supplier-customer relationships within each dimension.
Product Type:
Margin pools concentrate in botanical-derived categories where EFSA-driven reformulation is collapsing synthetic cost advantages.
- Natural:Rosemary, green tea, and mixed tocopherol extracts dominate clean-label positioning. German meat processors are redirecting procurement budgets here as REACH restrictions compress synthetic alternatives. Weather-driven harvest volatility in Spain and Morocco constrains margin stability.
- Synthetic:Butylated hydroxyanisole and butylated hydroxytoluene retain volume leadership in cost-sensitive animal feed channels. BASF SE sustates cost advantages through captive petrochemical feedstock access, though EFSA re-evaluation protocols are narrowing approved applications.
- Botanical Extracts:Standardized polyphenol concentrates from Mediterranean cultivation networks command premium positioning.
- Vitamins:Grain-derived tocopherol supply chains feed dual food and feed applications.
Natural holds installed capacity. Botanical Extracts is rotating up the share rankings.
Application:
Application-driven demand concentrates where lipid oxidation risk intersects with extended distribution requirements.
- Food Preservation:Powder formulations lead across processed meat and poultry manufacturing due to handling efficiency and dosing precision. Dual-extraction protocols for tocopherol recovery are gaining traction as manufacturers replace synthetic preservatives across chilled and frozen product lines.
- Nutraceuticals:Encapsulation technologies using modified starch matrices mask bitter polyphenol notes. The structural consequence is collapsing demand for uncoated extract powders.
- Beverages:Liquid carriers and nanoemulsion technologies enable homogeneous dispersion in functional drinks.
- Animal Feed:Volume leadership persists in synthetic antioxidants where cost sensitivity dominates procurement criteria.
Food Preservation anchors current revenue. Beverages is climbing the fastest.
Form:
Delivery format selection directly determines capital deployment requirements for processor infrastructure.
- Powder:Dominates industrial food manufacturing with established handling systems and dosing precision. Legacy equipment across mid-tier processors reinforces this format's installed base despite liquid alternatives gaining traction.
- Liquid:Nanoemulsion carriers are expanding most quickly in beverage applications where dispersion uniformity proves critical. Capital redeployment demands constrain adoption among smaller processors.
- Granules:Flow-enhanced formats reduce dust exposure in high-volume meat processing environments.
- Capsules:Pre-measured units serve dietary supplement channel requirements.
Powder retains infrastructure lock-in. Liquid is gaining share fastest.
End User:
Customer type determines technical service intensity and contract structure preferences.
- Food Manufacturers:Processed meat and poultry producers face compressed transition timelines under tightening German clean-label standards. Direct contracting with vertically integrated extract producers is displacing spot-market purchasing.
- Beverage Companies:Clear-label incorporation requirements are driving nanoemulsion technology adoption.
- Dietary Supplement Firms:Batch-to-batch polyphenol standardization commands premium analytical validation.
- Retailers:Private-label clean-label positioning is consolidating supplier relationships around provenance-verified botanical sourcing.
Food Manufacturers hold procurement volume. Beverage Companies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA anchors the dominant geography through systematic re-evaluation protocols under EU Regulation 1333/2008. Procurement patterns concentrate where clean-label mandates intersect with established meat processing infrastructure.
Germany
Processed meat manufacturers face compressed transition timelines as REACH restrictions tighten synthetic antioxidant approvals. The Federal Institute for Risk Assessment enforces accelerated compliance schedules for butylated hydroxyanisole replacement. The Lower Saxony meat processing cluster around Oldenburg is redirecting procurement budgets toward rosemary extract alternatives.
United States
The FDA maintains Generally Recognized As Safe listings for synthetic antioxidants while accelerating natural ingredient notification reviews. Grain-derived tocopherol supply chains feed both food and animal feed channels across the Midwest. Archer Daniels Midland Company anchors dual-channel infrastructure from Illinois processing facilities.
China
Domestic food manufacturers are expanding antioxidant procurement as clean-label positioning penetrates premium product tiers. The National Health Commission periodically revises approved additive lists under GB 2760 standards. The Yangtze River Delta processing hub around Shanghai requires dedicated regulatory navigation support for export-oriented manufacturers.
Spain
Mediterranean botanical cultivation networks supply rosemary oleoresin to European formulators seeking provenance-verified sourcing. Weather-driven harvest volatility in Andalusia and Murcia compresses margin structures for extract-dependent suppliers. The Albacete agricultural cluster is securing supply continuity through vertically controlled cultivation partnerships.
India
Domestic processed food manufacturers are adopting natural antioxidants as FSSAI tightens additive disclosure requirements. The Food Safety and Standards Authority mandates cleaner label declarations across packaged meat and snack categories. The Maharashtra food processing corridor around Mumbai and Pune is consolidating supplier relationships around standardized polyphenol concentrates.
Food Antioxidant Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Food Antioxidant Market. Petrochemical-anchored conglomerates sustain cost advantages in synthetic antioxidant production through captive feedstock access. Botanical sourcing specialists and grain-derived tocopherol processors occupy distinct competitive niches. Capacity expansion in Mediterranean cultivation networks and strategic partnerships for nanoemulsion technology licensing represent the dominant competitive moves reshaping supplier positioning.
Within the integrated petrochemical tier, BASF SE exemplifies scale-driven synthetic antioxidant production. Among botanical sourcing specialists, Kemin Industries occupies a position representing vertically controlled cultivation networks. Archer Daniels Midland Company anchors the grain-derived tocopherol segment serving dual food and feed applications. These three entities collectively represent the strategic archetypes competing for procurement budgets across reformulating meat processors and beverage manufacturers.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| DuPont |
| Kemin Industries |
| Cargill Incorporated |
| Kalsec Inc. |
| Eastman Chemical Company |
| Camlin Fine Sciences |
| Koninklijke DSM N.V. |
| Others |
Supply Flow & Price Mechanics
EFSA's systematic re-evaluation protocols under EU Regulation 1333/2008 gate both supplier qualification and price differentiation simultaneously, compressing synthetic antioxidant margins while elevating botanical extract premiums across European procurement channels.
Pricing Analysis
Long-term offtake agreements dominate procurement between vertically integrated extract producers and German meat processors facing compressed REACH compliance timelines. Price differentiation rests on certification grade and provenance-verified botanical sourcing, with EFSA-compliant rosemary oleoresin commanding substantial premiums over unvalidated alternatives. Cost compression in synthetic tiers intensifies as petrochemical feedstock volatility erodes BASF SE's historical cost advantage. Animal feed manufacturers exhibit highest price sensitivity due to volume procurement and minimal clean-label requirements.
Supply Chain Analysis
Spain and Morocco anchor Mediterranean rosemary oleoresin cultivation, while the American Midwest feeds grain-derived tocopherol supply chains through Archer Daniels Midland Company's Illinois processing facilities. Raw material dependencies center on harvest yields in Andalusia, petrochemical naphtha streams, and dual-extraction tocopherol recovery infrastructure. Weather-driven supply interruptions in Mediterranean growing regions constitute the dominant structural risk. Distribution runs through direct contracting arrangements that displace spot-market purchasing among reformulating meat processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where EFSA compliance timelines and REACH restriction schedules create switching costs that lock processors into validated supplier relationships.
For Market Incumbents: Shield market position by deepening backward integration into Mediterranean botanical cultivation networks before harvest volatility escalates. Accelerate toxicological validation investments for green tea and rosemary extracts to preempt emerging entrant certification bids. Channel control through direct long-term offtake agreements with German meat processors represents the critical defensive lever.
For New Entrants and Emerging Players: Technical service gaps in nanoemulsion beverage dispersion systems present immediate white-space opportunity, as incumbent botanical specialists under-serve clear-label functional drink manufacturers. GB 2760 compliance advisory services for Asia-Pacific exporters constitute the most penetrable segment given regulatory complexity and limited incumbent coverage. A go-to-market angle anchored in analytical method harmonization across EFSA and FDA notification pathways differentiates against commodity extract suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nanoemulsion technology licensing and encapsulation infrastructure, favoring acquisition targets with proven scale-up capabilities over early-stage extraction plays. Vertically integrated botanical cultivators with EFSA-validated supply chains represent the priority archetype. The signal to watch is accelerated direct contracting adoption among German meat processors as an inflection indicator for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Cultivation | Secures supply continuity against EFSA-driven formulation disruptions in German meat processing. |
| Nanoemulsion Technology Licensing | Enables clear-label incorporation into functional beverages where homogeneous dispersion proves critical. |
| Long-term Supply Agreement | Locks procurement relationships with reformulating processors facing compressed REACH compliance timelines. |
| Regulatory Compliance Service Expansion | Captures GB 2760 navigation demand from Asia-Pacific exporters targeting Chinese food manufacturers. |
| Encapsulation Infrastructure Investment | Addresses collapsing demand for uncoated extract powders in bakery and confectionery applications. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, procurement directors at meat processors, regulatory affairs specialists, and botanical cultivation operators; and secondary validation through EFSA additive re-evaluation databases, FDA Food Ingredient Contact Notification records, REACH restriction timelines, and customs trade flows for oleoresin and tocopherol categories. Bottom-up segment sizing triangulated against top-down market boundary estimates derived from petrochemical feedstock allocation disclosures and grain processing capacity reports.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product origin, application matrix, delivery format, and end-user procurement structure. CAGRs were derived from regression analysis against regulatory compliance schedule acceleration, clean-label penetration rates in processed meat categories, and nanoemulsion technology adoption curves. Forecast inputs incorporated EFSA re-evaluation protocol timelines, REACH restriction implementation phases, and GB 2760 revision cycles.
Forecasts assume regulatory continuity in EFSA, FDA, and National Health Commission regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated synthetic antioxidant bans, severe Mediterranean harvest failures, or abrupt GB 2760 standard revisions. Recalibration cycles align with material shifts in regulatory re-evaluation schedules and clean-label procurement adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Flavonoids Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Global Zeaxanthin Market