
 Food Grade Alginate Market | 2026-2036
Food Grade Alginate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Alginate Market Foresight
Modular ingredient bundling—where alginate suppliers package hydrocolloid blends with tailored viscosity profiles—is realigning how food manufacturers evaluate procurement contracts. KIMICA Corporation leverages its integrated seaweed farming operations to sustain supply consistency for Japanese and European dairy processors. Cargill, Incorporated anchors its position through backward integration into Atlantic brown seaweed sourcing, while CP Kelco Corporation differentiates via specialized alginic acid extraction technologies that yield higher guluronate ratios for meat-binding applications.
Food grade alginate comprises linear copolymers of β-D-mannuronic acid and α-L-guluronic acid extracted from brown seaweed species including Laminaria hyperborea and Macrocystis pyrifera, with the mannuronate-to-guluronate ratio determining gel strength, elasticity, and calcium reactivity in food matrices. Sodium alginate dominates formulation volumes across dairy and meat processing segments due to its cold-water solubility and controlled gelation with calcium salts, while calcium alginate occupies niche positions in encapsulation and structured meat applications where heat-stable gel networks command premium positioning. Powder bags remain the standard packaging configuration for industrial-scale food manufacturers, though liquid containers are gaining traction among beverage producers seeking direct-pump dosing systems.
EFSA and FDA frameworks govern alginate purity specifications, residual heavy metal limits, and additive labeling under E401-E405 designations, with EFSA's 2017 re-evaluation of sodium alginate tightening arsenic thresholds that redirected sourcing toward Atlantic versus Pacific seaweed stocks. China's SAMR and GB standards enforce parallel contaminant controls for domestically processed alginates entering the food chain. Stakeholders must monitor how evolving EU seaweed cultivation sustainability certifications and emerging state-level seaweed aquaculture permits in the United States reshape raw material access and cost structures.
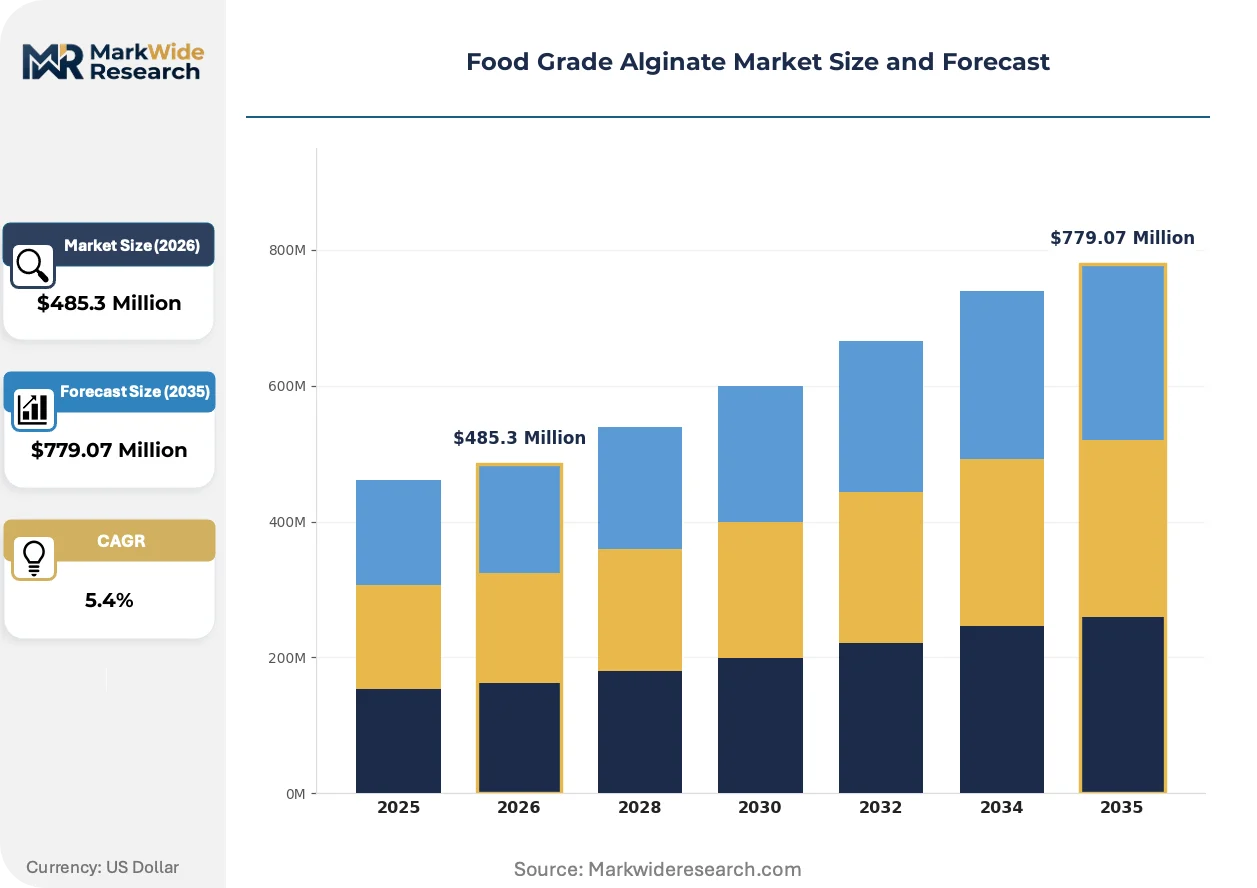
Market Dynamics
Clean-label reformulation mandates across EU member states are compressing synthetic hydrocolloid substitution timelines for alginate suppliers, while Chinese processing clusters consolidate raw material access for Asian food manufacturers.
Growth Catalysts
- EU Green Deal alignment:Seaweed-derived hydrocolloids gain preferential positioning under F-Gas Regulation tightening, redirecting bakery and confectionery procurement toward Atlantic-sourced alginates.
- Calcium-reactive gel networks:Meat processors deploy sodium alginate for cold-set binding applications, displacing phosphate systems in clean-label product lines.
- Qingdao-Dalian corridor concentration:Integrated brown seaweed farming and extraction infrastructure in Shandong and Liaoning provinces supplies downstream Asian dairy and beverage manufacturers at scale.
Market Restraints
- Arsenic threshold compression:EFSA's tightened heavy metal specifications for sodium alginate (E401) restrict viable seaweed stocks to Laminaria hyperborea harvests from Atlantic waters, elevating raw material costs.
- Brown seaweed supply geography:Macrocystis pyrifera harvesting concentrates along Chilean and Californian coastlines, exposing processors to climate-driven kelp forest volatility and seasonal yield compression.
- Protein isolate substitution:Pea and soy protein binding systems achieve functional parity in emulsified meat matrices at lower unit economics for cost-sensitive processors.
Strategic Opportunities
- Encapsulation application expansion:Calcium alginate gel beads command premium positioning in probiotic and omega-3 delivery systems for functional food manufacturers seeking gastric acid protection.
- US state-level aquaculture permitting:Emerging seaweed cultivation licenses in Maine and Alaska create domestic Atlantic biomass alternatives to Pacific import dependence.
- Direct-pump liquid dosing:Beverage producers adopt liquid alginate containers for continuous processing lines, bypassing powder reconstitution steps and reducing labor intensity.
Industry Challenges
- Alginic acid extraction specialization:Higher guluronate ratio production requires capital-intensive fractionation equipment that mid-scale processors struggle to deploy.
- Multi-jurisdiction certification synchronization:Simultaneous EFSA, FDA, and SAMR compliance timelines extend product launch cycles for alginate suppliers serving multinational food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Alginate Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alginate, Potassium Alginate, Ammonium Alginate, Calcium Alginate Application: Dairy Products, Bakery Items, Meat Processing, Confectionery, Beverages End User: Food Manufacturers, Beverage Producers, Confectionery Makers, Meat Processors, Dairy Processing Units Packaging Type: Powder Bags, Bulk Bags, Liquid Containers, Sachets |
| Companies Covered | FMC Corporation (Ingredion Incorporated), DuPont de Nemours, Inc. (IFF), KIMICA Corporation, Cargill, Incorporated, Algaia S.A., CP Kelco Corporation, Qingdao Bright Moon Seaweed Group Co., Ltd., Shandong Jiejing Group Corporation, Ingredients Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Alginate Market Shifts & Advancements
Modular hydrocolloid blending systems are reconfiguring how food manufacturers evaluate alginate procurement, shifting from single-ingredient specifications to viscosity-profiled solutions tailored to specific processing lines.
Controlled-release encapsulation technology is decentralizing probiotic and active ingredient protection from synthetic polymer systems toward calcium alginate gel networks. Functional food manufacturers in Germany and Japan adopt these systems for temperature-sensitive bioactive delivery. This shift is decentralizing supply relationships from centralized chemical suppliers toward specialized seaweed extraction operations with fractionation capabilities.
EFSA's 2017 sodium alginate re-evaluation and subsequent arsenic threshold reductions have redirected sourcing strategies toward Atlantic brown seaweed stocks. European dairy processors now specify Laminaria hyperborea-derived alginates in procurement contracts to preempt compliance failures. Meat-binding applications in France and the Netherlands experience the most acute reformulation pressure as clean-label mandates accelerate.
Ingredient bundling contracts are replacing single-hydrocolloid purchasing for industrial-scale food manufacturers. Bakery and confectionery producers in Italy and Spain now procure pre-blended viscosity-modified alginate systems rather than in-house formulation. This pattern concentrates procurement decision-making among technical service teams rather than commodity buyers, elevating supplier R&D capabilities as a selection criterion.
Food Grade Alginate Market Segmentation
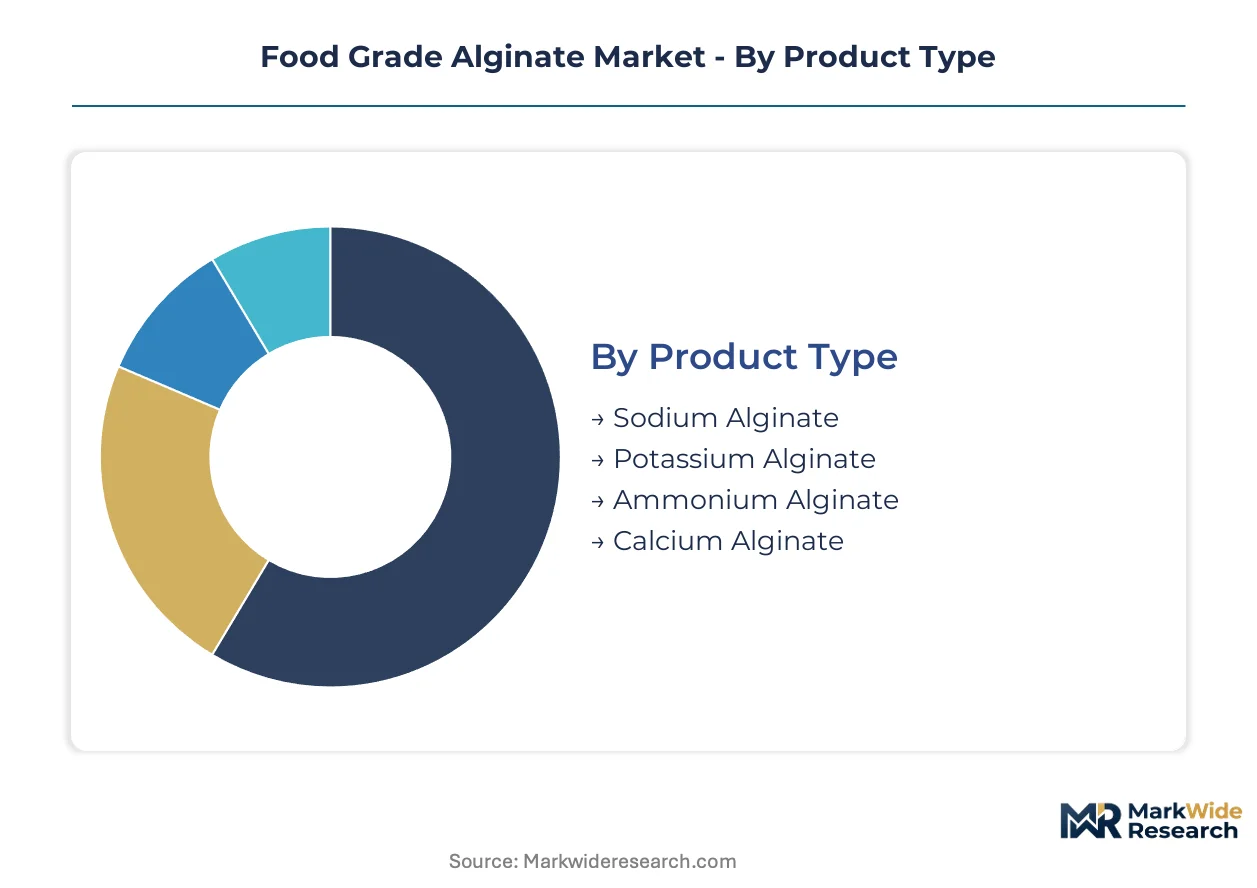
Segmentation in food grade alginate reveals how hydrocolloid functionality aligns with distinct processing requirements across dairy, meat, and bakery matrices. Each dimension—product chemistry, application, end-user scale, and packaging format—carries different margin profiles and technical service intensity.
Product Type:
Sodium alginate dominates standalone cold-set gelling applications, while calcium and potassium variants embed within multi-hydrocolloid systems for specialized binding or encapsulation functions.
- Sodium Alginate:Linear copolymer of β-D-mannuronic and α-L-guluronic acid with cold-water solubility and calcium-reactive gelation. Dairy processors in Germany and France specify this grade for clean-label yogurt structuring under EFSA E401 compliance timelines.
- Calcium Alginate:Pre-gelled insoluble form creating heat-stable networks for structured meat applications and probiotic encapsulation. Functional food manufacturers in Japan adopt this for gastric acid protection of temperature-sensitive bioactives.
- Potassium Alginate:Salt-tolerant variant for low-sodium meat reformulations where potassium chloride replacement requires compatible hydrocolloid chemistry.
- Ammonium Alginate:Niche film-forming applications in edible coatings for fresh produce preservation.
Sodium alginate leads volumes today; calcium alginate is gaining share fastest through encapsulation demand expansion.
Application:
Cost tier stratification separates commodity dairy and bakery uses from premium meat-binding and functional encapsulation segments requiring specialized fractionation.
- Dairy Products:Standardized viscosity grades for yogurt stabilization and ice cream overrun control. European processors specify Atlantic-sourced Laminaria hyperborea alginates to meet tightened EFSA arsenic thresholds.
- Meat Processing:Cold-set binding systems displacing phosphate additives in clean-label reformulations. French and Dutch processors face acute reformulation pressure under EU Green Deal alignment mandates.
- Bakery Items:Film-forming and moisture-retention functions in gluten-free and extended-shelf-life applications.
- Confectionery:Gel bead structuring for burst-release flavor systems and controlled dissolution profiles.
- Beverages:Direct-pump liquid dosing systems bypassing powder reconstitution in continuous processing lines.
Dairy applications anchor current procurement volumes; meat processing exhibits the steepest expansion trajectory driven by phosphate substitution mandates.
End User:
Customer type determines whether alginate enters as commodity-specified bulk ingredient or as bundled viscosity-profiled solution with technical service attachment.
- Food Manufacturers:Integrated procurement of hydrocolloid blends with tailored rheology specifications rather than single-ingredient purchasing. Italian and Spanish bakery producers now delegate formulation to supplier R&D teams.
- Meat Processors:Specialized demand for higher guluronate ratio alginates requiring capital-intensive fractionation equipment that concentrates supply among extraction specialists.
- Dairy Processing Units:Volume-driven procurement with strict EFSA and FDA purity documentation requirements extending product launch cycles.
- Beverage Producers:Adoption of liquid container formats for direct-pump dosing systems reducing labor intensity.
- Confectionery Makers:Precision-controlled gel bead applications demanding consistent mannuronate-to-guluronate ratios.
Food manufacturers represent the largest addressable base; meat processors command the highest technical service premiums.
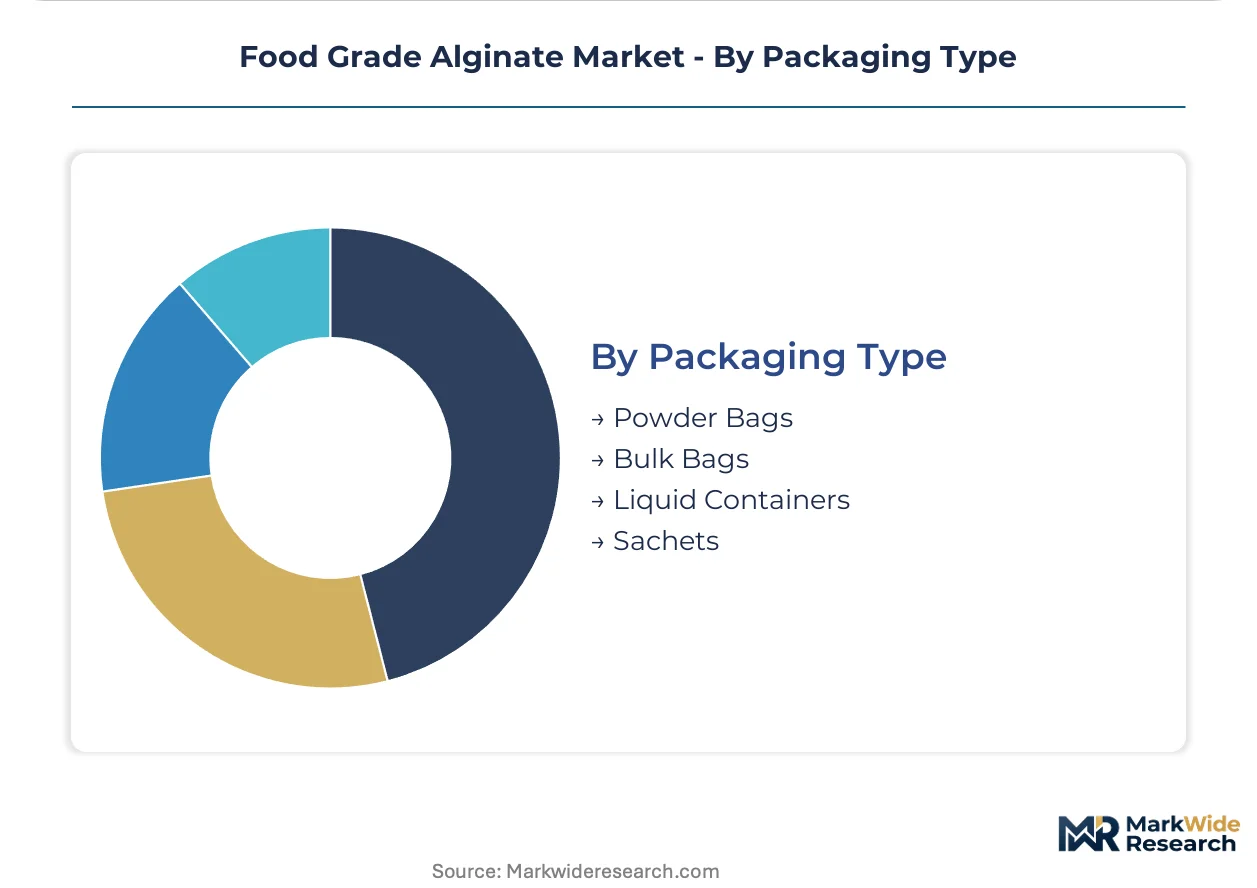
Packaging Type:
Volume scale and processing automation level dictate packaging selection, with powder formats retaining industrial dominance while liquid systems penetrate continuous beverage lines.
- Powder Bags:Standard industrial configuration for bakery, dairy, and meat processors with in-house reconstitution capabilities and batch processing workflows.
- Liquid Containers:Direct-pump dosing format eliminating dissolution steps for beverage producers and continuous processing operations seeking labor reduction.
- Bulk Bags:Ton-scale delivery for major dairy and meat processing facilities with integrated handling infrastructure.
- Sachets:Precision-portioned format for artisan confectionery and small-batch food service applications requiring exact dosing control.
Powder bags retain volume leadership; liquid containers are climbing the fastest through beverage industry automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seaweed-derived hydrocolloid extraction originated in Japanese coastal communities during the early twentieth century, with industrial-scale alginate production later consolidating in Scotland and Norway before expanding to Chilean and Chinese waters.
China
Qingdao and Dalian processing clusters supply sodium alginate to dairy and beverage manufacturers across Asia. SAMR enforces GB standards for heavy metal limits in domestically processed alginates entering the food chain. Shandong and Liaoning provinces host integrated brown seaweed farming and extraction infrastructure that feeds downstream Asian food manufacturing at scale.
Japan
Japanese dairy processors specify alginate grades for yogurt structuring and ice cream overrun control. METI oversees food additive safety assessments under the Food Sanitation Act framework. Kanto-based extraction specialists maintain captive seaweed farming operations to sustain supply consistency for domestic and European customers.
Germany
German bakery and confectionery producers procure pre-blended viscosity-modified alginate systems rather than in-house formulation. EFSA's tightened arsenic thresholds for sodium alginate redirect sourcing toward Atlantic Laminaria hyperborea stocks. Bavarian and North Rhine-Westphalian food manufacturers drive clean-label reformulation timelines under EU Green Deal alignment mandates.
France
French meat processors deploy sodium alginate for cold-set binding applications displacing phosphate additives. The EU F-Gas Regulation tightens processing standards for seaweed-derived hydrocolloids used in clean-label product lines. Paris Basin and Normandy dairy operations specify Atlantic-sourced alginates to preempt EFSA compliance failures.
United States
American beverage producers adopt liquid alginate containers for direct-pump dosing systems in continuous processing lines. FDA purity specifications govern residual heavy metal limits and additive labeling under E401-E405 designations. Maine and Alaska state-level aquaculture permitting creates domestic Atlantic biomass alternatives to Pacific import dependence.
Food Grade Alginate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction specialization and guluronate ratio control. The vendor base stratifies between integrated seaweed farming operations, chemical conglomerates with backward integration into Atlantic brown seaweed sourcing, and mid-scale processors with fractionation capabilities. Three archetypes dominate: captive supply chain operators, diversified ingredient conglomerates, and extraction technology specialists. Competitive moves concentrate on strategic partnerships for raw material access and portfolio diversification into encapsulation-grade calcium alginate.
Within the integrated farming tier, KIMICA Corporation exemplifies captive supply chain operators leveraging Japanese coastal seaweed cultivation. Cargill, Incorporated anchors the diversified conglomerate archetype through upstream control over Atlantic biomass sourcing. CP Kelco Corporation occupies the extraction specialist position with alginic acid fractionation capabilities. Qingdao Bright Moon Seaweed Group Co., Ltd. and Shandong Jiejing Group Corporation represent Chinese processors supplying Asian dairy and meat manufacturers from Shandong-based infrastructure.
| Leading Market Players |
|---|
| FMC Corporation (Ingredion Incorporated) |
| DuPont de Nemours, Inc. (IFF) |
| KIMICA Corporation |
| Cargill, Incorporated |
| Algaia S.A. |
| CP Kelco Corporation |
| Qingdao Bright Moon Seaweed Group Co., Ltd. |
| Shandong Jiejing Group Corporation |
| Ingredients Solutions, Inc. |
| Others |
Supply & Pricing Matrix
Controlled-release encapsulation technology is compressing extraction economics while concentrating supply among fractionation-capable processors. EFSA's tightened arsenic thresholds simultaneously elevate Atlantic Laminaria hyperborea premiums and disqualify Pacific biomass from European pharmaceutical-grade contracts.
Pricing Analysis
Three-tier pricing structure across encapsulation-grade, food-standard, and industrial-economy levels dominates procurement contracts. Price differentiation rests on guluronate ratio precision and EFSA/FDA dual-certification status. Cost compression in standard-grade sodium alginate intensifies because Chinese processors expand Shandong capacity. Meat processors exhibit highest price sensitivity; functional food manufacturers seeking gastric acid protection show lowest.
Supply Chain Analysis
Dual-sourcing mandates from European dairy processors require simultaneous Atlantic and Pacific biomass qualification. Supply concentrates in China, Norway, and Chile. Raw material flows draw from Laminaria hyperborea, Macrocystis pyrifera, and Ascophyllum nodosum harvests. Single-source vulnerability runs through Chilean kelp forest climate volatility. Distribution feeds through technical service teams rather than commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
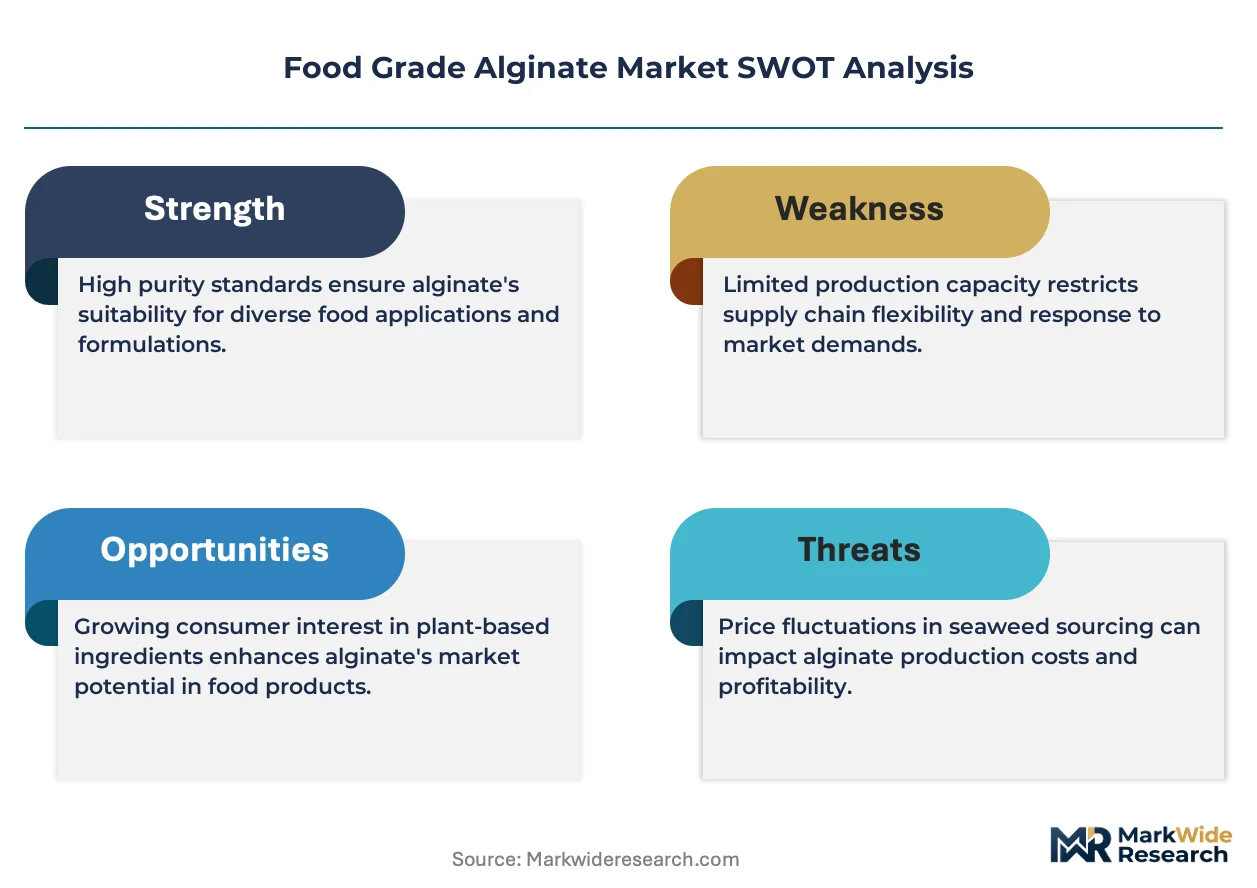
Food grade alginate represents a late-cycle quality story where EFSA compliance timelines and encapsulation-grade demand are redirecting procurement toward fractionation specialists. Premium specifications now govern contract renewals.
For Market Incumbents: Hedge Atlantic biomass exposure through Maine and Alaska aquaculture permitting while deepening alginic acid fractionation capabilities. Protein isolate substitution in cost-sensitive meat matrices threatens standard-grade volumes. Captive seaweed farming secures supply consistency for Japanese and European dairy processors. For New Entrants and Emerging Players: Launch via direct-pump liquid dosing systems for beverage automation lines. US state-level seaweed cultivation licenses offer the most penetrable white space. Encapsulation-grade calcium alginate for probiotic delivery commands technical service premiums that offset capital intensity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors with GB-standard compliance but lacking EFSA fractionation infrastructure. Long-term viability hinges on dual-jurisdiction certification synchronization capabilities. Watch EFSA heavy metal threshold reviews as inflection signal for Atlantic biomass repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atlantic Seaweed Farming | Cargill's Norwegian biomass sourcing secures EFSA-compliant raw material for European dairy contracts. |
| Alginic Acid Fractionation Capacity Expansion | CP Kelco's guluronate ratio control enables premium positioning in meat-binding applications. |
| Dual-Jurisdiction Certification Investment | KIMICA's simultaneous EFSA and SAMR compliance reduces product launch cycles for multinational food manufacturers. |
| Liquid Container Format Development | Beverage producers adopting direct-pump dosing bypass powder reconstitution labor costs. |
| Encapsulation Application Partnership | Calcium alginate gel networks displace synthetic polymers in German probiotic delivery systems. |
Research Methodology
Direct dialogue with extraction plant managers, hydrocolloid procurement leads at dairy and meat processors, EFSA regulatory affairs specialists, and Shandong-based distribution channel partners grounded qualitative insights. Secondary validation drew from customs trade data, EFSA additive re-evaluation dossiers, SAMR GB standard filings, and SEC 10-K disclosures from diversified ingredient conglomerates. Bottom-up volume modeling triangulated against top-down hydrocolloid market sizing.
Segment-level revenue outputs across sodium, calcium, potassium, and ammonium alginate grades were generated over the projection horizon. The analytical framework modeled chemistry type, application matrix, end-user scale, and packaging format dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating EFSA compliance timeline acceleration and encapsulation technology diffusion. Forecast inputs included Atlantic versus Pacific biomass availability differentials and state-level aquaculture permitting velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA heavy metal threshold revisions or kelp forest climate events. Deviation in EU Green Deal implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
India Food Hydrocolloids Market