
 Italy Food Hydrocolloids Market | 2026-2036
Italy Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Hydrocolloids Market Foresight
Clean-label bundling is pivoting how Italian food manufacturers specify hydrocolloid systems, with buyers now demanding pre-blended stabilizer packages that combine texturizing and shelf-life functions in single SKUs. Cargill Incorporated leverages its European ingredient network to supply these integrated systems across northern Italian dairy corridors. Tate & Lyle PLC anchors its position through specialized pectin and modified starch expertise tailored to Mediterranean formulation preferences. Archer Daniels Midland competes by extending its plant-protein adjacency into hydrocolloid blends for meat-alternative applications.
Italy food hydrocolloids comprise water-soluble biopolymers—primarily polysaccharides and proteins—that hydrate in aqueous systems to modify viscosity, gelation, and water-binding in processed foods, with typical usage levels ranging from 0.1% to 2.0% by weight depending on functional target. Gelatin dominates the product type landscape due to entrenched demand from confectionery and dairy applications, though pectin gains ground as clean-label gelling alternatives displace synthetic stabilizers in premium fruit preparations. Powder form leads volume shipments because of superior storage stability and dosing precision in automated Italian food manufacturing lines, while liquid hydrocolloids occupy niche positions in high-throughput sauce and dressing operations where inline dispersion matters.
Italy's Ministry of Health enforces EU-harmonized food additive standards through its national competent authority role, while FSSAI-aligned import checks on non-EU hydrocolloid shipments shape supplier qualification requirements for Indian and Southeast Asian gum sources. The EU Green Deal's Farm to Fork strategy is forcing reformulation timelines across Italian processed food sectors, with hydrocolloid suppliers now certifying sustainable sourcing credentials to maintain preferred vendor status. Stakeholders must monitor how Italy's transposition of the EU Deforestation Regulation reshapes supply chain documentation for tropical-origin gums like carrageenan and agar.
Market Dynamics
Clean-label reformulation mandates from the EU Green Deal's Farm to Fork strategy are compressing supplier qualification timelines across Italian food hydrocolloid procurement, forcing manufacturers to pre-certify sustainable sourcing credentials before contract renewal cycles.
Growth Catalysts
- EU Deforestation Regulation:Italian importers must document tropical-origin gum supply chains, accelerating demand for traceable carrageenan and agar alternatives from verified European sources.
- Emilia-Romagna dairy processing corridor:Concentrated yogurt and fresh cheese production in this northern cluster drives bulk pectin and gelatin consumption for texture standardization.
- Clean-label stabilizer blending:Food manufacturers now specify single-SKU hydrocolloid packages combining gelling and shelf-life functions, reducing formulation complexity and procurement overhead.
Market Restraints
- Seaweed supply volatility:Carrageenan and agar raw material costs fluctuate with Philippine and Indonesian harvest cycles, compressing margins for Italian texturizer compounders.
- Gelatin substitution ceiling:Plant-based gelling agents cannot replicate the melt-in-mouth profile of porcine gelatin in premium Italian confectionery, limiting clean-label penetration in traditional torrone and pastiglie segments.
- FSSAI-aligned import documentation:Non-EU gum shipments face extended laboratory testing protocols at Italian ports, delaying just-in-time delivery schedules for Southeast Asian suppliers.
Strategic Opportunities
- Lombardy plant-based meat alternatives:Emerging extruded protein applications require novel hydrocolloid binders to replace egg and dairy in vegan charcuterie formulations.
- CSRD-aligned sustainability reporting:Italian food manufacturers must disclose Scope 3 ingredient emissions, creating preferred supplier status for hydrocolloid vendors with certified carbon footprint data.
- Fermentation-derived precision hydrocolloids:Biotechnology platforms producing tailored polysaccharide structures enable functional matching to synthetic stabilizers with clean-label positioning.
Industry Challenges
- Cross-functional formulation expertise:Italian R&D teams lack specialists who bridge hydrocolloid science with automated dosing system engineering, slowing pilot-to-production scale-up.
- Legacy dairy equipment retrofitting:Powder-to-liquid hydrocolloid transition requires inline hydration system installation, demanding capital allocation that mid-tier processors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Hydrocolloids Market |
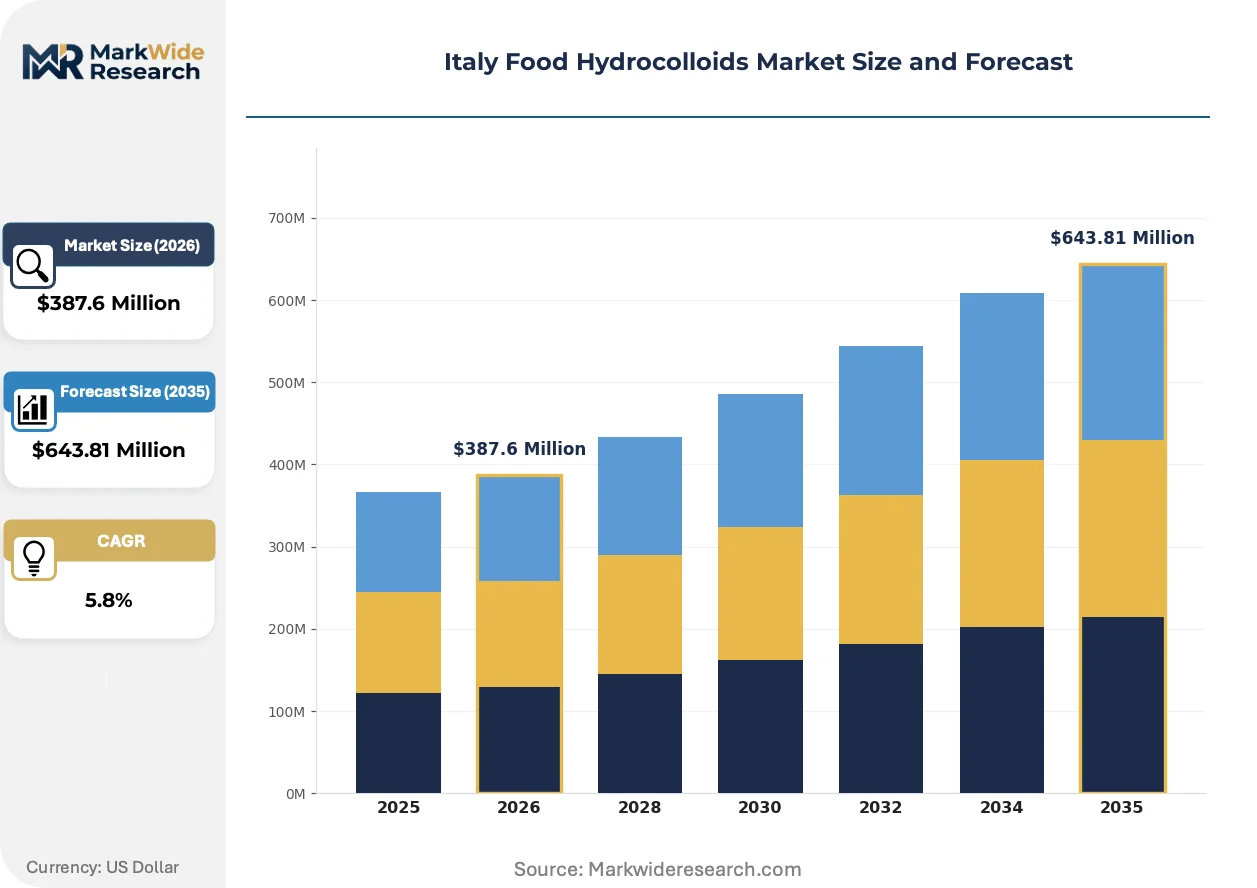
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Carrageenan Application: Dairy Products, Bakery, Meat Products, Sauces Form: Powder, Liquid, Granule, Sheet End User: Food Manufacturers, Restaurants, Retailers, Catering Services |
| Companies Covered | Ashland Global Holdings Inc, Archer Daniels Midland, Cargill Incorporated, Ideal Foods Sp, Behn Meyer Group, Ingredion Incorporated, Caldic BV, CP Kelco, Tate & Lyle PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Hydrocolloids Market Shifts & Advancements
Biotechnology and precision fermentation platforms are rewriting raw material sourcing assumptions for Italian hydrocolloid procurement, collapsing traditional geographic dependencies while introducing new bioprocess engineering requirements.
Precision fermentation of microbial polysaccharides is electrifying supplier R&D priorities across European ingredient houses. Italian dairy and alternative protein manufacturers are piloting these bio-identical hydrocolloids at accelerated 18-month evaluation cycles. The technology is compressing multi-year tropical cultivation timelines into weeks, threatening established seaweed and plant-extraction supply hierarchies.
The EU Green Deal's Farm to Fork strategy mandates 25% organic farming coverage and pesticide reduction targets that reshape hydrocolloid agricultural inputs. Italian food manufacturers now require documented sustainable cultivation credentials from gum arabic, locust bean, and guar suppliers. Premium fruit preparation and organic yogurt segments in northern Italy are first-movers, disqualifying uncertified vendors from tender processes.
Consolidated procurement of pre-blended stabilizer systems is replacing single-hydrocolloid purchasing across Italian food manufacturing. Large dairy processors in Lombardy and Emilia-Romagna now specify turnkey texture solutions rather than in-house formulation development. This behavioral shift concentrates buying power with integrated European suppliers capable of delivering functional guarantees, marginalizing commodity gum traders without application technical service capabilities.
Italy Food Hydrocolloids Market Segmentation
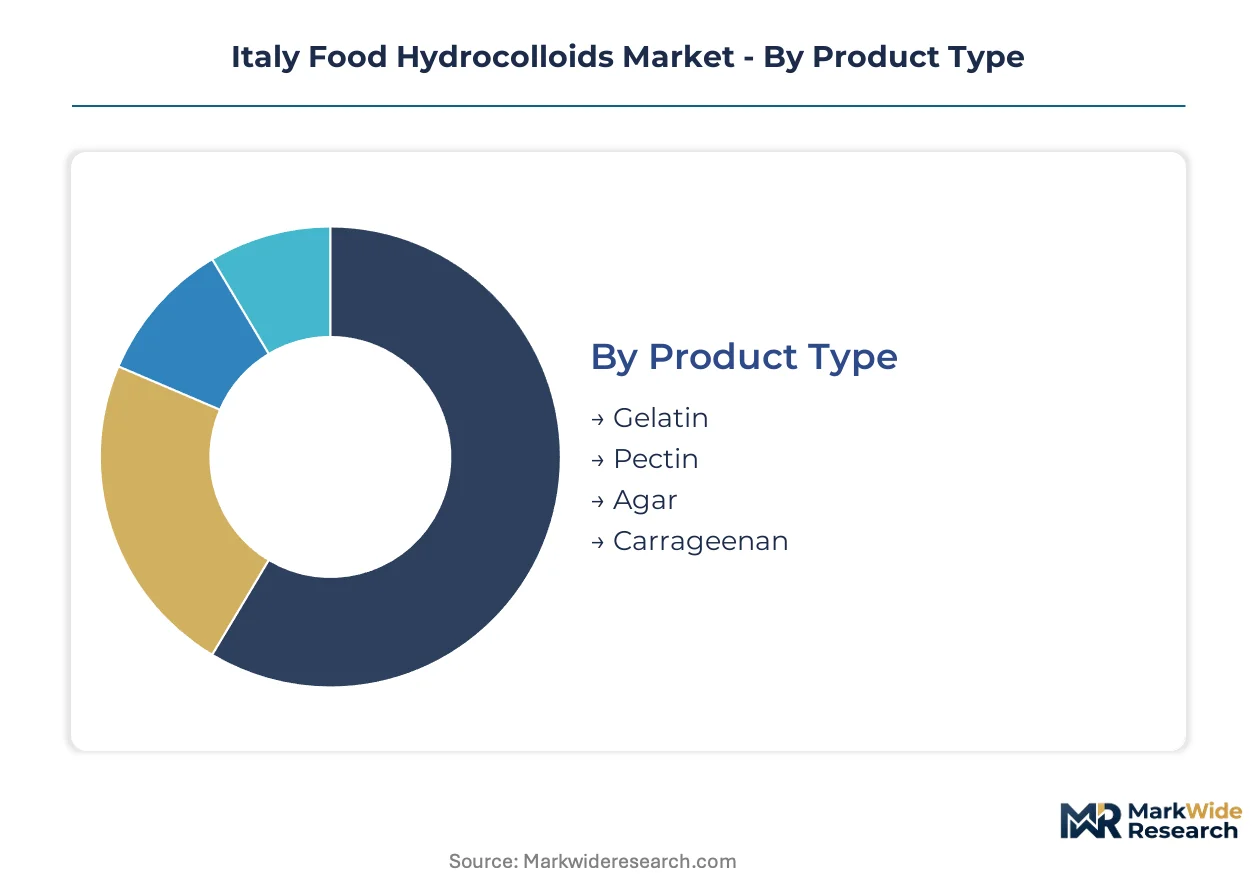
Italian food hydrocolloid procurement hinges on matching functional specifications to processing equipment constraints, with northern dairy corridors driving premium pectin and gelatin volumes while alternative protein startups reshape binder requirements. Segmentation reveals how clean-label mandates are compressing traditional category boundaries.
Product Type:
Formulation teams select hydrocolloids based on thermal stability requirements and label positioning targets, balancing cost against functional equivalence to synthetic alternatives.
- Gelatin:Derived from collagen hydrolysis, this protein-based gelling agent delivers irreproducible melt-in-mouth characteristics. Emilia-Romagna confectioners and Lombardy dairy processors anchor Italian demand, though porcine sourcing constraints limit clean-label penetration in premium torrone applications.
- Pectin:Extracted from citrus peel and apple pomace, this anionic polysaccharide forms thermoreversible gels in high-sugar, low-pH environments. Northern Italian organic yogurt manufacturers specify high-methoxyl grades for fruit preparation suspension, displacing synthetic stabilizers under EU Green Deal reformulation timelines.
- Agar:Seaweed-derived polysaccharide with superior gel strength at low concentrations; Emilia-Romagna plant-based cheese innovators pilot this for vegan mozzarella stretch replication.
- Carrageenan:Sulfated galactan from red algae; kappa and iota fractions dominate dairy texturization despite supply volatility from Philippine harvest cycles.
Gelatin leads on scale; pectin leads on momentum.
Application:
End-use concentration in northern Italy's food processing corridors dictates regional hydrocolloid inventory strategies and technical service deployment.
- Dairy Products:Yogurt, fresh cheese, and dessert applications require precise viscosity control and whey separation prevention. Lombardy processors specify pre-blended stabilizer systems combining pectin and starch for automated dosing compatibility.
- Bakery:Gelatin and agar control moisture migration in layered pastries and glazes; traditional panettone manufacturers maintain gelatin volumes despite clean-label pressure.
- Meat Products:Carrageenan and modified starches bind water in cooked hams and emulsified sausages; plant-based charcuterie startups in Milan demand novel hydrocolloid binders for extruded protein matrices.
- Sauces:Xanthan and guar gum suspensions stabilize dressings and condiments; liquid hydrocolloid concentrates enable inline dispersion for high-throughput bottling lines.
Dairy Products commands volume concentration; Meat Products shows steepest expansion trajectory from alternative protein formulation demand.
Form:
Physical presentation determines hydration kinetics, storage economics, and equipment compatibility across Italian manufacturing scales.
- Powder:Dominant shipment format offering extended shelf stability and gravimetric dosing precision; automated Lombardy dairy lines require dust-controlled particle size distributions for pneumatic conveying.
- Liquid:Pre-hydrated colloidal suspensions eliminate dispersion time; high-throughput sauce processors in Emilia-Romagna favor inline injection for continuous production.
- Granule:Intermediate dissolution rate for batch processing; mid-tier bakeries specify agar granules for controlled hydration in artisanal production.
- Sheet:Traditional gelatin presentation for premium confectionery; torrone producers in Cremona maintain sheet inventory for heritage recipe adherence.
Powder dominates operational economics; Liquid gains share fastest from continuous processing investments.
End User:
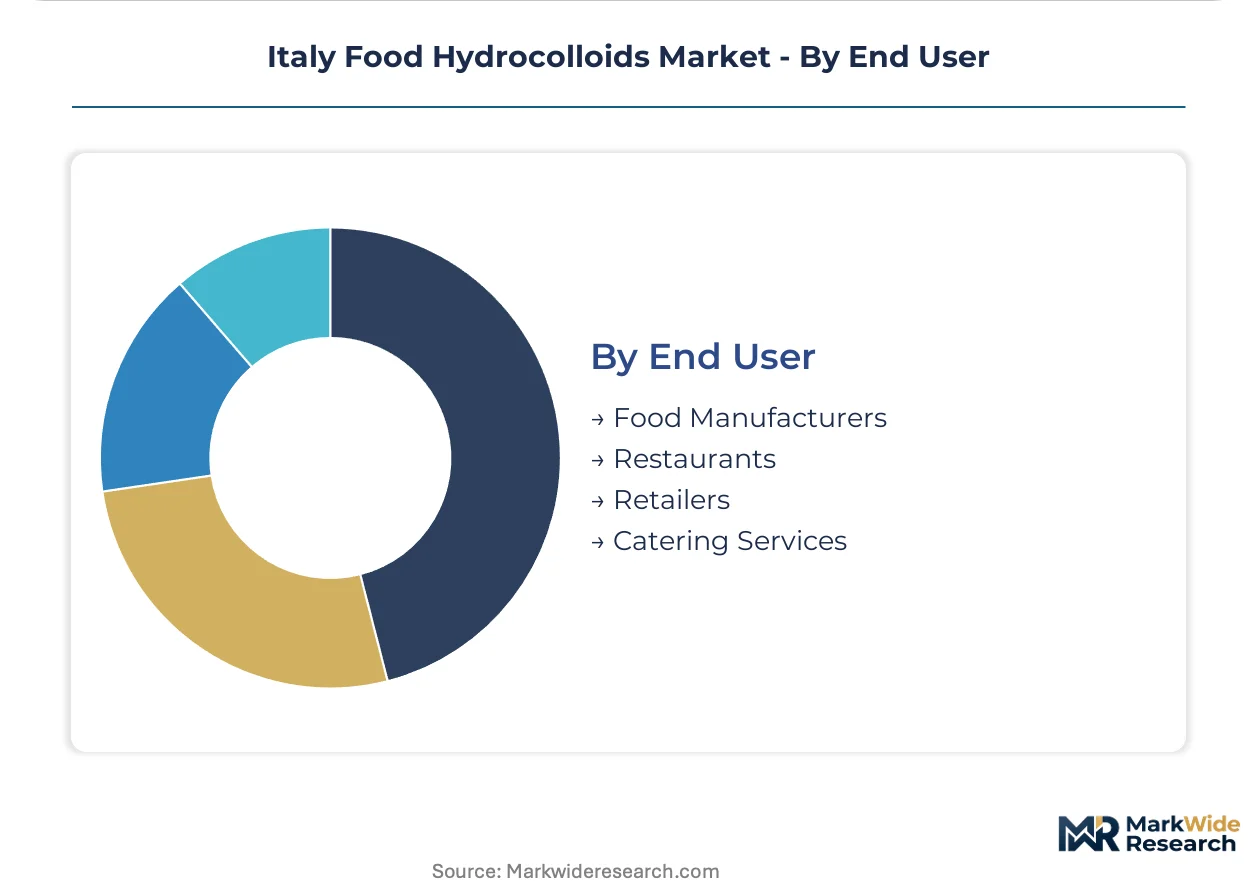
Procurement sophistication varies sharply across customer tiers, with integrated manufacturers demanding application technical service while foodservice prioritizes logistical reliability.
- Food Manufacturers:Large dairy and bakery compounders in northern Italy specify functional guarantees and sustainability documentation; CSRD-aligned carbon footprint data now conditions contract awards.
- Restaurants:Molecular gastronomy venues in Milan and Bologna source specialty hydrocolloids for spherification and gel textures; small-batch purchasing favors distributor intermediaries.
- Retailers:Private-label food producers require cost-optimized stabilizer blends; supermarket chains in Rome and Naples consolidate procurement through pan-European ingredient distributors.
- Catering Services:Industrial kitchen operators prioritize shelf-stable, pre-portioned hydrocolloid formats for consistency across decentralized production.
Food Manufacturers concentrate purchasing power; Restaurants expand most quickly from premium positioning strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's food hydrocolloid industry traces its modern foundations to post-war dairy cooperatives in the Po Valley, where gelatin stabilization of traditional fresh cheeses established technical expertise that now concentrates in northern processing corridors.
Lombardy
Milan anchors Italy's largest food manufacturing cluster, with yogurt and dessert processors driving bulk pectin and pre-blended stabilizer procurement. EFSA-aligned additive safety assessments condition ingredient approvals for automated dairy lines. The Milan hinterland concentrates multinational ingredient distributor warehouses serving pan-European supply chains.
Emilia-Romagna
Parma and Modena host heritage confectionery producers maintaining gelatin volumes for torrone and pastiglie despite clean-label pressures. The EU Green Deal's Farm to Fork pesticide reduction targets reshape sourcing specifications for organic fruit preparations. Bologna's food science universities feed specialized formulation talent into regional R&D labs.
Piedmont
Turin-based chocolate and hazelnut spread manufacturers specify lecithin-hydrocolloid hybrids for viscosity control in high-fat matrices. Italy's Ministry of Health enforces EU-harmonized additive standards through port-of-entry inspections at Genoa. The Alessandria-Asti corridor experiments with plant-based cheese analogues requiring novel agar and carrageenan binders.
Veneto
Verona and Vicenza processors supply European ready-meal markets with sauce applications demanding xanthan-guar stability under thermal processing. The EU Deforestation Regulation documentation requirements delay Southeast Asian gum shipments through Venice port. Treviso's prosecco district drives specialized encapsulation hydrocolloid demand for sparkling wine stabilization.
Tuscany
Florence and Pisa anchor artisanal gelato equipment manufacturing that shapes regional hydrocolloid hydration specifications. Organic certification bodies in Siena validate sustainable sourcing credentials for premium export-oriented food producers. The Chianti wine corridor applies pectinase-compatible stabilizers in low-intervention vinification.
Italy Food Hydrocolloids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service capabilities, with integrated European suppliers commanding price premiums for pre-blended stabilizer systems while traders compete on spot gum arbitrage. The vendor base stratifies into three tiers: multinational ingredient houses with application laboratories, regional compounders with formulation expertise, and import-dependent distributors without technical service. M&A activity concentrates on microbiome and fermentation technology acquisitions, while capacity expansion focuses on powder-to-liquid processing infrastructure for continuous manufacturing compatibility.
Within the multinational tier, Cargill Incorporated and Tate & Lyle PLC exemplify divergent positioning strategies—Cargill leveraging agricultural supply chain integration while Tate & Lyle occupies a specialization position in texturizing systems. Archer Daniels Midland represents the diversified agribusiness archetype, extending adjacent protein capabilities into hydrocolloid-adjacent formulation spaces. These three entities anchor competitive dynamics without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc |
| Archer Daniels Midland |
| Cargill Incorporated |
| Ideal Foods Sp |
| Behn Meyer Group |
| Ingredion Incorporated |
| Caldic BV |
| CP Kelco |
| Tate & Lyle PLC |
| Others |
Supply & Pricing Matrix
Premium-integrated stabilizer systems command three-to-four-fold markups over commodity gum spot purchases across northern Italian dairy corridors. EFSA-aligned certification tiers and CSRD-mandated carbon footprint documentation stratify supplier access, concentrating procurement leverage with European compounders capable of delivering pre-blended functional guarantees while marginalizing import-dependent traders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Italian hydrocolloid procurement, with organic-certified pectin and fermentation-derived precision polysaccharides anchoring premium brackets while unverified Southeast Asian carrageenan occupies economy tiers. Price differentiation hinges on EFSA safety dossier completeness and EU Deforestation Regulation supply chain traceability. Cost compression in commodity seaweed extracts intensifies because Philippine harvest volatility feeds raw material instability. Mid-tier dairy processors in Emilia-Romagna exhibit highest price sensitivity, whereas Milan-based alternative protein startups prioritize functional performance over unit economics.
Supply Chain Analysis
Direct-to-manufacturer channels handle bulk dairy processor demand while distributor intermediaries serve fragmented bakery and foodservice accounts across Italy. Raw material sourcing draws from Indonesia and the Philippines for carrageenan and agar, West Africa and India for gum arabic, and southern Europe for citrus-derived pectin. Seaweed supply concentration in Southeast Asian coastal regions creates single-source vulnerability for Italian texturizer compounders. Distribution runs through Rotterdam and Genoa port hubs with inland consolidation at Milan logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's food hydrocolloids sector operates as a regulatory compounder where EU Green Deal reformulation mandates and CSRD disclosure requirements generate sustained demand for certified sustainable sourcing credentials.
For Market Incumbents: Cement preferred supplier status by pre-certifying EU Deforestation Regulation documentation for tropical-origin gum supply chains before competitor renewal cycles. Deepen backward integration into fermentation-derived precision hydrocolloid production to offset seaweed supply volatility threatening margin stability in traditional extraction portfolios.
For New Entrants and Emerging Players: Enter via Lombardy plant-based meat alternative applications where novel binder requirements outpace established supplier technical service capacity. Target mid-tier Emilia-Romagna organic yogurt processors underserved by multinational compounders, leveraging rapid carbon footprint certification as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology platforms possessing microbial polysaccharide fermentation capabilities applicable to Italian clean-label reformulation demand. Long-term viability centers on precision hydrocolloid R&D assets with demonstrated pilot-to-production scale-up trajectories. Monitor EU transposition timelines for deforestation compliance enforcement as inflection indicator for supply chain restructuring velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biotechnology platforms collapse multi-year tropical cultivation timelines into weeks for Italian dairy reformulation. |
| EU Deforestation Regulation Compliance | Traceable supply chain documentation becomes mandatory gate for tropical-origin gum procurement contracts. |
| Pre-Blended Stabilizer System Development | Integrated functional guarantees concentrate buying power with European compounders serving Lombardy dairy corridors. |
| CSRD-Aligned Carbon Footprint Certification | Scope 3 emissions disclosure requirements reshape preferred supplier qualification across Italian food manufacturers. |
| Alternative Protein Binder Innovation | Vegan charcuterie extrusion applications in Milan drive novel hydrocolloid formulation demand beyond traditional dairy. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Italian dairy procurement directors, food manufacturer R&D leads, ingredient distributor category managers, and EFSA regulatory affairs specialists with secondary validation against EU customs trade data, Cefic chemical industry reports, SEC filings of multinational ingredient houses, and Italian Ministry of Health additive safety assessments. Bottom-up volume modeling across product type, application, and form segments triangulated against top-down market sizing from comparable European hydrocolloid markets.
Comparable historical periods anchored projection assumptions across the modeling period, with segmentation dimensions spanning gelatin versus plant-derived versus fermentation-derived source categories, dairy versus bakery versus meat alternative application end-uses, and powder versus liquid versus granule physical presentations. CAGRs derived from regression analysis of ingredient intensity trends in Italian processed food output, cross-referenced with EU Green Deal organic farming coverage targets and CSRD implementation timelines as structural demand drivers.
Inputs from Italian food manufacturer procurement systems and EFSA safety dossier databases were available through the study window; gaps in real-time Southeast Asian harvest yield data introduce uncertainty bands around carrageenan and agar price trajectory assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and clean-label adoption elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Europe Food Premix Market