
 Food Grade Magnesium Carbonate Market | 2026-2036
Food Grade Magnesium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Magnesium Carbonate Market Analysis
Market Context
The nutraceutical sector is decoupling from traditional baking applications as the primary demand engine for food grade magnesium carbonate. Hebei Meishen Technology leverages its integrated magnesite mining and refining operations to dominate domestic supply chains in Asia. Konoshima Chemical sustains competitive positioning through specialized high-purity grades that meet pharmaceutical-adjacent specifications. SCORA S.A.S anchors European demand with its longstanding technical-grade production expertise adapted for food compliance.
Technical Definition and Segment Structure
Food grade magnesium carbonate is a refined inorganic salt, typically synthesized to exceed 40 percent magnesium oxide equivalent and controlled for heavy metal content below 10 parts per million, functioning primarily as an anticaking agent, pH buffer, and magnesium fortification vehicle in processed foods and dietary supplements. The powder form leads volume due to its dispersion efficiency in industrial baking and dry mixing operations, while tablet and capsule formats within the product type category capture expanding margin pools as nutraceutical companies prioritize direct-to-consumer delivery systems. Application demand concentrates in nutritional supplements and food fortification, where magnesium bioavailability claims and clean-label positioning command premium positioning over conventional anticaking uses.
Regulatory Environment and Outlook
The FDA's food additive regulations under 21 CFR and the European Food Safety Authority's re-evaluation of magnesium additives as food fortificants are tightening purity benchmarks and reshaping supplier qualification requirements across both jurisdictions. China's National Health Commission and GB standards for food-grade mineral additives are simultaneously elevating domestic production norms, creating divergence in compliance pathways for exporters. Stakeholders must monitor evolving maximum permitted levels in fortified foods and the trajectory of organic mineral salt substitutes that could displace inorganic carbonate in premium supplement positioning.
Market Dynamics
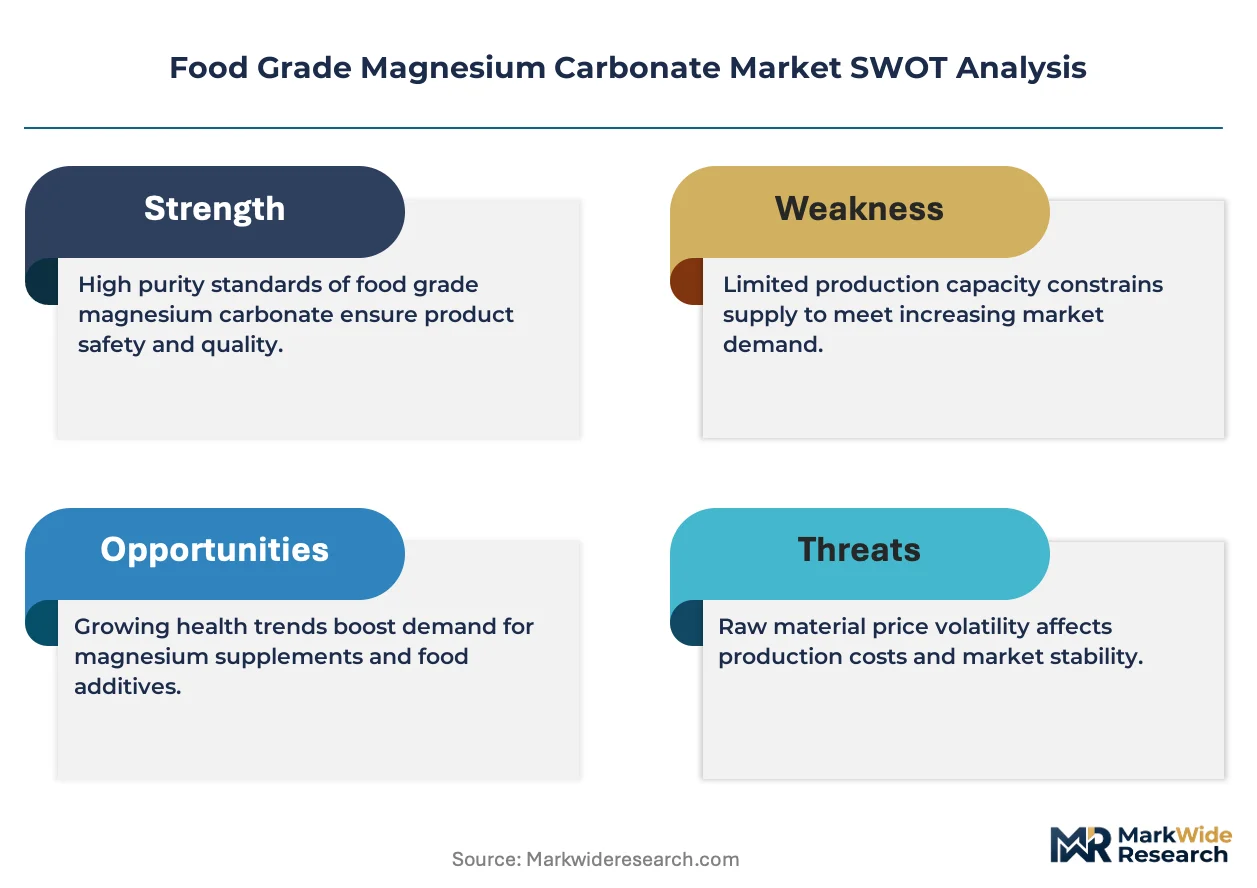
Nutraceutical manufacturers are pulling food grade magnesium carbonate away from traditional baking applications, creating supply tension as pharmaceutical-grade purity standards migrate downstream into functional foods and direct-to-consumer supplements.
Growth Catalysts
- EFSA Re-evaluation of Magnesium Additives:The European Food Safety Authority's 2023-2024 review of magnesium compounds as food fortificants has elevated permitted usage levels in fortified beverages, expanding addressable volume for compliant suppliers.
- China's GB Standard Harmonization:The National Health Commission's alignment of food-grade mineral additive standards with pharmaceutical purity benchmarks is unlocking export qualification for domestic magnesite processors.
- Tablet Manufacturing Automation:High-speed rotary tablet presses with integrated powder flow control are driving specification tightening for anticaking agents in nutraceutical contract manufacturing facilities.
Market Restraints
- Magnesite Ore Concentration:Over 60 percent of global feedstock mining clusters in Liaoning Province, exposing processors to concentrated geological risk and provincial environmental enforcement variability.
- Heavy Metal Compliance Costs:Lead and arsenic testing protocols under FDA 21 CFR 184.1425 and EFSA specifications require inductively coupled plasma mass spectrometry equipment that mid-tier producers cannot amortize.
- Organic Magnesium Salt Substitution:Magnesium glycinate and magnesium malate are capturing premium supplement positioning with superior bioavailability claims, compressing carbonate's addressable premium segment.
Strategic Opportunities
- India's FSSAI Fortification Mandates:The Food Safety and Standards Authority of India's mandatory rice and wheat fortification regulations are creating first-mover advantage for carbonate suppliers achieving BIS certification.
- Clean-Label Anticaking Positioning:"Mineral salt" ingredient declarations are displacing synthetic silica in premium snack and seasoning applications where EFSA-approved status supports marketing claims.
- Direct-to-Consumer Powder Sachets:Single-serve magnesium supplement formats are bypassing traditional pharmacy distribution, requiring micronized particle specifications that specialist producers can command margin premiums for.
Industry Challenges
- Pharmaceutical-Grade Talent Scarcity:Quality assurance personnel with simultaneous GMP and food-grade HACCP certification command compensation premiums that erode processor operating margins.
- Dual-Use Facility Validation:Converting technical-grade magnesia plants to food-grade compliance requires six-to-eighteen month sanitation and documentation timelines that delay revenue recognition.
- Legacy Distributor Inventory Confusion:Technical-grade and food-grade magnesium carbonate share identical CAS registry numbers, creating mis-shipment liability in multi-segment chemical distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Magnesium Carbonate Market |
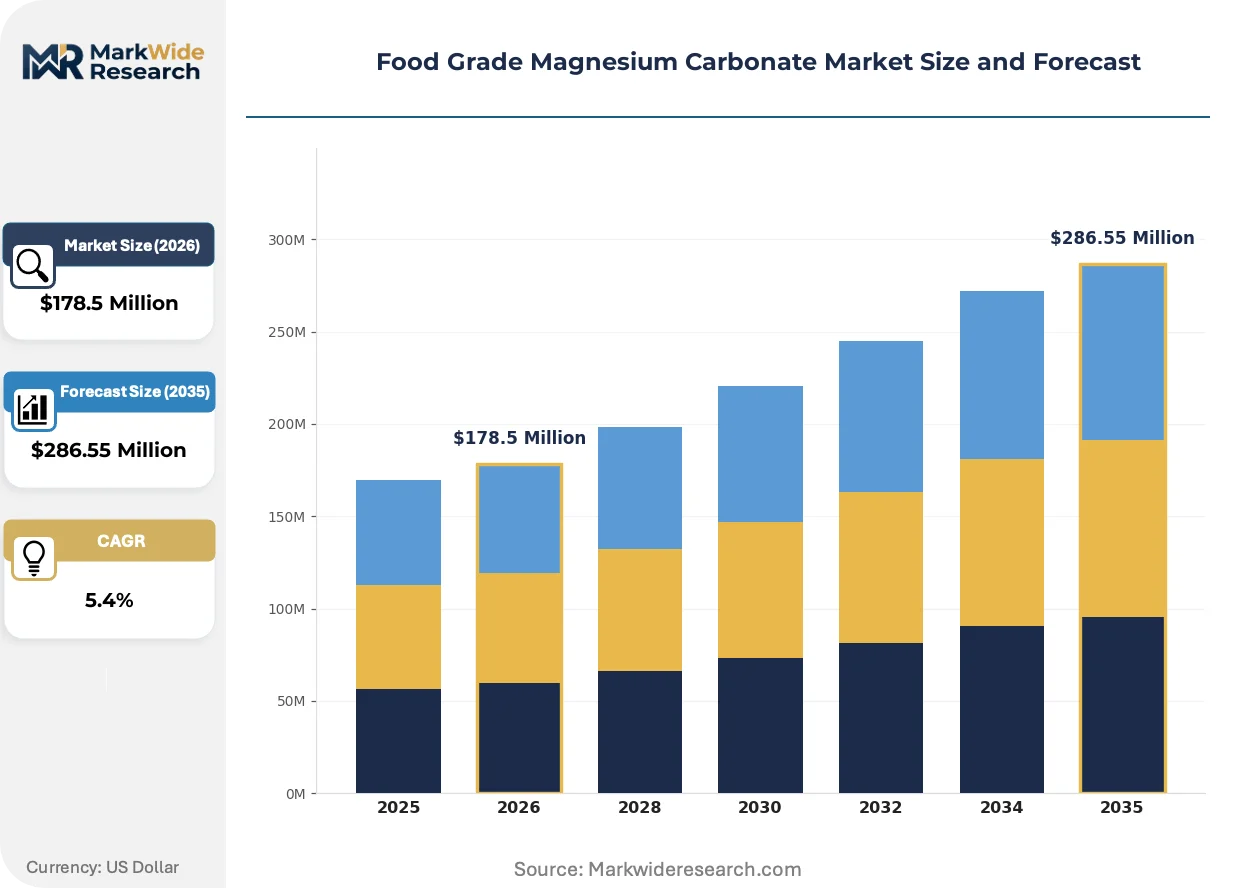
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $286.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Capsules Application: Baking Ingredient, Nutritional Supplement, Anticaking Agent, Food Fortification End User: Food Manufacturers, Nutraceutical Companies, Dietary Product Retailers, Pharmaceutical Companies Distribution Channel: Online Retail, Wholesale Supply, Supermarkets, Specialty Stores |
| Companies Covered | Naikai Salt Industries, Konoshima Chemical, SCORA S.A.S, Yingkou Magnesite Chemical, Hebei Meishen Technology, U.S. Magnesium LLC, Martin Marietta Materials, Reade International, Meishen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Magnesium Carbonate Market Emerging Trajectories
Continuous flow synthesis and micronization technologies are compressing batch-to-batch variability while regulatory divergence between FDA 21 CFR and EFSA specifications is forcing dual-track compliance investments.
Continuous precipitation reactor systems with real-time particle size monitoring are decentralizing quality control from centralized laboratories to production-line sensors. Nutraceutical contract manufacturers in Germany and the United States are adopting these systems to reduce release-testing bottlenecks. The technology is decentralizing batch release authority toward floor-level operators, compressing certificate-of-analysis turnaround times from days to hours.
China's GB 25587-2010 revision and accompanying SAMR enforcement protocols are mandating heavy metal testing at parts-per-billion thresholds previously reserved for pharmaceutical excipients. Domestic processors in Hebei and Liaoning provinces are retrofitting hydrometallurgical purification circuits to achieve compliance. The standard is accelerating consolidation among magnesite calciners lacking capital for effluent treatment upgrades.
Long-term offtake agreements with fixed volume-price mechanisms are displacing spot-market purchasing in North American and European nutraceutical supply chains. Large-scale tablet manufacturers are locking eighteen-to-twenty-four month supply contracts to secure qualification-audited supply sources. The shift is most visible in Germany and Switzerland, where magnesium carbonate functions as both active ingredient and excipient in combined mineral formulations.
Food Grade Magnesium Carbonate Market Segmentation
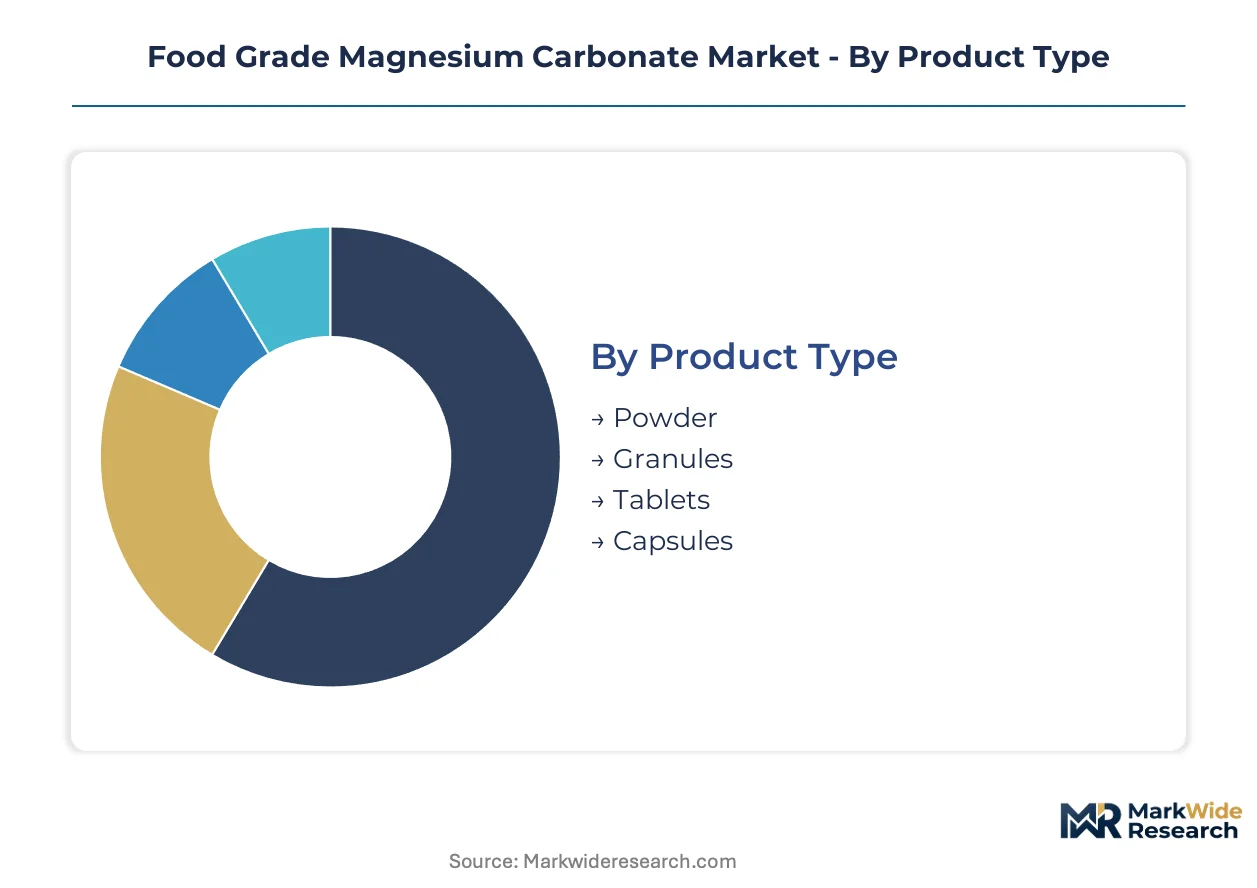
Segmentation in food grade magnesium carbonate reveals how purity specifications and delivery formats split procurement patterns across industrial baking, pharmaceutical-adjacent nutraceuticals, and direct-to-consumer wellness channels. Each dimension exposes different margin structures and compliance burdens.
Product Type:
Customization intensity runs from bulk commodity powders to precision-manufactured solid-dose formats requiring excipient-grade certification.
- Powder:Fine-milled particles below 45 microns dominate industrial-scale dry blending and flour conditioning operations. Food manufacturers in Germany and the United States consume the largest volumes for anticaking applications in baking mixes, though margin compression from technical-grade competition limits premium positioning.
- Tablets:Direct-compression grades with specified bulk density and flowability parameters command qualification-audited supply chains. Nutraceutical contract manufacturers in Switzerland and the United States are pulling these specifications toward pharmaceutical-grade boundaries, tightening release-testing protocols.
- Granules:Intermediate particle sizes serve seasoning and snack applications where dispersion rate matters more than powder flow. Specialty seasoning blenders in France specify these for clean-label anticaking claims.
- Capsules:Micronized grades with tight particle size distribution fill hard-shell gelatin and vegetable-derived capsules. Direct-to-consumer supplement brands in California and New York specify these for single-serve sachet formats.
Leading the category by volume: Powder. Growing fastest: Tablets.
Application:
End-use differentiation tracks the migration from commodity food processing toward bioavailability-claim functional positioning.
- Nutritional Supplement:Magnesium carbonate serves as both active mineral source and excipient in multimineral formulations, with EFSA-approved health claims driving European demand concentration. Tablet and capsule manufacturers in Germany and Italy prioritize heavy-metal-tested grades for premium positioning.
- Anticaking Agent:Functional performance in dry mixes and shredded cheese applications depends on surface area and moisture absorption capacity. Industrial bakers in the United States specify these for flour conditioning, though silica displacement is accelerating in clean-label segments.
- Baking Ingredient:Leavening acid neutralization and dough conditioning represent legacy demand concentrated in commercial bakery operations. Large-scale producers in the United Kingdom and Canada specify technical-grade material with food-grade certification overlays.
- Food Fortification:Mandatory rice and wheat fortification programs in India and voluntary beverage fortification in the European Union create specification divergence. FSSAI-mandated fortification in India requires BIS-certified suppliers with documented supply chain traceability.
Highest volume concentration: Anticaking Agent. Steepest expansion trajectory: Nutritional Supplement.
End User:
Procurement sophistication tiers from commodity chemical purchasing to integrated quality systems requiring audit rights and batch documentation.
- Nutraceutical Companies:Combined GMP-food HACCP facilities demand certificate-of-analysis packages with heavy-metal testing at parts-per-billion thresholds. Contract manufacturers in Germany and the United States are locking eighteen-to-twenty-four month offtake agreements to secure qualified supply.
- Food Manufacturers:Industrial-scale baking and dry-mix operations prioritize cost-efficient powder grades with basic FDA or EFSA compliance documentation. Large millers in the United States and the United Kingdom specify technical-grade material with food-grade certification overlays.
- Pharmaceutical Companies:Excipient-grade requirements under USP-NF or Ph.Eur. monographs impose additional microbial and endotoxin testing. Facilities in Switzerland and Ireland source these for mineral supplement lines positioned adjacent to prescription portfolios.
- Dietary Product Retailers:Private-label supplement brands without manufacturing capabilities rely on contract manufacturers to specify and procure. Direct-to-consumer brands in California and New York are bypassing traditional distribution to source micronized grades for powder sachets.
Most procurement volume: Food Manufacturers. Fastest qualification tightening: Nutraceutical Companies.
Distribution Channel:
Channel structure reflects the split between industrial-scale procurement and fragmented wellness-consumer access.
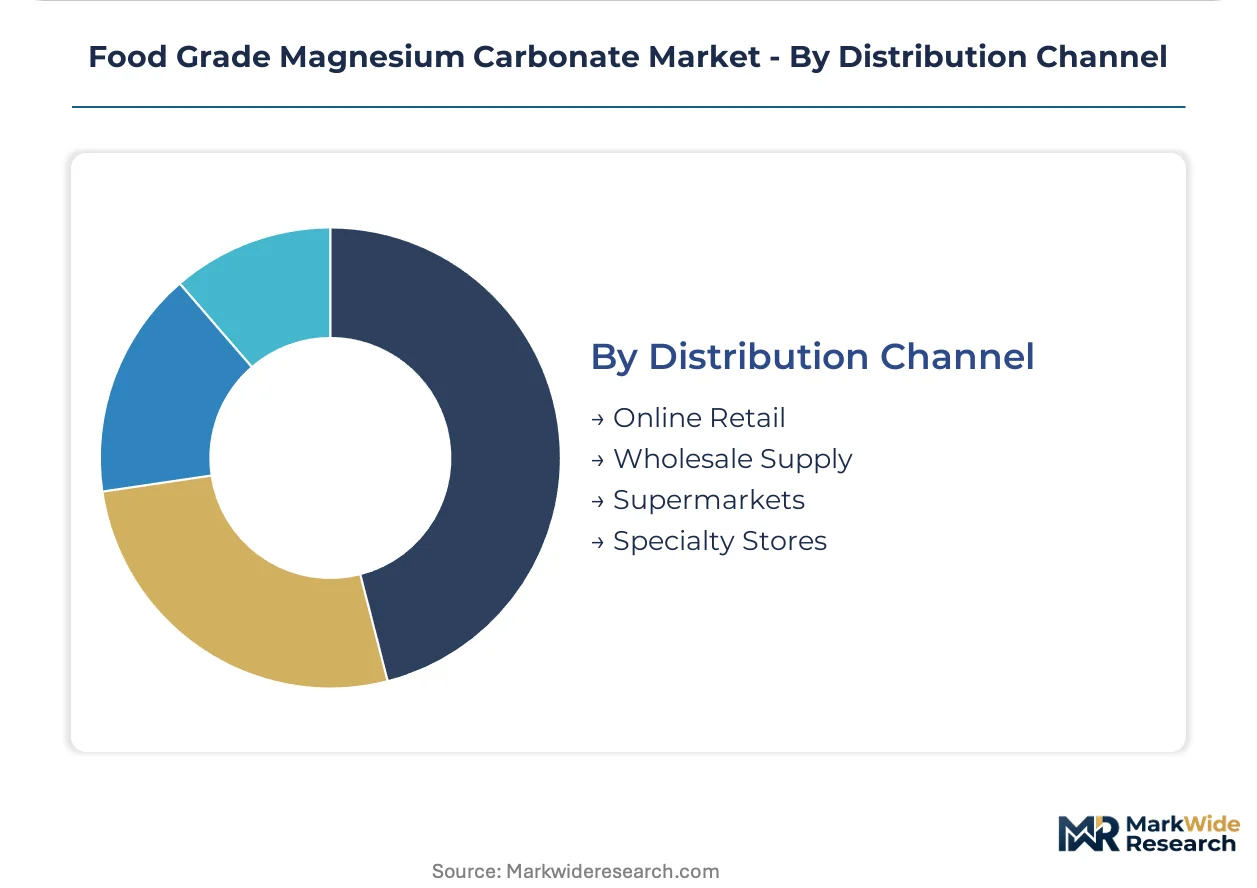
- Wholesale Supply:Bulk tote and drum shipments through chemical distributors serve food manufacturers and contract manufacturers with established supplier qualification programs. Distributors in the United States and Germany manage inventory segregation to prevent technical-grade mis-shipment.
- Online Retail:Direct-to-consumer powder sachets and small-format supplements bypass traditional pharmacy and grocery distribution. Amazon and specialized wellness platforms in the United States and the United Kingdom are capturing share from brick-and-mortar channels.
- Specialty Stores:Premium supplement retailers and compounding pharmacies stock pharmaceutical-grade material for discerning consumers. Independent pharmacies in Germany and Switzerland maintain these SKUs for mineral therapy protocols.
- Supermarkets:Mass-market supplement aisles and fortified food sections carry finished products containing magnesium carbonate as ingredient rather than standalone material. Retailers in the United Kingdom and Australia emphasize clean-label positioning in premium private-label lines.
Dominant volume channel: Wholesale Supply. Channel gaining share most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liaoning Province's magnesite processing clusters concentrate upstream supply, while nutraceutical demand pulls downstream value toward coastal manufacturing zones with GMP-food dual certification capabilities.
United States
Nutraceutical contract manufacturers in New Jersey and California drive specification tightening for direct-compression tablet grades. FDA's 21 CFR 184.1425 maintains heavy metal thresholds that favor qualified suppliers with ICP-MS testing infrastructure. The New Jersey corridor hosts tablet press automation clusters demanding flow-optimized powder specifications.
China
Hebei and Liaoning provinces dominate magnesite calcination capacity serving domestic and export markets. SAMR enforcement of revised GB 25587-2010 standards is forcing parts-per-billion heavy metal compliance that eliminates smaller calciners. Yingkou's magnesite chemical cluster is retrofitting hydrometallurgical purification to meet pharmaceutical-adjacent purity benchmarks.
Germany
EFSA-approved health claims for magnesium fortification drive premium supplement formulation demand. The country's national pharmaceutical regulator enforces excipient-grade standards that migrate into food-grade specifications. Bavarian and Rhineland contract manufacturing facilities lock long-term offtake agreements to secure qualified supply chains.
India
FSSAI mandatory rice and wheat fortification regulations are creating first-mover advantage for BIS-certified carbonate suppliers. Maharashtra and Gujarat processing hubs are upgrading to meet documented supply chain traceability requirements. Domestic magnesite processors in Rajasthan are seeking export qualification through GB standard harmonization.
Switzerland
Swissmedic-adjacent quality systems position the country for pharmaceutical-grade mineral supplement production. Zurich and Basel corridors host combined GMP-food HACCP facilities serving premium European markets. Contract manufacturers here specify eighteen-to-twenty-four month supply contracts to secure audit-qualified sources.
Food Grade Magnesium Carbonate Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with powder-grade commodity supply consolidating around integrated mining-refining operations while tablet-grade qualification creates stickier supplier relationships. The vendor base organizes into three archetypes: integrated magnesite miners with captive refining, specialized high-purity chemical processors, and regional distributors managing inventory segregation. Dominant competitive moves include backward integration into magnesite mining and technology licensing for continuous precipitation reactor systems.
Among Asia-Pacific integrated producers, Hebei Meishen Technology and Yingkou Magnesite Chemical occupy positions tied to Liaoning Province feedstock clusters. Konoshima Chemical represents the specialized high-purity processor archetype serving pharmaceutical-adjacent specifications. These three exemplify how geographic concentration of raw material processing shapes competitive positioning across purity tiers.
| Leading Market Players |
|---|
| Naikai Salt Industries |
| Konoshima Chemical |
| SCORA S.A.S |
| Yingkou Magnesite Chemical |
| Hebei Meishen Technology |
| U.S. Magnesium LLC |
| Martin Marietta Materials |
| Reade International |
| Meishen |
| Others |
Supply Flow & Price Mechanics
Magnesite ore processing costs in Liaoning Province cascade through three distinct pricing tiers downstream, with heavy metal compliance investments at calcination facilities separating pharmaceutical-adjacent premiums from technical-grade commodity basements. Buyers in Germany and Switzerland absorb qualification-audited premiums for direct-compression tablet grades, while industrial bakers in the United States and United Kingdom purchase technical-grade material with food-grade certification overlays at compressed margins.
Pricing Analysis
Short lead-time premiums for qualified tablet-grade material run 15-25 percent above contract baselines, while spot inventory of unqualified powder trades at discounts to long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EFSA-approved heavy metal testing commanding the top tier and basic FDA compliance anchoring the bottom. Pricing pressure stems from organic magnesium salt substitution in premium supplements, compressing carbonate's addressable high-margin segment. Nutraceutical contract manufacturers exhibit lowest price sensitivity due to qualification lock-in, while industrial food manufacturers drive aggressive cost negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Swiss tablet manufacturers, while chemical distributors manage inventory segregation for mid-tier food processors in the United States and United Kingdom. Raw material supply concentrates in China, with secondary calcination capacity in India and specialized high-purity processing in Japan. The chain draws from magnesite ore, energy-intensive calcination inputs, and inductively coupled plasma mass spectrometry testing equipment. Single-source vulnerability in Liaoning Province feedstock creates concentrated geological and regulatory enforcement risk. Distribution runs through qualified bulk tote shipments for GMP-certified facilities and unqualified drum lots for technical-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive magnesite mining and downstream qualification-audited tablet-grade production represents the dominant competitive race, with players pursuing upstream ore security and downstream certification stickiness as dual levers for margin defense.
For Market Incumbents: Hedge against organic magnesium salt substitution by locking eighteen-to-twenty-four month offtake agreements with nutraceutical contract manufacturers before glycinate and malate formats capture additional premium share. Prioritize GB standard harmonization investments at Chinese facilities to unlock export qualification for domestic magnesite processors, securing first-mover positioning as SAMR enforcement eliminates smaller calciners lacking capital for hydrometallurgical purification upgrades. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-adjacent tablet grades and technical-grade powder creates entry space for mid-purity producers achieving BIS certification for India's FSSAI-mandated rice and wheat fortification programs. Target Maharashtra and Gujarat processing hubs upgrading to meet documented supply chain traceability requirements. Bypass established distributor networks by supplying direct-to-consumer powder sachet brands in California and New York with micronized particle specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated magnesite miners with captive refining operations in Hebei and Liaoning provinces as SAMR enforcement accelerates consolidation among calciners lacking effluent treatment capital. Long-term viability over the projection horizon rests on qualification-audited supply relationships with GMP-food dual certification facilities in Germany and Switzerland. Watch for inflection in FSSAI enforcement intensity across Indian states as the signal for fortification-driven volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Magnesite Mining | Secures ore supply for processors in Liaoning Province facing SAMR consolidation pressure. |
| Continuous Precipitation Reactor Technology Licensing | Enables real-time particle size monitoring for German contract manufacturers reducing release-testing bottlenecks. |
| BIS Certification for Indian Fortification Supply | Unlocks first-mover positioning in Maharashtra and Gujarat as FSSAI mandates expand. |
| Long-term Offtake Agreements with Swiss Tablet Manufacturers | Locks qualification-audited revenue streams for eighteen-to-twenty-four month supply security. |
| Dual GMP-Food HACCP Facility Validation | Captures pharmaceutical-adjacent premium tiers as EFSA tightens magnesium additive specifications. |
Methodological Framework
Document review covered FDA 21 CFR filings, EFSA scientific opinions, SAMR GB standard revisions, and FSSAI fortification notifications, complemented by interviews with plant managers at magnesite calcination facilities, procurement leads at nutraceutical contract manufacturers, distribution channel partners managing inventory segregation, and technical R&D directors developing continuous flow synthesis systems. Secondary validation drew from customs and trade data, SEC 10-K disclosures from listed chemical processors, and industry association reports from Cefic and the American Chemistry Council. Bottom-up volume estimates from individual facility capacities and top-down demand triangulation from end-use consumption patterns were reconciled.
Segment-level value outputs across the analysis window were generated through granular modeling of powder, tablet, granule, and capsule product types; nutritional supplement, anticaking agent, baking ingredient, and food fortification applications; and nutraceutical company, food manufacturer, pharmaceutical company, and dietary product retailer end users. CAGRs were derived from regression analysis of historical consumption patterns and projected specification tightening trajectories. Forecast inputs incorporated EFSA re-evaluation timelines, SAMR enforcement intensity scenarios, and tablet manufacturing automation adoption curves.
Inputs from SAMR enforcement protocols and FSSAI fortification implementation schedules were available through the study window; gaps in real-time inventory data from multi-segment chemical distributors introduce uncertainty bands around spot-market pricing assumptions. Forecasts reflect documented qualification timelines and regulatory divergence scenarios. Periodic stress-testing of base assumptions against EFSA maximum permitted level revisions and organic magnesium salt substitution rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market