
 South America Food Hydrocolloids Market | 2026-2036
South America Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Hydrocolloids Market Analytics
Multi-source procurement for hydrocolloid feedstocks is hardening across South American food manufacturers. Cargill Incorporated leverages its regional grain-processing infrastructure to secure consistent guar and cellulose-derived supply chains. CP Kelco anchors its position through specialized fermentation capacity for xanthan gum production in the Mercosur zone. DuPont de Nemours competes on pectin and gellan gum formulations tailored to tropical fruit-processing applications.
Food hydrocolloids are high-molecular-weight hydrophilic biopolymers—typically polysaccharides or proteins—that hydrate in aqueous systems to modify viscosity, gelation, emulsion stability, or water-binding capacity; xanthan gum, for instance, achieves stable pseudoplastic flow at concentrations below one percent, making it indispensable in low-pH beverage systems. The South American market segments by product type into gelatin, pectin, agar, and xanthan gum, with xanthan and pectin capturing expanding share as beverage and fruit-spread processors reformulate for cleaner labels. Application segmentation spans dairy products, bakery, sauces, and beverages, where dairy and beverages concentrate margin pools due to higher throughput volumes and stricter texture specifications demanded by Brazilian and Argentine processors.
ANVISA governs food additive approvals and maximum usage levels for hydrocolloids across Brazil, while Argentina's national food code enforces parallel safety thresholds that shape cross-border formulation strategies. The EU-Mercosur trade agreement's technical annexes on food standards are creating alignment pressure on regional manufacturers adopting CE-marking-equivalent quality systems. Stakeholders must monitor how evolving South American regulatory convergence affects import substitution incentives for locally produced seaweed and plant-based hydrocolloids.
Market Dynamics
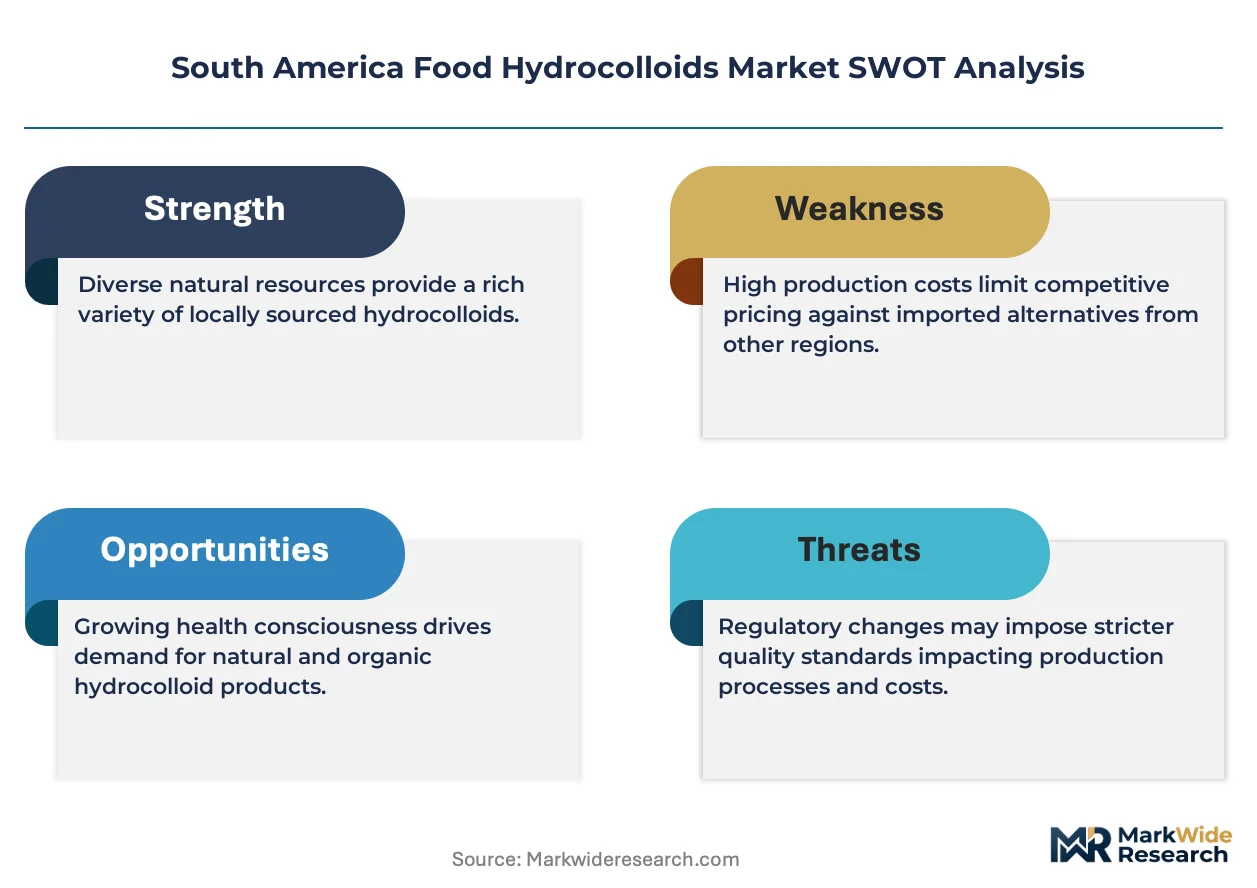
Clean-label reformulation across South American dairy and beverage processors is compressing hydrocolloid specification cycles, forcing suppliers to synchronize innovation pipelines with ANVISA's tightening additive purity schedules while managing raw material volatility from Andean guar and Chilean seaweed harvests.
Growth Catalysts
- ANVISA additive modernization:Brazil's evolving food additive standards are mandating higher purity thresholds for imported stabilizers, creating procurement pull toward certified regional suppliers capable of documentation-intensive compliance.
- Fermentation capacity expansion:Specialized bioreactor infrastructure for microbial polysaccharide production is scaling across the Mercosur zone, reducing lead times for xanthan gum dependent on low-pH beverage systems.
- Southeastern manufacturing corridor concentration:São Paulo-based dairy and sauce processors are consolidating procurement volumes, generating economies of scale that justify dedicated hydrocolloid formulation laboratories.
Market Restraints
- Seaweed supply geography:Carrageenan and agar feedstock dependence on Chilean and Peruvian coastal harvesting creates seasonal availability constraints amplified by El Niño oscillation patterns.
- Import substitution cost premiums:ANVISA's local production incentives impose compliance cost structures that disadvantage small-scale Brazilian gum processors against Argentine cellulose derivative networks.
- Protein hydrocolloid functionality gaps:Gelatin alternatives from plant sources exhibit inferior melt profiles in tropical climate distribution, limiting clean-label substitution in Argentine confectionery applications.
Strategic Opportunities
- Colombian Andean guar cultivation:Underdeveloped acreage in Colombia's eastern plains offers backward integration potential for processors seeking supply chain de-risking outside traditional Indian import channels.
- EU-Mercosur alignment protocols:Technical annexes on food additive equivalence are creating CE-marking pathway opportunities for Brazilian exporters targeting European dairy ingredient markets.
- Precision fermentation platforms:Convergence of synthetic biology with existing regional ethanol infrastructure enables novel hydrocolloid molecular architectures for reduced-inclusion clean-label formulations.
Industry Challenges
- Food technologist specialization scarcity:Formulation expertise spanning hydrocolloid synergies, protein interactions, and tropical shelf-stability testing remains concentrated in São Paulo and Buenos Aires metropolitan labor pools.
- Multi-jurisdiction certification timelines:Parallel ANVISA and Argentine national food code approval processes for novel hydrocolloid blends extend commercialization cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Hydrocolloids Market |
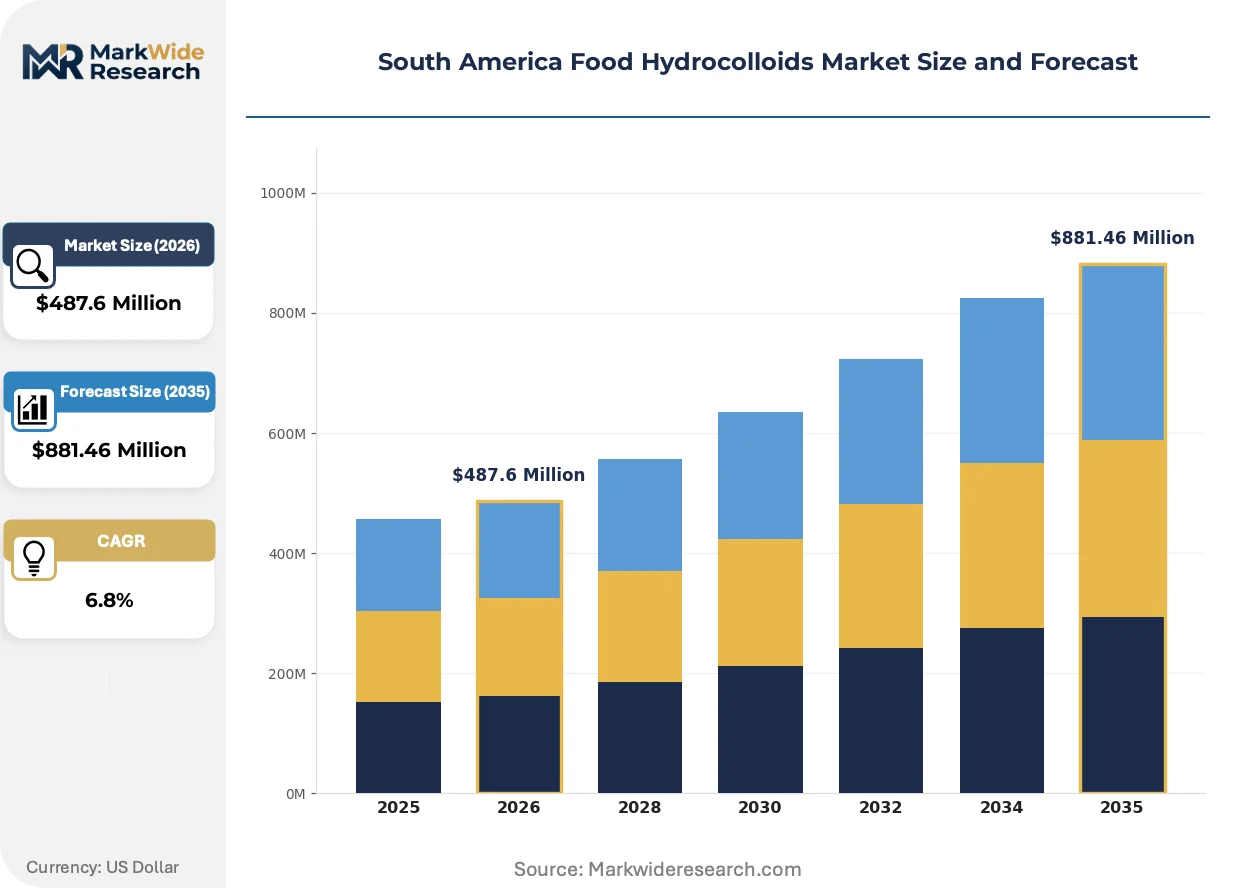
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Xanthan Gum Application: Dairy Products, Bakery, Sauces, Beverages Source: Plant-based, Animal-based, Synthetic, Seaweed Form: Powder, Liquid, Granular, Gel |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, CP Kelco, DuPont de Nemours, Kerry Group plc, Tate & Lyle PLC, Archer Daniels Midland Company, Ashland Inc., Koninklijke DSM, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Hydrocolloids Market Evolving Landscape
Bioprocess engineering advances and regulatory convergence protocols are restructuring how South American hydrocolloid suppliers compete on specification speed and tropical climate performance guarantees.
Cellulose nanofibril technology is expanding into low-fat dairy applications where fat-mimetic mouthfeel reconstruction demands sub-micron particle distribution. Argentine yogurt processors are piloting these systems at commercial scale. The technology is expanding into premium private-label contracts previously dominated by modified starch blends.
ANVISA's 2023 additive reclassification framework is compressing maximum usage levels for synthetic hydrocolloids in pediatric food categories. Industrial consequence includes accelerated reformulation timelines for Brazilian infant nutrition manufacturers. Fruit-based puree processors in Minas Gerais are responding by accelerating pectin-native fruit sourcing partnerships.
Buyer concentration among São Paulo-based dairy cooperatives is compressing supplier negotiation cycles from annual to quarterly frameworks. Direct procurement agreements with fermentation facilities are displacing traditional distributor intermediaries. This pattern is most visible in UHT milk stabilizer contracts where volume thresholds now trigger dedicated technical service attachments.
South America Food Hydrocolloids Market Segmentation
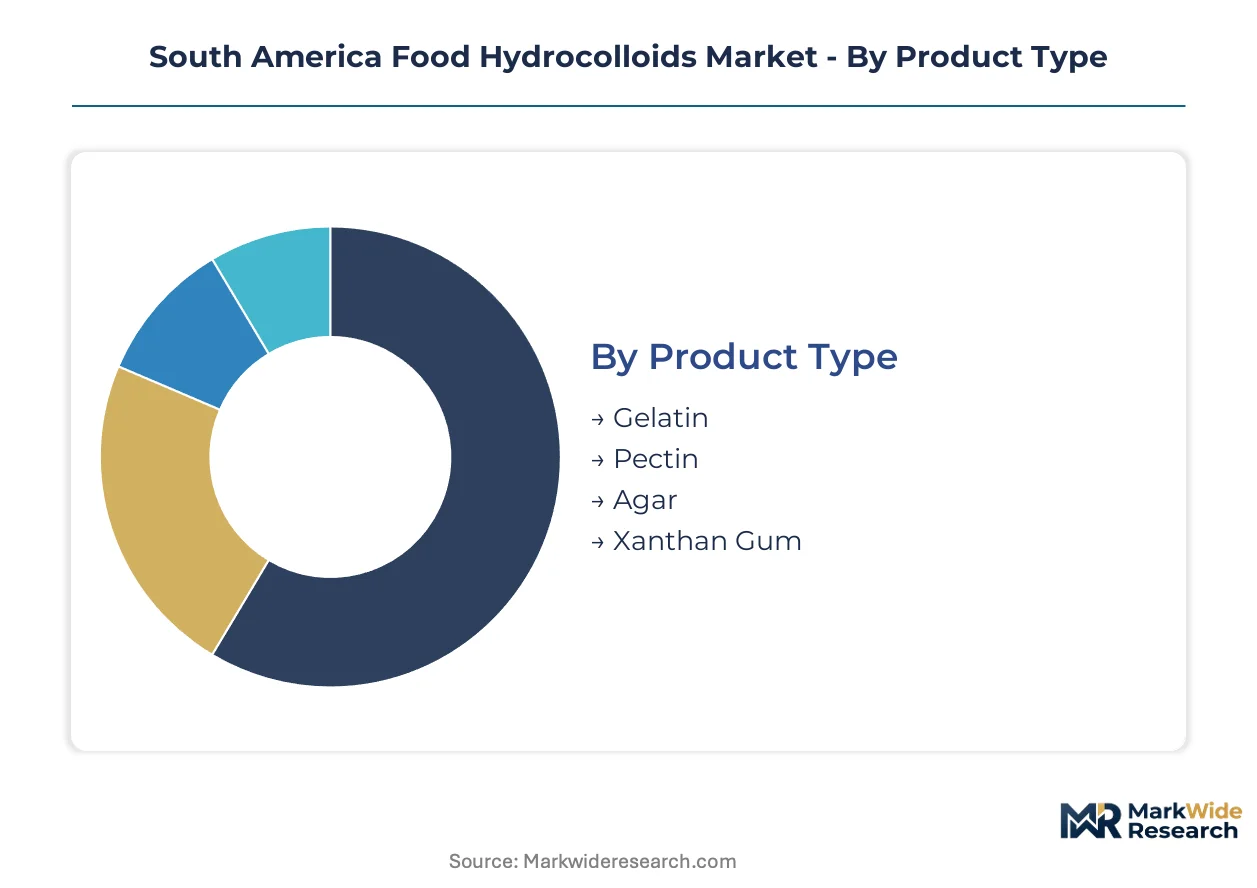
Hydrocolloid specification cycles in South America diverge sharply by functional performance requirements and regulatory compliance burden. Procurement patterns across Brazilian and Argentine processors reveal how clean-label mandates and ANVISA purity standards reshape segment prioritization.
Product Type:
Xanthan gum and pectin command premium positioning through fermentation-derived consistency and native fruit compatibility, while gelatin and agar occupy volume tiers constrained by climate stability and harvest volatility.
- Xanthan Gum:Microbial polysaccharide produced via Xanthomonas campestris fermentation achieves stable pseudoplastic viscosity at sub-one-percent concentrations. São Paulo-based low-pH beverage processors specify this grade for shelf-stability in tropical distribution.
- Pectin:Extracted from citrus peel and apple pomace, high-methoxyl variants gel under acid-sugar conditions without calcium dependency. Minas Gerais fruit-spread manufacturers are accelerating native pectin sourcing partnerships to satisfy ANVISA's tightening additive schedules.
- Gelatin:Collagen-derived protein hydrocolloid from bovine and porcine sources exhibits thermoreversible gelation with melt profiles suited to confectionery.
- Agar:Seaweed-extracted polysaccharide from Chilean and Peruvian Gracilaria species forms brittle gels with high melting points; El Niño oscillations constrain regional supply reliability.
Today's leader: Xanthan gum. Tomorrow's challenger: Pectin.
Application:
Dairy and beverage applications concentrate margin pools through higher throughput volumes and stricter texture specifications, while bakery and sauces segments compete on cost efficiency and process tolerance.
- Dairy Products:Yogurt, ice cream, and UHT milk systems demand hydrocolloid synergies for fat stabilization and syneresis prevention. Argentine processors pilot cellulose nanofibril systems for low-fat mouthfeel reconstruction at commercial scale.
- Beverages:Low-pH fruit juices and dairy-alternative drinks require suspension stability and pulp uniformity. Brazilian southeastern manufacturing corridors anchor procurement volumes for xanthan-dependent stabilization systems.
- Bakery:Bread improvers and cake batters utilize hydrocolloids for moisture retention and crumb structure; modified starch blends face displacement from clean-label cellulose derivatives.
- Sauces:Emulsion stability in mayonnaise and salad dressings drives medium-viscosity gum specifications; heat-processed variants demand thermal tolerance beyond native starch performance.
Dairy and beverages capture the steepest expansion trajectory as Brazilian cooperatives consolidate procurement into quarterly negotiation frameworks with dedicated technical service attachments.
Source:
Plant-based and seaweed sources align with clean-label positioning but face supply geography constraints, while animal-based and synthetic categories confront regulatory compression and consumer perception headwinds.
- Plant-based:Guar gum from Colombian eastern plains and cellulose derivatives from Argentine wood pulp networks offer backward integration potential outside Indian import channels. ANVISA local production incentives disadvantage small-scale Brazilian processors against these established networks.
- Seaweed:Carrageenan and agar from Chilean coastal harvesting operations suffer seasonal availability constraints amplified by climate oscillation patterns.
- Animal-based:Gelatin from bovine and porcine collagen sources faces functionality gaps in tropical climate distribution, limiting substitution in Argentine confectionery.
- Synthetic:Cellulose derivatives and chemically modified starches encounter maximum usage level compression under ANVISA's pediatric food reclassification framework.
Plant-based sources dominate current procurement volumes. Seaweed sources face the most severe supply concentration risk.
Form:
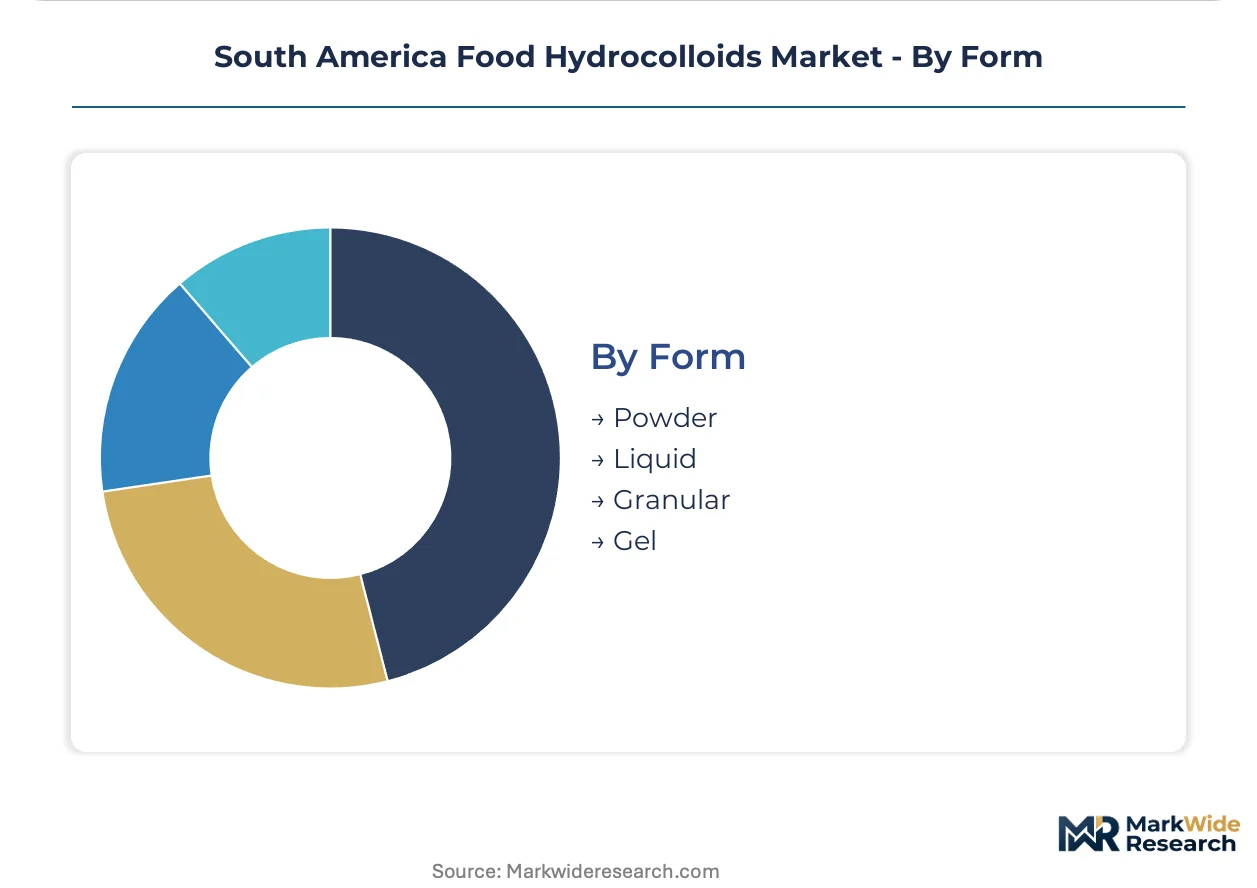
Powder and liquid formats split the market by handling economics and dissolution speed, with granular and gel forms serving niche processing requirements.
- Powder:Spray-dried and roller-dried particulates offer extended shelf stability and bulk handling efficiency; dry-blend compatibility favors dairy premix applications.
- Liquid:Pre-hydrated dispersions eliminate dust exposure and accelerate production line integration; higher freight costs limit distribution radius from Mercosur fermentation facilities.
- Granular:Coarse-particle grades reduce clumping in high-shear mixing environments; specialized for sauce manufacturing with direct-dump processing.
- Gel:Pre-formed hydrocolloid matrices serve research and development calibration and small-batch artisanal production.
Powder forms retain manufacturing preference. Liquid forms are gaining share fastest as São Paulo processors eliminate dry-blend steps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's southeastern manufacturing corridor anchors continental hydrocolloid procurement, concentrating dairy and beverage formulation demand across the Mercosur zone. Brazilian processors drive specification cycles while Argentine cellulose networks and Chilean seaweed harvests shape supply-side geography.
Brazil
ANVISA's additive modernization mandates compress maximum usage levels for synthetic stabilizers in pediatric categories. São Paulo-based dairy cooperatives consolidate procurement into quarterly frameworks with dedicated technical service attachments. Minas Gerais fruit-spread manufacturers accelerate native pectin sourcing partnerships to satisfy tightening purity schedules.
Argentina
The national food code enforces parallel safety thresholds that shape cross-border formulation strategies with Brazilian exporters. Buenos Aires metropolitan labor pools concentrate scarce food technologist expertise spanning hydrocolloid synergies and tropical shelf-stability testing. Argentine yogurt processors pilot cellulose nanofibril systems for low-fat mouthfeel reconstruction at commercial scale.
Chile
Coastal harvesting operations for Gracilaria species supply carrageenan and agar feedstocks, though El Niño oscillations constrain seasonal availability. The country's seaweed processing infrastructure faces climate-driven supply volatility that amplifies procurement risk for regional stabilizer buyers. Technical annexes from the EU-Mercosur trade agreement create alignment pressure on quality system adoption.
Colombia
Underdeveloped guar acreage in the eastern plains offers backward integration potential for processors seeking supply chain de-risking outside traditional Indian import channels. The national agricultural development framework incentivizes non-traditional crop expansion in Orinoquia region cultivation zones. Bogotá-based food ingredient distributors are evaluating direct procurement partnerships with emerging gum processors.
South America Food Hydrocolloids Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived specialty grades and clean-label formulation services. The market structures around three tiers: multinational ingredient conglomerates with regional grain-processing infrastructure, specialized biopolymer fermenters with Mercosur zone capacity, and regional distributors consolidating into direct procurement arrangements. Dominant competitive moves include backward integration into Andean guar cultivation and precision fermentation platform development leveraging existing ethanol infrastructure.
Within the multinational conglomerate tier, Cargill Incorporated and DuPont de Nemours exemplify divergent strategic positioning. Cargill leverages its regional grain-processing footprint to secure consistent guar and cellulose-derived supply chains across Brazilian and Argentine manufacturing corridors. DuPont occupies a position emphasizing pectin and gellan gum formulations tailored to tropical fruit-processing applications. CP Kelco anchors the specialized fermentation segment through microbial polysaccharide production capacity serving low-pH beverage systems.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| CP Kelco |
| DuPont de Nemours |
| Kerry Group plc |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ashland Inc. |
| Koninklijke DSM |
| Others |
Value Network & Pricing Analysis
Fermentation-grade xanthan gum and commodity seaweed extracts occupy divergent value tiers, with ANVISA-certified purity grades commanding substantial premiums over standard import classifications while procurement teams reconfigure supplier portfolios around these certification ladders. This bifurcation concentrates pricing power among Mercosur-based fermentation facilities capable of documentation-intensive compliance, simultaneously compressing margins for distributors dependent on Chilean coastal harvesting cycles.
Pricing Analysis
Input-cost pass-through from Andean guar harvest volatility and Chilean seaweed supply interruptions shapes contract structures across Brazilian processors. Three-tier pricing structure across premium fermentation-derived, standard plant-extracted, and economy-grade modified starch tiers reflects ANVISA certification status and tropical climate performance guarantees. Cost compression in commodity seaweed extracts is intensifying because El Niño-driven harvest shortfalls restrict availability. Small-scale Brazilian gum processors exhibit highest price sensitivity due to import substitution cost premiums, while São Paulo-based dairy cooperatives prioritize specification stability over unit economics.
Supply Chain Analysis
Freight cost differentials between pre-hydrated liquid dispersions and powder formats constrain distribution radius from Mercosur fermentation facilities, favoring regional procurement concentration. Supply concentrates in Brazil's southeastern manufacturing corridor, Argentina's cellulose derivative networks, and Chile's coastal seaweed processing infrastructure. Raw material dependencies rest on Colombian eastern plains guar cultivation, Chilean Gracilaria species harvesting, and Argentine wood pulp feedstocks. Single-source vulnerability around Chilean carrageenan supply amplifies procurement risk during climate oscillation events. Distribution runs through direct procurement agreements with fermentation facilities displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Brazilian dairy cooperatives and beverage processors are prioritizing ANVISA-certified fermentation grades over commodity alternatives, compressing specification cycles and rewarding suppliers capable of documentation-intensive compliance.
For Market Incumbents: To counter emerging Colombian guar processors and precision fermentation platforms, Cargill Incorporated and CP Kelco should deepen backward integration into Andean cultivation zones while expanding dedicated technical service attachments for São Paulo-based dairy cooperatives. Capacity addition in Colombian eastern plains offers supply chain de-risking outside traditional Indian import channels. Certification investment in ANVISA-equivalent quality systems creates EU-Mercosur alignment pathway opportunities. For New Entrants and Emerging Players: Enter via Colombian guar cultivation partnerships targeting Brazilian processors seeking supply chain de-risking, or precision fermentation platforms leveraging existing regional ethanol infrastructure for novel hydrocolloid molecular architectures. The most penetrable segment sits in clean-label pectin formulations for Minas Gerais fruit-spread manufacturers accelerating native sourcing partnerships. A technical service-led go-to-market angle outperforms commodity distribution for quarterly negotiation frameworks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized biopolymer fermenters possessing Mercosur zone capacity and established ANVISA compliance documentation. Long-term viability favors platforms capable of reduced-inclusion clean-label formulations through synthetic biology convergence. Acquisition targets should display fermentation infrastructure co-located with Brazilian southeastern manufacturing demand clusters. The signal to watch is quarterly procurement framework adoption rates among São Paulo dairy cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Andean Guar Cultivation | Colombian eastern plains acreage development reduces Indian import dependency for Brazilian processors. |
| Precision Fermentation Platform Development | Synthetic biology convergence with regional ethanol infrastructure enables novel molecular architectures. |
| ANVISA Certification Investment | CE-marking-equivalent quality systems unlock EU-Mercosur trade agreement technical annex pathways. |
| Direct Procurement Agreement Expansion | São Paulo dairy cooperatives are consolidating volumes into quarterly frameworks with technical service attachments. |
| Native Pectin Sourcing Partnerships | Minas Gerais fruit-spread manufacturers accelerate partnerships to satisfy tightening additive purity schedules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food technologists at São Paulo and Buenos Aires formulation laboratories, procurement leads at Brazilian dairy cooperatives, ANVISA regulatory affairs specialists, and Chilean seaweed processing operators with secondary validation. Secondary sources included ANVISA additive reclassification frameworks, Argentine national food code provisions, EU-Mercosur trade agreement technical annexes, and customs data on hydrocolloid import flows. Bottom-up volume aggregation across product type and application segments was cross-checked against top-down market sizing derived from processor capacity utilization and formulation inclusion rates.
Segment-weighting approaches applied differential growth assumptions across xanthan gum, pectin, gelatin, and agar categories, with additional granularity by dairy, beverage, bakery, and sauce applications. Modeled dimensions included hydrocolloid source type, form factor, and regional manufacturing corridor concentration. CAGRs were derived from trajectory analysis of historical procurement volumes and projected reformulation timelines tied to regulatory purity schedule implementations. Industry-specific forecast inputs incorporated ANVISA maximum usage level compression effects and El Niño oscillation patterns on Chilean seaweed harvest reliability.
The model holds under stable ANVISA regulatory enforcement and continued EU-Mercosur alignment progress; deviation in climate oscillation severity or trade agreement ratification delays would shift supply availability assumptions and pricing tier differentials. Forecasts reflect documented assumptions about fermentation capacity expansion rates and clean-label reformulation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
France Food Hydrocolloids Market