
 Nasal Packing Devices Market | 2026-2036
Nasal Packing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Packing Devices Market Intelligence
Hospital procurement of nasal packing devices is tilting toward bundled contracts with integrated distributors. Medtronic plc leverages its broad ENT portfolio to anchor multi-year supply agreements with major health systems. Stryker Corporation competes through specialized hemostasis product lines that sustain high switching costs among surgeons. Smith & Nephew plc differentiates via advanced biomaterial R&D that positions its absorbable segments in academic medical centers.
Nasal packing devices are sterile, compressible inserts—typically composed of oxidized cellulose, gelatin foam, or silicone-based polymers—engineered to control epistaxis and post-surgical bleeding by exerting localized pressure and promoting clot stabilization. Absorbable packing dominates current volume due to elimination of painful removal procedures, while silicone packing commands premium pricing in complex endoscopic sinus surgery where non-adherent surfaces reduce mucosal trauma. Biodegradable materials represent the fastest-expanding material category as manufacturers reformulate to meet EU Green Deal sustainability targets and FDA guidance on resorbable surgical implants.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and market access costs for nasal packing innovations. The EPA and ECHA additionally scrutinize polymer constituents for environmental persistence, pressuring shifts away from polyvinyl chloride formulations. Stakeholders must monitor evolving MDR clinical evidence requirements and state-level hospital sustainability mandates that will determine which material platforms secure long-term reimbursement.
Market Dynamics
The transition from non-absorbable to absorbable biomaterials is compressing device replacement cycles while elevating clinical outcome expectations across ENT surgical suites.
Growth Catalysts
- EU MDR clinical evidence requirements:Stringent post-market surveillance mandates for hemostatic implants are accelerating manufacturer investment in biodegradable polymer R&D pipelines.
- Ambulatory surgical centers:Outpatient sinonasal procedure volumes in the United States are expanding demand for single-use absorbable packing that eliminates follow-up removal visits.
- Oxidized cellulose reformulation:Next-generation carboxymethyl cellulose derivatives with enhanced mucosal adhesion properties are displacing gelatin-based alternatives in academic medical centers.
Market Restraints
- Raw material concentration:Pharmaceutical-grade oxidized cellulose supply concentrates among three European chemical processors, creating input cost volatility during harvest-season fluctuations.
- FDA 510(k) pathway friction:Substantial equivalence determinations for novel resorbable polymers now require extended biocompatibility testing that extends time-to-market by 8-14 months.
- Silicone packing substitution:Non-adherent silicone balloon catheters retain preference in complex skull-base reconstructions where precise pressure modulation outweighs absorbable convenience.
Strategic Opportunities
- German hospital sustainability mandates:State-level procurement directives favoring biodegradable surgical materials create preferential reimbursement positioning for EU Green Deal-compliant packing.
- Japan's aging ENT patient base:Underpenetrated demand for outpatient epistaxis management in Tokyo-Osaka corridor clinics supports ambulatory care model expansion.
- Telehealth-integrated follow-up:Remote post-operative monitoring protocols are enabling same-day discharge workflows that pair absorbable packing with digital symptom tracking.
Industry Challenges
- Biomaterial characterization expertise:Scarce analytical chemistry talent capable of resorption-rate validation against ISO 10993 standards constrains product pipeline velocity.
- Legacy sterilization infrastructure:Gamma irradiation facilities optimized for non-resorbable polymers require revalidation for temperature-sensitive biodegradable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Packing Devices Market |
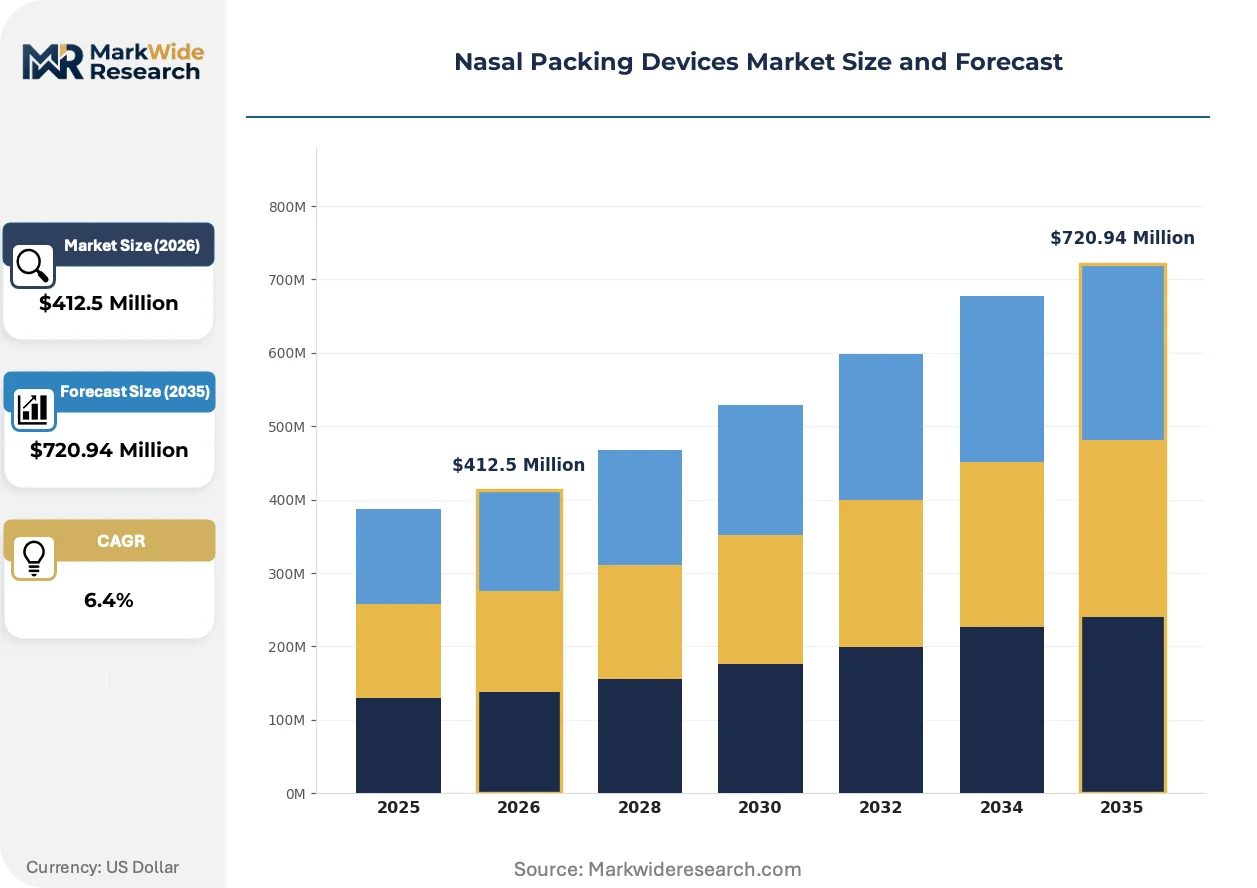
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Packing, Non-Absorbable Packing, Silicone Packing, Other Packing Material: Polyurethane, Polyvinyl Chloride, Silicone, Biodegradable Materials End User: Hospitals, Clinics, Ambulatory Surgical Centers, Emergency Care Facilities Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Medtronic plc, Stryker Corporation, Smith & Nephew plc, Summit Medical (Innovia), Teleflex Incorporated, Olympus Corporation, Lohmann & Rauscher, Network Medical Products Ltd, Meril Life Sciences Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Packing Devices Market Strategic Shifts & Innovations
Digital simulation of nasal cavity hemodynamics is compressing clinical trial design timelines while biomaterial science advances enable patient-specific resorption profiles.
Computational fluid dynamics modeling of nasal airflow and bleeding patterns is virtualizing preclinical validation workflows for next-generation hemostatic devices. ENT device manufacturers in Germany and the United States now deploy patient-specific anatomical simulations to predict packing efficacy before physical prototyping. This capability is compressing regulatory submission preparation cycles and reducing animal testing requirements.
REACH authorization processes for polymer constituents are tightening supply chain documentation obligations across European nasal packing manufacturers. ECHA scrutiny of persistent organic pollutants in polyvinyl chloride formulations is accelerating phase-out timelines for conventional non-absorbable materials. German and French distributors now require comprehensive substance-of-very-high-concern attestations that smaller component suppliers struggle to furnish.
Surgeon preference for procedure-specific device kits is fragmenting purchasing authority away from centralized hospital procurement. Academic medical centers in Japan and the United States now negotiate directly with manufacturers for specialty sinus surgery configurations that bundle absorbable packing with endoscopic instruments. This behavior concentrates volume among integrated ENT portfolios while squeezing standalone packing specialists.
Nasal Packing Devices Market Segmentation
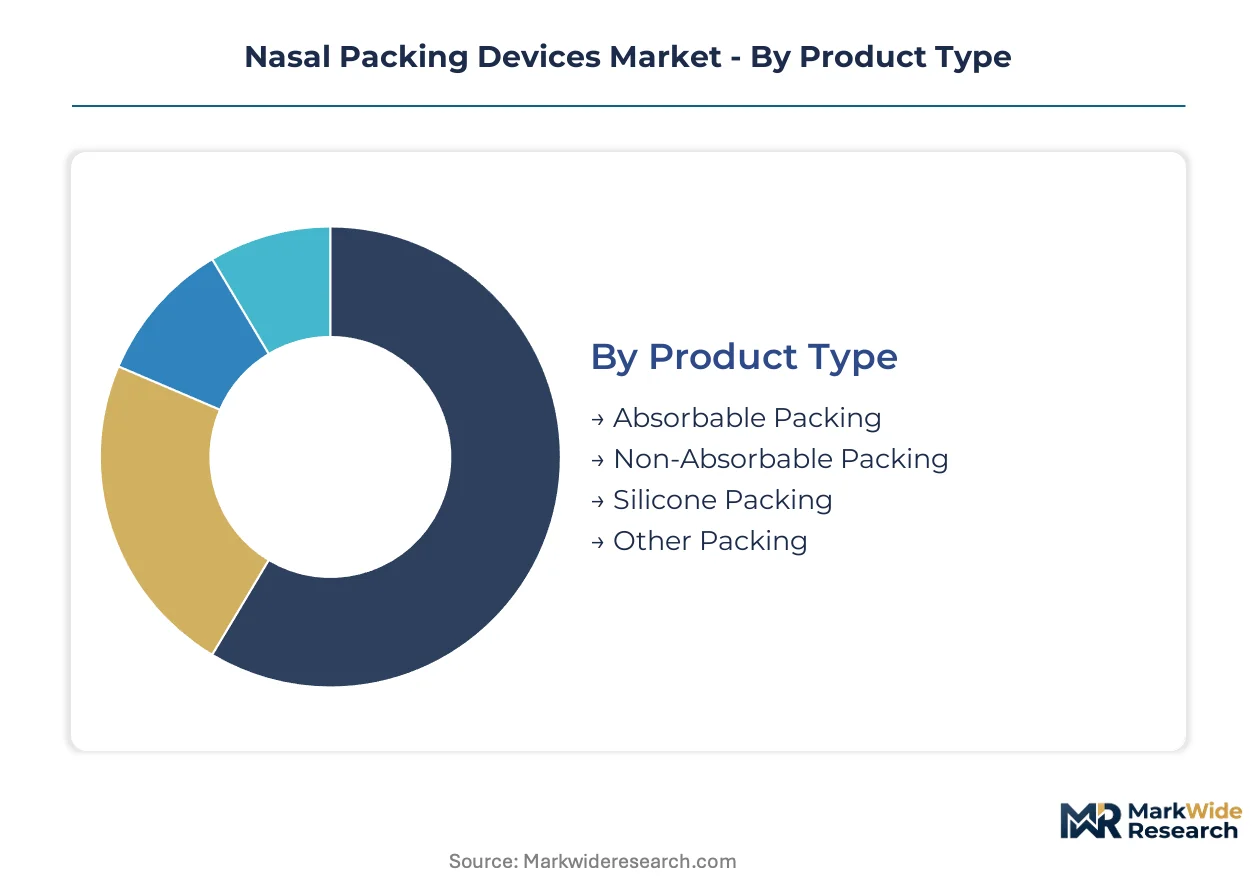
Segmentation in nasal packing devices reveals how material science, procedural setting, and supply chain configuration fragment purchasing authority. Manufacturers must align product portfolios across absorbable innovation, non-absorbable reliability, and silicone precision to capture divergent clinical workflows.
Product Type:
Mature absorbable formats dominate current volume while silicone and novel non-absorbable designs occupy emerging premium niches.
- Absorbable Packing:Composed of oxidized cellulose, gelatin foam, or carboxymethyl cellulose derivatives that resorb within 48-72 hours. Demand concentrates in ambulatory surgical centers across the United States where elimination of painful removal procedures supports same-day discharge protocols and reduces follow-up visit costs.
- Silicone Packing:Non-adherent polymer surfaces engineered for precise pressure modulation in complex endoscopic sinus surgery. Academic medical centers in Germany and Japan command premium pricing here where mucosal trauma reduction outweighs absorbable convenience in skull-base reconstructions.
- Non-Absorbable Packing:Traditional gauze and polyvinyl chloride formats retained for emergency epistaxis control where immediate hemostasis trumps removal logistics.
- Other Packing:Hybrid configurations and experimental biomaterial prototypes in limited clinical evaluation.
Absorbable packing retains volume leadership; silicone packing holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity polymers from validated biodegradable platforms undergoing regulatory scrutiny.
- Biodegradable Materials:Next-generation resorbable polymers reformulated to meet EU Green Deal sustainability targets and FDA guidance on resorbable surgical implants. German hospital procurement directives now favor these materials with preferential reimbursement positioning.
- Silicone:Medical-grade elastomers with non-adherent surface chemistry commanding premium pricing in complex procedures. Tokyo-Osaka corridor clinics in Japan demonstrate concentrated uptake for balloon catheter applications.
- Polyurethane:Versatile foam substrates balancing absorption capacity with structural integrity.
- Polyvinyl Chloride:Legacy formulation facing phase-out pressure from ECHA scrutiny of persistent organic pollutants under REACH authorization processes.
Biodegradable materials are climbing the fastest; polyvinyl chloride faces steepest contraction risk.
End User:
Customer type fragmentation shifts purchasing authority from centralized hospital procurement toward procedure-specific surgeon preference.
- Ambulatory Surgical Centers:Outpatient sinonasal procedure expansion in the United States drives single-use absorbable packing demand. Bundled contracts with integrated distributors now anchor supply relationships as these facilities eliminate follow-up removal visits.
- Hospitals:Multi-year supply agreements with major health systems concentrate volume among broad ENT portfolio manufacturers. Academic medical centers negotiate directly for specialty sinus surgery configurations.
- Clinics:Primary care and community ENT settings with standardized procedure volumes.
- Emergency Care Facilities:Rapid epistaxis intervention requiring immediate hemostasis without removal logistics.
Hospitals retain volume leadership; ambulatory surgical centers gain share fastest.
Distribution Channel:
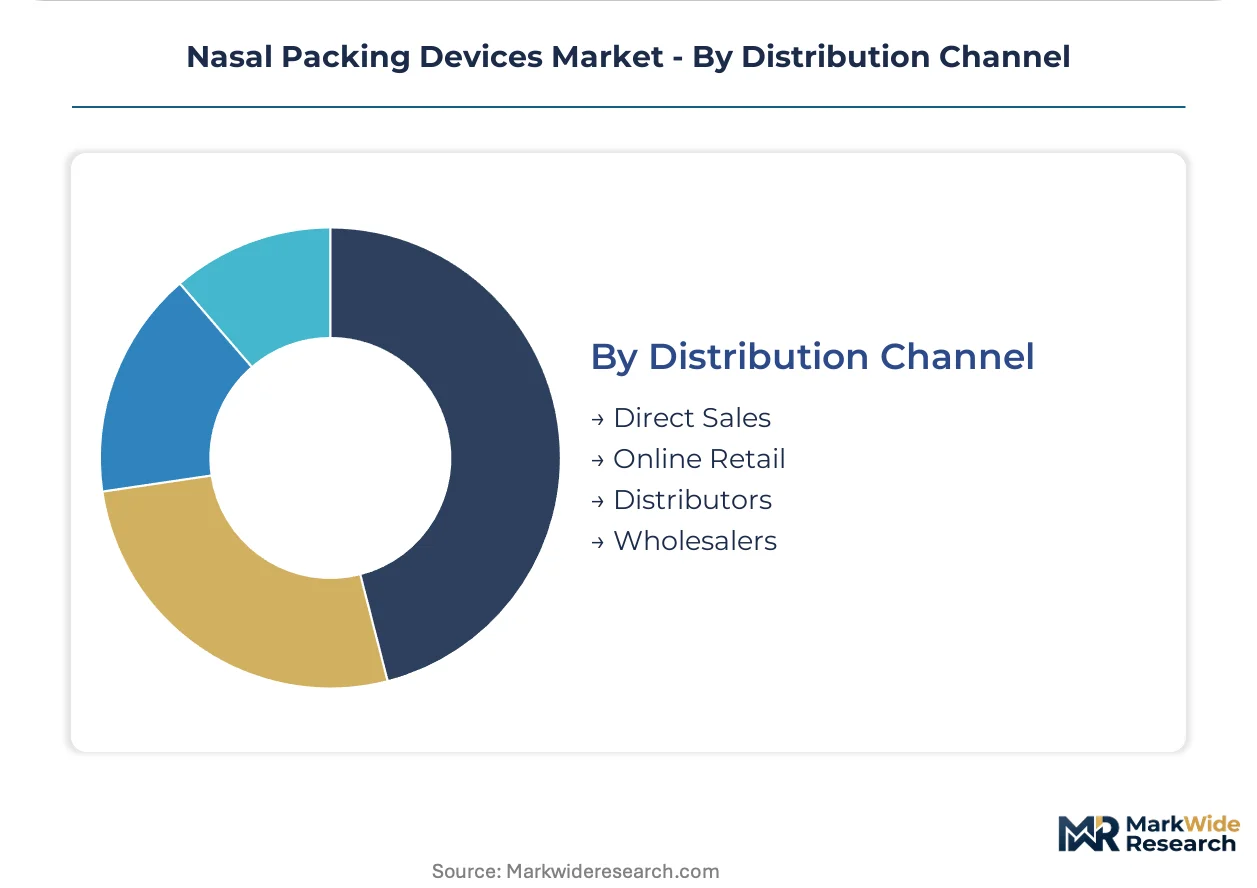
Supply concentration among integrated distributors is reshaping access patterns for standalone packing specialists.
- Distributors:Specialized ENT and surgical supply intermediaries dominating hospital procurement channels. German and French distributors now require comprehensive substance-of-very-high-concern attestations that constrain smaller component suppliers.
- Direct Sales:Manufacturer-to-provider relationships concentrated in academic medical centers and large health systems negotiating specialty configurations.
- Online Retail:Emerging channel for standardized absorbable formats in smaller clinic settings.
- Wholesalers:Bulk procurement intermediaries serving emergency care facilities with inventory depth requirements.
Distributors retain volume leadership; direct sales channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Europe's central role in oxidized cellulose supply chains, while direct air freight corridors from Cincinnati/Northern Kentucky International Airport anchor North American distribution velocity for time-sensitive ENT consumables.
United States
Ambulatory surgical centers in the Southeast and Pacific Northwest are expanding same-day sinonasal procedure volumes. FDA 510(k) clearance pathways for novel resorbable polymers now require extended biocompatibility testing that extends time-to-market. The Cincinnati-Northern Kentucky corridor concentrates sterilization and distribution infrastructure for absorbable packing formats.
Germany
State-level hospital sustainability mandates in Bavaria and North Rhine-Westphalia favor biodegradable surgical materials with preferential reimbursement positioning. EU MDR clinical evidence requirements under the Medical Device Regulation accelerate manufacturer investment in resorbable polymer R&D. The Rhine-Main cluster around Frankfurt anchors pharmaceutical-grade oxidized cellulose processing for European device manufacturers.
Japan
Tokyo-Osaka corridor clinics demonstrate concentrated uptake for silicone balloon catheter applications in complex skull-base reconstructions. PMDA regulatory frameworks for hemostatic biomaterials align with ISO 10993 standards for resorption-rate validation. The Kanto region's aging ENT patient base supports ambulatory care model expansion for outpatient epistaxis management.
United Kingdom
Academic medical centers in London and the Midlands negotiate directly with manufacturers for specialty sinus surgery configurations. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR clinical evidence requirements for hemostatic implants. The Oxford-Cambridge arc concentrates advanced biomaterial R&D partnerships between device manufacturers and university research centers.
India
Domestic ENT procedure volumes in Maharashtra and Karnataka are rising alongside private hospital chain expansion in tier-1 cities. CDSCO medical device regulations for hemostatic implants are tightening material validation protocols for imported absorbable packing. The Hyderabad-Bengaluru corridor attracts contract manufacturing investment for oxidized cellulose derivatives serving Asian markets.
Nasal Packing Devices Market Key Industry Players
On the supply side, the industry is consolidating around integrated ENT portfolios that anchor multi-year hospital supply agreements. Tiered competitive positioning separates broad-platform manufacturers from specialized hemostasis product lines and standalone packing specialists. Strategic archetypes include integrated medical device conglomerates, dedicated wound-care specialists, and regional contract manufacturers. Dominant competitive moves encompass backward integration into pharmaceutical-grade biomaterial supply and geographic expansion through distributor acquisition.
Among Ireland and UK-registered multinationals, Medtronic plc and Smith & Nephew plc exemplify the integrated portfolio archetype, leveraging broad ENT device ranges to secure health system contracts. Stryker Corporation represents the specialized hemostasis tier, occupying a position where high switching costs among surgeons sustain differentiated pricing. These three entities anchor competitive dynamics, while smaller specialists including Summit Medical and Network Medical Products sit within regional niche positions.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Smith & Nephew plc |
| Summit Medical (Innovia) |
| Teleflex Incorporated |
| Olympus Corporation |
| Lohmann & Rauscher |
| Network Medical Products Ltd |
| Meril Life Sciences Pvt Ltd |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade oxidized cellulose supply concentrates among three European chemical processors, anchoring margin pools downstream with integrated device manufacturers who command volume-discount leverage against standalone packing specialists.
Pricing Analysis
Volume-discount tiering structures separate three distinct pricing levels across premium silicone balloon catheters, standard absorbable formats, and economy non-absorbable gauze. Price differentiation hinges on FDA 510(k) clearance tier and ambulatory surgical center contract scale. Pricing pressure intensifies in the standard absorbable segment as German hospital sustainability mandates favor biodegradable materials with preferential reimbursement. Academic medical centers demonstrate lowest price sensitivity for silicone precision formats, while emergency care facilities prioritize unit cost minimization.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended payment terms have become standard for German and United States distributors managing inventory depth for hospital system contracts. Raw material sourcing draws from Belgium, Germany, and India for oxidized cellulose derivatives, gelatin foam substrates, and medical-grade silicone elastomers. Single-source vulnerability concentrates in pharmaceutical-grade carboxymethyl cellulose supply from the Rhine-Main cluster. Distribution runs through specialized ENT and surgical supply intermediaries with direct sales channels gaining share in academic medical center negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where surgeon switching costs around procedure-specific device kits create durable competitive entrenchment for integrated portfolio manufacturers.
For Market Incumbents: Pre-empt biodegradable material substitution by accelerating backward integration into pharmaceutical-grade oxidized cellulose supply chains in the Rhine-Main corridor. Secure multi-year GPO contracts with Southeast United States ambulatory surgical center networks before regional hospital systems consolidate purchasing authority. Anchor defensive positioning through captive supply of next-generation carboxymethyl cellulose derivatives with enhanced mucosal adhesion properties.
For New Entrants and Emerging Players: Pursue white-space opportunity in Tokyo-Osaka corridor outpatient epistaxis clinics where silicone balloon catheter penetration remains underdeveloped relative to academic medical centers. Target direct-to-clinic distribution models bypassing entrenched hospital procurement committees. Leverage telehealth-integrated follow-up protocols as a differentiated go-to-market angle pairing absorbable packing with digital symptom tracking platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed wound-care specialists holding regional European distributor networks but lacking integrated ENT portfolios. Long-term viability across the analysis window favors manufacturers with validated EU MDR clinical evidence packages and established hospital sustainability compliance. Watch PMDA regulatory alignment with ISO 10993 resorption-rate standards as the inflection signal for Japanese market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Accelerated resorbable polymer R&D pipelines secure preferential German hospital procurement positioning. |
| Biodegradable Material Reformulation | EU Green Deal compliance opens reimbursement advantages in Bavaria and North Rhine-Westphalia state mandates. |
| Ambulatory Surgical Center Partnership | Same-day discharge protocols in United States Southeast drive single-use absorbable packing volume concentration. |
| Telehealth-Integrated Follow-Up Development | Remote post-operative monitoring enables digital symptom tracking paired with absorbable packing workflows. |
| Pharmaceutical-Grade Biomaterial Integration | Backward control over oxidized cellulose supply reduces harvest-season input cost volatility exposure. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with ENT surgeons, biomedical engineers, GPO contracts managers, and pharmaceutical-grade biomaterial procurement leads. Secondary validation drew from ECHA REACH authorization records, CMS Medicare procedure volume data, and customs trade statistics for oxidized cellulose derivatives. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across absorbable, silicone, and non-absorbable product categories.
Assumption sets held fixed regulatory pathway timelines and reimbursement framework stability while varying ambulatory surgical center expansion rates and biodegradable material adoption curves across the projection horizon. Segmentation dimensions modeled included product type, material platform, end-user facility category, and distribution channel configuration. CAGRs derived from logistic curve fitting to historical procedure volume trajectories with elasticity adjustments for FDA 510(k) pathway friction and EU MDR clinical evidence requirement phase-ins.
Sensitivities concentrate around FDA biocompatibility testing timeline extensions, ECHA persistent organic pollutant restriction enforcement, and German state-level sustainability mandate implementation pace. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement framework continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygen Conservers Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Artificial Retina Market
Medical Devices
Vascular Boot Market
Medical Devices
Cyclotron Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Medical Device Cros Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Australia Drug Delivery Devices Market