
 Vascular Boot Market | 2026-2036
Vascular Boot Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Boot Market Analytics
ISO 13485 certification is rotating the competitive landscape by filtering out suppliers lacking quality management systems for medical device production. DJO Global (Enovis) leverages its orthopedic rehabilitation portfolio to sustain channel dominance across hospital purchasing networks. Össur hf. anchors its position through specialized prosthetic and vascular compression expertise, while Mölnlycke Health Care AB competes via advanced wound care integration with boot systems.
A vascular boot is a medical-grade external compression device engineered with multi-chamber inflatable bladders, typically constructed from thermoplastic polyurethane or nylon-reinforced fabrics, designed to enhance venous return and reduce edema in lower extremities. The device operates through sequential pneumatic compression cycles calibrated to 30-50 mmHg pressure ranges, serving primary clinical purposes in deep vein thrombosis prophylaxis, lymphedema management, and post-operative circulatory support. Compression boots command the largest revenue share within product type segmentation due to established clinical protocols and reimbursement familiarity, while hydrotherapy boots represent the fastest-expanding category as thermal-mechanical combination therapies gain traction in sports medicine. Home care end users are emerging as a critical demand vector, though hospitals retain the deepest margin pools through bundled procurement contracts.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) framework govern market access, with both agencies intensifying scrutiny of pneumatic compression device biocompatibility and electrical safety standards. The US Centers for Medicare & Medicaid Services reimbursement schedules directly shape hospital purchasing volumes, while Health Canada's Medical Devices Bureau maintains aligned pressure therapy classification criteria. Stakeholders must monitor evolving post-market surveillance requirements and pressure-based therapeutic equivalence studies to anticipate shifts in competitive qualification barriers.
Market Dynamics
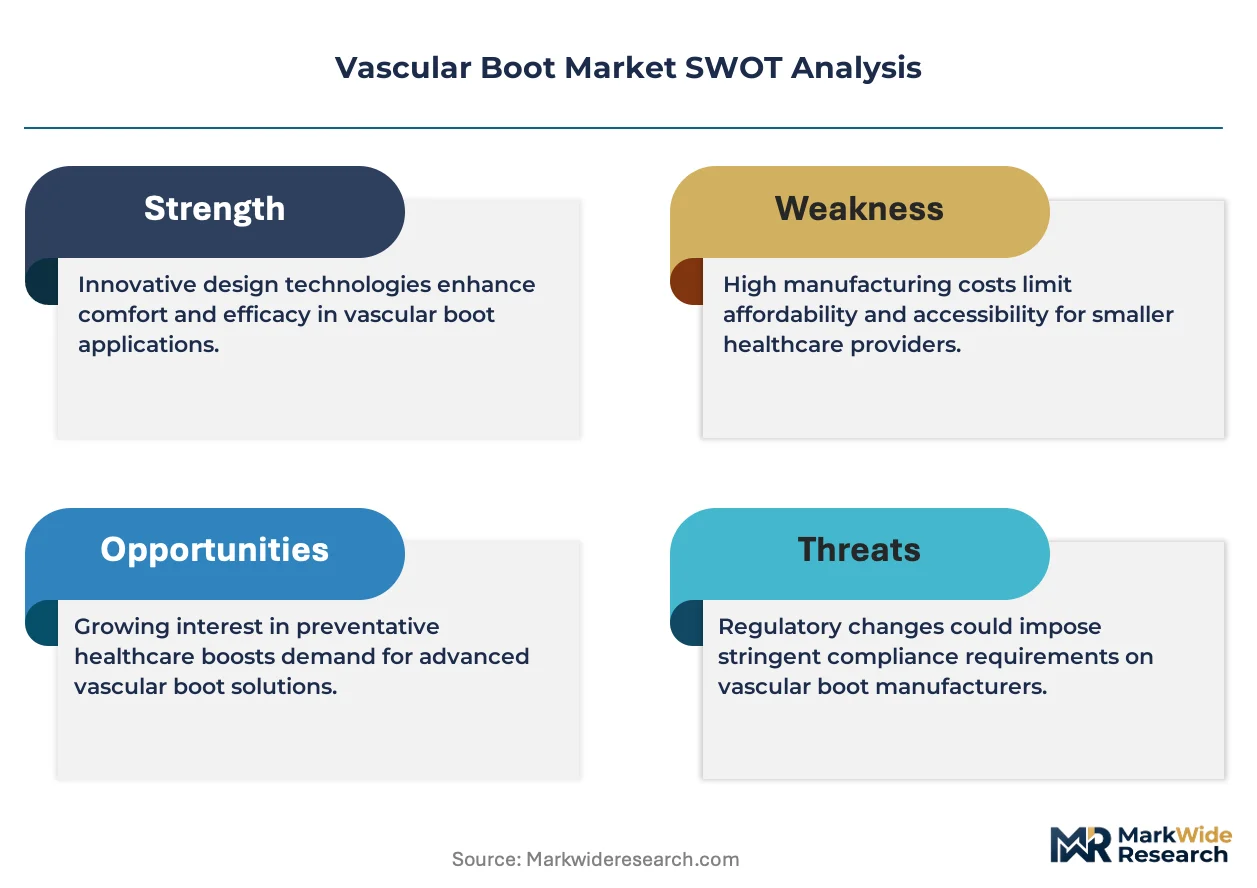
ISO 13485 certification requirements and EU MDR compliance timelines are compressing supplier qualification windows, forcing hospital procurement teams to consolidate vendor lists around established pneumatic compression device manufacturers with proven regulatory track records.
Growth Catalysts
- Post-surgical DVT prophylaxis protocols:Acute care hospitals in the United States are embedding pneumatic compression into standardized orthopedic recovery pathways, creating institutional purchasing momentum.
- Japan's reimbursement expansion:METI-aligned chronic wound management coverage is extending device eligibility to outpatient lymphedema patients, opening new prescription volumes.
- Thermoplastic polyurethane bladder advances:Multi-chamber inflation precision is improving pressure calibration reliability, reducing clinical skepticism toward home-use deployment.
Market Restraints
- Medical-grade polymer supply concentration:Nylon-reinforced fabric sourcing clusters in East Asian textile manufacturing regions, exposing finished goods producers to freight cost volatility.
- FDA 510(k) pathway friction:Biocompatibility testing documentation requirements for pneumatic compression surfaces are extending clearance timelines by eight to fourteen months for novel entrants.
- Manual compression substitute persistence:Low-cost elastic bandage wraps retain preference in price-sensitive long-term care facilities, capping premium device penetration.
Strategic Opportunities
- German home care infrastructure:Bundled reimbursement for venous insufficiency therapies is enabling direct-to-patient rental models outside hospital purchasing networks.
- Sports medicine thermal-mechanical convergence:Hydrotherapy boot integration with cryotherapy protocols is creating new outpatient clinic demand vectors distinct from traditional vascular applications.
- Health Canada pressure therapy alignment:Harmonized classification criteria with FDA standards is reducing dual-market registration costs for North American suppliers.
Industry Challenges
- Electrical safety certification bottlenecks:IEC 60601-1 third-edition testing for pneumatic pump systems is creating backlogs at notified bodies, delaying product launches.
- Clinical evidence generation costs:Pressure-based therapeutic equivalence studies required for EU MDR technical documentation are consuming substantial R&D budgets.
- Legacy EMR integration complexity:Hospital information systems lack standardized data fields for compression therapy session logging, complicating outcomes tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Boot Market |
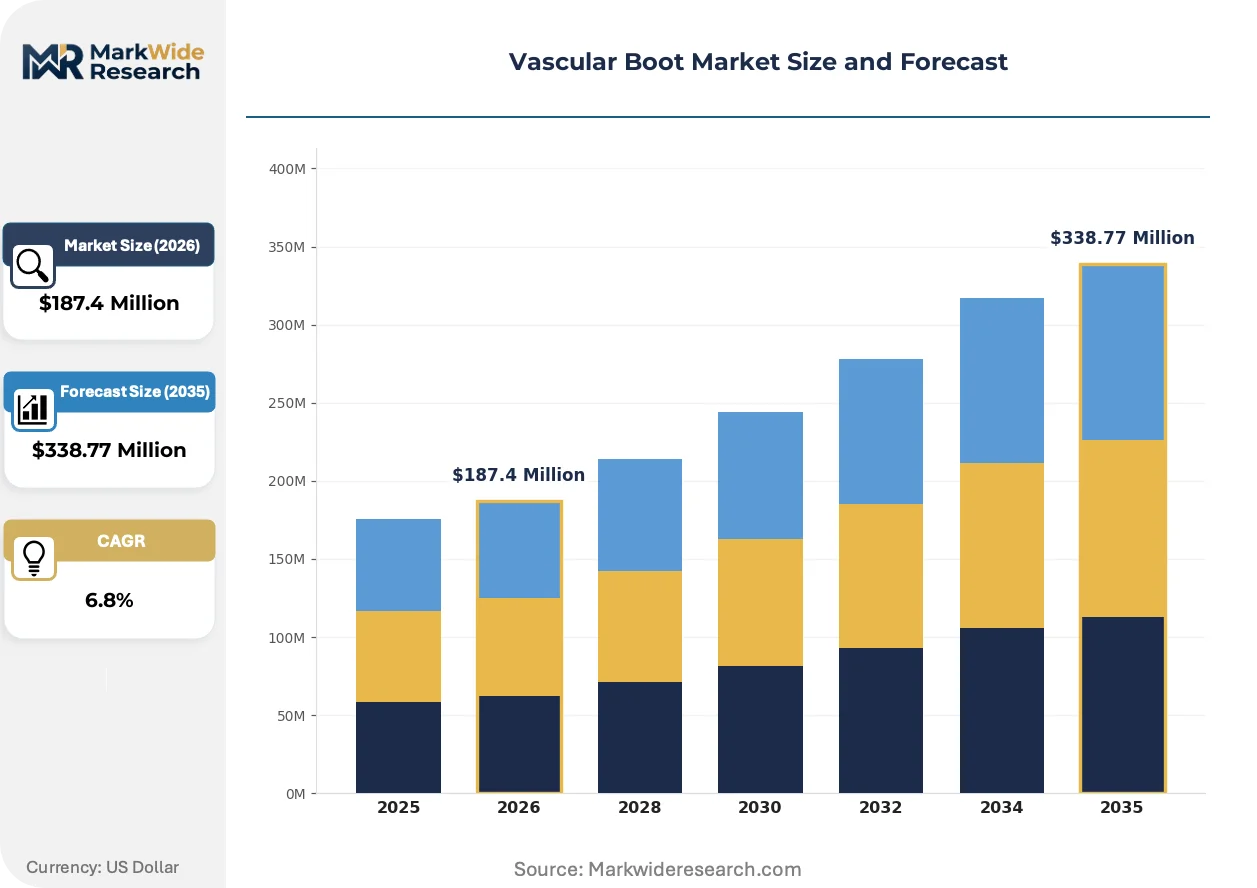
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Boots, Non-Inflatable Boots, Hydrotherapy Boots, Compression Boots Application: Rehabilitation, Post-Surgery Care, Injury Prevention, Pain Management End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics Material: Plastic, Foam, Fabric, Rubber |
| Companies Covered | DJO Global (Enovis), Össur hf., EHOB, Inc., DARCO International, Inc., Mölnlycke Health Care AB, Span-America Medical Systems, Medtronic, Boston Scientific Corporation, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Boot Market Evolving Landscape
Portable pneumatic systems are displacing stationary hospital-grade units as battery technology and pressure sensor miniaturization enable ambulatory venous therapy. Regulatory convergence and procurement model evolution are simultaneously compressing commercialization timelines and reshaping channel economics.
Wearable compression technology is miniaturizing through solid-state pressure generation and flexible circuit integration. Outpatient orthopedic clinics in Germany and Japan are piloting prescription take-home units with remote pressure monitoring. This shift is miniaturizing the addressable market for capital-intensive hospital bedside systems while expanding recurring revenue streams through disposable sleeve attachments.
EU MDR Article 120 transition deadlines are forcing legacy device recertification through notified body capacity constraints. Pneumatic compression manufacturers with pre-2021 CE marks face technical documentation gaps around biological safety evaluation. Class IIa vascular boot suppliers are consolidating testing partnerships to secure 2027-2028 certificate renewal slots ahead of queue bottlenecks.
Hospital purchasing consortiums are consolidating compression device procurement through orthopedic implant bundled contracts. Group purchasing organizations in the United States are extracting volume commitments in exchange for sole-source or dual-source arrangements. This concentration is visible in integrated delivery networks across Texas and California, where vascular boot selection now flows through spine and joint replacement implant vendor relationships.
Vascular Boot Market Segmentation
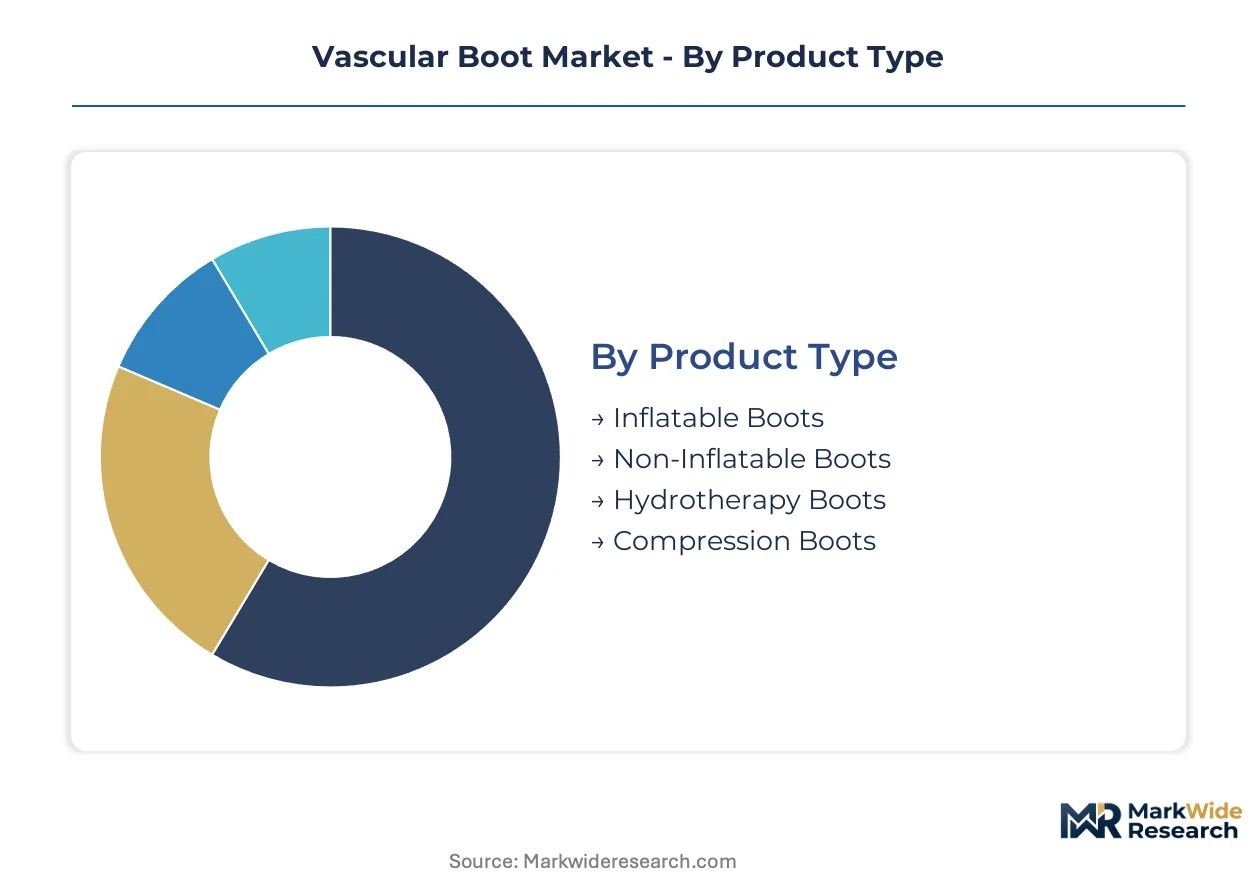
Product configuration determines reimbursement pathways and procurement channel access for vascular boot manufacturers. Channel economics diverge sharply between capital-intensive hospital systems and distributed home care networks.
Product Type:
Hospital purchasing networks favor pneumatic systems with established FDA 510(k) clearances, while home care channels prioritize portability and rental economics.
- Compression Boots:Multi-chamber inflatable bladders constructed from thermoplastic polyurethane deliver calibrated 30-50 mmHg pressure cycles. Acute care hospitals in the United States embed these devices into orthopedic recovery bundles, creating institutional purchasing momentum through bundled implant contracts.
- Hydrotherapy Boots:Thermal-mechanical combination systems integrate cryotherapy protocols with graduated compression. Sports medicine clinics in Germany and Japan are piloting prescription take-home units, opening outpatient demand vectors distinct from traditional vascular applications.
- Inflatable Boots:Single-chamber pneumatic designs serve price-sensitive long-term care facilities with basic DVT prophylaxis functionality.
- Non-Inflatable Boots:Passive compression systems rely on elastic material tension without powered inflation, dominating emergency medical services and field trauma applications.
By volume, Compression Boots lead hospital procurement. By growth pace, Hydrotherapy Boots are climbing the fastest through sports medicine channel expansion.
Application:
Clinical protocol standardization varies by reimbursement code availability, with post-surgical applications commanding premium pricing through bundled contracts.
- Post-Surgery Care:Standardized orthopedic recovery pathways in acute care hospitals mandate pneumatic compression for DVT prophylaxis. METI-aligned chronic wound management coverage in Japan extends device eligibility to outpatient settings, broadening prescription volumes.
- Rehabilitation:Lymphedema management protocols drive recurring use in specialized clinics. German bundled reimbursement for venous insufficiency therapies enables direct-to-patient rental models outside hospital networks.
- Pain Management:Chronic venous insufficiency patients access devices through durable medical equipment suppliers with periodic replacement schedules.
- Injury Prevention:Athletic programs and occupational health departments deploy portable units for high-risk personnel in manufacturing and logistics sectors.
Post-Surgery Care captures the deepest margin pools through bundled procurement. Rehabilitation is expanding most quickly as home care infrastructure matures.
End User:
Customer concentration shapes pricing power, with integrated delivery networks extracting volume commitments through sole-source arrangements.
- Hospitals:Group purchasing organizations in Texas and California consolidate vascular boot selection through spine and joint replacement implant vendor relationships, concentrating procurement decisions.
- Home Care:Battery technology and pressure sensor miniaturization enable ambulatory venous therapy with remote monitoring capabilities.
- Rehabilitation Centers:Specialized lymphedema clinics maintain direct relationships with manufacturers for customized pressure calibration protocols.
- Sports Clinics:Outpatient orthopedic facilities in Germany pilot prescription take-home units with disposable sleeve attachment revenue models.
Hospitals dominate capital expenditure budgets. Home Care is gaining share fastest as portable systems displace stationary bedside units.
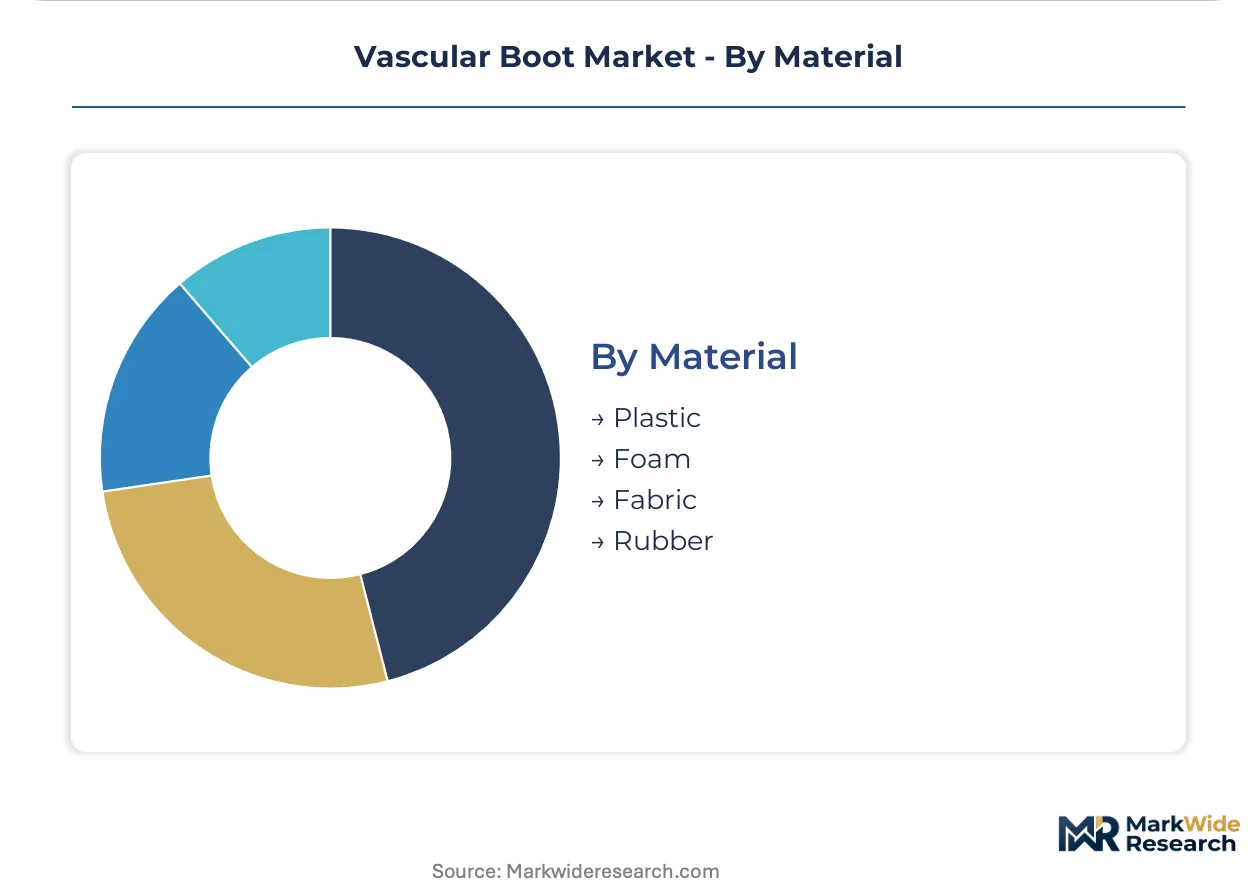
Material:
Supply chain geography for medical-grade polymers exposes finished goods producers to freight cost volatility and qualification timeline compression.
- Fabric:Nylon-reinforced textiles from East Asian manufacturing regions form the structural layer for multi-chamber inflatable systems.
- Plastic:Thermoplastic polyurethane bladders provide biocompatibility and pressure calibration reliability for pneumatic compression surfaces.
- Foam:Closed-cell cushioning materials serve non-inflatable designs for patient comfort in extended wear applications.
- Rubber:Natural and synthetic elastomers seal inflation chambers and connection interfaces in legacy pneumatic systems.
Fabric commands the largest procurement volumes. Plastic is advancing most quickly through thermoplastic polyurethane bladder technology improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement expansion for chronic wound management and venous insufficiency therapies is redirecting procurement volumes toward acute care networks and home care infrastructure across concentrated healthcare markets.
United States
Group purchasing organizations in Texas and California consolidate vascular boot selection through spine and joint replacement implant vendor relationships. FDA 510(k) clearance pathways govern market access for pneumatic compression devices. Integrated delivery networks in Houston and Los Angeles extract volume commitments through sole-source arrangements.
Germany
Bundled reimbursement for venous insufficiency therapies enables direct-to-patient rental models outside hospital purchasing networks. EU MDR compliance timelines compress supplier qualification windows through notified body capacity constraints. Outpatient orthopedic clinics in Bavaria pilot prescription take-home units with remote pressure monitoring capabilities.
Japan
METI-aligned chronic wound management coverage extends device eligibility to outpatient lymphedema patients. PMDA regulatory frameworks align with international standards for pneumatic compression device classification. Rehabilitation centers in Osaka and Tokyo maintain direct relationships with manufacturers for customized pressure calibration protocols.
United Kingdom
NHS procurement frameworks prioritize ISO 13485-certified suppliers with established pneumatic compression track records. MHRA post-market surveillance requirements intensify scrutiny of biocompatibility documentation. Hospital purchasing consortia in Greater London and the Midlands consolidate compression device procurement through orthopedic implant bundled contracts.
Vascular Boot Market Competitive Landscape
Player mix skews toward diversified orthopedic rehabilitation specialists with established regulatory track records and pneumatic compression device portfolios. Market structure concentrates around manufacturers with proven FDA 510(k) and EU MDR compliance histories. Three archetypes dominate: integrated orthopedic conglomerates, specialized vascular compression firms, and wound care system integrators. Competitive moves center on procurement bundling through implant vendor relationships and consolidation of notified body testing partnerships.
Within the integrated orthopedic tier, DJO Global (Enovis) and Össur hf. occupy positions shaped by rehabilitation portfolio breadth and vascular compression specialization respectively. Mölnlycke Health Care AB represents the wound care integration archetype. These three entities exemplify how channel dominance in hospital purchasing networks derives from either orthopedic implant bundling capabilities or advanced wound care system integration.
| Leading Market Players |
|---|
| DJO Global (Enovis) |
| Össur hf. |
| EHOB, Inc. |
| DARCO International, Inc. |
| Mölnlycke Health Care AB |
| Span-America Medical Systems |
| Medtronic |
| Boston Scientific Corporation |
| Becton Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with East Asian textile manufacturers lock in nylon-reinforced fabric supply while capping input cost volatility for pneumatic compression device producers. Hospital purchasing consortiums leverage these anchored supply positions to negotiate volume-based price ceilings across bundled orthopedic implant contracts.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-certified premium tiers and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, EU MDR compliance depth, and after-sales calibration support bundling. Cost compression in the economy tier is intensifying because long-term care facilities substitute manual elastic bandage wraps for powered systems. Home care end users exhibit the highest price sensitivity due to out-of-pocket rental exposure, while integrated delivery networks in Texas and California demonstrate the lowest sensitivity through captive procurement scale.
Supply Chain Analysis
Inventory lead times for thermoplastic polyurethane bladder components stretch across fourteen to eighteen weeks due to medical-grade polymer qualification protocols. Manufacturing concentrates in China, South Korea, and Taiwan for nylon-reinforced fabrics and thermoplastic polyurethane sheeting. Finished device assembly draws from these inputs while sourcing pressure sensors and pneumatic pumps from Japanese and German component specialists. Single-source vulnerability pervades the East Asian textile tier where freight cost spikes transmit directly into landed cost structures. Distribution runs through hospital group purchasing organizations in the United States and direct-to-patient rental platforms in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vascular boot market sits in early-cycle expansion as portable pneumatic systems displace stationary hospital-grade units and home care infrastructure matures across reimbursement-advanced economies.
For Market Incumbents: Shield market position through backward integration into thermoplastic polyurethane bladder production and accelerated notified body testing partnerships to secure EU MDR certificate renewal slots ahead of queue bottlenecks. Consolidate procurement bundling relationships with spine and joint replacement implant vendors before emerging players establish orthogonal channel access. For New Entrants and Emerging Players: Differentiate on remote pressure monitoring software integration for prescription take-home units in German and Japanese outpatient markets. Target sports medicine thermal-mechanical convergence as the most penetrable white space, leveraging hydrotherapy boot-cryotherapy protocol combinations distinct from established vascular applications. Pursue direct-to-clinic sales models bypassing hospital GPO consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with existing ISO 13485 infrastructure and dormant FDA 510(k) clearances awaiting portfolio activation. Long-term viability hinges on regulatory convergence momentum and home care reimbursement expansion across the next decade. Watch Health Canada pressure therapy alignment with FDA standards as the signal indicating reduced dual-market registration friction and accelerated North American consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certificate Renewal Acceleration | Notified body queue positioning determines 2027-2028 market access continuity for Class IIa suppliers. |
| Hospital System Partnership | Bundled orthopedic implant contracts in Texas and California concentrate vascular boot selection through vendor relationships. |
| Software Companion Development | Remote pressure monitoring integration enables prescription take-home unit pilots in German outpatient clinics. |
| Reimbursement Strategy | METI-aligned chronic wound management coverage in Japan extends device eligibility to outpatient lymphedema patients. |
| Backward Integration | In-house thermoplastic polyurethane bladder production reduces exposure to medical-grade polymer supply concentration. |
Research Methodology
Cross-validation between hospital procurement database analysis and clinician interview transcripts anchors the qualitative findings in this study. Primary fieldwork encompassed biomedical engineers, GPO contracts managers, hospital purchasing committee members, and rehabilitation center clinical directors across the United States, Germany, and Japan. Secondary sources included FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital capital expenditure records. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across product configurations and end-user channels.
Sensitivity analysis around reimbursement policy shifts and regulatory timeline compression informs the probabilistic forecast range. The analytical framework models product type, application, end user, material composition, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level growth rate blending weighted by revenue contribution. Forecast inputs incorporate pneumatic compression device adoption curves in post-surgical protocols and portable system battery technology advancement trajectories.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR transition timelines, and Japan METI reimbursement expansion; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Orthodontic Equipment Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Glass Syringe Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Canada Spinal Surgery Devices Market