
 Actigraphy Sensors and Polysomnography Devices Market | 2026-2036
Actigraphy Sensors and Polysomnography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Actigraphy Sensors and Polysomnography Devices Market Analysis
A shift from outsourced component procurement to in-house MEMS fabrication is hardening among top-tier manufacturers. ResMed leverages captive sensor production to protect margin pools on continuous monitoring hardware. Philips sustains dual-source strategies for polysomnography amplifiers while competing on integrated software-to-cloud architectures. Garmin anchors its position through backward integration into accelerometer design, differentiating consumer-grade actigraphy from clinical-tier offerings.
Actigraphy sensors and polysomnography devices comprise electromechanical systems that capture tri-axial acceleration, peripheral blood oxygen saturation, electroencephalographic waveforms, and respiratory effort signals at sampling rates between 10 Hz and 512 Hz for epoch-based sleep staging and activity classification. These systems serve commercial purposes spanning diagnostic sleep medicine, cardiometabolic risk stratification, and pharmaceutical trial endpoint verification. Wearable sensors and monitoring systems command the dominant revenue share due to recurring electrode and adhesive consumables, while mobile apps connected to wireless integration backends represent the fastest-expanding margin pool as software-only reimbursement codes gain traction. Cloud technology deployments within polysomnography workflows concentrate margin capture among platform operators rather than hardware OEMs.
The FDA's 510(k) pathway for multi-parameter sleep monitors and the EU MDR's Class IIa reclassification for ambulatory polygraphy systems impose clinical-validation burdens that filter subscale entrants. Japan's PMDA enforces JIS T 0601 electromagnetic-compatibility standards that delay foreign product registrations by twelve to eighteen months. China's NMPA now requires domestic cybersecurity reviews for cloud-connected sleep data, creating parallel certification tracks. Stakeholders must monitor divergence between FDA software-as-medical-device guidance and EU AI Act risk tiers for automated sleep-scoring algorithms.
Market Dynamics
The transition from facility-based polysomnography to home sleep testing is compressing capital equipment cycles while elevating consumable revenue streams for wearable sensor manufacturers.
Growth Catalysts
- Home Sleep Testing Reimbursement:CMS and private payers in the United States now cover unattended polygraphy for obstructive sleep apnea diagnosis, diverting patient volume from hospital sleep laboratories.
- EU MDR Class IIa Pathway:The reclassification of ambulatory polygraphy systems under the EU Medical Device Regulation creates harmonized market access across Germany, France, and Italy for validated devices.
- MEMS Fabrication Scale:Captive production of tri-axial accelerometers by tier-one manufacturers is lowering bill-of-materials costs for clinical-grade actigraphy wristbands.
Market Restraints
- Electrode Raw Material Concentration:Silver-silver chloride electrode production concentrates in East Asian chemical processors, exposing consumables margins to precious metal price volatility.
- PMDA Electromagnetic Compatibility Testing:Japan's JIS T 0601 standards impose eighteen-month registration delays that freeze foreign device entrants out of the world's third-largest sleep diagnostics market.
- Algorithm Substitution Risk:FDA-cleared automated sleep-scoring software threatens hardware attachment rates by reducing reliance on manual polysomnography technologist interpretation.
Strategic Opportunities
- Pharmaceutical Trial Endpoint Verification:Contract research organizations in Germany and the United States are integrating actigraphy-derived sleep-wake parameters as objective outcome measures in central nervous system drug development.
- Cardiometabolic Risk Stratification:Sleep clinics in Japan are deploying combined actigraphy-oximetry systems to identify atrial fibrillation burden through nocturnal oxygen desaturation pattern recognition.
- Cloud-Connected Reimbursement Codes:CPT Category III codes for remote patient monitoring are expanding software-only revenue pools for platform operators managing sleep disorder longitudinal care.
Industry Challenges
- Polysomnography Technologist Shortage:Sleep medicine accreditation bodies in the United States report insufficient board-registered technologists to meet rising home sleep testing interpretation demand.
- Cross-Border Data Residency Requirements:China's NMPA cybersecurity reviews for cloud-connected sleep data force manufacturers to maintain parallel domestic server infrastructure, fragmenting platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Actigraphy Sensors and Polysomnography Devices Market |
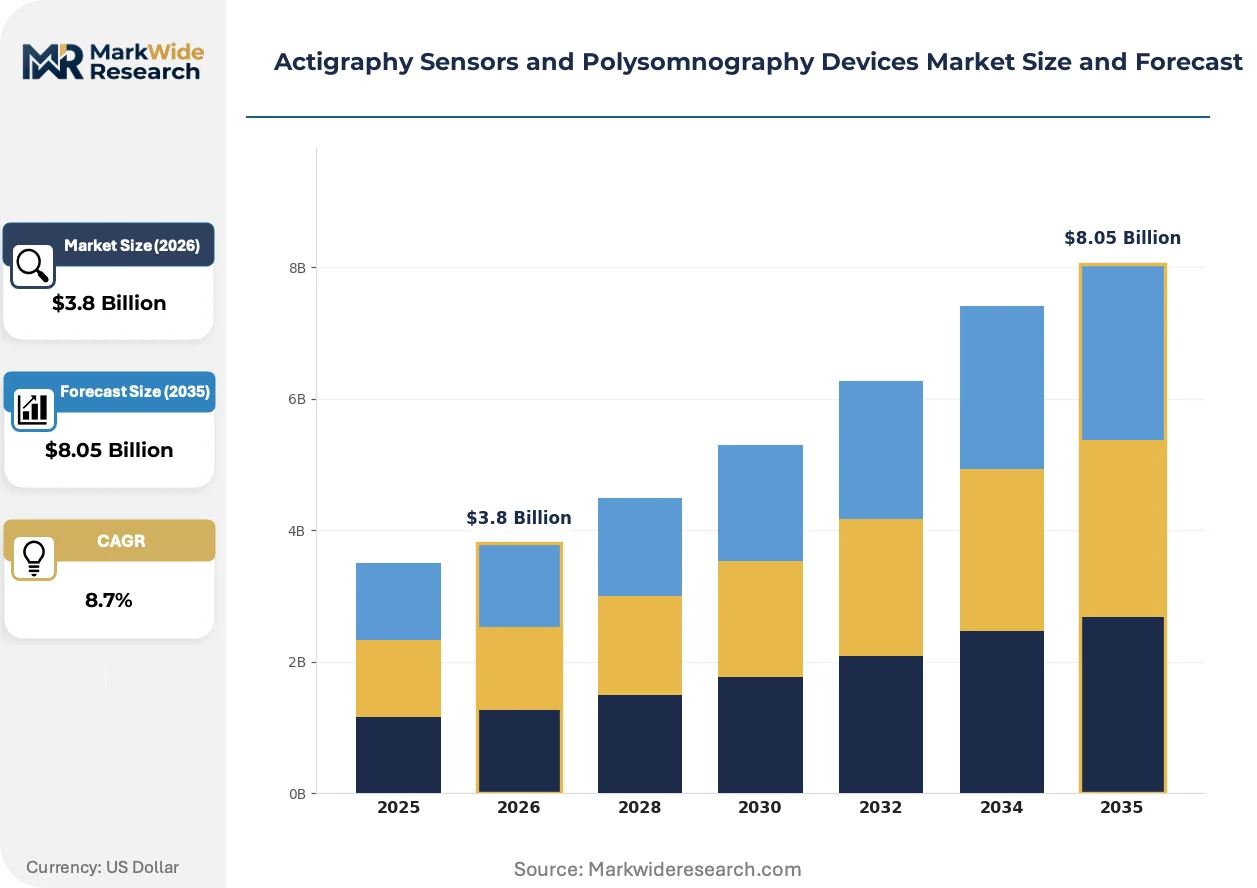
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Tabletop Devices, Mobile Apps, Monitoring Systems End User: Hospitals, Homecare Providers, Research Institutions, Fitness Centers Technology: Actigraphy, Polysomnography, Wireless Integration, Cloud Technology Application: Sleep Disorders, Physical Activity Monitoring, Clinical Research, Wellness Assessment |
| Companies Covered | ResMed, Nox Medical, Philips, Compumedics, SOMNOmedics, Garmin, Natus Medical, ActiGraph, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Actigraphy Sensors and Polysomnography Devices Market Emerging Trajectories
Machine learning inference at the sensor edge is displacing cloud-dependent sleep staging workflows while regulatory divergence between FDA software guidance and EU AI Act risk tiers is fragmenting algorithm deployment strategies.
Photoplethysmography-enabled actigraphy sensors are expanding into continuous blood pressure estimation and arterial stiffness monitoring. Cardiology outpatient clinics in Germany and Japan are piloting these dual-use wearables for integrated sleep-cardiovascular risk assessment. The technology is expanding into pharmaceutical safety monitoring by capturing nocturnal hypotension events during antihypertensive trials.
The FDA's evolving software-as-medical-device guidance now treats machine learning-enabled sleep scoring as a distinct regulatory category from static algorithm predicate devices. This policy divergence from EU MDR's risk-based classification approach is forcing manufacturers to maintain separate validation datasets for United States and European submissions. Sleep technology startups are responding by establishing dual-track clinical trial programs earlier in development cycles.
Hospital sleep centers are unbundling diagnostic interpretation from device provision, contracting directly with independent diagnostic testing facilities for home sleep testing logistics. This channel restructuring concentrates procurement authority with supply chain managers rather than clinical department heads. The shift is most advanced in United States integrated delivery networks where centralized purchasing agreements cover multiple hospital sleep laboratories across state boundaries.
Actigraphy Sensors and Polysomnography Devices Market Segmentation
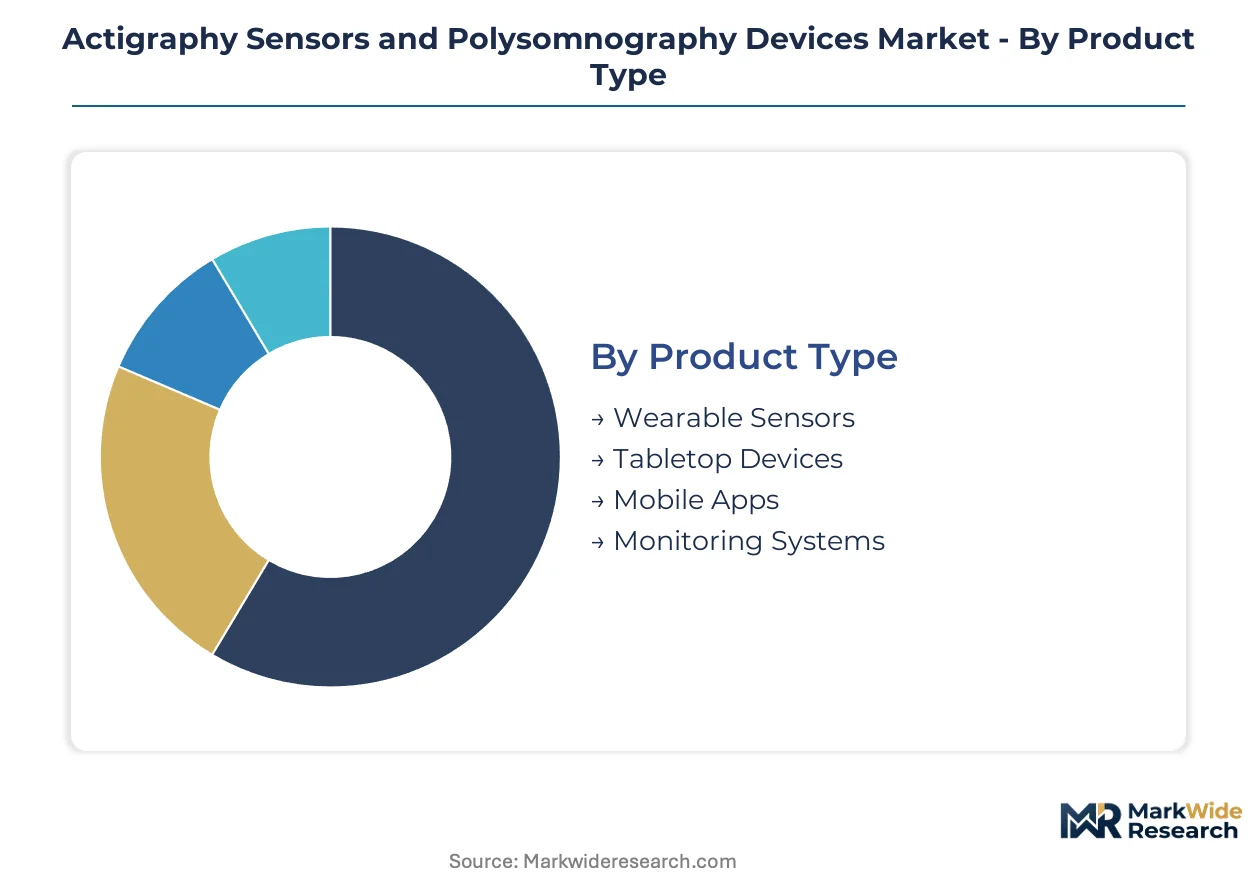
Segmentation in sleep diagnostics reveals how hardware form factors, care delivery settings, and data architectures compete for procurement budgets. Each dimension exposes distinct margin pools and regulatory exposure profiles that shape vendor positioning.
Product Type:
Replacement cycles vary sharply across form factors, with wearable sensors refreshing every 18-24 months while tabletop polysomnography systems persist for 7-10 years.
- Wearable Sensors:Tri-axial accelerometers with photoplethysmography modules capture limb movement and peripheral oxygen saturation at sub-milliwatt power budgets. Sleep clinics in the United States favor wrist-worn actigraphy for home sleep testing protocols where CMS reimbursement codes now cover unattended diagnostics.
- Tabletop Devices:Multi-channel polysomnography amplifiers integrate electroencephalography, electrooculography, and respiratory effort transducers in cart-mounted configurations. Hospital sleep centers in Germany retain these systems for complex parasomnia evaluations where manual technologist scoring remains the clinical standard.
- Mobile Apps:Smartphone-based sleep diaries and acoustic snoring detection leverage onboard microphones and accelerometers for consumer-grade screening.
- Monitoring Systems:Integrated hardware-software platforms combine bedside units with cloud dashboards for longitudinal sleep disorder management.
Wearable Sensors sits at the top of the volume ranking, with Mobile Apps climbing the fastest.
End User:
Procurement authority is migrating from clinical department heads to supply chain managers as integrated delivery networks consolidate purchasing across multiple facilities.
- Hospitals:Academic medical centers maintain in-laboratory polysomnography suites for surgical clearance and narcolepsy confirmation. The FDA's 510(k) pathway for multi-parameter sleep monitors governs device selection in these settings.
- Homecare Providers:Independent diagnostic testing facilities manage logistics for mail-order home sleep testing, capturing patient volume diverted from hospital laboratories. CMS reimbursement expansion for unattended polygraphy accelerates capital deployment in this channel.
- Research Institutions:Contract research organizations in Germany and the United States specify actigraphy-derived endpoints for central nervous system drug trials.
- Fitness Centers:Corporate wellness programs deploy consumer-grade wearables for population-level sleep hygiene screening without diagnostic claims.
Hospitals command the largest installed base, though Homecare Providers are expanding most quickly.
Technology:
Data architecture decisions determine whether margin pools accrue to hardware OEMs or platform operators managing cloud backends.
- Actigraphy:Epoch-based movement classification algorithms process tri-axial acceleration at 10-50 Hz sampling rates for sleep-wake scoring. Japan's PMDA enforces JIS T 0601 electromagnetic-compatibility standards that filter subscale entrants from this technology segment.
- Polysomnography:Gold-standard multi-channel recording captures electroencephalographic, respiratory, and cardiac signals at 200-512 Hz for manual sleep staging. The EU MDR's Class IIa reclassification for ambulatory polygraphy systems imposes clinical-validation burdens that reshape competitive dynamics.
- Wireless Integration:Bluetooth Low Energy and proprietary radio protocols enable cable-free sensor connectivity for patient comfort.
- Cloud Technology:Centralized data repositories with automated scoring algorithms shift value capture toward software operators.
Actigraphy holds the dominant revenue position, while Cloud Technology shows the steepest expansion trajectory.
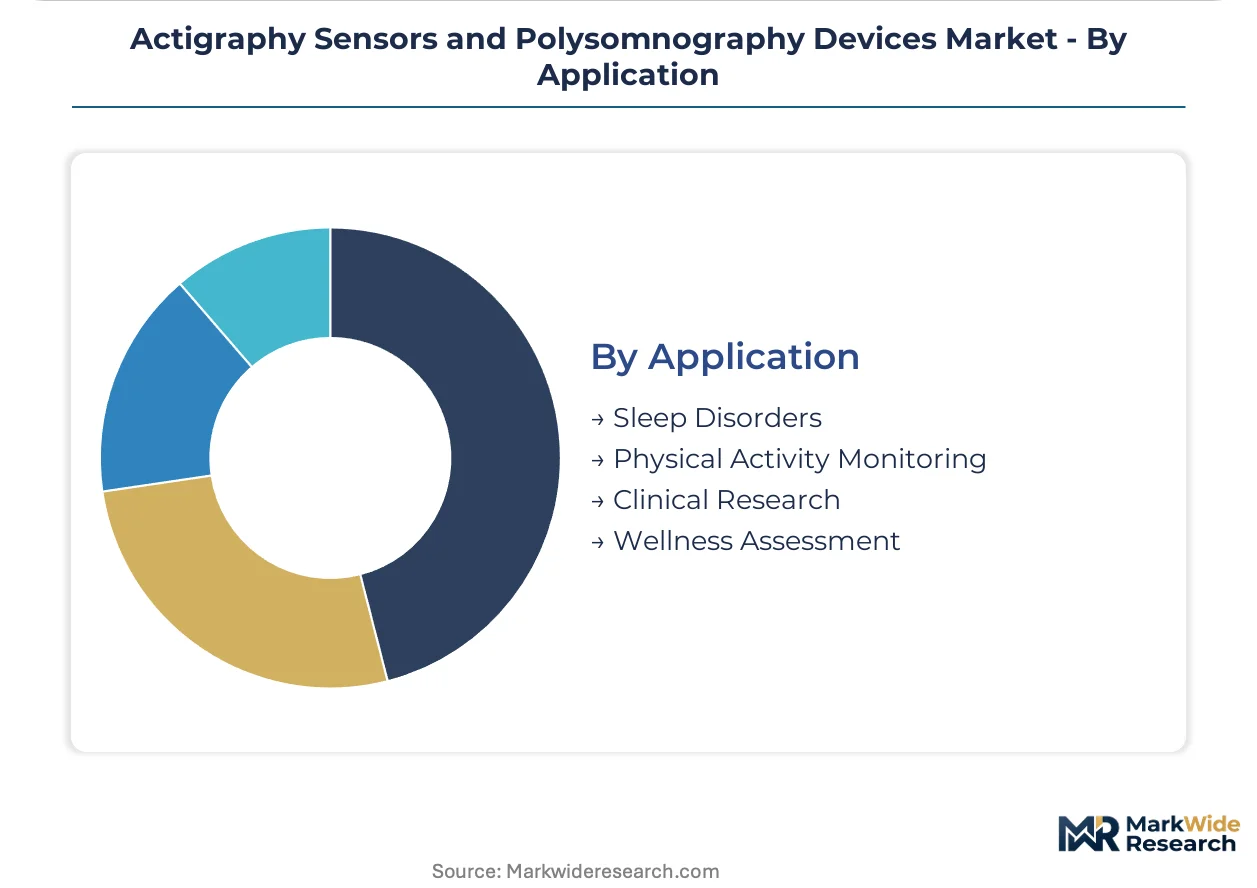
Application:
Clinical validation requirements separate reimbursable diagnostic applications from consumer wellness use cases with limited regulatory oversight.
- Sleep Disorders:Obstructive sleep apnea diagnosis drives the majority of reimbursed testing volume, with home sleep testing protocols displacing facility-based polysomnography for uncomplicated cases. Germany's statutory health insurance funds now cover ambulatory polygraphy with comparable reimbursement rates to in-laboratory studies.
- Physical Activity Monitoring:Circadian rhythm assessment for shift workers and athletes leverages actigraphy-derived rest-activity patterns without diagnostic claims. Fitness centers in Japan pilot these applications for corporate wellness contracts.
- Clinical Research:Pharmaceutical trials require FDA-cleared devices with documented accuracy against polysomnography reference standards.
- Wellness Assessment:Consumer sleep tracking operates outside medical device regulations with limited clinical utility validation.
Sleep Disorders leads in revenue concentration, with Clinical Research gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as tier-one producers relocate MEMS fabrication to jurisdictions with streamlined medical device certification pathways. Cost-of-compliance gaps between the FDA's 510(k) process and Japan's PMDA electromagnetic-compatibility testing create eighteen-month entry differentials that concentrate final assembly in lower-burden markets.
United States
CMS reimbursement expansion for unattended home sleep testing diverts patient volume from hospital laboratories toward independent diagnostic testing facilities. The FDA's evolving software-as-medical-device guidance imposes distinct validation burdens for machine learning-enabled sleep scoring algorithms. Sleep technology clusters in California and Massachusetts concentrate venture-backed startups pursuing dual-track clinical trial programs for transatlantic submissions.
Germany
Statutory health insurance funds now cover ambulatory polygraphy with reimbursement rates comparable to in-laboratory polysomnography, accelerating capital deployment in homecare channels. The EU MDR's Class IIa reclassification for ambulatory polygraphy systems harmonizes market access across German, French, and Italian territories. Medical device engineering concentrates in Baden-Württemberg, where contract research organizations integrate actigraphy endpoints into central nervous system pharmaceutical trials.
Japan
PMDA enforcement of JIS T 0601 electromagnetic-compatibility standards delays foreign product registrations by twelve to eighteen months, filtering subscale entrants from the world's third-largest sleep diagnostics market. METI funding for digital health innovation supports domestic wearable sensor development. Sleep clinics in Tokyo and Osaka deploy combined actigraphy-oximetry systems for nocturnal atrial fibrillation burden assessment through oxygen desaturation pattern recognition.
China
NMPA cybersecurity reviews for cloud-connected sleep data force manufacturers to maintain parallel domestic server infrastructure, fragmenting platform architectures. The country's national medical device regulator now requires local clinical validation datasets for algorithm clearance. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate silver-silver chloride electrode production, exposing consumables margins to precious metal price volatility.
Actigraphy Sensors and Polysomnography Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in pharmaceutical trial endpoint verification and cardiometabolic risk stratification. The vendor base stratifies across three tiers: integrated sleep medicine platforms with captive sensor production, specialized polysomnography amplifier manufacturers, and consumer-grade wearable specialists seeking clinical validation pathways. Dominant competitive moves include backward integration into MEMS fabrication to protect margin pools and strategic partnerships with contract research organizations for drug trial data generation.
Among diversified medical technology conglomerates, ResMed and Philips exemplify the integrated platform archetype, while Garmin occupies a position bridging consumer wellness and clinical-tier actigraphy. Specialists in polysomnography amplifier design include Nox Medical and Compumedics, representing the precision instrumentation tier. These named entities anchor competitive dynamics without constraining the full competitive set, as regional specialists and venture-backed algorithm developers occupy adjacent positions in the value chain.
| Leading Market Players |
|---|
| ResMed |
| Nox Medical |
| Philips |
| Compumedics |
| SOMNOmedics |
| Garmin |
| Natus Medical |
| ActiGraph |
| Fitbit |
| Others |
Supply Flow & Price Mechanics
Captive MEMS fabrication by tier-one manufacturers anchors supply security and pricing power for clinical-grade actigraphy hardware. ResMed's in-house accelerometer production insulates margins from silver-silver chloride electrode volatility while Philips maintains dual-source amplifier strategies to preserve negotiating leverage with German sensor foundries.
Pricing Analysis
Distributor margins on tabletop polysomnography systems compress as hospital sleep centers consolidate procurement through integrated delivery network agreements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from CE-marked ambulatory systems and consumer-grade wellness trackers. Cost compression in electrode consumables intensifies because East Asian precious metal processors command raw material pricing. Homecare providers exhibit highest price sensitivity due to CMS reimbursement rate ceilings, while academic medical centers absorb premium pricing for multi-channel in-laboratory systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States integrated delivery networks, bypassing traditional medical device distributors. Manufacturing concentrates in China for silver-silver chloride electrodes, Germany for precision polysomnography amplifiers, and Japan for JIS T 0601-compliant wearable sensors. Component sourcing rests on Taiwanese MEMS foundries, South Korean battery suppliers, and domestic Chinese cloud infrastructure providers. Single-source vulnerability in East Asian chemical processing exposes consumables margins to commodity price swings. Distribution runs through hospital purchasing committees, independent diagnostic testing facilities, and contract research organizations for pharmaceutical trial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where FDA 510(k) pathways diverge from EU MDR Class IIa validation burdens, compressing time-to-market differentials by twelve to eighteen months for agile entrants.
For Market Incumbents: Extend cloud platform subscriptions to capture recurring revenue pools as hardware attachment rates face pressure from FDA-cleared automated sleep-scoring algorithms. Deepen backward integration into photoplethysmography module design to differentiate clinical-tier wristbands from consumer-grade alternatives. Prioritize dual-track clinical validation programs spanning United States and European submission pathways to preempt regulatory fragmentation costs. For New Entrants and Emerging Players: CMS reimbursement expansion for unattended home sleep testing in the United States opens a window for independent diagnostic testing facility partnerships without hospital laboratory infrastructure investments. Target pharmaceutical trial endpoint verification as the most penetrable application, where contract research organizations in Germany and Massachusetts seek actigraphy-derived objective outcome measures. Pursue software-as-medical-device clearance ahead of hardware development to accelerate revenue generation through CPT Category III remote patient monitoring codes. For Investors and Strategic Acquirers: Roll-up economics work for specialized polysomnography amplifier manufacturers because hospital sleep center consolidation concentrates procurement authority with supply chain managers seeking single-vendor solutions. Five-to-ten year viability hinges on algorithm-enabled margin capture shifting from hardware OEMs to platform operators. Watch FDA software-as-medical-device guidance divergence from EU AI Act risk tiers as the inflection signal for dual-track regulatory investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive accelerometer production protects margin pools from East Asian precious metal volatility. |
| Dual-Track Regulatory Investment | Parallel FDA and EU MDR validation programs preempt twelve-to-eighteen month market access delays. |
| Cloud Platform Subscription Expansion | Recurring software revenue offsets hardware attachment rate pressure from automated scoring algorithms. |
| Pharmaceutical Trial Partnership Development | Contract research organization alliances in Germany and Massachusetts secure actigraphy endpoint verification contracts. |
| Home Sleep Testing Logistics Integration | Independent diagnostic testing facility channel control captures patient volume diverted from hospital laboratories. |
Methodological Framework
Direct dialogue with hospital purchasing committee members, polysomnography technologists, biomedical engineers at sleep centers, and GPO contracts managers grounded qualitative findings in procurement decision patterns. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract registries. Bottom-up unit economics and top-down epidemiological demand models triangulated market sizing across wearable sensors, tabletop devices, and cloud-connected monitoring platforms.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through structured forecasting frameworks spanning the projection horizon. CAGRs were derived from regression analysis of historical reimbursement expansion rates, MEMS cost curves, and pharmaceutical trial endpoint adoption patterns. Model inputs included PMDA registration delay distributions, NMPA cybersecurity review timelines, and silver price elasticity coefficients for electrode consumables.
Revisions become necessary when FDA software-as-medical-device guidance diverges from EU AI Act implementation timelines, when PMDA electromagnetic-compatibility testing durations shift, or when CMS reimbursement codes for remote patient monitoring expand or contract. Forecasts reflect documented assumptions regarding MEMS fabrication scale economies and cloud infrastructure deployment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Airway Management Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Air Compressor Nebulizer Market