
 Global Blood Plasma Derivatives Market | 2026-2036
Global Blood Plasma Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Plasma Derivatives Market Foresight
Fractionation service revenue is tilting toward high-yield immunoglobulin and specialty coagulation factor outputs as plasma collectors seek margin protection against raw material cost volatility. CSL Limited leverages its vertically integrated plasma collection network across the United States and Germany to sustain throughput advantages. Grifols anchors its position through controlled plasma supply chains and dense donor center footprints in Southern Europe and North America. Takeda Pharmaceutical Company Limited differentiates via its specialty immunology portfolio and concentrated hemophilia therapy expertise.
Blood plasma derivatives are therapeutic proteins isolated from human plasma through industrial fractionation, with immunoglobulin products typically requiring cold ethanol precipitation followed by chromatographic purification to achieve immunoglobulin G concentrations exceeding 95 percent. These derivatives serve essential clinical functions ranging from immune modulation and clotting restoration to volume expansion and wound sealing in acute and chronic care settings. Immunoglobulin commands the largest value share within product type segmentation, reflecting its broad application across primary and secondary immunodeficiency conditions. Albumin maintains steady demand in surgical and burn management applications where volume resuscitation protocols remain standardized. Coagulation factors represent the fastest-expanding margin pool, driven by prophylactic hemophilia regimens and extended half-life recombinant-enhanced formulations.
FDA plasma collection and fractionation standards govern product safety and viral inactivation requirements in the United States, while EMA's centralized marketing authorization procedures and the EU's F-Gas Regulation constrain cold-chain logistics and storage infrastructure choices across European manufacturing sites. Japan's PMDA enforces stringent lot-release testing that limits import velocity and privileges domestic fractionation partnerships. Stakeholders must monitor regulatory divergence in pathogen safety validation, as emerging nucleic acid testing and prion reduction mandates will reshape capital deployment priorities for fractionation capacity expansion.
Market Dynamics
Fractionation capacity constraints are compressing margin structures as plasma collection economics tighten against viral safety mandates and cold-chain infrastructure requirements. Raw material scarcity is forcing collectors to secure donor volumes through geographic expansion and loyalty program investments.
Growth Catalysts
- FDA plasma collection standards:Stringent viral inactivation protocols validate product safety for hospital procurement committees, accelerating institutional adoption of certified derivatives in critical care settings.
- Chromatography purification methods:Advanced resin-based separation technologies are lifting immunoglobulin yields above 95 percent purity thresholds, improving unit economics for specialty coagulation factor production.
- Japan's aging demographic:Expanding elderly populations with chronic immunodeficiency conditions are sustaining prophylactic immunoglobulin regimens through established reimbursement pathways.
Market Restraints
- Plasma donor availability volatility:Compensation cost inflation and competing biologics recruitment are constraining source material access in United States collection networks.
- EMA F-Gas Regulation:Refrigerant phase-down mandates are elevating cold-chain infrastructure capital requirements for European fractionation facilities.
- Recombinant factor concentrates:Engineered alternatives with extended half-life profiles are displacing plasma-derived coagulation factors in prophylactic hemophilia protocols.
Strategic Opportunities
- India's emerging reimbursement framework:Expanding health insurance penetration is creating addressable demand for albumin and immunoglobulin in tertiary care hospitals.
- Subcutaneous immunoglobulin delivery:Home-administration protocols are opening ambulatory care channels previously captive to hospital infusion centers.
- ISO 13485 quality convergence:Harmonized medical device quality standards are streamlining multi-jurisdictional product registration for fractionators seeking geographic diversification.
Industry Challenges
- Fractionation specialist talent scarcity:Bioprocess engineering expertise for plasma protein purification is concentrating at established manufacturing clusters, constraining new facility staffing.
- Prion reduction validation timelines:PMDA lot-release testing extensions are delaying product commercialization for Japanese market entrants.
- Legacy ERP integration:Cold-chain track-and-trace mandates are forcing expensive system overhauls at mid-scale collectors with dated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Plasma Derivatives Market |
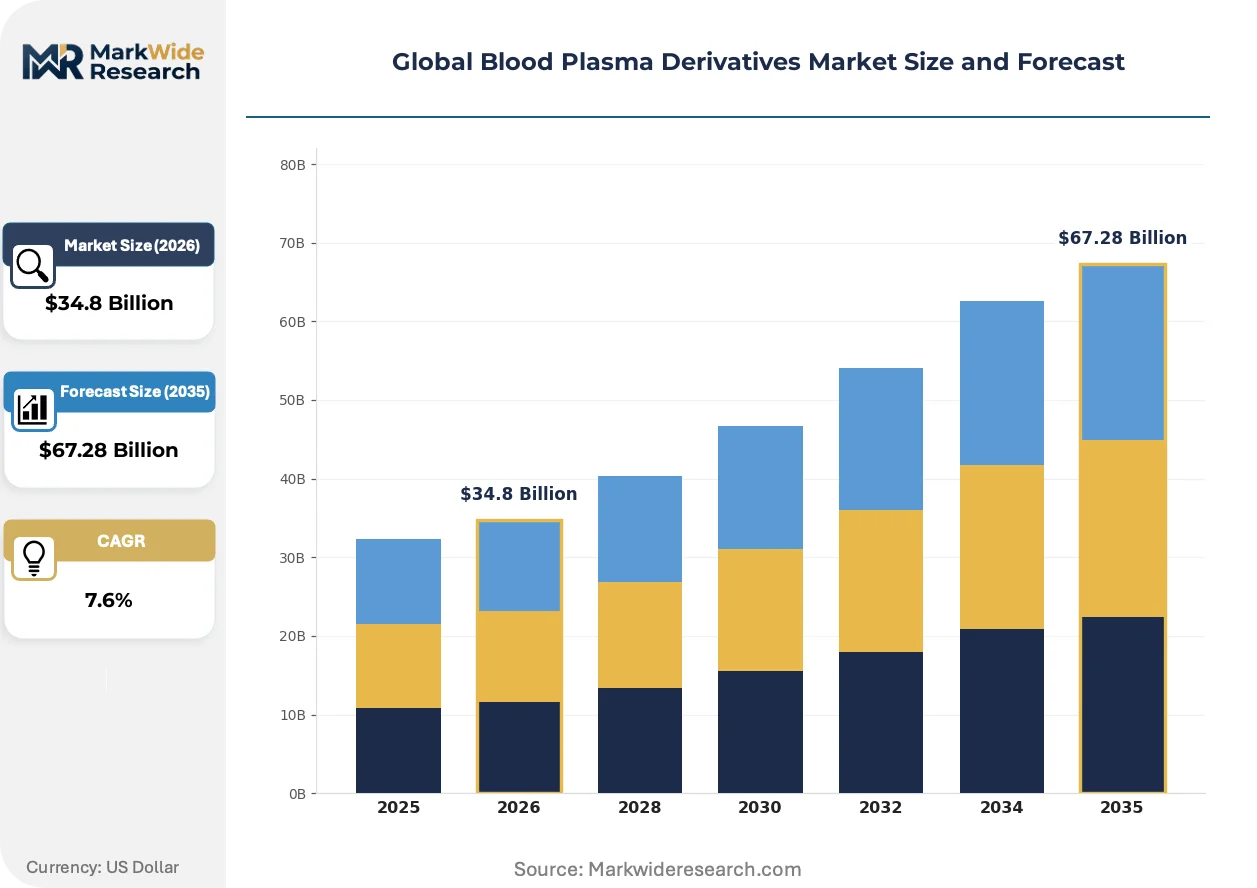
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $67.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulin, Albumin, Coagulation Factors, Fibrin Sealants, Protease Inhibitors, Others Application: Immunodeficiency Disorders, Surgical Hemostasis, Chronic Inflammatory Diseases, Burn Management, Liver Cirrhosis, Hemophilia Treatment End User: Specialty Clinics, Hematology Centers, Burn Units, Research Laboratories, Therapeutic Apheresis Centers, Blood Banks Technology: Chromatography, Precipitation, Filtration, Solvent Detergent, Freeze Drying, Nanofiltration |
| Companies Covered | CSL Limited, Grifols, Takeda Pharmaceutical Company Limited, Octapharma, Kedrion, Sanofi, Bayer, Bio Products Laboratory, LFB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Plasma Derivatives Market Shifts & Advancements
Continuous processing architectures are displacing batch fractionation, compressing production cycles and tightening viral safety windows through real-time monitoring integration.
Nanofiltration membranes with 15-20 nanometer pore ratings are hybridizing with traditional cold ethanol precipitation, enabling simultaneous pathogen removal and protein fractionation in single-unit operations. Hospital burn units and surgical centers are adopting these hybrid-process outputs for albumin and fibrin sealant applications where purity specifications exceed 99 percent. This convergence is compressing validation timelines while elevating capital intensity for retrofitting legacy precipitation trains.
EMA's centralized marketing authorization procedures are tightening post-market surveillance requirements for plasma-derived medicinal products, mandating periodic safety update reports and risk management systems. Fractionators are consolidating regulatory affairs functions in Amsterdam and London to manage centralized procedures efficiently. Specialty immunoglobulin portfolios face heightened pharmacovigilance scrutiny relative to established albumin products with longer safety records.
Consolidated purchasing by hospital network procurement alliances is compressing supplier rosters and demanding outcome guarantees for immunoglobulin therapy protocols. Integrated delivery networks in Germany and the United States are unbundling product supply from clinical pharmacy services, forcing fractionators to demonstrate total cost-of-therapy value. This behavioral shift is most pronounced in hemophilia treatment centers where prophylactic regimen adherence metrics determine contract renewal.
Global Blood Plasma Derivatives Market Segmentation
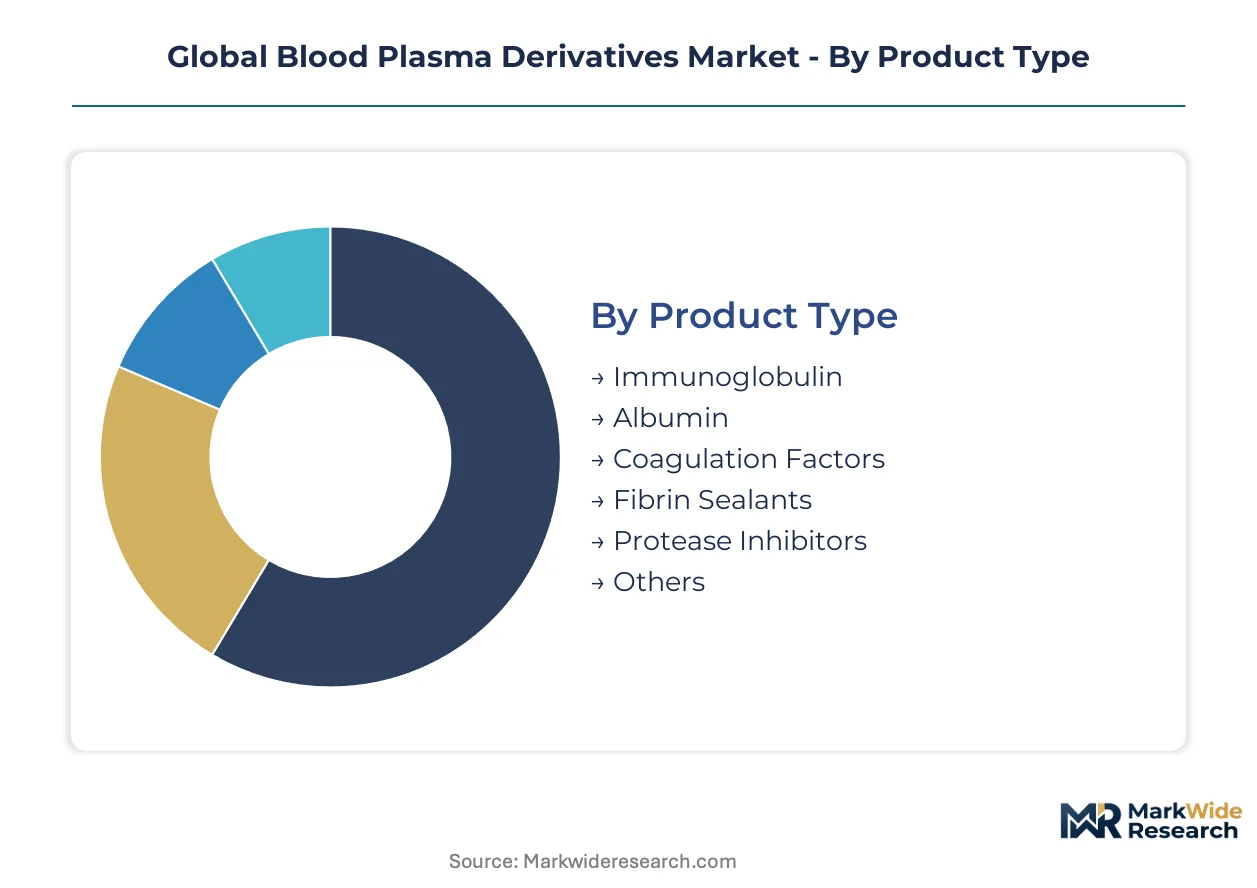
Segmentation in blood plasma derivatives reveals how clinical utility, manufacturing complexity, and reimbursement pathways concentrate value across distinct product and technology categories. Understanding these divides exposes where fractionators must defend margin structures against raw material volatility and regulatory escalation.
Product Type:
Mature immunoglobulin and albumin outputs dominate revenue concentration, while specialty coagulation factors and fibrin sealants represent emerging margin pools with steeper technical barriers.
- Immunoglobulin:Polyclonal antibody preparations exceeding 95 percent immunoglobulin G purity serve primary and secondary immunodeficiency protocols through intravenous and subcutaneous delivery. Demand concentrates in the United States and Japan where aging populations sustain prophylactic regimens through established reimbursement. PMDA lot-release testing and FDA viral inactivation mandates elevate entry costs for new fractionators.
- Albumin:Human serum albumin at 96-98 percent purity provides volume expansion in surgical and burn management settings where crystalloid alternatives prove insufficient. Hospital procurement committees in Germany and the United States standardize albumin protocols for hypovolemic shock and hypoalbuminemia, though biosimilar pressure is compressing pricing power in European tenders.
- Coagulation Factors:Plasma-derived factor VIII and IX concentrates address hemophilia A and B prophylaxis.
- Fibrin Sealants:Topical hemostatic preparations combining fibrinogen and thrombin for surgical adhesion.
- Protease Inhibitors:Alpha-1 antitrypsin and C1 esterase inhibitor concentrates for hereditary angioedema and emphysema.
- Others:Specialized plasma proteins including antithrombin and factor XIII for niche coagulopathies.
Immunoglobulin handles the majority of throughput; coagulation factors are gaining share fastest as extended half-life formulations displace recombinant alternatives in selected protocols.
Application:
Volume concentration tracks chronic disease prevalence and acute care protocol standardization, with cost tier differentiation separating prophylactic immunodeficiency therapy from episodic surgical applications.
- Immunodeficiency Disorders:Primary immunodeficiency and secondary hypogammaglobulinemia from hematologic malignancies drive sustained immunoglobulin consumption. Japanese and German tertiary centers maintain the highest per-capita utilization rates for prophylactic replacement therapy.
- Hemophilia Treatment:Prophylactic factor replacement regimens require high-purity concentrates with documented viral safety profiles. Hemophilia treatment centers in the United States and Germany are unbundling product supply from pharmacy services, demanding adherence metrics for contract renewal.
- Surgical Hemostasis:Intraoperative bleeding control using fibrin sealants and factor concentrates.
- Chronic Inflammatory Diseases:Off-label immunoglobulin use in neurological autoimmune conditions.
- Burn Management:Albumin resuscitation protocols for extensive thermal injury.
- Liver Cirrhosis:Albumin replacement in hepatorenal syndrome and large-volume paracentesis.
Immunodeficiency disorders absorb the largest share of immunoglobulin volume; hemophilia treatment is expanding most quickly as prophylaxis penetration deepens in previously undertreated populations.
End User:
Customer type segmentation reflects site-of-care migration, with hospital-based infusion giving way to ambulatory and home administration channels that alter cold-chain and service economics.
- Hematology Centers:Dedicated hemophilia treatment centers coordinate comprehensive care including factor dispensing, inhibitor monitoring, and physical therapy. German and United States centers are consolidating purchasing through network alliances that compress supplier rosters.
- Specialty Clinics:Outpatient immunology and rheumatology practices administer subcutaneous immunoglobulin in ambulatory settings. Home infusion nursing services in the United States are capturing volume from hospital outpatient departments as reimbursement shifts favor lower-acuity sites.
- Burn Units:Surgical critical care departments with standardized albumin resuscitation protocols.
- Therapeutic Apheresis Centers:Facilities performing plasma exchange for neurological and renal indications.
- Research Laboratories:Academic and commercial R&D consuming specialized plasma fractions.
- Blood Banks:Hospital-based transfusion services with limited derivative preparation capacity.
Hematology centers command the highest per-site revenue concentration; specialty clinics are climbing the fastest as subcutaneous delivery protocols expand addressable geography.
Technology:
Manufacturing method segmentation tracks capital intensity and yield optimization, with legacy precipitation methods yielding to chromatographic and membrane-based purification that tightens viral safety windows.
- Chromatography:Ion exchange and affinity resin systems achieve immunoglobulin purity above 95 percent while enabling coagulation factor separation with specific activity metrics. CSL Limited and Grifols have retrofitted legacy facilities with continuous chromatography trains that compress cycle times.
- Nanofiltration:15-20 nanometer pore membranes remove enveloped and non-enveloped viruses while retaining therapeutic proteins. Japanese PMDA validation requirements for prion reduction are accelerating nanofiltration adoption as a dual-purpose pathogen removal and protein concentration step.
- Precipitation:Cold ethanol fractionation remains the baseline method for primary protein separation.
- Filtration:Depth and membrane filtration for clarification and bioburden reduction.
- Solvent Detergent:Viral inactivation for enveloped pathogens in coagulation factor preparations.
- Freeze Drying:Lyophilization for product stability and cold-chain flexibility.
Chromatography handles the majority of high-value fractionation throughput; nanofiltration is seeing the steepest capacity expansion as regulators tighten pathogen safety expectations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. Japanese patients receive immunoglobulin primarily through hospital infusion centers, while German and United States channels increasingly shift toward home-based subcutaneous administration. This site-of-care migration alters cold-chain logistics requirements and service economics for fractionators.
United States
Hospital burn units and hemophilia treatment centers sustain albumin and coagulation factor demand through standardized critical care protocols. FDA plasma collection standards enforce stringent viral inactivation requirements that validate product safety for institutional procurement committees. The Southeast and Midwest harbor dense networks of plasma collection centers where donor loyalty programs compete for source material access.
Germany
Aging populations with chronic immunodeficiency conditions drive prophylactic immunoglobulin regimens through established statutory health insurance reimbursement. EMA centralized marketing authorization procedures and F-Gas Regulation constraints elevate cold-chain infrastructure capital requirements for fractionation facilities. The Frankfurt-Rhine-Main corridor hosts consolidated regulatory affairs functions managing centralized European procedures.
Japan
Elderly demographics with primary immunodeficiency sustain per-capita immunoglobulin utilization rates exceeding Western benchmarks. PMDA enforces stringent lot-release testing and prion reduction validation timelines that limit import velocity and privilege domestic fractionation partnerships. The Kanto region around Tokyo concentrates hemophilia treatment centers and specialized infusion facilities.
India
Expanding health insurance penetration creates addressable demand for albumin and immunoglobulin in tertiary care hospitals treating trauma and burn cases. The national pharmaceutical regulator enforces evolving quality standards for plasma-derived medicinal products entering commercial distribution. Maharashtra and Karnataka host emerging fractionation partnerships targeting domestic production capacity.
Brazil
Hemophilia treatment centers and surgical burn units drive coagulation factor and albumin consumption through public health system procurement channels. ANVISA oversees marketing authorization and post-market surveillance for imported plasma derivatives serving patient populations. São Paulo and Rio de Janeiro concentrate hospital pharmacy services and specialized transfusion medicine infrastructure.
Global Blood Plasma Derivatives Market Competitive Landscape
Capability concentration sits with established fractionators possessing validated viral inactivation expertise; scale advantage sits with collectors commanding dense donor center footprints across multiple geographies. The market structure tilts toward vertical integration, with plasma collection economics and fractionation throughput determining competitive position. Three archetypes dominate: integrated plasma collector-fractionators, specialty immunology-focused biopharmaceuticals, and regional fractionation service providers. Consolidation through controlled plasma supply chain acquisitions and continuous processing technology licensing represent the dominant competitive moves.
Among integrated collector-fractionators, CSL Limited and Grifols exemplify the scale-driven archetype, occupying positions anchored in United States and European donor center networks. Takeda Pharmaceutical Company Limited represents the specialty immunology tier, with positioning concentrated in concentrated hemophilia therapy expertise. These three entities collectively illustrate how vertical control over plasma supply and fractionation output separates market tiers.
| Leading Market Players |
|---|
| CSL Limited |
| Grifols |
| Takeda Pharmaceutical Company Limited |
| Octapharma |
| Kedrion |
| Sanofi |
| Bayer |
| Bio Products Laboratory |
| LFB Group |
| Others |
Supply & Pricing Matrix
Trans-Atlantic refrigerated freight corridors connecting United States collection centers to European fractionation hubs impose cost dynamics that concentrate supply-side power among integrated collector-fractionators while stratifying downstream pricing across premium-certified and standard-grade product tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between hospital networks and established fractionators, insulating volume commitments against spot-market volatility in raw plasma pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated viral-inactivated outputs from EMA-compliant tier and emerging-market standard grades. Cost compression in the economy tier is intensifying because biosimilar albumin pressure and tender consolidation in European procurement alliances. Hemophilia treatment centers exhibit the least price sensitivity due to prophylactic regimen adherence requirements, while burn units in emerging markets demonstrate acute price elasticity.
Supply Chain Analysis
Contract manufacturing concentration for fractionation capacity sits with CSL Limited, Grifols, and Takeda Pharmaceutical Company Limited, which collectively command the majority of validated viral inactivation throughput. Geographic supply concentration spans the United States, Germany, and Japan, where PMDA lot-release testing and FDA collection standards enforce quality differentiation. Raw material dependencies center on paid plasma donor volumes, specialized chromatography resins, and nanofiltration membrane assemblies. Single-source vulnerability concentrates in 15-20 nanometer pore-rated nanofiltration membranes qualified for prion reduction. Distribution runs through hospital pharmacy services and specialized hemophilia treatment centers with cold-chain validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates substantial switching costs for hospital procurement committees validated to specific fractionator viral safety profiles.
For Market Incumbents: Harden plasma collection network density in the United States Southeast and Midwest through loyalty program investments that preempt donor poaching by emerging competitors. Deepen captive supply of source plasma through controlled donor center acquisitions in Germany's Frankfurt-Rhine-Main corridor, insulating throughput against EMA F-Gas Regulation compliance cost inflation. For New Entrants and Emerging Players: Establish a beachhead in India's expanding tertiary care hospital segment where evolving CDSCO quality standards create a narrow accreditation window for first-movers with validated cold-chain infrastructure. Target subcutaneous immunoglobulin delivery protocols as the most penetrable application, leveraging home-infusion nursing partnerships to bypass entrenched hospital infusion center relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates seeking to divest non-core plasma fractionation assets amid portfolio rationalization pressures. Mid-term viability hinges on regulatory validation moats deepening rather than eroding across the analysis window. Monitor PMDA lot-release testing timeline extensions as the critical signal for Japanese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Technology Licensing | Compresses viral safety windows while elevating immunoglobulin yields above 95 percent purity thresholds for CSL Limited and Grifols retrofit programs. |
| Plasma Collection Network Expansion | Dense donor center footprints in Southern Europe and North America anchor Grifols' raw material access against compensation cost inflation. |
| Subcutaneous Delivery Protocol Development | Home-administration channels open ambulatory care geography previously captive to hospital infusion centers in United States specialty clinics. |
| Prion Reduction Validation Investment | PMDA-compliant nanofiltration capacity secures Japanese market entry against stringent lot-release testing timelines for domestic fractionation partnerships. |
| Integrated Delivery Network Partnership | Unbundled product supply from pharmacy services at German and United States hemophilia treatment centers demands adherence metrics for contract renewal. |
Research Methodology
Desk research of FDA plasma collection guidance documents, EMA centralized marketing authorization procedures, and PMDA lot-release testing protocols preceded structured interviews with fractionation operations directors, hospital pharmacy procurement managers, hemophilia treatment center coordinators, and plasma donor center network planners. Secondary validation drew from customs trade data for plasma-derived medicinal products, SEC 10-K filings of publicly traded fractionators, and hospital procurement database extracts. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and technology segmentation dimensions.
Assumptions held fixed include prevailing FDA viral inactivation standards, EMA F-Gas Regulation refrigerant phase-down timelines, and PMDA prion reduction validation requirements; variables tested included plasma donor availability elasticity, recombinant factor concentrate substitution rates, and subcutaneous immunoglobulin penetration trajectories. CAGRs were derived from segmented volume projections weighted by purity-adjusted pricing tiers across the analysis window. Forecast inputs incorporated fractionation capacity utilization rates, cold-chain infrastructure capital deployment schedules, and chronic immunodeficiency prevalence demographics.
Sensitivities concentrate around plasma donor recruitment cost inflation, nucleic acid testing mandate expansion, and recombinant coagulation factor half-life extension breakthroughs. Forecasts reflect documented assumptions subject to revision upon regulatory divergence in pathogen safety validation. Quarterly review of PMDA lot-release testing queue lengths, EMA periodic safety update report filings, and hospital network procurement alliance contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Oncology Small Molecule Drugs Market