
 Mexican Intraocular Lens Market | 2026-2036
Mexican Intraocular Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Mexican Intraocular Lens Market Foresight
Leasing arrangements for femtosecond laser platforms and phacoemulsification systems is reshaping how independent eye clinics and smaller ambulatory surgery centers access advanced surgical infrastructure without full capital outlay. Alcon leverages its integrated phaco-IOL workflow to sustain premium positioning across Mexico's tier-one hospital networks. STAAR Surgical differentiates through its proprietary collagen copolymer material and EVO Visian implantable collamer lens portfolio. Johnson & Johnson Vision anchors volume share through broad hydrophobic acrylic monofocal distribution via established distributor relationships.
An intraocular lens is a biocompatible optical implant, typically measuring 5.5–6.5 mm in optic diameter with haptic designs enabling in-the-bag fixation, manufactured through precision lathing or molding of acrylic, silicone, or polymethyl methacrylate materials to restore refractive power after natural lens extraction. Monofocal lenses dominate procedure volumes in Mexico's public sector contracts, though toric variants command margin premiums in private settings where astigmatism correction drives out-of-pocket willingness. Hydrophobic acrylic materials lead value capture due to posterior capsular opacification resistance and controlled unfolding characteristics that reduce surgical variability.
COFEPRIS maintains mandatory registration for all imported and domestically distributed intraocular lenses under Mexico's medical device regulations, while Secretaría de Salud procurement frameworks shape public hospital purchasing cycles and tender participation requirements. Compliance with ISO 11979 biocompatibility and mechanical testing standards remains essential for market authorization, and alignment with NOM-240 standards for health technology assessment influences reimbursement eligibility in social security institutions. Stakeholders must monitor evolving COFEPRIS equivalency agreements with FDA and Health Canada that could streamline approval pathways for multinational manufacturers.
Market Dynamics
Leasing models for femtosecond laser and phacoemulsification systems are redistributing capital requirements across Mexico's ophthalmology provider base, enabling independent clinics to compete with hospital networks without full equipment ownership.
Growth Catalysts
- Aging Demographics:Mexico's expanding population over 60 years drives cataract surgery volumes through public hospital systems in Mexico City and Jalisco.
- COFEPRIS Modernization:Streamlined medical device registration timelines accelerate product authorization for imported intraocular lenses.
- Hydrophobic Acrylic Superiority:Posterior capsular opacification resistance in advanced materials commands preference in private surgical settings.
Market Restraints
- Import Dependency:Domestic manufacturing absence concentrates supply risk on foreign production facilities and currency fluctuation exposure.
- Public Sector Procurement Rigidity:Secretaría de Salud tender frameworks impose extended purchasing cycles that delay technology adoption.
- Monofocal Reimbursement Ceiling:Social security institution payment caps for standard lenses compress margin realization in volume segments.
Strategic Opportunities
- Guadalajara Cluster Expansion:Jalisco's specialized ophthalmology hub attracts medical tourism from Central America seeking premium refractive solutions.
- Toric Segment Penetration:Astigmatism-correcting variants capture out-of-pocket willingness in private practice settings.
- ISO 11979 Alignment:Biocompatibility certification streamlines COFEPRIS equivalency pathways for multinational manufacturers.
Industry Challenges
- Surgeon Training Bottlenecks:Premium lens implantation techniques require specialized fellowship programs concentrated in Mexico City academic centers.
- Distributor Consolidation Pressure:Established channel relationships limit market access for novel entrants without proven Mexican logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexican Intraocular Lens Market |
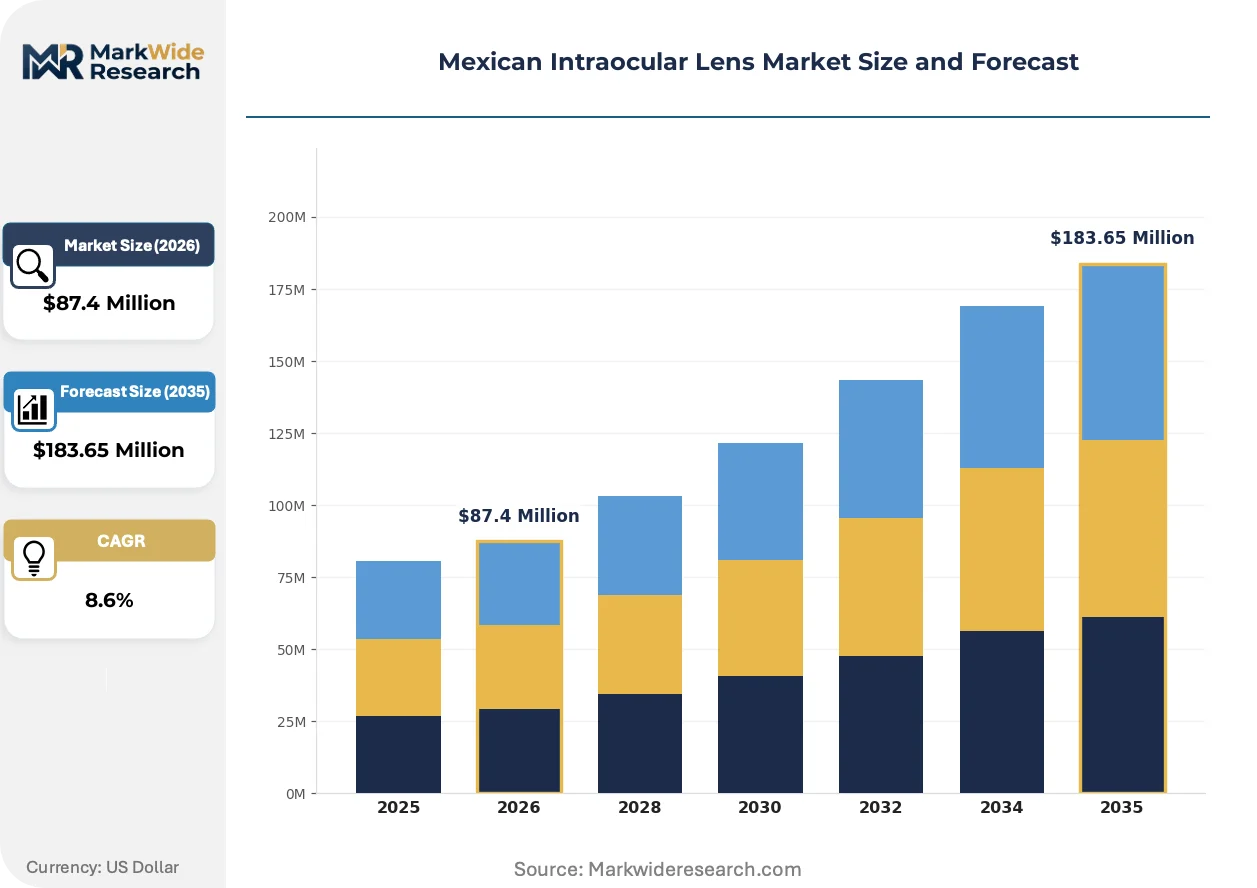
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Accommodative End User: Hospitals, Eye Clinics, Ambulatory Surgery Centers, Research Institutions Material: PMMA, Silicone, Hydrophilic Acrylic, Hydrophobic Acrylic Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Hoya Corporation, STAAR Surgical, Alcon, Lenstec, Rayner, Bausch & Lomb, Johnson & Johnson Vision, PhysIOL, Carl Zeiss Meditec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexican Intraocular Lens Market Shifts & Advancements
Digital surgical planning platforms and advanced material science are compressing procedural variability while expanding refractive precision capabilities across Mexico's tiered provider landscape.
Femtosecond laser-assisted cataract surgery is virtualizing manual incision and capsulotomy steps through computer-guided tissue interaction. Private ambulatory surgery centers in Mexico City adopt this platform through leasing arrangements rather than capital purchase. The technology is virtualizing traditional phacoemulsification workflows by reducing surgeon-dependent variability and enabling standardized outcomes across less experienced operators.
COFEPRIS equivalency agreements with FDA and Health Canada are compressing registration timelines for pre-approved devices. This regulatory convergence accelerates product launch velocity for multinational manufacturers. Premium hydrophobic acrylic and toric variants benefit most, as these categories face the highest technical documentation requirements under NOM-240 health technology assessment standards.
Out-of-pocket payment models are displacing traditional insurance-reimbursed channels for astigmatism-correcting and presbyopia-mitigating lenses. Affluent patient segments in Mexico City and Monterrey directly finance premium procedures outside social security frameworks. This behavioral shift concentrates margin capture in metropolitan private practice networks while public hospital systems remain anchored to monofocal volume contracts.
Mexican Intraocular Lens Market Segmentation
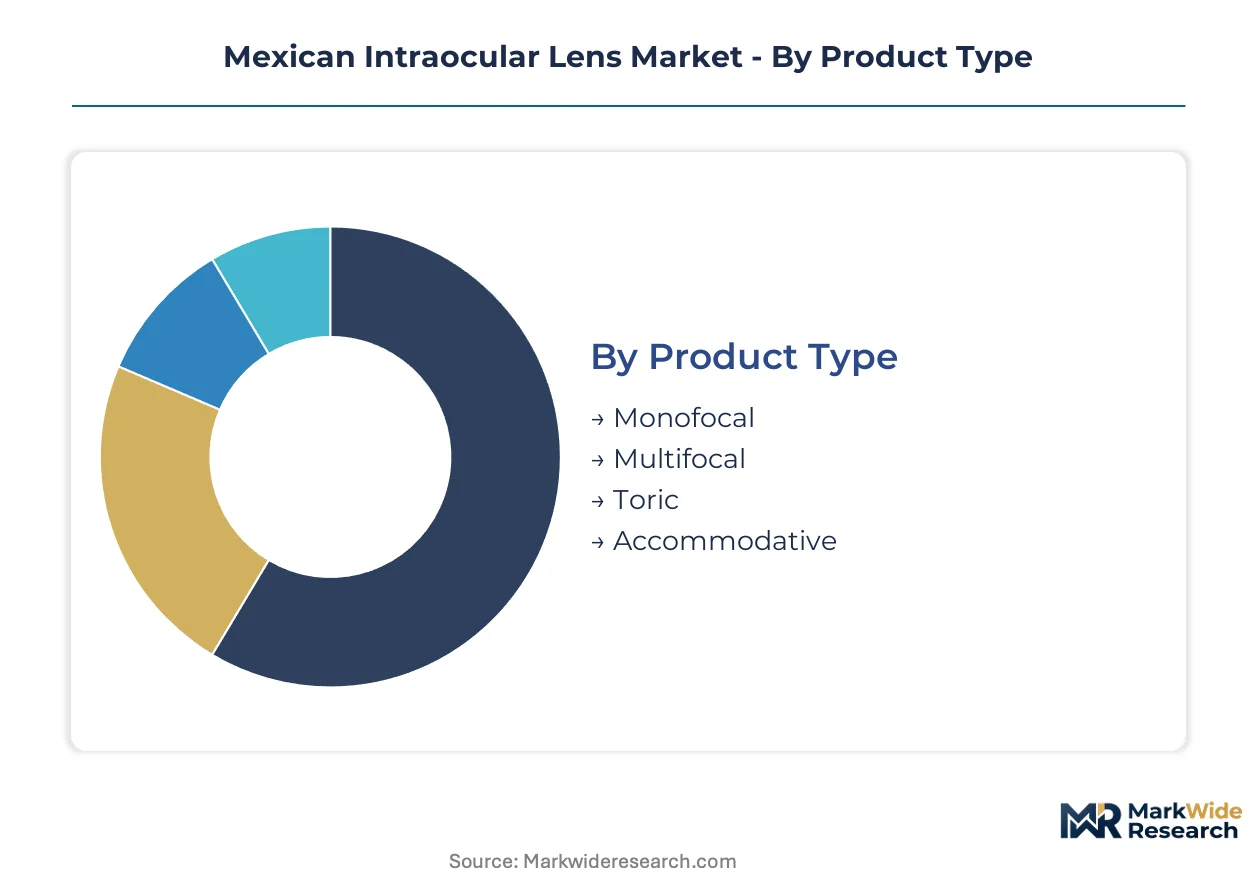
Segmentation in the Mexican intraocular lens market reveals distinct procurement patterns across public and private healthcare channels. Material composition and optical design determine reimbursement eligibility under COFEPRIS frameworks and Secretaría de Salud contracts.
Product Type:
Optical design complexity spans from basic vision restoration to advanced refractive correction, with reimbursement tiers separating public from private channel economics.
- Monofocal:Single-focus optics manufactured from hydrophobic acrylic or PMMA materials dominate Secretaría de Salud procurement tenders. Public hospital systems in Mexico City and Jalisco anchor volume demand through standardized monofocal contracts that prioritize unit cost over refractive precision.
- Toric:Cylindrical power correction for pre-existing astigmatism commands out-of-pocket premiums in Monterrey and Guadalajara private practices. Affluent patient segments finance these variants outside social security reimbursement frameworks, concentrating margin capture in metropolitan ambulatory surgery centers.
- Multifocal:Diffractive or refractive zone designs address presbyopia through simultaneous distance and near focus. Demand concentrates in medical tourism corridors serving Central American patients seeking premium refractive outcomes.
- Accommodative:Hinge-based designs attempt to restore dynamic focusing through ciliary muscle interaction. Limited surgeon training infrastructure in Mexico restricts adoption to academic medical centers with specialized fellowship programs.
The dominant share belongs to Monofocal, while Toric is closing the gap fastest.
End User:
Provider infrastructure determines technology access, with capital equipment ownership separating hospital networks from independent practice economics.
- Hospitals:Tertiary institutions in Mexico City and Jalisco maintain captive surgical volumes through integrated phacoemulsification platforms. IMSS and ISSSTE facilities anchor monofocal procurement under centralized tender frameworks.
- Eye Clinics:Specialized ophthalmology practices in Polanco, Santa Fe, and Monterrey's San Pedro Garza García concentrate premium lens demand. Leasing arrangements for femtosecond laser systems enable competitive positioning without full capital commitment.
- Ambulatory Surgery Centers:Outpatient facilities in Nuevo León and Puebla exploit regulatory flexibility for same-day cataract procedures. These centers capture migrating volume from congested public hospital waiting lists.
- Research Institutions:Academic medical centers conduct COFEPRIS-sanctioned clinical trials for novel IOL designs. UNAM and UANL ophthalmology departments generate surgeon training pipelines that shape regional adoption patterns.
Hospitals retain volume leadership, though Ambulatory Surgery Centers are expanding capacity most aggressively.
Material:
Biocompatibility profiles and mechanical handling characteristics differentiate material selection across surgical settings and reimbursement tiers.
- Hydrophobic Acrylic:Controlled unfolding dynamics and posterior capsular opacification resistance command preference in private surgical settings. The material's surface properties reduce inflammatory response, supporting premium positioning in out-of-pocket channels.
- Silicone:Lower refractive index and pliable insertion characteristics suit micro-incision techniques. Demand concentrates in high-volume public sector contracts where material cost efficiency outweighs long-term optical stability considerations.
- Hydrophilic Acrylic:Water-absorbing properties enable dehydrated insertion with in-situ expansion. The material occupies mid-tier pricing segments between premium hydrophobic variants and economy PMMA options.
- PMMA:Rigid polymethyl methacrylate designs require larger incision sizes that conflict with modern small-incision cataract surgery standards. Residual demand persists in rural public health clinics with limited equipment upgrade budgets.
Hydrophobic Acrylic commands value leadership, while Silicone maintains volume dominance in public procurement.
Distribution Channel:
Logistics infrastructure and regulatory compliance capabilities separate channel participants in Mexico's import-dependent supply structure.
- Distributors:Established Mexican medical device distributors with COFEPRIS import licenses and cold-chain capabilities control hospital network access. These intermediaries manage currency hedging and inventory positioning for foreign manufacturers.
- Direct Sales:Multinational manufacturers deploy specialized ophthalmology sales teams for tier-one hospital system accounts. Direct relationships enable bundled phaco-IOL workflow pricing and surgeon training program integration.
- Wholesalers:Regional medical supply aggregators serve secondary cities and state-level health systems. Their fragmented footprint limits premium product penetration outside metropolitan clusters.
- Online Sales:Digital procurement platforms emerging for consumable ophthalmology supplies face regulatory constraints on implantable device traceability. COFEPRIS serialization requirements currently restrict online channel development for IOLs specifically.
Distributors anchor channel control, though Direct Sales is gaining share among premium manufacturers seeking hospital network integration.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's intraocular lens supply depends entirely on imported finished devices, with no domestic manufacturing base. Currency exposure and foreign production concentration shape procurement risk across the country's fragmented healthcare infrastructure.
Mexico City Metro
The capital's tertiary hospital networks anchor national cataract surgery volumes through IMSS and ISSSTE facilities. COFEPRIS headquarters proximity accelerates regulatory submissions for multinational manufacturers seeking market authorization. Polanco and Santa Fe ophthalmology clusters concentrate premium lens demand from affluent out-of-pocket patients.
Jalisco
Guadalajara's specialized ophthalmology hub attracts Central American medical tourism seeking premium refractive outcomes. The state's public hospital system maintains high-volume monofocal contracts under Secretaría de Salud procurement frameworks. UANL academic medical centers generate surgeon training pipelines that shape regional adoption patterns.
Nuevo León
Monterrey's San Pedro Garza García district concentrates private ambulatory surgery center capacity for same-day cataract procedures. Out-of-pocket payment models dominate astigmatism-correcting lens demand outside social security reimbursement. Leasing arrangements for femtosecond laser systems enable independent clinic competition with hospital networks.
Bajío Region
Querétaro and Guanajuato manufacturing corridors lack IOL production but host medical device distribution infrastructure serving central Mexico. State health systems participate in consolidated Secretaría de Salud tenders that prioritize unit cost over refractive precision. Rural clinics in this zone maintain residual PMMA lens demand due to limited equipment upgrade budgets.
Northern Border States
Baja California and Chihuahua ophthalmology practices serve cross-border patient flows from California and Texas seeking cost-advantaged surgical procedures. Currency differentials between peso and dollar pricing create arbitrage opportunities for private providers. COFEPRIS-FDA equivalency discussions could streamline product registration for manufacturers with existing US approvals.
Mexican Intraocular Lens Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Mexican IOL market structures around three distinct competitive tiers: multinational ophthalmology conglomerates with integrated phaco-IOL workflows, mid-scale lens manufacturers with differentiated material portfolios, and regional distributors with COFEPRIS import licenses and hospital network relationships. Consolidation pressure concentrates among distributor channels, while product-level competition intensifies on hydrophobic acrylic formulations and toric design precision. Strategic moves center on surgeon training program expansion and bundled equipment-lens pricing for tier-one hospital accounts.
Among the integrated platform tier, Alcon, Johnson & Johnson Vision, and STAAR Surgical occupy positions that exemplify divergent specialization vectors. Alcon anchors system-level positioning through phacoemulsification platform dominance. Johnson & Johnson Vision represents volume-scale distribution through established Mexican distributor relationships. STAAR Surgical sits within the premium specialty niche through its proprietary collagen copolymer material science. These three entities collectively illustrate how multinational ophthalmology players segment the Mexican market across workflow integration, channel breadth, and material differentiation archetypes.
| Leading Market Players |
|---|
| Hoya Corporation |
| STAAR Surgical |
| Alcon |
| Lenstec |
| Rayner |
| Bausch & Lomb |
| Johnson & Johnson Vision |
| PhysIOL |
| Carl Zeiss Meditec |
| Others |
Supply & Pricing Matrix
Overcapacity in hydrophobic acrylic lens manufacturing across US and European production facilities is compressing supplier margins while enabling aggressive pricing postures for Mexican distributor negotiations. This utilization dynamic concentrates pricing power among multinational manufacturers with captive supply chains, forcing regional distributors to absorb currency hedging costs.
Pricing Analysis
Public hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels through Secretaría de Salud tender frameworks. Price differentiation hinges on ISO 11979 certification tier and volume scale commitments, with hydrophobic acrylic variants commanding premiums over silicone alternatives. Cost compression in monofocal segments is intensifying because IMSS and ISSSTE reimbursement ceilings compress margin realization. Private ambulatory surgery centers exhibit least price sensitivity, while state-level health systems in the Bajío region demonstrate highest elasticity.
Supply Chain Analysis
Contract manufacturing for intraocular lenses concentrates among Alcon's Fort Worth facility, Johnson & Johnson Vision's Jacksonville plant, and STAAR Surgical's Monrovia operations. Finished devices draw from acrylic polymer feedstock anchored in US and Japanese chemical production, with haptic component fabrication resting on Swiss precision machining. Single-source vulnerability permeates collagen copolymer material supply for EVO Visian lenses. Distribution runs through established Mexican medical device distributors with COFEPRIS import licenses and validated cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as out-of-pocket payment models displace traditional reimbursement channels, creating niche entry points for specialized lens manufacturers outside consolidated public procurement.
For Market Incumbents: Build workflow integration moats through bundled phacoemulsification-IOL platform offerings that lock tier-one hospital networks into captive consumable streams. Expand surgeon training fellowship programs at UNAM and UANL academic centers to entrench proprietary implantation techniques. Threat from femtosecond laser leasing models enabling independent clinic competition demands countermeasures through equipment financing partnerships. Capacity addition in Guadalajara distribution infrastructure reinforces channel control against emerging distributor consolidation. For New Entrants and Emerging Players: Mid-market toric lens demand in Monterrey and Guadalajara private practices represents the most penetrable entry point given limited incumbent specialization. Jalisco's medical tourism corridor serving Central American patients offers secondary white-space for premium multifocal variants. Go-to-market execution should prioritize direct surgeon engagement through specialized ophthalmology congress presence rather than distributor channel dependency. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ambulatory surgery center equipment leasing sub-segments, reducing barrier thresholds for clinic network expansion. Long-term viability favors acquisition targets with established COFEPRIS registration dossiers and proven Mexican logistics infrastructure rather than technology differentiation alone. Signal to monitor is Secretaría de Salud tender framework revisions that could accelerate or delay technology substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Equivalency Pathway Alignment | Streamlined FDA-Health Canada recognition accelerates product authorization timelines for imported devices. |
| Hospital System Partnership | IMSS and ISSSTE integrated contracts anchor volume share through centralized procurement frameworks. |
| Surgeon Training Program Expansion | UANL and UNAM fellowship pipelines shape regional adoption patterns for premium lens technologies. |
| Femtosecond Laser Leasing Arrangement | Equipment financing enables independent clinic competition without full capital ownership burdens. |
| Reimbursement Strategy Development | NOM-240 health technology assessment alignment determines social security institution payment eligibility. |
Research Methodology
A standing panel of cataract surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources encompassed COFEPRIS registration databases, Secretaría de Salud procurement records, IMSS formulary listings, and hospital supply chain disclosures. Bottom-up procedure volume modeling triangulated against top-down market value estimates derived from distributor import records and manufacturer revenue allocations.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning optical design complexity, material composition, end-user facility type, and regional procurement cluster. CAGRs emerged from fitted growth curves applied to cataract surgery incidence rates, aging demographic trajectories, and technology substitution elasticities. Forecast inputs incorporated COFEPRIS approval velocity assumptions and social security reimbursement policy stability parameters.
Practitioners should monitor COFEPRIS equivalency agreement expansions and Secretaría de Salud tender framework modifications for early signals of regulatory or procurement inflection. Forecasts embed assumptions regarding currency stability and import logistics continuity that material supply disruptions or peso volatility could revise. Quarterly review of hospital procurement database entries and distributor inventory positioning is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Global Concussion Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Artificial Disc Replacement Market