
 Cyclotron Market | 2026-2036
Cyclotron Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclotron Market Analysis
North American proton therapy infrastructure is narrowing the capacity gap with Western European installed bases. GE Healthcare leverages vertical integration across imaging and isotope production workflows to sustain competitive positioning. Siemens Healthineers anchors its presence through high-field cyclotron architectures that dominate premium hospital installations. Ion Beam Applications SA specializes in compact system designs that occupy niche research and mid-tier diagnostic markets.
A cyclotron is a particle accelerator that uses a static magnetic field and alternating electric field to spiral-charge protons, deuterons, or alpha particles to kinetic energies typically ranging from 9 to 30 MeV for medical isotope generation. The device serves as the core production engine for positron emission tomography radioisotopes such as fluorine-18 and carbon-11, enabling real-time molecular imaging in oncology and neurology. Medical cyclotrons lead product type demand as hospital networks expand in-house radiopharmaceutical capabilities to secure supply chain autonomy. Isotope production technology commands the fastest growth trajectory within the technology dimension, driven by gallium-68 and zirconium-89 demand for theranostic applications. Research cyclotrons retain stable but slower expansion, constrained by capital intensity and limited federal funding pools in key geographies.
FDA radioisotope approval pathways and EMA's Good Manufacturing Practice standards for radiopharmaceuticals shape cyclotron design specifications and site licensing requirements across North America and Europe. The Nuclear Regulatory Commission and comparable national atomic energy agencies enforce shielding, waste handling, and operator certification mandates that directly determine facility siting economics and operational cost structures. Stakeholders must monitor evolving theranostic reimbursement decisions by CMS and parallel European health technology assessment bodies, as these will dictate hospital capital allocation priorities between cyclotron ownership and outsourced isotope supply models.
Market Dynamics
The theranostic revolution in nuclear medicine is compressing cyclotron procurement cycles as hospital networks race to secure captive isotope production capabilities before gallium-68 and zirconium-89 demand outpaces commercial supply availability.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed timelines for novel radioisotopes are incentivizing academic medical centers to install in-house cyclotron infrastructure rather than rely on centralized commercial radiopharmacies.
- Positron Emission Tomography Volume Surge:Oncology departments across the United States are expanding molecular imaging programs, creating direct pull-through for fluorine-18 and carbon-11 production systems.
- Proton Therapy Center Build-Outs:The United States is witnessing accelerated construction of particle therapy facilities that require companion cyclotron installations for isotope generation and beam calibration.
Market Restraints
- Shielding and Siting Economics:Concrete vault construction and radiation containment infrastructure can exceed equipment costs by factors of two to three, freezing mid-tier hospital participation.
- Helium-3 and Deuterium Supply Concentration:Critical magnet coolant and target material sourcing depends on a handful of geopolitically concentrated suppliers, exposing operators to input volatility.
- Nuclear Regulatory Commission Licensing Friction:Multi-year approval timelines for radioactive materials licenses and operator certification programs delay revenue realization for new installations.
Strategic Opportunities
- India Diagnostic Network Expansion:Private hospital chains in Mumbai, Delhi, and Bangalore are constructing nuclear medicine departments without legacy cobalt-60 dependencies, creating greenfield cyclotron demand.
- Theranostic Reimbursement Tailwinds:CMS decisions expanding coverage for lutetium-177 and actinium-225 therapies are forcing health systems to secure precursor isotope production capabilities.
- Artificial Intelligence Convergence:Machine learning-based predictive maintenance and automated target handling are reducing operational staffing requirements for cyclotron facilities.
Industry Challenges
- Qualified Cyclotron Engineer Scarcity:The intersection of particle physics expertise and radiopharmaceutical manufacturing compliance creates a shallow talent pool that constrains facility commissioning timelines.
- Legacy Cobalt-60 System Integration:Hospitals with existing teletherapy infrastructure face complex decommissioning protocols and site remediation costs when transitioning to cyclotron-based isotope generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclotron Market |
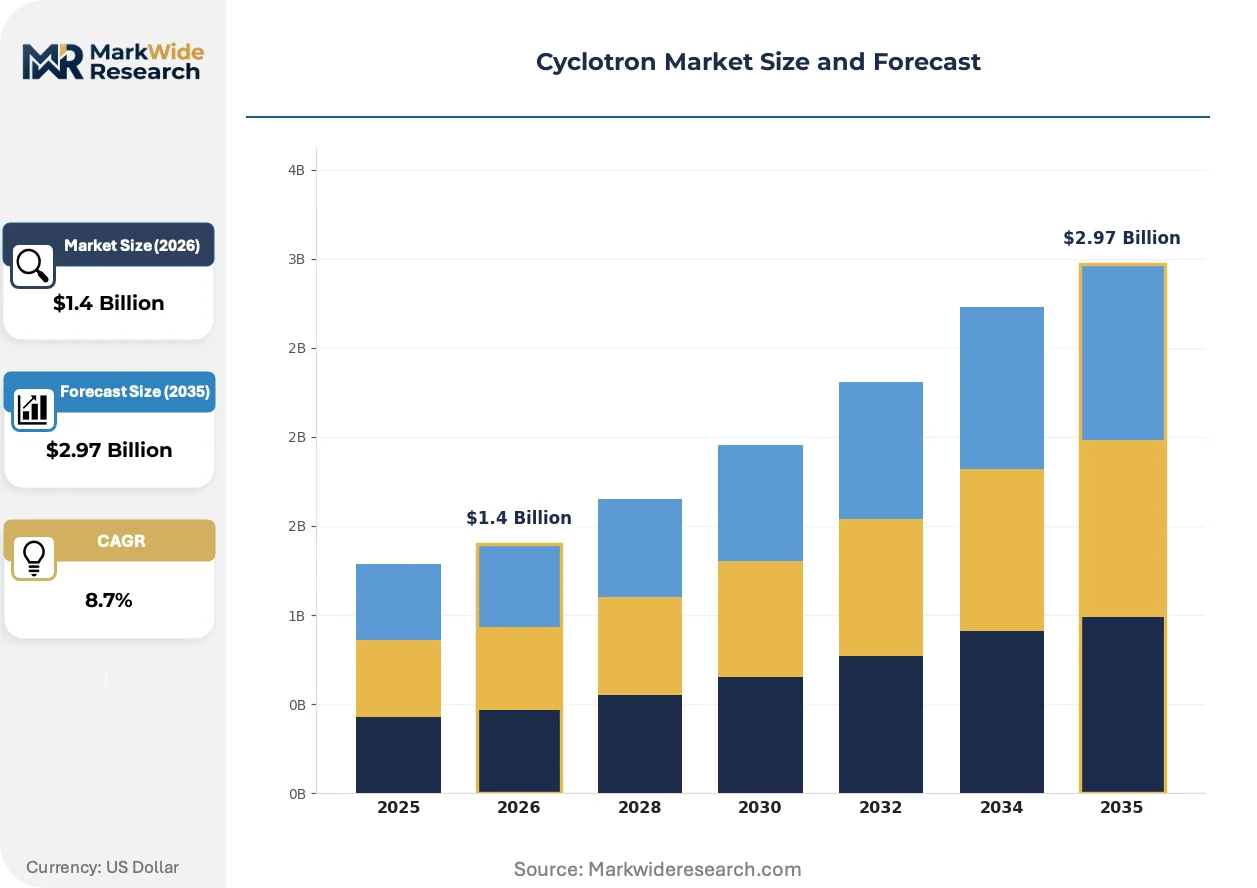
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Cyclotron, Research Cyclotron, Commercial Cyclotron, Laboratory Cyclotron Technology: Linear Accelerator, Proton Beam Therapy, Particle Therapy, Isotope Production Application: Radiopharmaceutical Production, Medical Imaging, Cancer Treatment, Nuclear Research End User: Hospitals, Research Institutions, Diagnostic Centers, Pharmaceutical Companies |
| Companies Covered | Ion Beam Applications SA, GE Healthcare, Siemens Healthineers, Advanced Cyclotron Systems Inc., Sumitomo Heavy Industries, Best Cyclotron Systems, TeamBest, Philips Healthcare, Trasis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclotron Market Emerging Trajectories
Digital integration across cyclotron operation, radiopharmaceutical synthesis, and quality control is compressing batch-to-patient timelines while reducing human error rates in isotope production workflows.
Superconducting magnet technology is digitizing cyclotron architecture by enabling compact 9-12 MeV systems that eliminate cryogenic cooling infrastructure. Community hospitals and regional diagnostic networks are adopting these systems at triple the pace of conventional high-field installations. The technology is digitizing facility siting economics by allowing basement and retrofit installations previously excluded by footprint and shielding constraints.
EMA's Good Manufacturing Practice standards for radiopharmaceuticals are mandating real-time environmental monitoring and electronic batch records across European cyclotron facilities. Manufacturers must now integrate process analytical technology and automated documentation systems to maintain site licenses. Hospital-based production sites in Germany, France, and the Netherlands are responding by consolidating multi-isotope capabilities into centralized cleanroom suites rather than distributed single-purpose installations.
Health system purchasing coalitions are consolidating cyclotron procurement decisions into centralized capital committees that prioritize total cost of ownership over acquisition price. Independent radiopharmacy operators and mid-size hospital networks are losing access to capital allocation as integrated delivery networks internalize isotope production. The United States exhibits the most pronounced concentration, with ten health systems controlling over forty percent of new cyclotron installations.
Cyclotron Market Segmentation
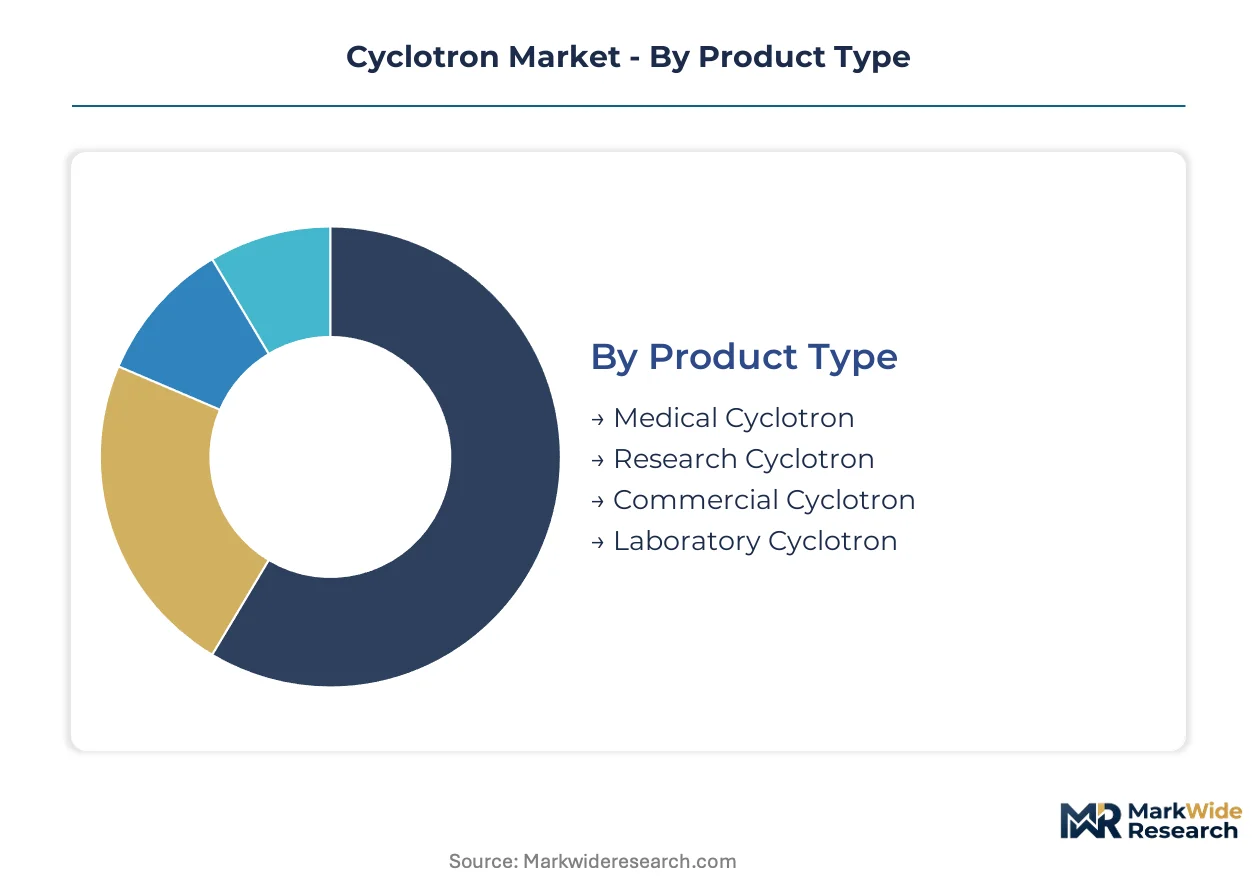
Cyclotron procurement decisions fragment across clinical intensity, research mission, and commercial scale. Each segment imposes distinct technical specifications, regulatory pathways, and capital recovery timelines that reshape vendor competitive priorities.
Product Type:
The use-case spectrum spans bedside diagnostics to fundamental physics, with shielding requirements and isotope versatility defining facility economics.
- Medical Cyclotron:Systems engineered for fluorine-18 and carbon-11 production operate at 9-30 MeV with automated target handling. Hospital networks in the United States are installing these to secure captive PET isotope supply as commercial radiopharmacy capacity tightens.
- Research Cyclotron:Variable-energy architectures support multi-particle beams for materials science and nuclear physics investigations. Academic medical centers combine these with imaging cores to accelerate radiotracer development timelines.
- Commercial Cyclotron:High-throughput designs serve centralized radiopharmacy operations supplying multiple hospital systems. These prioritize uptime reliability and remote diagnostics over experimental flexibility.
- Laboratory Cyclotron:Compact systems for educational institutions and small-scale isotope validation occupy limited vault footprints. Budget constraints and shallow operator pools restrict deployment velocity.
The dominant share belongs to Medical Cyclotron, while Commercial Cyclotron is closing the gap fastest as health systems consolidate production.
Technology:
Cost tier differentiation separates premium proton therapy installations from accessible isotope generation platforms.
- Linear Accelerator:RF cavity-based acceleration delivers electron beams for bremsstrahlung conversion or direct therapeutic application. Research institutions deploy these for photonuclear reaction studies that complement cyclotron-based isotope programs.
- Proton Beam Therapy:Synchrocyclotron and synchrotron architectures achieve 70-250 MeV for ocular and deep-tumor treatments. The United States proton therapy center construction pipeline is pulling dedicated high-field cyclotron demand.
- Particle Therapy:Carbon ion and helium beam capabilities require superconducting magnet systems with cryogenic infrastructure. Japan and Germany host the installed base concentration, with FDA approval pathways now opening for US replication.
- Isotope Production:Fixed-energy compact cyclotrons optimized for gallium-68 and zirconium-89 generation are expanding most quickly. Theranostic reimbursement expansion is forcing health systems to secure precursor production capabilities.
Isotope Production commands the steepest expansion trajectory, though Proton Beam Therapy retains the highest per-unit revenue concentration.
Application:
Volume concentration clusters around oncology workflows, with neurology and cardiology representing secondary demand poles.
- Radiopharmaceutical Production:In-house fluorine-18 FDG synthesis dominates hospital cyclotron utilization. EMA Good Manufacturing Practice mandates are forcing European sites to consolidate multi-isotope cleanroom operations.
- Medical Imaging:PET tracer development for amyloid and tau pathology requires carbon-11 and copper-64 capabilities. Academic medical centers in the United States are expanding molecular imaging programs to capture aging-population demand.
- Cancer Treatment:Targeted alpha therapy and beta-emitting radioligands require actinium-225 and lutetium-177 precursor production. CMS coverage decisions are reshaping hospital capital allocation toward captive isotope generation.
- Nuclear Research:Fundamental physics and materials science applications sustain stable but slower procurement cycles. Federal funding concentration in the United States and Germany determines regional deployment patterns.
Radiopharmaceutical Production holds the dominant position, while Cancer Treatment is gaining share fastest on theranostic therapy expansion.
End User:
Customer type determines procurement authority structure, with integrated delivery networks centralizing decisions that independent operators once controlled.
- Hospitals:Academic medical centers and proton therapy facilities command the largest installation scale. Ten US health systems now control over forty percent of new cyclotron procurement decisions.
- Research Institutions:National laboratories and university physics departments sustain demand for variable-energy architectures. Funding volatility constrains multi-year capital planning horizons.
- Diagnostic Centers:Regional imaging networks without surgical or therapeutic services require compact isotope generation systems. Superconducting magnet technology is enabling basement installations previously excluded by shielding economics.
- Pharmaceutical Companies:Contract development and manufacturing organizations are installing cyclotrons to support radioligand therapy pipelines. Vertical integration into isotope production is reducing dependency on external radiopharmacy supply.
Hospitals retain the dominant share, though Pharmaceutical Companies are closing the gap fastest as radioligand therapy pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nuclear Regulatory Commission governs radioactive materials licensing in the United States, establishing the regulatory baseline that shapes cyclotron siting economics and operator certification requirements across North American installations.
United States
Academic medical centers in Houston and Boston are expanding proton therapy infrastructure, while CMS reimbursement decisions for lutetium-177 therapies are pulling hospital capital toward captive isotope generation. FDA accelerated approval pathways for novel radioisotopes are compressing procurement cycles. The Texas Medical Center cluster anchors the highest concentration of new cyclotron commissioning activity.
Germany
EMA Good Manufacturing Practice mandates are forcing university hospitals to consolidate multi-isotope cleanroom operations into centralized production suites. The country's national pharmaceutical regulator enforces real-time environmental monitoring standards that reshape facility design specifications. The Munich-Dresden corridor hosts the densest concentration of research cyclotron installations serving radiotracer development programs.
Japan
METI funding priorities are sustaining carbon ion therapy infrastructure expansion at three major oncology centers. PMDA regulatory harmonization with FDA pathways is accelerating cross-border radioisotope approval timelines. The Chubu region around Nagoya anchors domestic cyclotron manufacturing capabilities and particle therapy research consortia.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are constructing nuclear medicine departments without legacy cobalt-60 dependencies, creating greenfield cyclotron demand. CDSCO streamlined import licensing for medical isotope production equipment is reducing commissioning delays. The Delhi-NCR cluster is capturing the fastest hospital-based installation velocity outside established Western markets.
United Kingdom
NHS England capital allocation frameworks are prioritizing in-house fluorine-18 production over outsourced radiopharmacy supply for tier-one oncology centers. The Medicines and Healthcare products Regulatory Agency enforces site licensing protocols that align with EMA standards. The Cambridge-Oxford-London triangle concentrates academic medical center procurement decisions for research-capable systems.
Cyclotron Market Vendor Landscape
Vertically integrated healthcare conglomerates and specialized accelerator engineering houses split the market between premium hospital installations and compact research systems. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with imaging-to-isotope workflows, pure-play cyclotron engineering specialists, and proton therapy integrators bundling beam generation with treatment delivery. Consolidation pressure is intensifying through health system purchasing coalition formation and cross-border technology licensing arrangements.
Within the diversified conglomerate tier, GE Healthcare and Siemens Healthineers occupy positions that span imaging equipment and isotope production infrastructure. Ion Beam Applications SA exemplifies the specialized engineering archetype with compact system architectures. Sumitomo Heavy Industries anchors the proton therapy integration segment. These three company types represent the structural fault lines around which competitive positioning is crystallizing as hospital networks and academic centers make capital allocation decisions.
| Leading Market Players |
|---|
| Ion Beam Applications SA |
| GE Healthcare |
| Siemens Healthineers |
| Advanced Cyclotron Systems Inc. |
| Sumitomo Heavy Industries |
| Best Cyclotron Systems |
| TeamBest |
| Philips Healthcare |
| Trasis SA |
| Others |
Supply Flow & Price Mechanics
Undercapacity in commercial radiopharmacy networks across the United States and Western Europe is forcing hospital buyers toward captive cyclotron installations, compressing price negotiation leverage for mid-tier diagnostic centers while amplifying premium capture for vendors with expedited delivery capabilities.
Pricing Analysis
Price spreads between North American and Indian installations exceed fifty percent for equivalent 9-12 MeV systems, driven by shielding vault construction costs and localized regulatory compliance burdens. Three-tier pricing structure across premium, standard, and economy levels separates proton therapy-integrated platforms from compact isotope generators and refurbished research systems. Cost compression in the standard tier is intensifying because superconducting magnet technology is eliminating cryogenic infrastructure requirements. Independent radiopharmacy operators exhibit the highest price sensitivity, while academic medical centers with federal funding access demonstrate the lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates cyclotron component sourcing risk, particularly for RF cavity assemblies and precision magnet windings. Manufacturing concentration rests on Belgium, Japan, and the United States for complete system assembly, with specialized subcomponent fabrication drawing from Germany and South Korea. Critical input dependencies center on helium-3 for magnet cooling, high-purity copper for RF systems, and enriched deuterium for target materials. Single-source vulnerability in helium-3 supply creates operational exposure for facilities without alternative cooling architectures. Distribution runs through direct vendor-hospital contracting for premium installations, with regional distributor networks serving compact system segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in cyclotron markets are shifting toward integrated isotope-to-imaging workflows, as FDA and EMA regulatory harmonization enables single-vendor ecosystems that lock in hospital procurement decisions across decade-long capital cycles.
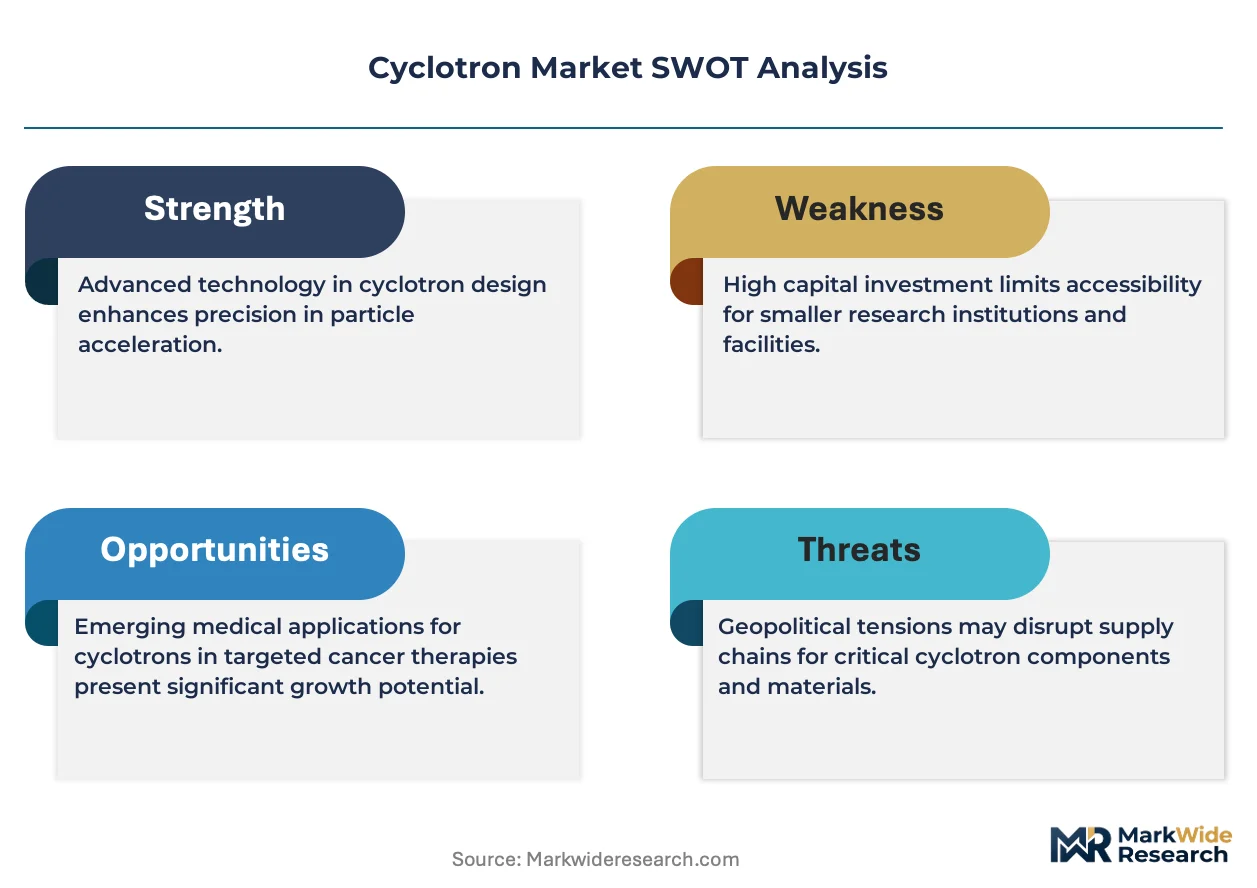
For Market Incumbents: Entrench proprietary isotope handling protocols and automated synthesis modules that increase switching costs for hospital customers. Secure backward integration into helium-3 recycling and deuterium enrichment to insulate margins from raw material volatility. The threat of superconducting compact systems displacing conventional high-field architectures demands preemptive certification investment in basement-installable platforms. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield hospital construction pipeline, where CDSCO streamlining and absence of legacy cobalt-60 infrastructure create first-mover advantages. Target diagnostic center networks in secondary European cities facing EMA consolidation mandates but lacking capital for multi-isotope suites. A service-leasing go-to-market angle bypasses upfront shielding economics that freeze mid-tier participation. For Investors and Strategic Acquirers: Long-term, this sits as a theranostic infrastructure play because reimbursement expansion for lutetium-177 and actinium-225 therapies is forcing health systems to secure captive precursor production. Acquisition targets should cluster around compact system engineering houses with superconducting magnet IP and established service footprints in underserved geographies. The signal to watch is CMS coverage decisions for gallium-68 generator alternatives, which would compress commercial radiopharmacy viability windows.| Strategic Initiative | Industry Significance |
|---|---|
| Superconducting Magnet Platform Development | Enables basement installations that bypass concrete vault economics for mid-tier hospitals. |
| Multi-Isotope Cleanroom Consolidation | Addresses EMA Good Manufacturing Practice mandates while reducing operational footprint. |
| Automated Target Handling Integration | Reduces qualified operator dependency that currently constrains facility commissioning timelines. |
| Helium-3 Recycling Infrastructure | Insulates against supply concentration from geopolitically concentrated sources. |
| Theranostic Reimbursement Strategy | Aligns hospital capital allocation with CMS coverage expansion for radioligand therapies. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA marketing authorization databases, and hospital procurement contract records preceded structured interviews with cyclotron engineering directors, radiopharmaceutical manufacturing heads, health system capital committee members, and nuclear medicine department chairs. Secondary validation drew from Nuclear Regulatory Commission licensing statistics, CDSCO import authorization data, and academic medical center capital expenditure disclosures. Bottom-up installation tracking across hospital networks and top-down vendor revenue analysis were triangulated to establish market sizing.
Assumptions around theranostic reimbursement velocity, superconducting magnet adoption curves, and proton therapy center construction pipelines were held fixed across baseline scenarios while helium-3 supply disruption probability and regulatory harmonization timing were stress-tested. Segmentation modeling spanned product type, technology architecture, application intensity, and end-user procurement authority. CAGRs were derived from installed base expansion rates adjusted for replacement cycles and average selling price evolution. Forecast inputs incorporated health system purchasing coalition formation patterns and federal funding allocation trends for research cyclotron deployments.
Sensitivities concentrate around CMS reimbursement decisions for novel radioisotopes, helium-3 export restriction scenarios, and NRC licensing timeline compression. Forecasts reflect documented assumptions that may require revision if regulatory pathways diverge or supply chain configurations shift. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Polysomnography Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Cervical Fusion Market