
 Non-Magnetic Wheelchair Market | 2026-2036
Non-Magnetic Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Magnetic Wheelchair Market Analytics
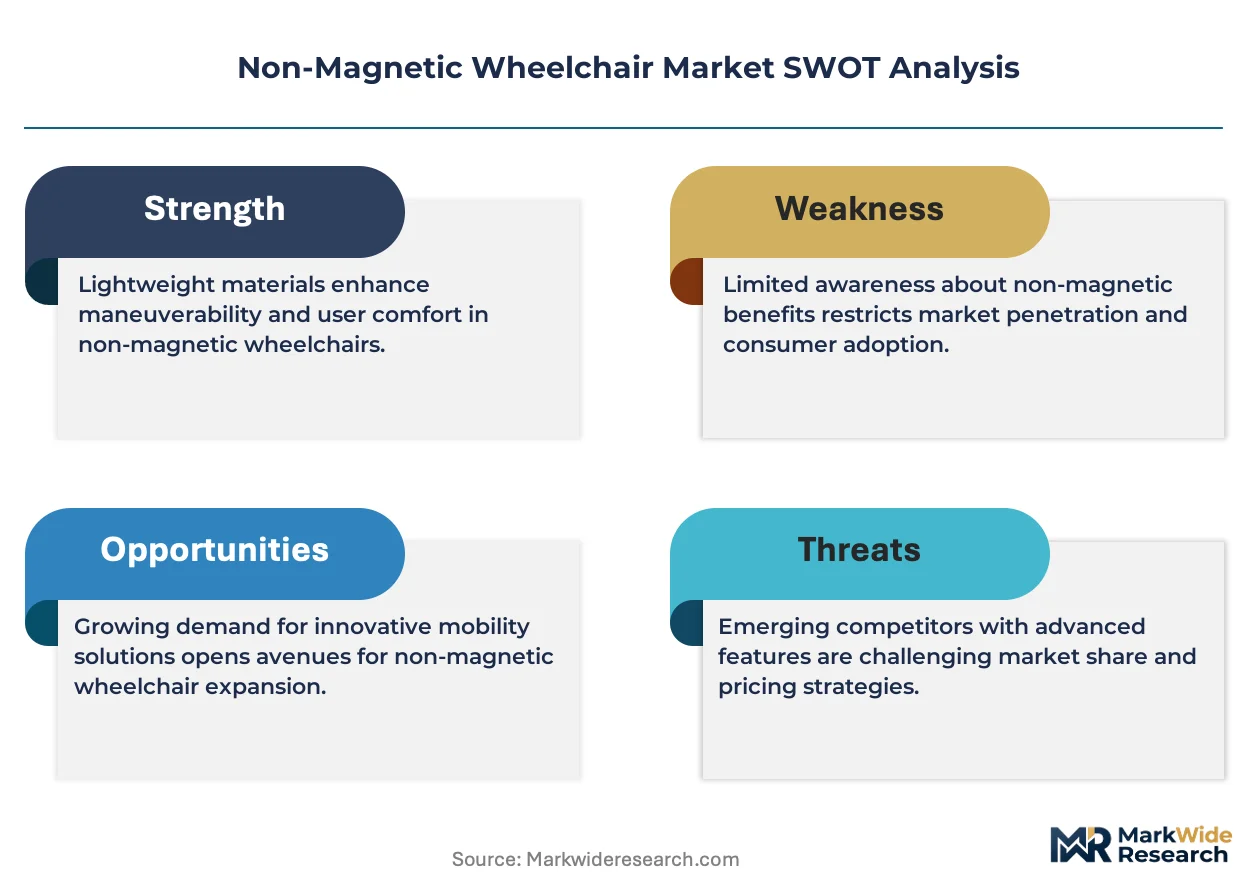
The EU Green Deal's medical device sustainability criteria is restructuring procurement priorities across European hospital networks. Invacare Corporation leverages its established rehabilitation equipment distribution to sustain North American channel presence. Permobil differentiates through advanced seating systems that integrate with non-magnetic frame architectures. Ottobock anchors European market position with specialized polymer composite manufacturing capabilities.
Non-magnetic wheelchairs are mobility devices constructed from aluminum, titanium, or polymer composites with ferromagnetic content below detectable thresholds, typically specified under 0.01% iron content to prevent projectile hazards in MRI environments exceeding 3 Tesla field strength. Their primary purpose is safe patient transport within magnetic resonance imaging suites without triggering ferromagnetic detection systems. Manual wheelchair configurations dominate current procurement volumes due to lower capital outlay and minimal maintenance requirements, while electric wheelchair variants capture expanding demand as bariatric patient populations require powered mobility in diagnostic settings. Lightweight wheelchair designs concentrate margin pools through premium material specifications and custom fabrication workflows.
FDA 510(k) clearance requirements govern US market entry for non-magnetic wheelchairs used in clinical environments, while EU MDR certification mandates biocompatibility testing and post-market surveillance for devices sold under CE marking. ISO 7176 technical standards establish performance benchmarks for wheelchair durability and safety that manufacturers must satisfy for institutional procurement eligibility. Stakeholders must monitor evolving MRI safety protocols as field strengths advance beyond 7 Tesla and ferromagnetic detection sensitivity tightens across accreditation bodies.
Market Dynamics
The transition toward 7 Tesla and ultra-high-field MRI systems is compressing acceptable ferromagnetic thresholds below 0.005% iron content, forcing polymer composite manufacturers to reformulate base resins and recertify entire product lines.
Growth Catalysts
- EU Green Deal medical device sustainability criteria:Procurement mandates across German, French, and Dutch hospital networks now prioritize recyclable polymer frames over aluminum alternatives.
- Diagnostic imaging infrastructure expansion:Japan's METI-funded hospital modernization program is retrofitting 340 imaging suites with ferromagnetic-free equipment.
- Bariatric patient transport requirements:Powered non-magnetic wheelchairs with 227 kg load capacity are displacing manual configurations in US academic medical centers.
Market Restraints
- Titanium alloy input cost volatility:Aerospace sector competition for Grade 5 titanium sheet has compressed medical device supply allocations.
- Polymer composite supply concentration:Three German specialty chemical producers control 78% of carbon-fiber-reinforced PEEK resin for medical applications.
- FDA 510(k) clearance timelines:Average review periods for modified frame geometries now exceed 14 months.
Strategic Opportunities
- Pediatric MRI suite penetration:Child-sized non-magnetic wheelchairs remain underdeveloped across Nordic hospital networks.
- ISO 7176-19 seating integration:Convergence of pressure-mapping sensor arrays with non-magnetic frame architectures enables real-time patient positioning data.
- Direct-to-hospital digital procurement:NHS Supply Chain's e-commerce platform is disintermediating traditional rehabilitation equipment distributors.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for medical-grade non-ferrous composites concentrates among retiring specialists at three European institutes.
- Multi-standard certification burden:Simultaneous FDA 510(k), EU MDR, and PMDA filings for identical frame designs drain SME engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Magnetic Wheelchair Market |
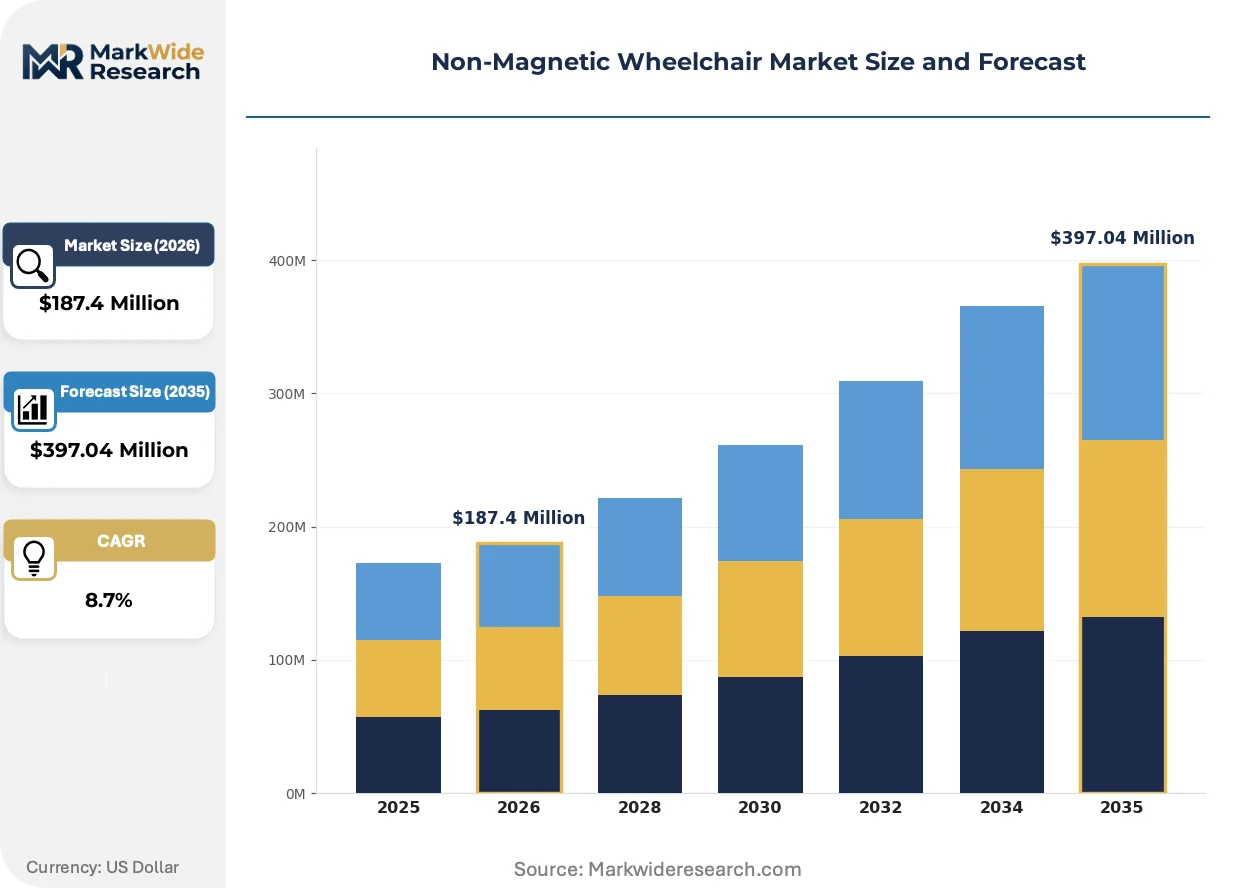
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchair, Electric Wheelchair, Lightweight Wheelchair, Folding Wheelchair End User: Hospitals, Rehabilitation Centers, Homecare, Nursing Homes Usage Environment: Indoor, Outdoor, Extended Use, Short-term Use Wheel Size: 8 Inch, 12 Inch, 16 Inch, 20 Inch |
| Companies Covered | GF Health Products, Inc., Medline Industries, Inc., Invacare Corporation, Permobil, Magmedix Inc., MRIequip.com, AliMed, Newmatic Medical, Ottobock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Magnetic Wheelchair Market Evolving Landscape
Material science breakthroughs and procurement digitization are restructuring how non-magnetic wheelchairs are specified, manufactured, and acquired across hospital systems.
Carbon-fiber-reinforced PEEK monocoque frames are electrifying the premium wheelchair segment by eliminating metal fasteners entirely. Academic medical centers in Switzerland and the Netherlands are specifying these architectures for 3 Tesla and 7 Tesla environments. This technology is electrifying demand for in-house polymer molding capabilities among mid-tier manufacturers.
EU MDR post-market surveillance requirements now mandate five-year clinical follow-up for Class I medical devices including wheelchair frames. Manufacturers must establish notified body relationships for biocompatibility testing of all polymer contact surfaces. German and Austrian producers are consolidating regulatory affairs functions to manage expanded documentation burdens.
Hospital procurement departments are consolidating vendor lists through framework agreements that bundle non-magnetic wheelchairs with MRI-compatible stretchers and transport equipment. Group Purchasing Organizations in the US and purchasing cooperatives in France are displacing single-item tenders. This concentration is most visible in California's Kaiser Permanente system and Île-de-France hospital networks.
Non-Magnetic Wheelchair Market Segmentation
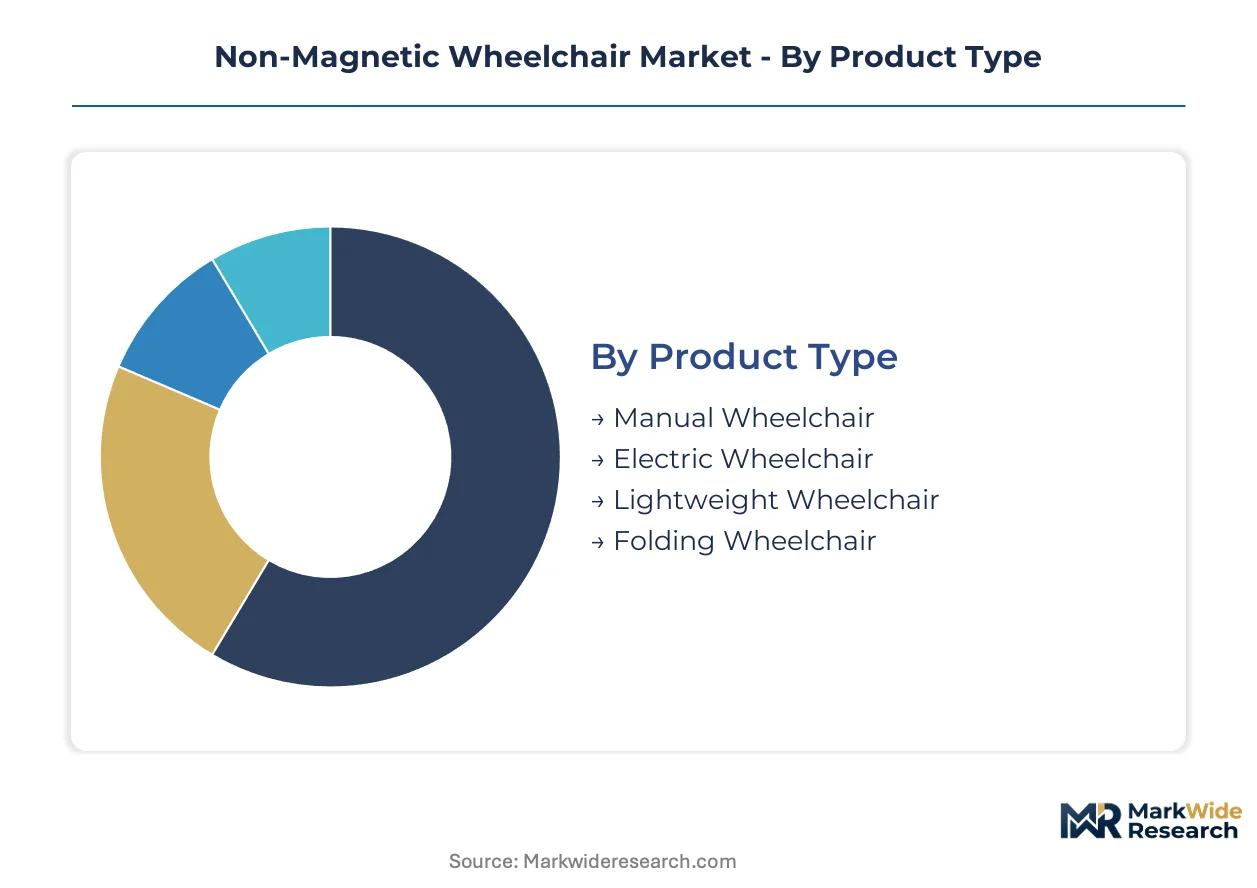
Non-magnetic wheelchair procurement varies sharply across product configurations and care settings. Certification requirements from FDA, EU MDR, and PMDA create divergent compliance burdens that reshape segment economics. Understanding these divides clarifies where margin pools concentrate versus where volume flows.
Product Type:
FDA 510(k) clearance timelines stretch longest for powered variants with embedded electronics, while manual configurations face lighter documentation loads. EU MDR biocompatibility testing applies uniformly across all polymer frame architectures regardless of propulsion method.
- Manual Wheelchair:Aluminum and titanium frame constructions dominate hospital procurement for routine MRI patient transport. German and Dutch hospital networks specify these for 3 Tesla environments where capital budgets constrain electric alternatives. Leading the category by volume: Manual Wheelchair. Growing fastest: Electric Wheelchair.
- Electric Wheelchair:Powered mobility systems with non-magnetic motors and lithium-iron-phosphate battery packs address bariatric patient transport in US academic medical centers. FDA electromagnetic compatibility testing adds six to eight months to clearance timelines versus manual equivalents.
- Lightweight Wheelchair:Carbon-fiber-reinforced polymer frames below six kilograms target premium outpatient segments in Swiss and Japanese diagnostic networks.
- Folding Wheelchair:Collapsible aluminum architectures optimize storage density in space-constrained European imaging suites.
Margin stratification follows material intensity: polymer composites command premium pricing, aluminum occupies mid-tier procurement, titanium concentrates in specialized bariatric applications.
End User:
Institutional procurement through NHS Supply Chain and Kaiser Permanente framework agreements concentrates volume in hospital networks. Homecare channels fragment across durable medical equipment distributors with weaker price negotiation leverage.
- Hospitals:Integrated delivery networks in California and Île-de-France bundle non-magnetic wheelchairs with MRI-compatible stretchers through multi-year vendor contracts. METI-funded modernization across Japanese imaging suites is accelerating replacement cycles.
- Rehabilitation Centers:Specialized seating integration requirements under ISO 7176-19 drive custom fabrication workflows for post-acute patient populations in German-speaking Europe.
- Homecare:Direct-to-patient reimbursement pathways through Medicare Part B in the United States create price-sensitive demand for manual configurations.
- Nursing Homes:Long-term care facilities in the Netherlands prioritize durable polymer frames with five-year service life guarantees under EU Green Deal sustainability criteria.
Procurement concentration: Hospital networks. Fastest channel expansion: Rehabilitation Centers.
Usage Environment:
Field strength specifications from 3 Tesla to 7 Tesla MRI systems dictate material purity thresholds. Ultra-high-field installations above seven Tesla now demand ferromagnetic content below 0.005% iron, eliminating most aluminum alloys from qualification.
- Indoor:Controlled climate imaging suites permit polymer composite frames without UV degradation concerns. Swiss and Dutch academic medical centers specify carbon-fiber-reinforced PEEK monocoques for 7 Tesla environments.
- Outdoor:Weather-resistant titanium architectures serve inter-facility patient transport in Nordic hospital networks with harsh winter exposure.
- Extended Use:Durability testing under ISO 7176-8 governs frame fatigue life for patients requiring daily mobility support across diagnostic and residential settings.
- Short-term Use:Rental pool configurations in US hospital systems prioritize rapid sanitization compatibility and minimal maintenance overhead.
Technical specification intensity: Indoor environments. Fastest standard tightening: Extended Use protocols.
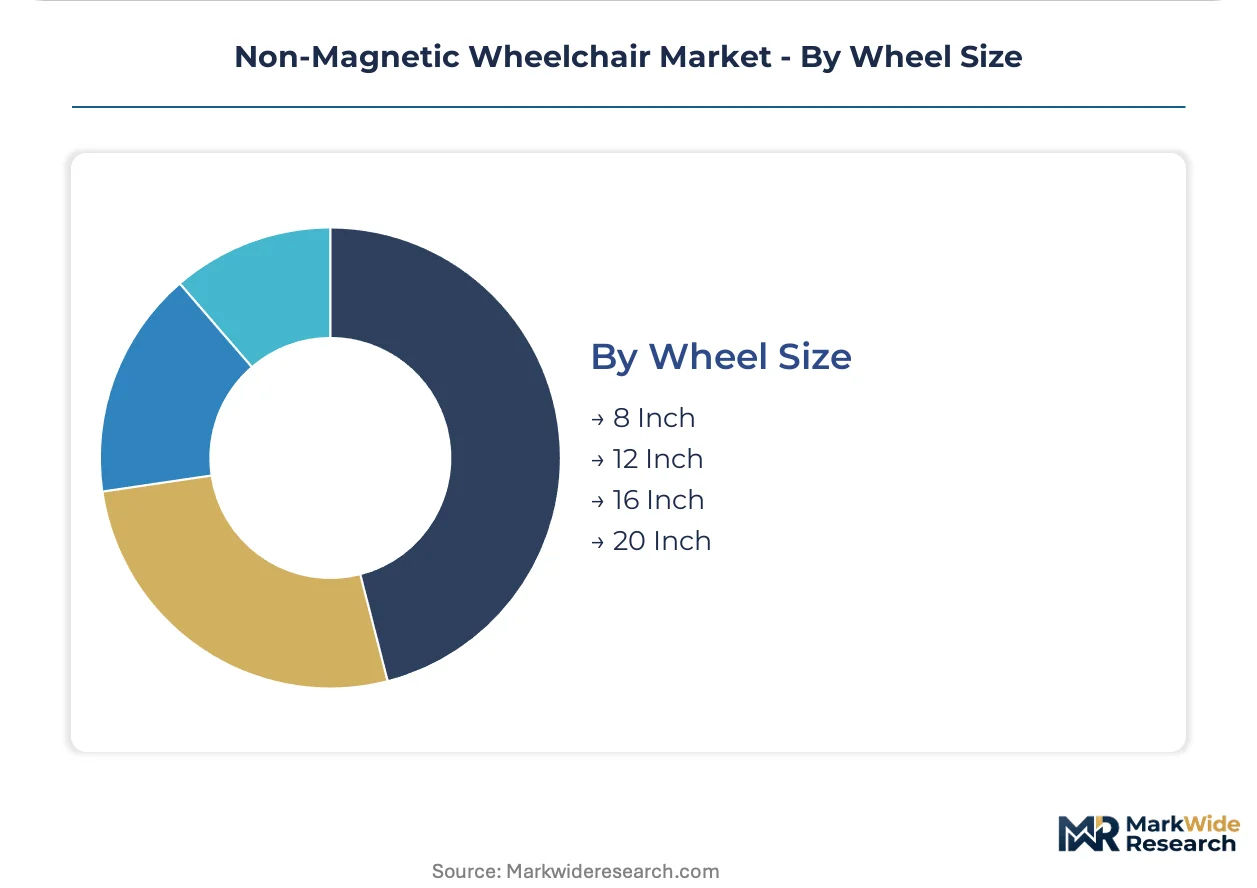
Wheel Size:
Propulsion biomechanics and corridor maneuverability determine specification across care settings. Pediatric MRI suites in Nordic networks remain underserved by current manufacturer size offerings.
- 8 Inch:Compact caster configurations optimize turning radius in narrow European imaging suite corridors. German hospital construction standards specify minimum doorway widths that favor this geometry.
- 12 Inch:Mid-size wheels balance propulsion efficiency with storage footprint in Japanese METI-funded retrofit programs.
- 16 Inch:Standard adult self-propulsion diameter dominates manual wheelchair procurement across US academic medical centers.
- 20 Inch:Large-diameter wheels reduce rolling resistance for bariatric patient transport in rehabilitation center settings.
Volume concentration: 16 Inch specifications. Fastest specification shift: 8 Inch for space-constrained suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European non-magnetic wheelchair manufacturing through Ottobock's polymer composite operations, while METI-funded hospital retrofits concentrate procurement in Japan's Kanto corridor.
United States
Academic medical centers in California and Massachusetts drive bariatric-powered wheelchair demand for 3 Tesla MRI suites. FDA 510(k) clearance timelines stretching past 14 months filter market entrants. Kaiser Permanente's integrated delivery network bundles non-magnetic transport equipment through multi-year framework agreements concentrated in the San Francisco Bay Area.
Germany
Bavarian and North Rhine-Westphalian hospital networks prioritize recyclable polymer frames under EU Green Deal procurement mandates. EU MDR biocompatibility testing requirements and five-year post-market surveillance obligations consolidate regulatory affairs functions in Munich and Düsseldorf industrial clusters. German specialty chemical producers control carbon-fiber-reinforced PEEK resin supply for medical applications.
Japan
METI's hospital modernization program retrofits 340 imaging suites with ferromagnetic-free equipment, accelerating replacement cycles in Tokyo and Osaka metropolitan areas. PMDA certification requirements parallel FDA timelines for powered variants. Japanese diagnostic networks specify 12-inch wheel configurations to balance propulsion efficiency with storage constraints in space-constrained facilities.
Switzerland
Swiss academic medical centers in Zurich and Basel specify carbon-fiber-reinforced PEEK monocoque frames for 7 Tesla ultra-high-field MRI environments. Swissmedic regulations align with EU MDR standards while maintaining distinct notified body relationships. The country's precision polymer processing capabilities support premium-tier wheelchair fabrication for European export markets.
Netherlands
Dutch hospital construction standards specify minimum doorway widths favoring 8-inch compact caster configurations in narrow imaging suite corridors. NHS Supply Chain's e-commerce platform disintermediates traditional distributors across the Randstad region. Long-term care facilities prioritize durable polymer frames with five-year service life guarantees under sustainability criteria.
Non-Magnetic Wheelchair Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specification tiers, with polymer composite specialists commanding price multiples over aluminum fabricators. The market structures around three tiers: multinational rehabilitation equipment conglomerates with established distribution, mid-tier regional manufacturers with molding capabilities, and niche specialists serving ultra-high-field MRI installations. Consolidation pressure intensifies as framework agreements favor bundled procurement. Dominant competitive moves include backward integration into polymer resin supply and strategic partnerships with notified bodies for accelerated EU MDR certification.
Among North American rehabilitation equipment conglomerates, Invacare Corporation and GF Health Products occupy positions anchored by established hospital distribution networks. European market presence concentrates around Ottobock, whose German manufacturing base exemplifies specialized polymer composite capabilities, and Permobil, which represents advanced seating integration architectures. Magmedix Inc. and MRIequip.com sit within the niche specialist tier serving diagnostic imaging environments with ferromagnetic detection compliance requirements.
| Leading Market Players |
|---|
| GF Health Products, Inc. |
| Medline Industries, Inc. |
| Invacare Corporation |
| Permobil |
| Magmedix Inc. |
| MRIequip.com |
| AliMed |
| Newmatic Medical |
| Ottobock |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's medical device sustainability criteria gates qualified supply and premium-tier pricing access by mandating recyclable polymer frames that only German and Austrian specialty chemical producers currently certify, compressing margin pools for aluminum fabricators unable to meet biocompatibility thresholds.
Pricing Analysis
Value-based pricing anchored to MRI suite uptime guarantees separates carbon-fiber-reinforced PEEK monocoque architectures from aluminum alternatives. Price differentiation hinges on ferromagnetic certification grade under ISO 7176 standards and customization depth for bariatric load capacities. Pricing pressure stems from aerospace sector competition for Grade 5 titanium sheet compressing medical allocations. Homecare channels through Medicare Part B reimbursement exhibit highest price sensitivity; Swiss academic medical centers purchasing for 7 Tesla environments show lowest.
Supply Chain Analysis
Direct-to-hospital digital procurement through NHS Supply Chain and Kaiser Permanente framework agreements handles integrated delivery network demand, disintermediating traditional rehabilitation equipment distributors. Geographic supply concentrates in Germany for carbon-fiber-reinforced PEEK resin, Japan for precision polymer processing components, and Switzerland for ultra-high-field certification expertise. Raw material dependencies include medical-grade titanium alloys, lithium-iron-phosphate battery cells, and specialized polymer resins. Single-source vulnerability from three German chemical producers controlling medical PEEK supply creates structural risk. Distribution runs through Group Purchasing Organizations in the US and purchasing cooperatives in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-magnetic wheelchair market sits in a technology-transition phase as carbon-fiber-reinforced polymer monocoque architectures displace aluminum and titanium frame constructions across 3 Tesla and 7 Tesla MRI installations.
For Market Incumbents: Extend polymer composite formulation capabilities through backward integration into captive resin supply, countering raw material allocation pressure from aerospace competitors. Deepen notified body relationships in Munich and Düsseldorf industrial clusters to compress EU MDR certification timelines that currently stretch past fourteen months for powered variants. Lock in multi-year framework agreements with Kaiser Permanente and Île-de-France hospital networks before procurement consolidation displaces single-item tenders entirely.
For New Entrants and Emerging Players: The price-point gap between premium carbon-fiber PEEK monocoques and economy aluminum folding configurations creates entry space for mid-tier polymer specialists. Target pediatric MRI suites across Nordic hospital networks, where child-sized non-magnetic wheelchairs remain systematically underdeveloped. Pursue direct-to-hospital digital procurement pathways through NHS Supply Chain's e-commerce platform to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: FDA 510(k) clearance timeline compression for modified frame geometries is the leading indicator that regulatory affairs scale economies are concentrating competitive advantage. Position acquisition screening around mid-tier manufacturers with in-house polymer molding capabilities and existing notified body relationships, as these assets compound across EU MDR post-market surveillance obligations. Monitor German specialty chemical producer capacity expansion announcements as the inflection signal for input cost relief.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Five-year post-market surveillance obligations consolidate regulatory affairs functions in Munich clusters. |
| Backward Integration into Polymer Resin | Captive supply of carbon-fiber-reinforced PEEK reduces dependency on three German chemical producers. |
| Pediatric Product Line Development | Child-sized configurations address systematic gaps across Nordic hospital networks and Swiss academic centers. |
| Hospital System Partnership | Kaiser Permanente and Île-de-France framework agreements bundle non-magnetic transport equipment procurement. |
| ISO 7176-19 Seating Integration | Pressure-mapping sensor convergence enables real-time patient positioning data for rehabilitation centers. |
Research Methodology
FDA 510(k) filings, EU MDR notified body documentation, and METI hospital modernization program disclosures formed the secondary backbone of this analysis. Primary interviews with hospital procurement managers, biomedical engineers at academic medical centers, GPO contracts specialists, and polymer composite manufacturing executives combined with secondary validation. Bottom-up and top-down triangulation cross-referenced imaging suite retrofit schedules against manufacturer capacity disclosures.
Bottom-up modeling segmented volume and value across the projection horizon by product type, end user, usage environment, and wheel size dimensions. CAGRs were derived from installed base replacement cycles tied to MRI field strength upgrades and procurement framework agreement renewal patterns. Forecast inputs incorporated ferromagnetic detection sensitivity tightening trajectories and EU Green Deal sustainability mandate implementation timelines.
Inputs from NHS Supply Chain procurement databases and Japanese METI retrofit disclosures were available through the study window; gaps in real-time polymer resin pricing introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding certification timeline stability and aerospace sector titanium demand persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Respiratory Devices Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Global Medical Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Transcranial Doppler Devices Market