
 Peritoneal Dialysis Solutions Market | 2026-2036
Peritoneal Dialysis Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Peritoneal Dialysis Solutions Market Analytics
Biocompatible glucose-sparing formulations are reshaping peritoneal dialysis solution development, reducing glucose exposure and preserving peritoneal membrane integrity over extended therapy cycles. Baxter International leverages its integrated manufacturing footprint to sustain supply chain control across North America and Europe. Fresenius Medical Care AG anchors its position through vertical integration into dialysis services, linking solution production directly to patient treatment networks. Terumo Corporation differentiates through specialized R&D intensity in low-GDP, neutral-pH solution portfolios.
Peritoneal dialysis solutions are sterile, electrolyte-balanced fluids containing glucose, amino acids, or icodextrin as osmotic agents, designed to remove metabolic wastes and excess fluid through the peritoneal membrane during automated or continuous ambulatory procedures. The home care application segment leads volume consumption as healthcare systems shift chronic kidney disease management toward patient-directed settings with remote monitoring support. Solution formulations capture the largest margin pool within the product type structure, while device and accessory categories compete on price and compatibility standards.
The FDA enforces current Good Manufacturing Practice requirements for sterile peritoneal dialysis solutions, directly conditioning market access and batch release protocols for domestic and imported products. The European Medicines Agency applies Medical Device Regulation and REACH chemical safety standards to solution containers and osmotic agent compositions, shaping formulation choices for EU market participants. Stakeholders must monitor evolving reimbursement classifications for home-based dialysis modalities, as payor policy shifts will determine patient access trajectories and manufacturer volume commitments without reference to specific forecast years.
Market Dynamics
The home care migration in peritoneal dialysis is compressing hospital-based revenue streams while expanding remote monitoring infrastructure requirements. This structural shift demands that manufacturers reconfigure supply chains toward direct-to-patient distribution models with cold-chain integrity guarantees.
Growth Catalysts
- Biocompatible Formulation Mandates:The FDA's current Good Manufacturing Practice requirements for sterile solutions are accelerating glucose-sparing icodextrin adoption. These standards reduce peritoneal membrane damage rates and extend therapy viability.
- Japan's Aging Demographics:METI-supported chronic kidney disease management programs prioritize home-based modalities to contain hospitalization costs. Patient-directed treatment settings reduce facility overhead burdens.
- Remote Monitoring Integration:Cloud-connected automated peritoneal dialysis devices enable real-time clinical oversight without clinic visits. Telehealth reimbursement expansions in Medicare accelerate platform deployment.
Market Restraints
- Glucose Raw Material Volatility:Corn-derived dextrose monohydrate supply fluctuations from Midwestern US agricultural regions create formulation cost instability. Manufacturers lack viable short-term substitution pathways.
- EMA REACH Compliance Burden:Chemical safety documentation requirements for solution containers and osmotic agents extend EU market entry timelines. Small-batch producers face disproportionate compliance costs.
- Peritoneal Membrane Failure Rates:Long-term glucose exposure induces fibrosis and ultrafiltration decline. This biological limitation caps therapy duration and creates hemodialysis substitution pressure.
Strategic Opportunities
- Rural India Penetration:CDSCO streamlined medical device registration pathways enable localized solution production. Dialysis deserts in Bihar and Uttar Pradesh present volume expansion potential.
- Amino Acid-Based Osmotic Agents:Neutral-pH formulations with reduced glucose load address malnutrition in diabetic nephropathy patients. Clinical validation studies in Germany and Italy support premium positioning.
- Direct-to-Patient Subscription Models:Home delivery platforms bypass traditional hospital procurement hierarchies. Inventory management shifts from bulk institutional orders to individualized consumption tracking.
Industry Challenges
- Sterile Manufacturing Workforce Scarcity:Aseptic processing technicians with peritoneal dialysis solution specialization command premium wages. Training pipelines fail to match capacity expansion timelines.
- Legacy Device Compatibility Certification:New solution formulations require validation across multiple automated peritoneal dialysis machine generations. Retrofitting protocols delay commercial launches.
- Cold-Chain Distribution Infrastructure:Temperature-controlled logistics networks for home-delivered solutions demand capital deployment in secondary markets. Last-mile integrity failures risk product spoilage and patient safety incidents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peritoneal Dialysis Solutions Market |
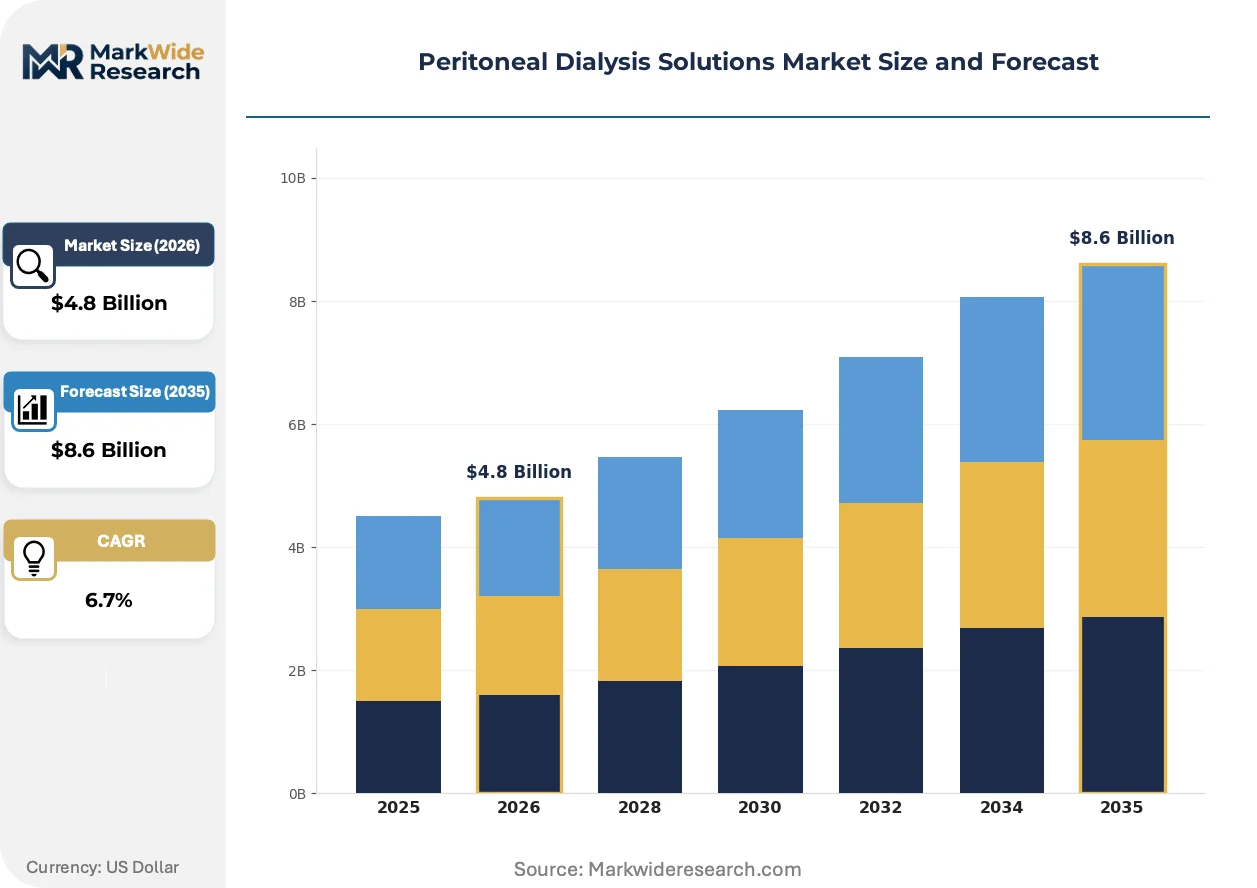
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Solutions, Devices, Accessories Application: Home Care, Hospitals, Clinics, Long-term Care End User: Patients, Healthcare Providers, Caregivers, Laboratories Distribution Channel: Retail, E-commerce, Direct Sales, Wholesalers |
| Companies Covered | Baxter International Inc., Fresenius Medical Care AG, Terumo Corporation, Medtronic plc, Utah Medical Products, Inc., B. Braun Melsungen AG, Nipro Corporation, DaVita Inc., Newsol Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peritoneal Dialysis Solutions Market Evolving Landscape
Formulation chemistry and care delivery architecture are undergoing simultaneous transformation. These parallel developments are compressing traditional competitive advantages while opening new value capture mechanisms.
Low-GDP neutral-pH solutions containing bicarbonate or lactate buffers are rendering obsolete conventional acidic glucose formulations in extended therapy protocols. European dialysis centers with high automated peritoneal dialysis penetration are adopting these biocompatible alternatives at accelerated rates. The structural consequence is margin compression for legacy formulation portfolios while premium positioning opens for membrane-preserving technologies.
The EU Medical Device Regulation's strengthened clinical evidence requirements for solution-container combinations are forcing retrospective data collection investments. Manufacturers must demonstrate biocompatibility across full product lifecycles rather than relying on component-level approvals. Solution portfolios with pre-MDR legacy certifications face renewal cliffs that favor larger players with dedicated regulatory affairs infrastructure.
Patient self-management platforms with integrated consumption tracking are displacing nurse-administered inventory assessments in home care settings. Remote monitoring vendors capture data streams that previously flowed through clinic-based encounters. This behavioral shift concentrates most visibly in United States Medicare Advantage populations where capitated reimbursement rewards reduced acute intervention rates.
Peritoneal Dialysis Solutions Market Segmentation
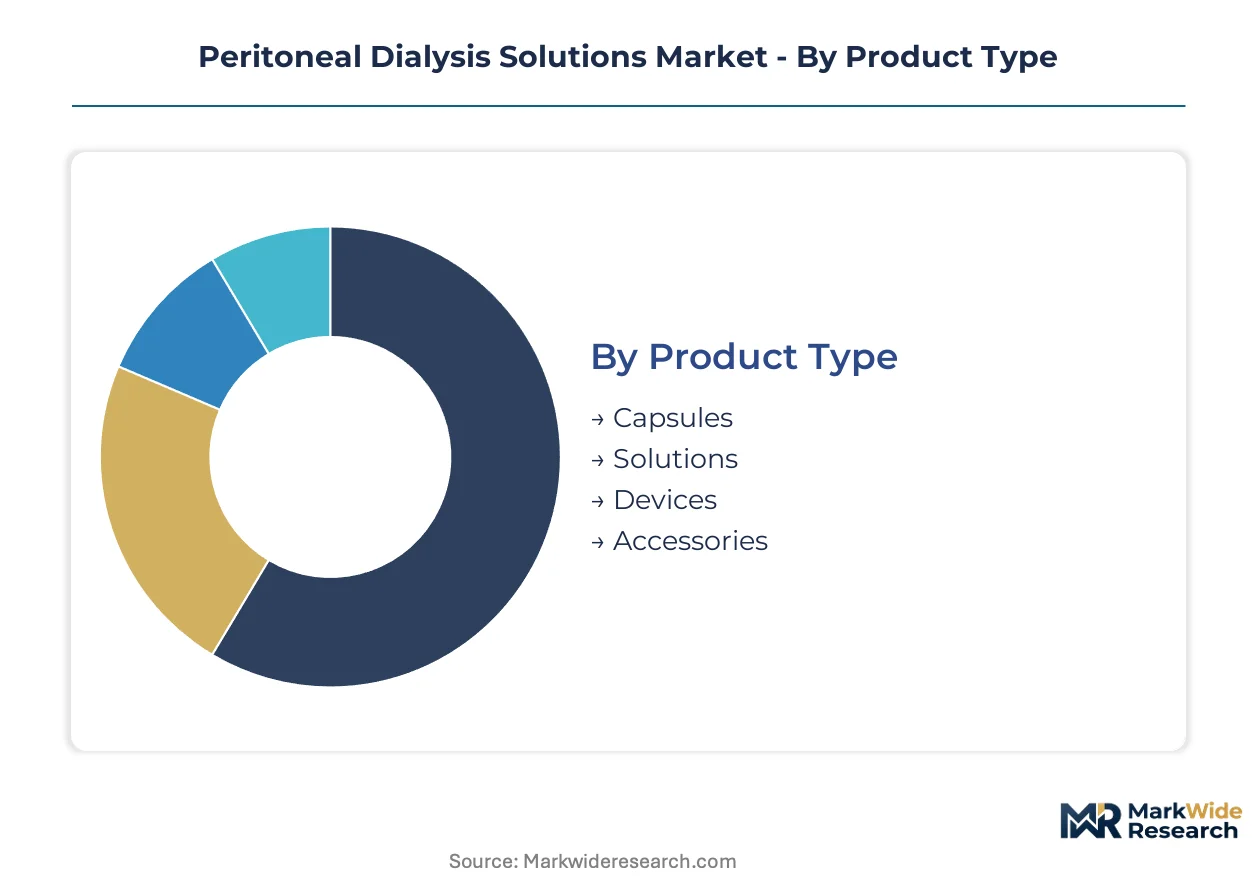
Peritoneal dialysis solutions demand precise segmentation alignment with reimbursement pathways and patient self-management capabilities. Each category reflects distinct supply chain configurations, from sterile manufacturing batch economics to last-mile cold-chain logistics. Understanding these segment boundaries enables manufacturers to match formulation investments with accessible volume pools.
Product Type:
After-sales service intensity varies sharply across product types, with solutions requiring minimal technical support while devices demand continuous calibration and firmware maintenance.
- Solutions:Sterile electrolyte-balanced fluids containing glucose, amino acids, or icodextrin as osmotic agents. Demand concentrates in home care settings across the United States, where Medicare Advantage capitation rewards reduced hospitalization rates through patient-directed therapy.
- Devices:Automated peritoneal dialysis machines with cloud-connected monitoring capabilities. European dialysis centers with high automated penetration are adopting these systems most aggressively, driven by EMA Medical Device Regulation compliance requirements and staff efficiency targets.
- Capsules:Pre-measured osmotic agent cartridges for simplified patient handling. These formats reduce preparation errors in elderly patient populations.
- Accessories:Transfer sets, catheter connectors, and drainage bags with standardized Luer-lock interfaces. Compatibility certification across multiple device generations shapes procurement decisions.
By volume, Solutions leads. By growth pace, Devices is gaining share fastest as remote monitoring integration accelerates replacement cycles.
Application:
Cost tier stratification across applications determines margin capture, with institutional procurement favoring volume discounts and home care commanding premium pricing for convenience.
- Home Care:Patient-directed peritoneal dialysis with telehealth oversight and direct-to-patient delivery logistics. Japan's METI-supported chronic kidney disease programs prioritize this modality to contain hospitalization costs in aging demographics.
- Hospitals:Acute initiation and complication management with intensive nursing support. These settings face revenue compression as cases migrate to outpatient environments.
- Clinics:Hybrid models combining physician oversight with patient self-administration training. Rural penetration in India through CDSCO-streamlined registration pathways is expanding this segment.
- Long-term Care:Skilled nursing facilities managing patients with limited mobility or cognitive impairment. Staffing ratios and infection control protocols constrain adoption rates.
By volume, Home Care leads. By expansion trajectory, Clinics is climbing the fastest as healthcare systems seek intermediate cost structures.
End User:
Customer type heterogeneity demands differentiated education and support investments, from patient self-management platforms to clinical laboratory quality assurance protocols.
- Patients:Individual consumers managing therapy schedules, inventory, and symptom reporting through mobile applications. Remote monitoring reimbursement expansions in United States Medicare accelerate platform engagement.
- Healthcare Providers:Nephrology practices and dialysis centers prescribing and overseeing therapy protocols. These entities capture data streams that inform population health management contracts.
- Caregivers:Family members or home health aides assisting patients with limited dexterity or vision. Training burden and liability exposure shape adoption thresholds.
- Laboratories:Clinical reference labs performing peritoneal effluent analysis and infection screening. Automated chemistry platforms reduce turnaround times for culture results.
By volume, Patients leads. By service intensity per account, Healthcare Providers is expanding most quickly as value-based contracts consolidate prescribing authority.
Distribution Channel:
Supply concentration in direct sales models is producing channel conflict with traditional wholesale networks as manufacturers seek patient relationship ownership.
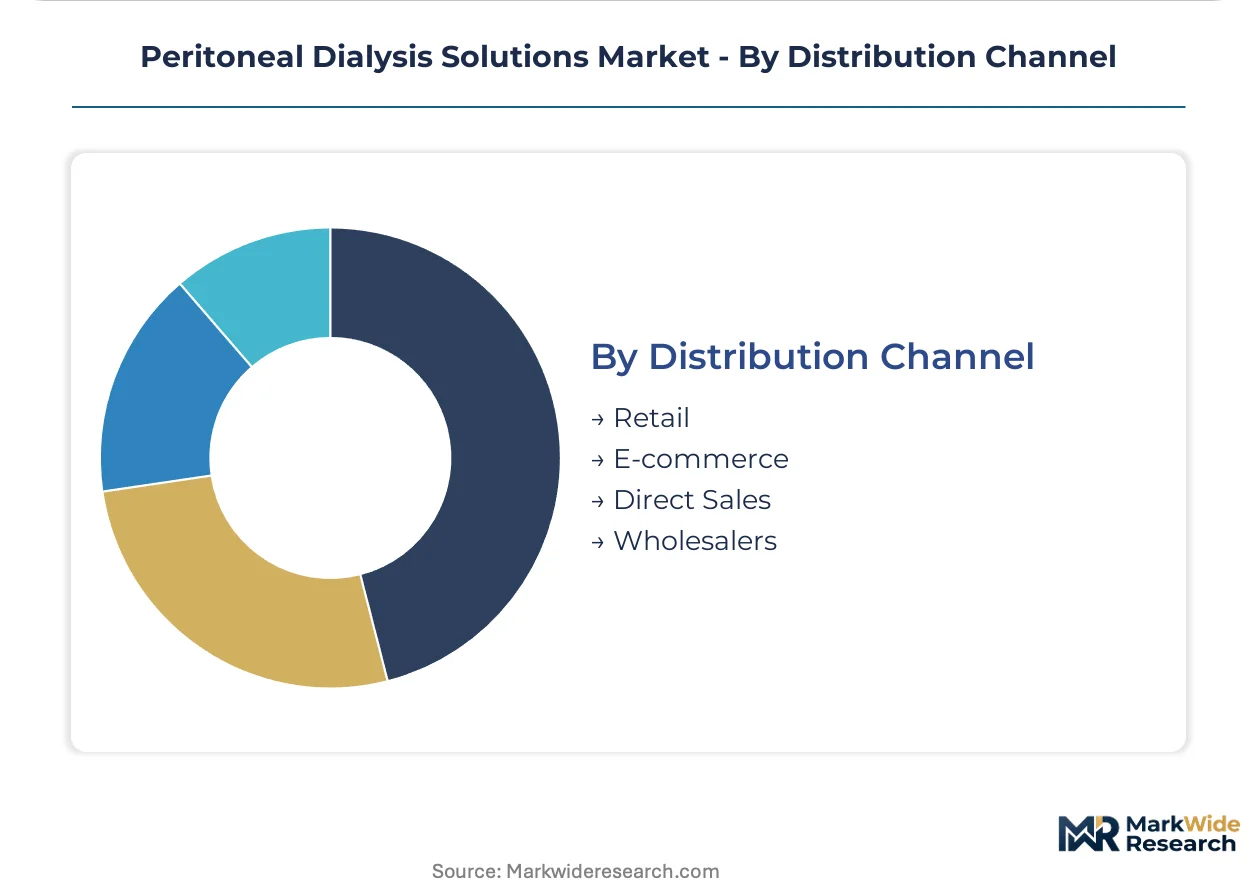
- Direct Sales:Manufacturer-managed home delivery with consumption tracking and automated replenishment. Inventory management shifts from bulk institutional orders to individualized patient monitoring.
- Retail:Pharmacy-based pickup for emergency or travel supplies. Cold-chain integrity requirements limit geographic reach of this channel.
- E-commerce:Platform-mediated ordering with third-party logistics fulfillment. Regulatory validation of temperature-controlled shipping containers constrains market entry.
- Wholesalers:Traditional hospital and clinic procurement hierarchies with volume-based pricing tiers. These intermediaries face margin pressure from direct-to-patient disintermediation.
By volume, Direct Sales leads. By structural transformation pace, E-commerce is ahead as patient digital engagement expectations reshape ordering behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports peritoneal dialysis solutions and manufacturing equipment to healthcare systems across Central and Eastern Europe, anchoring regional supply corridors with cold-chain logistics networks radiating from Rhine-Ruhr industrial clusters.
United States
Medicare Advantage capitation models reward home-based dialysis with reduced hospitalization rates, while the FDA enforces current Good Manufacturing Practice standards for sterile solution batch release. Baxter International maintains integrated manufacturing control across Illinois and California production facilities.
Japan
METI-supported chronic kidney disease management programs prioritize patient-directed modalities to contain facility costs in aging demographics. The PMDA regulates solution-container combinations under strengthened clinical evidence requirements. Osaka-based dialysis service networks are adopting remote monitoring platforms at accelerated rates.
Germany
Fresenius Medical Care anchors European solution production through captive supply integration into dialysis treatment networks. The EMA applies Medical Device Regulation and REACH chemical safety standards to osmotic agent compositions. Baden-Württemberg manufacturing clusters specialize in low-GDP neutral-pH formulation development.
India
CDSCO streamlined medical device registration pathways enable localized production for dialysis deserts in Bihar and Uttar Pradesh. The country's national pharmaceutical regulator enforces sterile manufacturing benchmarks for imported and domestic solutions. Maharashtra-based contract manufacturers are expanding capacity for amino acid-based osmotic agents.
Italy
Clinical validation studies for biocompatible formulations concentrate in nephrology research centers across Lombardy and Emilia-Romagna. The EMA's REACH compliance burden shapes formulation choices for EU market entry. Milan-area dialysis centers are adopting automated peritoneal dialysis systems with cloud-connected oversight capabilities.
Peritoneal Dialysis Solutions Market Competitive Landscape
On the supply side, the industry is consolidated around integrated healthcare conglomerates with captive manufacturing and direct-to-patient distribution infrastructure. Three strategic archetypes dominate: diversified medical technology multinationals with sterile solution specialization, vertically integrated dialysis service providers with backward integration into solution production, and regional specialists focused on low-GDP biocompatible formulations. Competitive dynamics center on regulatory certification speed and cold-chain distribution network density rather than price competition alone.
Within the integrated multinational tier, Baxter International Inc. and Fresenius Medical Care AG exemplify archetypes combining manufacturing scale with direct patient service networks. Terumo Corporation occupies a position among Japanese specialists emphasizing R&D intensity in membrane-preserving technologies. These three anchors represent distinct geographic and strategic positioning vectors without implying specific market share claims.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Fresenius Medical Care AG |
| Terumo Corporation |
| Medtronic plc |
| Utah Medical Products, Inc. |
| B. Braun Melsungen AG |
| Nipro Corporation |
| DaVita Inc. |
| Newsol Technologies |
| Others |
Value Network & Pricing Analysis
Rhine-Ruhr industrial clusters anchor European peritoneal dialysis solution production, with capacity concentration in Baden-Württemberg manufacturing hubs translating into downstream pricing power for membrane-preserving formulations. FDA batch release protocols and EMA REACH compliance requirements create tiered cost structures that manufacturers pass through to hospital procurement committees and direct-to-patient subscription channels.
Pricing Analysis
Current-generation low-GDP neutral-pH solutions command substantial premiums over prior-generation acidic glucose formulations, while next-generation amino acid-based osmotic agents remain in clinical validation with undefined pricing. Three-tier pricing structure across premium membrane-preserving, standard biocompatible, and economy conventional formulations dominates procurement. Price differentiation rests on FDA certification tier and cold-chain delivery infrastructure density. Cost compression in economy tiers intensifies because corn-derived dextrose feedstock volatility squeezes formulation margins. Home care patients exhibit lowest price sensitivity due to Medicare Advantage capitation rewards, while clinic procurement committees in India demonstrate highest sensitivity to per-liter costs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for osmotic agent raw material procurement, with supply-chain finance facilities concentrated among Illinois and California production hubs. Geographic supply concentration centers on the United States, Germany, and Japan for sterile manufacturing capacity. Raw material dependencies draw from Midwestern US corn regions for dextrose monohydrate, Italian chemical processors for lactate buffers, and Japanese specialty manufacturers for icodextrin polymers. Single-source vulnerability in glucose feedstock creates exposure to agricultural commodity cycles. Distribution runs through direct-to-patient cold-chain networks with automated replenishment platforms displacing traditional wholesale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peritoneal dialysis solutions represent an early-cycle expansion story as home care migration accelerates patient-directed therapy adoption beyond hospital-centric models. Remote monitoring reimbursement expansions in United States Medicare create structural tailwinds for volume penetration.
For Market Incumbents: Insulate formulation margins by deepening captive supply integration into dialysis service networks and accelerating low-GDP neutral-pH certification investments ahead of EMA MDR renewal cliffs. Emerging regional specialists in India threaten volume positions through CDSCO-streamlined localized production. Cold-chain distribution density constitutes the critical defensive lever against direct-to-patient disintermediation. For New Entrants and Emerging Players: Rural dialysis deserts in Bihar and Uttar Pradesh represent the most penetrable entry point for amino acid-based osmotic agent formulations with reduced glucose load. Elderly patient populations in Japan's METI-supported chronic kidney disease programs offer secondary white-space for simplified capsule delivery formats. Go-to-market execution should anchor on hospital system partnership models with embedded clinical validation protocols. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease infrastructure play because aging demographics across developed economies guarantee sustained demand for home-based renal replacement modalities. Acquisition targets should prioritize regional manufacturers with established sterile processing capabilities and pending FDA or EMA certification pathways. The signal to watch is reimbursement classification shifts for remote monitoring platforms in Medicare Advantage and Japan's national health insurance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Biocompatible Formulation | Accelerates market access for glucose-sparing solutions under current Good Manufacturing Practice standards. |
| CE Marking Pathway for Solution-Container Combinations | Enables European commercialization under strengthened EMA Medical Device Regulation clinical evidence requirements. |
| Hospital System Partnership for Home Care Transition | Captures patient volume migration from institutional settings to remote monitoring platforms. |
| Software Companion Development for Consumption Tracking | Integrates automated peritoneal dialysis devices with cloud-connected inventory management systems. |
| Reimbursement Strategy for Telehealth Oversight | Aligns manufacturer value propositions with Medicare Advantage capitation incentives for reduced hospitalization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with nephrology practice administrators, hospital purchasing committee members, biomedical engineers specializing in dialysis device integration, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA centralized procedure submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up volume estimates from sterile manufacturing batch economics triangulated with top-down demand projections from chronic kidney disease prevalence modeling.
Forecast inputs considered solution formulation chemistry generations, automated versus continuous ambulatory delivery modalities, home care versus institutional application settings, and direct-to-patient versus wholesale distribution channels across the projection horizon. CAGRs derived from segmented growth rate analysis applied to baseline volume and value estimates. Industry-specific inputs incorporated peritoneal membrane failure rate trajectories and remote monitoring platform penetration assumptions.
Practitioners should monitor reimbursement classification shifts, glucose feedstock commodity cycles, and sterile manufacturing workforce availability for early signals of forecast deviation. Macroeconomic contraction affecting Medicare Advantage enrollment, regulatory acceleration of hemodialysis substitution protocols, or breakthrough bioartificial kidney technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Band Ligators Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
North America Refractive Surgery Devices Market