
 Europe Invisible Orthodontics Market | 2026-2036
Europe Invisible Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Invisible Orthodontics Market Foresight
Digital intraoral scanning paired with AI-driven treatment planning is rewriting how invisible orthodontic appliances are designed and fabricated across European dental networks. Align Technology leverages its proprietary scanner-aligner ecosystem to sustain premium positioning in high-volume markets. Institut Straumann AG anchors its competitive stance through integrated digital workflow platforms that connect clinics directly with manufacturing. Dentsply Sirona competes by extending its CAD/CAM infrastructure into orthodontics from its established restorative base.
Europe invisible orthodontics encompasses removable clear polymer aligners, bonded lingual appliances, and tooth-colored ceramic brackets engineered for aesthetic tooth movement with force delivery between 0.5 and 1.5 Newtons per tooth. These systems employ medical-grade thermoplastic polyurethane or multilayer polyethylene terephthalate glycol compositions manufactured through thermoforming over 3D-printed dental models. Clear aligners dominate product type revenue given adult willingness to pay for removability, while ceramic braces retain share among teenagers seeking fixed-appliance reliability at lower cost. Lingual braces occupy a narrow premium tier concentrated in affluent urban orthodontic clinics. Short-term and intermediate-term treatment durations are expanding fastest as accelerated orthodontic protocols reduce average case times.
The EU Medical Device Regulation and CE marking framework govern market access, with notified bodies in Germany and France conducting conformity assessments that lengthen approval timelines for new aligner materials. EMA-aligned biocompatibility standards and national dental board guidelines in Italy and Spain shape clinical training requirements and indirect demand. Stakeholders must monitor how forthcoming EU AI Act provisions classify automated treatment planning algorithms and whether Germany's KBA-equivalent medical device regulator imposes additional software validation burdens on AI-integrated orthodontic platforms.
Market Dynamics
Digital intraoral scanning is compressing traditional alginate impression workflows across European orthodontic practices, with AI-driven treatment planning now embedded in standard clinical protocols. This technological displacement is reshaping capital allocation, training requirements, and patient throughput economics.
Growth Catalysts
- EU Medical Device Regulation compliance:MDR certification requirements for clear aligner materials are elevating quality thresholds that filter out marginal suppliers, consolidating demand around notified body-approved manufacturers in Germany and France.
- Adult aesthetic dentistry demand:Working-age professionals in the United Kingdom, Germany, and France are prioritizing removable clear polymer aligners over fixed appliances for career-visible treatment.
- Accelerated orthodontic protocols:Short-term treatment durations using high-frequency vibration adjuncts and micro-osteoperforation are expanding addressable cases beyond traditional 18-24 month candidacy.
Market Restraints
- Medical-grade thermoplastic input costs:Polyethylene terephthalate glycol and polyurethane supply concentration in German and Dutch chemical producers creates margin pressure during petrochemical volatility cycles.
- Notified body capacity constraints:Germany's BfArM-delegated conformity assessment backlog and France's ANSM review timelines extend CE marking duration for new aligner materials by 8-14 months.
- Lingual appliance technical limitations:Bonded fixed appliances behind anterior teeth require specialized orthodontist training and chair time that restricts scalable deployment outside affluent urban clinics.
Strategic Opportunities
- Spain and Italy underpenetration:Southern European orthodontic clinic density remains 40% below German levels, creating whitespace for digital workflow platforms that reduce specialist labor intensity.
- EU AI Act algorithm classification:Automated treatment planning software may receive favorable risk categorization, enabling faster deployment of predictive tooth movement modeling across notified body jurisdictions.
- Direct-to-clinic manufacturing integration:In-house thermoforming and 3D printing of dental models bypasses traditional dental laboratory intermediaries, capturing margin and reducing turnaround time.
Industry Challenges
- Digital workflow integration complexity:Legacy practice management systems in established German orthodontic clinics resist seamless API connectivity with cloud-based treatment planning platforms.
- Specialist orthodontist training bottlenecks:National dental boards in Italy and Spain maintain variable certification requirements for clear aligner therapy that slow workforce expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Invisible Orthodontics Market |
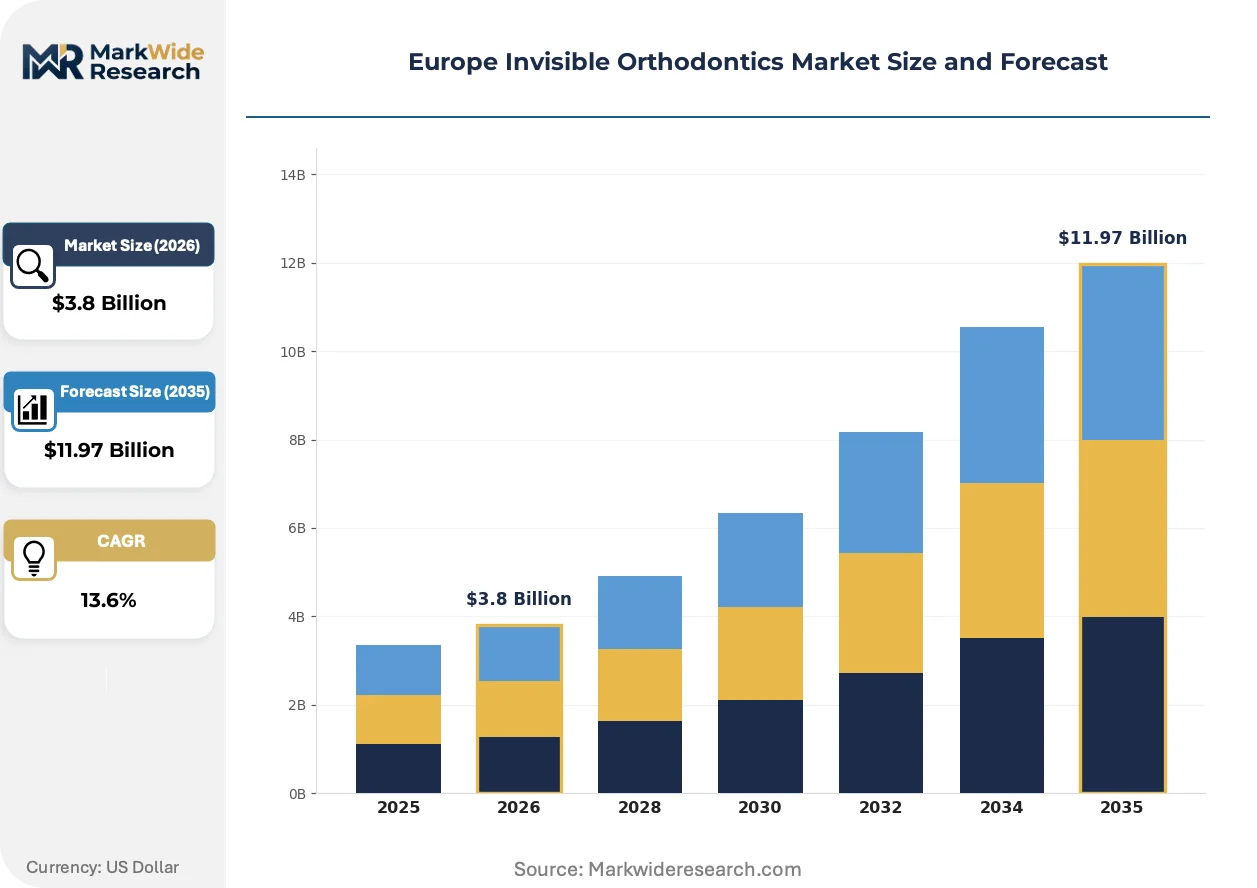
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Lingual Braces, Ceramic Braces, Retainers End User: Adults, Teenagers, Orthodontic Clinics, Dental Hospitals Treatment Duration: Short-term, Intermediate-term, Long-term, Maintenance Distribution Channel: Direct Sales, Online Retail, Distributors, Dental Practices |
| Companies Covered | Align Technology, Dentsply Sirona, Envista Holdings, Institut Straumann AG, 3M, Henry Schein, Dentaurum GmbH & Co. KG, FORESTADENT - Bernhard Foerster GmbH, TP Orthodontics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Invisible Orthodontics Market Shifts & Advancements
Artificial intelligence is penetrating orthodontic treatment planning at the diagnostic and predictive stages, compressing traditional manual cephalometric analysis and enabling mass-customization of appliance fabrication. This shift is redistributing value from clinical labor to software and manufacturing infrastructure.
Multilayer thermoplastic compositions are migrating from single-material polyethylene terephthalate glycol to gradient-density polyurethane structures that deliver variable force delivery across treatment phases. Adult patients in the United Kingdom and Germany are adopting these next-generation aligners for complex malocclusion cases previously reserved for fixed appliances. The technology is migrating from premium-tier positioning toward mid-market accessibility as manufacturing scale reduces per-unit material costs.
The EU AI Act's risk classification framework for medical device software is imposing documentation burdens on automated orthodontic treatment planning algorithms. Manufacturers must demonstrate clinical validation datasets and post-market surveillance protocols to notified bodies in Germany and France. Clear aligner platforms with integrated AI diagnostics face the steepest compliance costs, while standalone software vendors seek MDR certification through partnership with established device manufacturers.
Subscription-based appliance procurement is displacing per-case aligner purchasing in high-volume orthodontic groups across France and the United Kingdom. These consolidated practices negotiate unlimited-aligner contracts that flatten variable costs and lock supplier relationships. The model is most visible among dental service organizations operating 15-plus clinic networks, where procurement centralization extracts volume discounts unavailable to independent practitioners.
Europe Invisible Orthodontics Market Segmentation
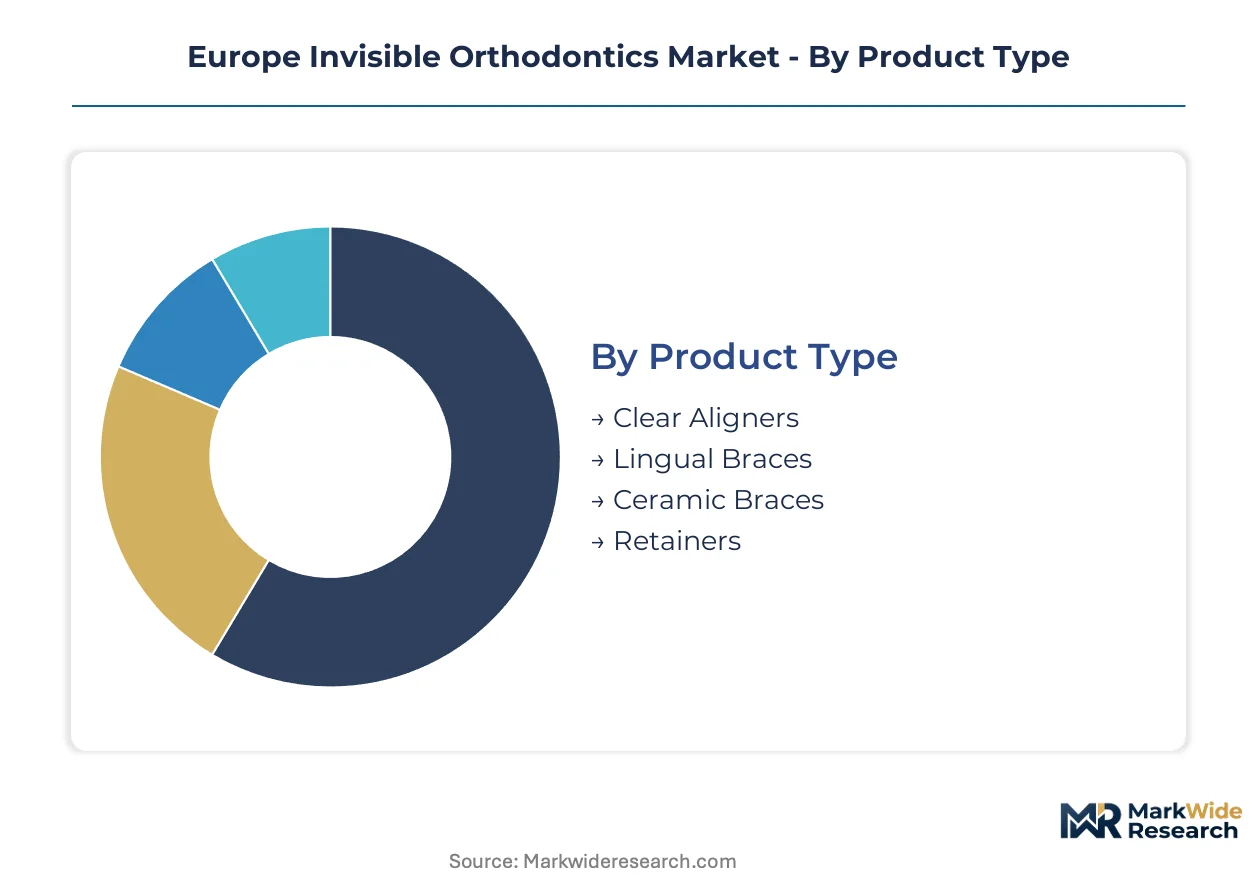
Segmentation in Europe invisible orthodontics reveals how clinical workflows, patient demographics, and procurement channels fragment purchasing power across distinct value pools. Each dimension carries different margin profiles and regulatory exposure that shape manufacturer go-to-market priorities.
Product Type:
After-sales service intensity varies sharply across appliance categories, with removable systems demanding ongoing patient monitoring and fixed alternatives requiring specialized intervention protocols.
- Clear Aligners:Medical-grade thermoplastic polyurethane or multilayer polyethylene terephthalate glycol compositions deliver 0.5 to 1.5 Newtons per tooth through sequential tray replacement. Demand concentrates among working-age professionals in the United Kingdom and Germany who prioritize removability for career-visible settings; adult willingness to pay premiums sustains manufacturer margins despite material cost volatility.
- Lingual Braces:Bonded fixed appliances positioned behind anterior teeth employ custom-fabricated archwires and brackets engineered for complete aesthetic concealment. Deployment clusters in affluent urban orthodontic clinics across Paris, London, and Munich where specialized orthodontist training justifies elevated chair-time economics and premium pricing tiers.
- Ceramic Braces:Tooth-colored polycrystalline alumina or zirconia brackets offer fixed-appliance reliability at moderate cost, retaining share among teenagers seeking durability without metallic visibility.
- Retainers:Post-treatment removable or fixed devices maintain tooth position, generating recurring revenue streams through replacement cycles and long-term patient relationships.
Clear aligners hold the largest share; momentum sits with multilayer polyurethane compositions as manufacturing scale reduces per-unit costs.
End User:
Cost tier stratification separates high-discretion adult self-pay demand from price-sensitive adolescent segments and institutional procurement.
- Adults:Self-directed aesthetic correction drives premium appliance selection and accelerated protocol adoption across Germany, France, and the United Kingdom.
- Teenagers:Parent-influenced purchasing favors ceramic braces for reliability and cost predictability, with clear aligner uptake growing among older adolescents.
- Orthodontic Clinics:High-volume specialty practices centralize procurement through subscription-based unlimited-aligner contracts that flatten variable costs and lock supplier relationships.
- Dental Hospitals:Academic and public institutions prioritize CE-marked devices with established clinical evidence, extending procurement timelines but offering volume stability.
Orthodontic clinics generate the highest per-site revenue; adults are expanding most quickly as aesthetic dentistry normalizes among professionals.
Treatment Duration:
Volume concentration shifts toward compressed protocols as accelerated orthodontic techniques reduce average case times and expand addressable candidacy.
- Short-term:Six-to-twelve-month regimens using high-frequency vibration adjuncts and micro-osteoperforation are climbing the fastest among adult professionals seeking rapid results.
- Intermediate-term:Twelve-to-eighteen-month cases balance complexity management with patient commitment, representing the core revenue base for established practices.
- Long-term:Eighteen-to-twenty-four-month or extended treatments address severe malocclusions, commanding higher total fees but slower patient throughput.
- Maintenance:Indefinite retainer wear and periodic refinement generate recurring low-intensity revenue with minimal clinical labor.
Intermediate-term cases anchor current volume; short-term protocols are gaining share fastest as technology compresses treatment windows.
Distribution Channel:
Supply concentration in direct sales and dental practice relationships reflects the technical consultation intensity inherent to orthodontic appliance selection.
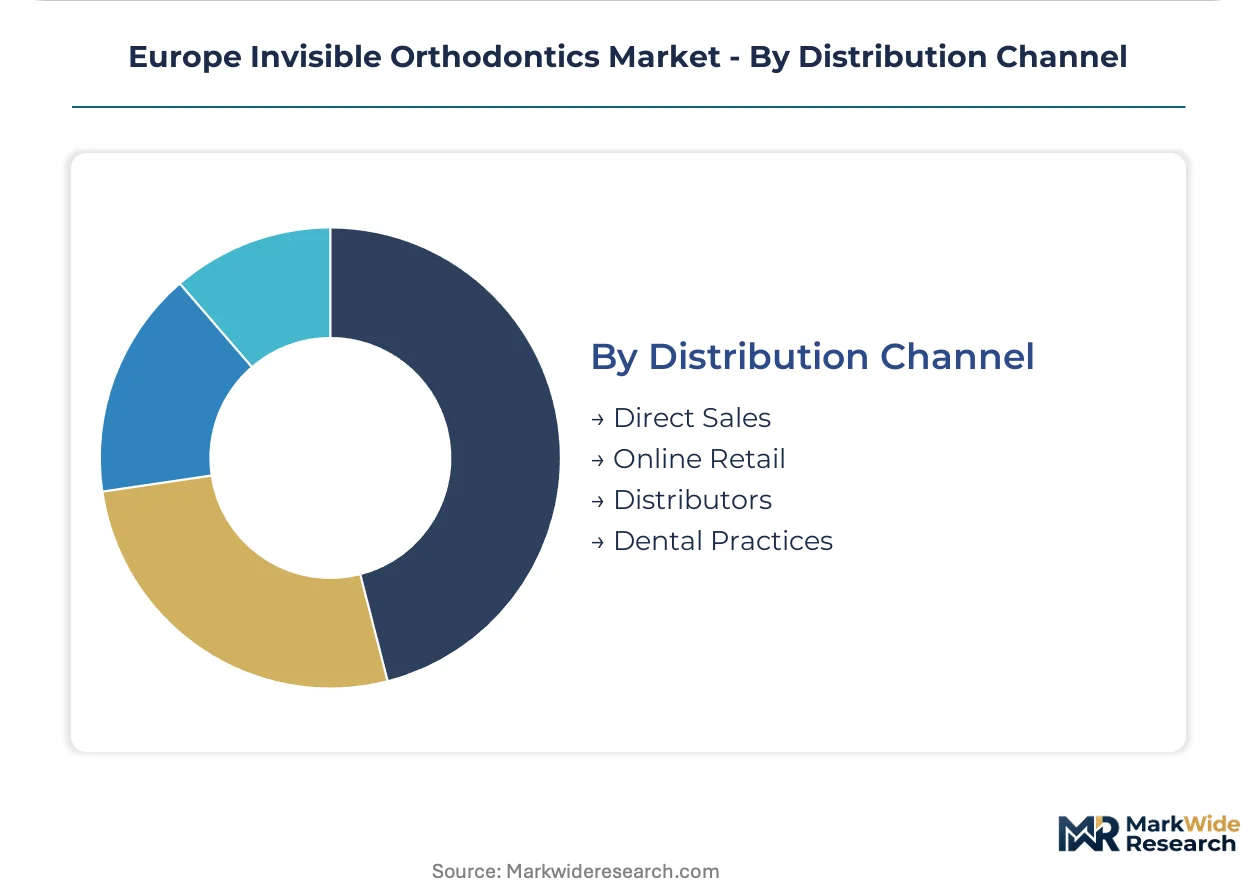
- Direct Sales:Manufacturer field forces engage high-volume orthodontic groups and dental service organizations with 15-plus clinic networks, centralizing procurement decisions and extracting volume discounts unavailable to independent practitioners.
- Online Retail:Direct-to-consumer aligner platforms bypass traditional clinical channels in select European markets, though MDR compliance and national dental board restrictions limit scalable deployment.
- Distributors:Regional dental supply intermediaries serve fragmented independent practices in Italy and Spain where clinic density remains below German levels.
- Dental Practices:General dentistry referrals to orthodontic specialists create indirect demand capture, with intraoral scanner placement influencing aligner brand selection.
Direct sales commands the largest share; dental practices are expanding most quickly as digital workflow integration tightens manufacturer-practice relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working-age professionals in Germany, the United Kingdom, and France concentrate purchasing power for aesthetic dental correction, while orthodontic clinic density and regulatory frameworks fragment market access across Southern and Northern Europe.
Germany
Adult self-pay demand for clear aligners and accelerated treatment protocols dominates volume, with Berlin and Munich hosting the densest orthodontic clinic networks. BfArM-delegated notified bodies enforce MDR certification timelines that extend CE marking duration for new aligner materials. The Rhine-Ruhr corridor anchors manufacturing integration between digital workflow platforms and thermoforming facilities.
United Kingdom
London's professional workforce sustains premium positioning for removable clear polymer aligners in career-visible settings. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR frameworks while maintaining separate UKCA marking requirements post-Brexit. Dental service organizations in Greater Manchester and Birmingham centralize procurement through subscription-based unlimited-aligner contracts.
France
Parisian affluent urban clinics concentrate deployment of lingual braces requiring specialized orthodontist training and elevated chair-time economics. ANSM review timelines for conformity assessments create notified body capacity constraints extending approval cycles. The Lyon-Grenoble corridor hosts emerging digital workflow platform adoption reducing specialist labor intensity.
Italy
Orthodontic clinic density remains 40% below German levels, creating whitespace for digital intraoral scanning and AI-driven treatment planning penetration. National dental board guidelines maintain variable certification requirements for clear aligner therapy that slow workforce expansion. Milan and Rome concentrate private aesthetic dentistry demand among northern Italian professionals.
Spain
Barcelona and Madrid dental hospitals prioritize CE-marked devices with established clinical evidence, extending procurement timelines but offering volume stability. Underpenetration relative to Northern European benchmarks creates opportunity for direct-to-clinic manufacturing integration bypassing traditional laboratory intermediaries. Regional dental supply distributors serve fragmented independent practices in Valencia and Andalusia.
Europe Invisible Orthodontics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around notified body-approved manufacturers. Premium-tier scanner-aligner ecosystems, integrated digital workflow platforms, and CAD/CAM infrastructure extensions from restorative bases define three strategic archetypes. M&A activity targets digital workflow capabilities, while capacity expansion concentrates in direct-to-clinic thermoforming and 3D printing integration.
Among Swiss-anchored conglomerates, Institut Straumann AG exemplifies integrated digital workflow platform positioning. Align Technology represents the scanner-aligner ecosystem archetype with proprietary hardware-software lock-in. Dentsply Sirona occupies a position bridging CAD/CAM restorative infrastructure into orthodontic applications. These three entities anchor competitive dynamics around digital workflow control, notified body certification leverage, and subscription-based procurement consolidation.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| Envista Holdings |
| Institut Straumann AG |
| 3M |
| Henry Schein |
| Dentaurum GmbH & Co. KG |
| FORESTADENT - Bernhard Foerster GmbH |
| TP Orthodontics |
| Others |
Supply & Pricing Matrix
German and Dutch petrochemical producers concentrate medical-grade thermoplastic polyurethane supply, anchoring margin pools downstream with clear aligner manufacturers who negotiate volume commitments against raw material indexation clauses. This upstream concentration transfers cost volatility risk to appliance brands while preserving pricing power for notified body-certified producers.
Pricing Analysis
Cost-plus contracts with polyethylene terephthalate glycol indexation dominate procurement between aligner manufacturers and thermoplastic suppliers. Three-tier pricing structure across premium multilayer polyurethane, standard single-material aligners, and economy ceramic brackets separates patient segments by clinical complexity tolerance. Pricing pressure stems from subscription-based unlimited-aligner contracts flattening per-unit margins for high-volume orthodontic groups. Teenagers and parent-influenced purchasers exhibit highest price sensitivity, while working-age professionals in London and Munich accept premium positioning for removability.
Supply Chain Analysis
Tariff exposure between German chemical producers and French orthodontic manufacturers dominates supply chain risk assessment for thermoplastic input sourcing. Manufacturing concentrates in Germany, the Netherlands, and Switzerland for medical-grade polymer production, with Italy and Spain hosting downstream thermoforming and 3D printing fabrication. Raw material dependencies rest on petroleum-derived polyurethane, polyethylene terephthalate glycol, and photopolymer resins for dental model printing. Distribution runs through direct sales forces engaging dental service organizations alongside regional distributors serving fragmented independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe invisible orthodontics market sits in cyclical recovery as adult aesthetic dentistry demand rebounds from pandemic-deferred treatment and accelerated protocols expand addressable case volumes.
For Market Incumbents: Harden notified body certification leverage by deepening relationships with BfArM-delegated assessors in Germany and ANSM in France, extending approval timelines that marginal competitors cannot absorb. Anchor capacity expansion in direct-to-clinic thermoforming integration, bypassing dental laboratory intermediaries to capture margin and reduce turnaround time against emerging digital workflow platforms.
For New Entrants and Emerging Players: Establish a beachhead in Spain and Italy where orthodontic clinic density remains 40% below German benchmarks and national dental board certification variability slows incumbent workforce expansion. Target independent practices in Valencia and Andalusia through distributor partnerships, then migrate toward direct sales as volume thresholds justify field force investment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed dental service organizations operating 15-plus clinic networks across Greater Manchester and Birmingham, where procurement centralization has extracted subscription-based unlimited-aligner contracts. Five-to-ten year viability hinges on AI-integrated treatment planning platform differentiation and EU AI Act algorithm classification outcomes. The signal to watch is notified body capacity expansion in France and Germany, which would accelerate CE marking timelines and compress competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | MDR certification with BfArM-delegated notified bodies filters marginal suppliers and consolidates demand. |
| Digital Workflow Platform Integration | AI-driven treatment planning embedded in Straumann and Align Technology ecosystems locks clinic relationships. |
| Direct-to-Clinic Manufacturing Buildout | In-house thermoforming and 3D printing bypasses dental laboratory intermediaries, capturing margin and compressing turnaround. |
| Subscription-Based Procurement Consolidation | Unlimited-aligner contracts with dental service organizations flatten variable costs and lock supplier relationships. |
| EU AI Act Compliance Architecture | Automated treatment planning algorithm documentation with notified bodies in Germany and France shapes competitive positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU MDR submission databases, orthodontic clinic procurement records, and petrochemical trade flow data. Orthodontic clinic directors, biomedical engineers at aligner manufacturers, notified body assessment officers in Germany and France, and dental service organization procurement heads provided structured interviews. Secondary validation drew from EMA biocompatibility standards documentation, national dental board guidelines in Italy and Spain, and customs records for thermoplastic polyurethane imports. Bottom-up clinic density modeling and top-down manufacturer revenue triangulation anchored market sizing.
Forecast inputs include patient demographic shifts, regulatory approval timeline trajectories, and digital workflow adoption curves across the projection horizon. Segmentation dimensions modeled encompass product type, end user, treatment duration, and distribution channel, with additional weighting for AI-integrated versus conventional treatment planning platforms. CAGRs derive from compounding annual patient volume growth against average selling price trajectories, with specific sensitivity to accelerated orthodontic protocol penetration and subscription contract conversion rates.
Stress conditions across petrochemical price volatility, notified body capacity constraints, and EU AI Act algorithm classification severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about adult aesthetic dentistry demand normalization and MDR compliance cost absorption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Global Medical Implants Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Soft Contact Lenses Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Implantable Drug Delivery Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Next-Generation Neurofeedback Device Market