
 Oxygen Conservers Market | 2026-2036
Oxygen Conservers Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Conservers Market Analysis
North American medical device manufacturing is consolidating as oxygen conserver production gravitates toward established respiratory equipment hubs. Inogen leverages direct-to-patient channel control to sustain brand loyalty among homecare users. Koninklijke Philips N.V. anchors its position through R&D intensity in pulse dose algorithms. Invacare Corporation competes on geographic dominance, with distribution networks spanning rehabilitation centers across multiple states.
Oxygen conservers are pneumatic or electronic devices that regulate oxygen delivery from compressed gas cylinders or liquid oxygen systems by releasing oxygen only during inhalation, typically achieving conservation ratios between 3:1 and 7:1 compared to continuous flow. Their primary purpose is to extend cylinder duration for ambulatory patients requiring long-term oxygen therapy, reducing refill frequency and improving mobility. Portable conservers lead volume shipments due to patient demand for mobility outside clinical settings, while electronic conservers command premium positioning through algorithm-driven dose synchronization. Homecare end users represent the fastest-expanding segment as discharge protocols and remote monitoring technologies enable domestic oxygen management.
FDA 510(k) clearance requirements and ISO 80601-2-69 standards govern device safety and electromagnetic compatibility for oxygen conservers in the United States, directly shaping product development timelines and market entry costs. CMS national coverage determinations for home oxygen therapy establish reimbursement thresholds that influence provider procurement decisions and patient access. Stakeholders must monitor evolving pulse dose validation protocols and competitive bidding program adjustments to align portfolio investments with reimbursement trajectories.
Market Dynamics
The oxygen conservers market pivots on CMS competitive bidding program adjustments, which compress reimbursement rates for home oxygen equipment while simultaneously accelerating provider consolidation and technology substitution toward algorithm-driven delivery systems.
Growth Catalysts
- Ambulatory oxygen therapy protocols:Germany's statutory health insurance framework mandates portable oxygen systems for COPD patients with mobility requirements, expanding prescription volumes for electronic conserver units in outpatient settings.
- ISO 80601-2-69 harmonization:Electromagnetic compatibility standards for respiratory equipment reduce technical barriers to cross-border device certification, enabling faster market entry for pulse dose innovations across European Economic Area jurisdictions.
- Liquid oxygen system phase-out:Homecare providers in the United States are converting cylinder-based fleets to conserve-enabled compressed gas configurations as stationary LOX infrastructure reaches end-of-life.
Market Restraints
- Aluminum alloy cylinder supply concentration:Raw material sourcing for lightweight portable cylinders clusters among North American and Chinese smelters, exposing manufacturers to tariff volatility and logistics bottlenecks.
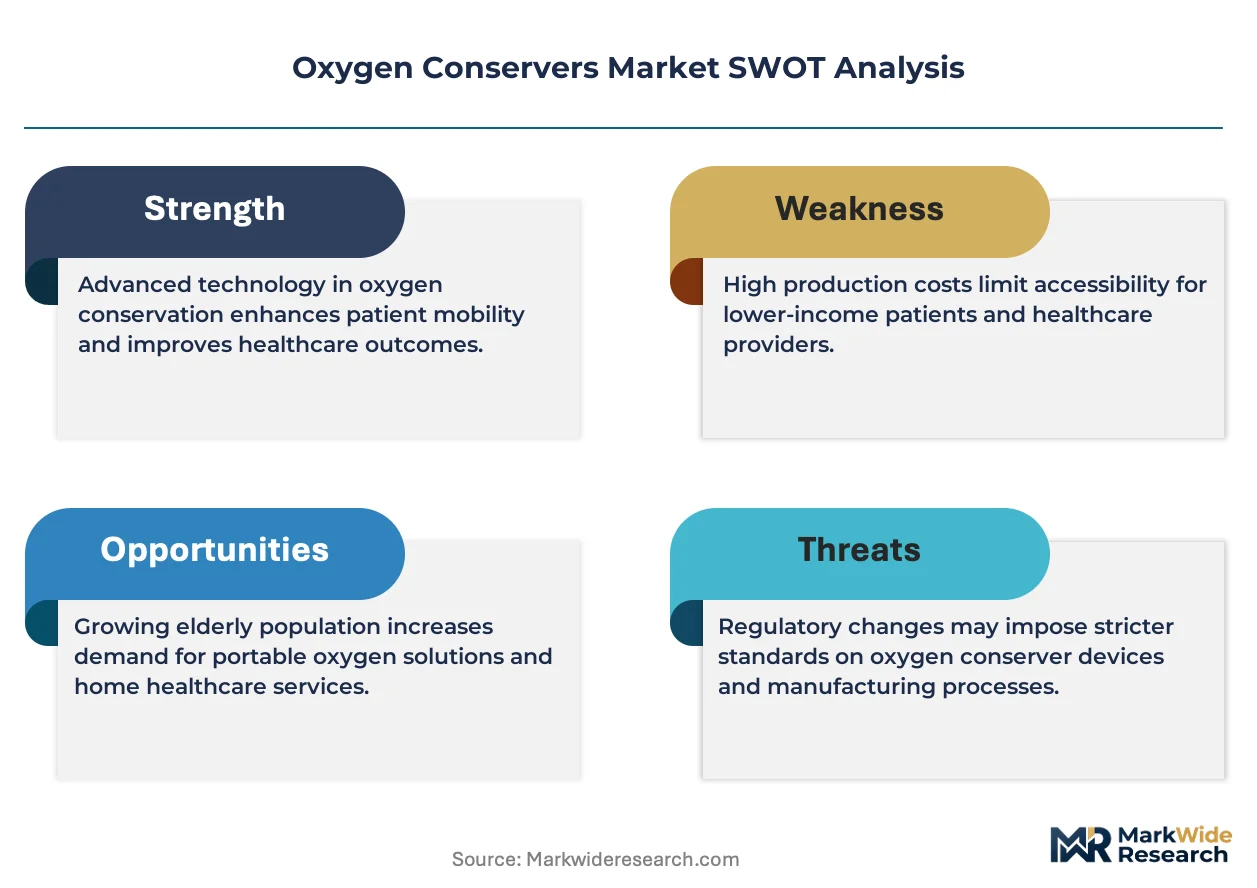
- FDA 510(k) pathway duration:Predicate device identification requirements for novel pulse dose algorithms extend regulatory review timelines, delaying revenue recognition for R&D-intensive product launches.
- Stationary oxygen concentrator substitution:Plug-in home units with integrated conserving functions capture price-sensitive patients who might otherwise select portable cylinder-based alternatives.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled conservers transmitting usage data to clinical dashboards create recurring revenue streams through software subscription models attached to hardware deployments.
- India's PLI scheme for medical devices:Production-linked incentive structures for respiratory equipment manufacturing attract contract assembly investments serving South Asian and Middle Eastern export markets.
- Japan's super-aging prefectures:Rural municipalities in Hokkaido and Tottori face acute homecare workforce shortages, creating demand for automated oxygen delivery systems requiring minimal patient manipulation.
Industry Challenges
- Pulse dose validation expertise scarcity:Biomedical engineering talent capable of calibrating breath-detection algorithms against heterogeneous patient respiratory patterns commands premium compensation, constraining development velocity for mid-tier manufacturers.
- Legacy fleet interoperability:Homecare providers operating mixed-vendor cylinder inventories encounter connector standardization gaps when deploying next-generation conservers across existing patient bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Conservers Market |
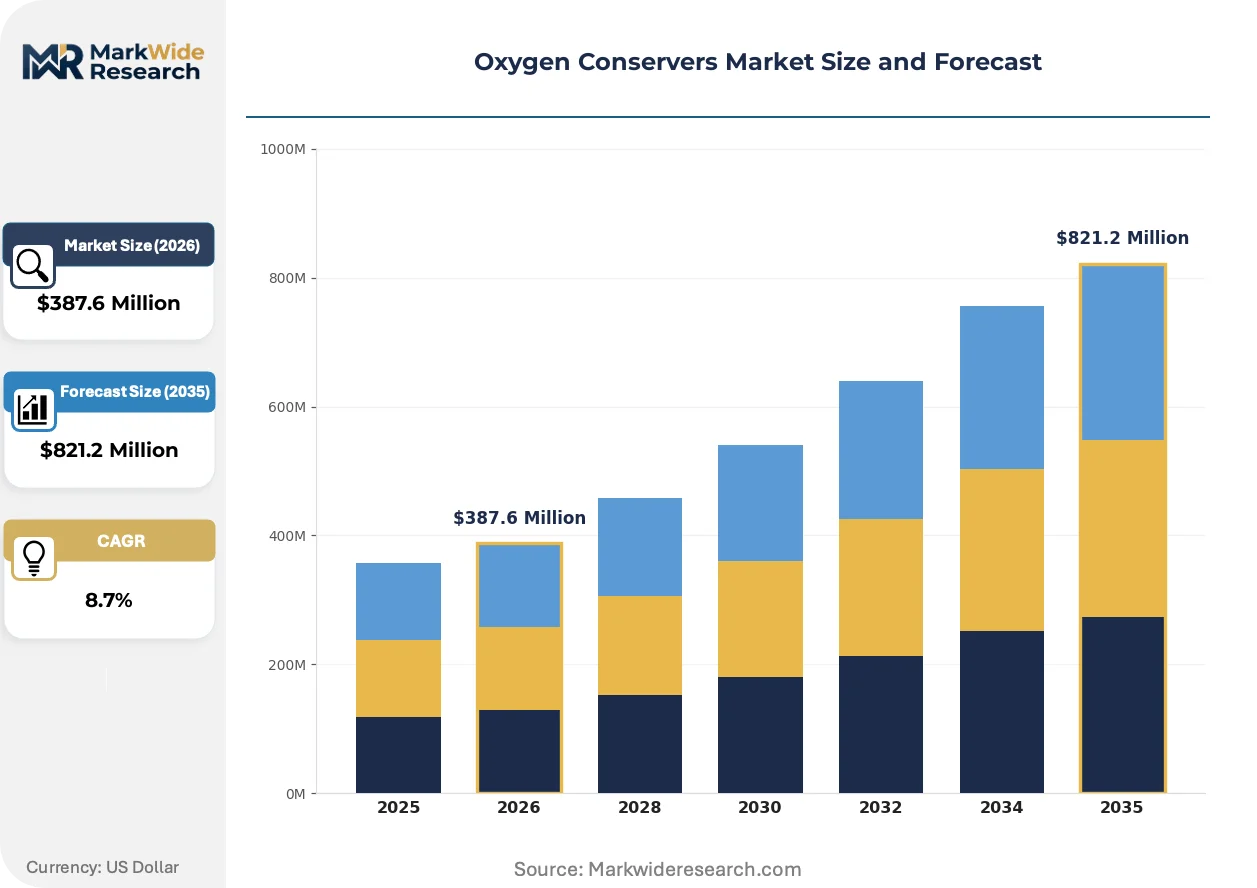
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Conservers, Stationary Conservers, Handheld Conservers, Liquid Conservers End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Technology: Electronic Conservers, Mechanical Conservers, Pulse Dose Technology, Standard Flow Technology Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesalers |
| Companies Covered | Inogen, Inc., Koninklijke Philips N.V., Invacare Corporation, Drive DeVilbiss Healthcare, Medline Industries, Inc., Precision Medical, Inc., Chart Industries, CAIRE Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Conservers Market Emerging Trajectories
Algorithmic breath detection is displacing mechanical pneumatic sensing as the dominant oxygen delivery control paradigm, with downstream effects on device pricing tiers, service revenue models, and provider procurement specifications.
Machine learning inference at the device edge is automating real-time adjustment of pulse dose volumes based on activity pattern recognition. Homecare providers deploying these systems report reduced emergency interventions for desaturation events. The technology is automating clinical oversight functions that previously required respiratory therapist home visits, compressing operational cost structures for distributed oxygen service networks.
EU MDR transition deadlines for Class IIa respiratory devices are forcing portfolio rationalization among manufacturers serving European markets. Technical documentation requirements for clinical evidence and post-market surveillance have expanded internal regulatory affairs headcounts. Small and mid-sized device firms without legacy MDD certificates face accelerated market exit timelines as notified body capacity constraints persist.
Direct-to-patient e-commerce channels are capturing oxygen conserver transactions previously mediated through durable medical equipment distributors. Sleep apnea equipment retailers and online respiratory specialists now stock portable conserving devices for cash-pay customers seeking travel configurations. This channel rotation is most advanced in the United States, where high-deductible health plans increase price transparency sensitivity among ambulatory oxygen users.
Oxygen Conservers Market Segmentation
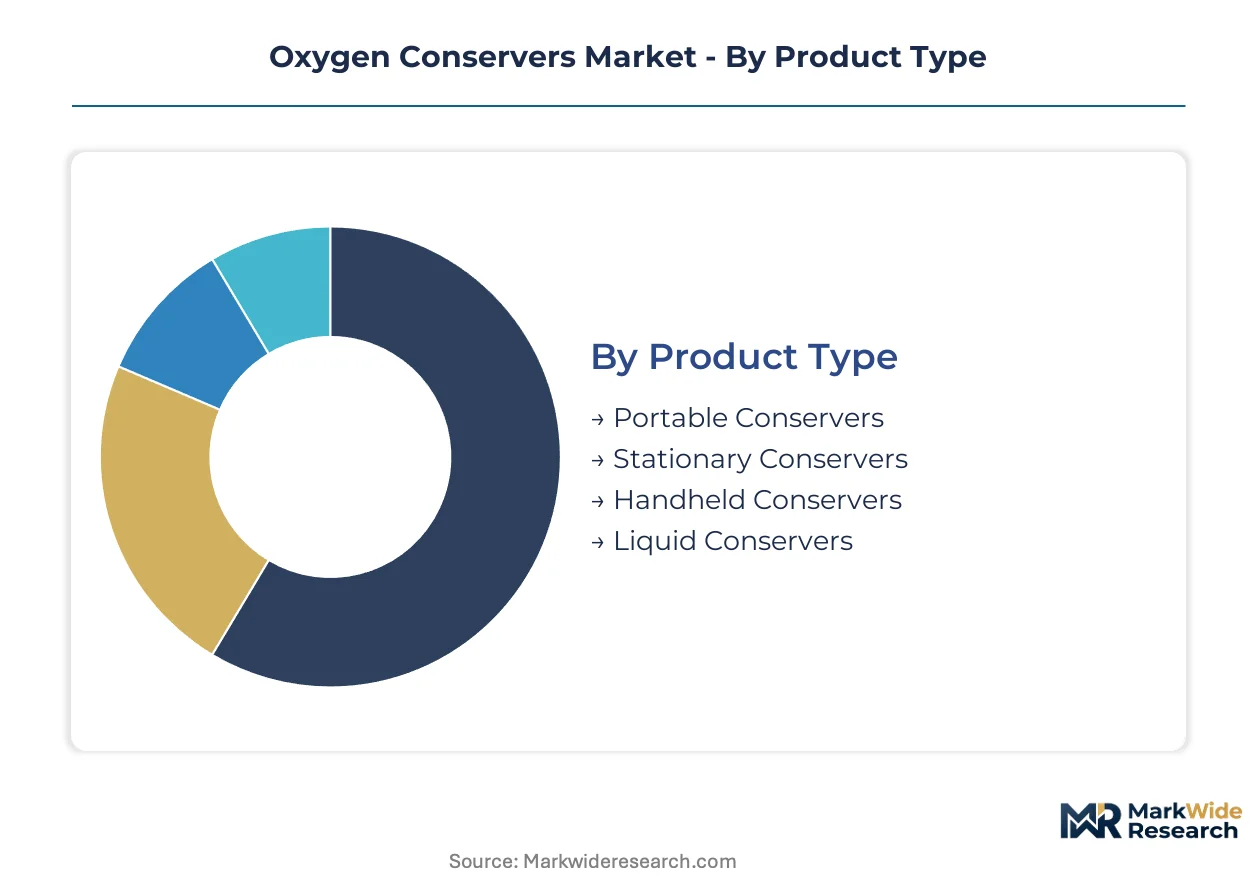
Oxygen conserver segmentation reveals how device specifications align with patient mobility requirements and care settings. Product architecture, delivery technology, and procurement channels each create distinct competitive arenas with unique margin profiles and regulatory exposures.
Product Type:
Form factor and patient mobility capacity define this segmentation axis, with weight, cylinder compatibility, and conservation ratio serving as primary technical differentiators.
- Portable Conservers:Lightweight units under 2 pounds attach directly to aluminum alloy cylinders, achieving conservation ratios up to 7:1 through pneumatic or electronic pulse dose mechanisms. Demand concentrates among ambulatory COPD patients in Germany and the United States where statutory insurance frameworks mandate portable oxygen for qualified outpatients, though aluminum supply concentration among North American and Chinese smelters exposes procurement to tariff volatility.
- Stationary Conservers:Fixed-installation units integrate with high-pressure manifold systems in clinical or residential settings, typically employing continuous flow regulation rather than breath-synchronized delivery. Procurement volumes cluster in US rehabilitation centers and Japanese rural municipalities facing homecare workforce shortages, with plug-in oxygen concentrators capturing price-sensitive patients who might otherwise select cylinder-based alternatives.
- Handheld Conservers:Ultra-compact devices designed for short-duration mobility and travel applications prioritize minimal weight over conservation efficiency.
- Liquid Conservers:Specialized units interface with cryogenic oxygen reservoirs, now declining as US homecare providers convert cylinder-based fleets away from end-of-life stationary LOX infrastructure.
Mature deployment sits with Stationary Conservers in institutional settings. Newer deployment is concentrated in Portable Conservers as post-acute care shifts toward domestic settings.
End User:
Care setting determines device specification requirements, with reimbursement pathways and clinical oversight intensity varying sharply across delivery environments.
- Homecare:Patients managing long-term oxygen therapy in residential settings require devices balancing conservation efficiency with minimal manipulation complexity. This segment is expanding most quickly as US discharge protocols and remote monitoring technologies enable domestic oxygen management, though FDA 510(k) clearance requirements and ISO 80601-2-69 standards govern device safety and directly shape product development timelines.
- Hospitals:Acute care facilities deploy conservers primarily for patient transport and step-down units, prioritizing reliability and rapid cylinder exchange over advanced algorithmic features.
- Clinics:Outpatient pulmonary practices prescribe conservers for ambulatory oxygen trials and portable system fittings.
- Rehabilitation Centers:Post-acute facilities across multiple US states source conservers through Invacare Corporation distribution networks, with geographic dominance shaping competitive positioning in this channel.
Procurement volume leadership rests with Hospitals. Steepest expansion trajectory belongs to Homecare as remote monitoring integration creates recurring revenue streams through software subscription models.
Technology:
Control mechanisms separate premium algorithm-driven systems from legacy pneumatic designs, with downstream effects on pricing tiers and service revenue potential.
- Electronic Conservers:Microprocessor-controlled units employ breath-detection sensors and pulse dose algorithms to synchronize oxygen release with inhalation phases, enabling real-time adjustment based on activity pattern recognition. Koninklijke Philips N.V. anchors market position through R&D intensity in this domain, with machine learning inference at the device edge automating clinical oversight functions that previously required respiratory therapist home visits.
- Pulse Dose Technology:Discrete delivery mode releasing oxygen only during initial inhalation phase, implemented across both electronic and mechanical platforms.
- Mechanical Conservers:Pneumatic sensing mechanisms without electronic components offer lower cost and electromagnetic immunity but sacrifice conservation precision and adaptive response.
- Standard Flow Technology:Continuous delivery without breath-synchronization provides baseline oxygen supply for patients with irregular respiratory patterns.
Technology substitution is accelerating toward Electronic Conservers as algorithmic breath detection displaces mechanical pneumatic sensing. Legacy mechanical platforms retain position in price-sensitive procurement.
Distribution Channel:
Channel structure determines margin capture and patient access, with direct-to-patient models disrupting traditional durable medical equipment intermediation.
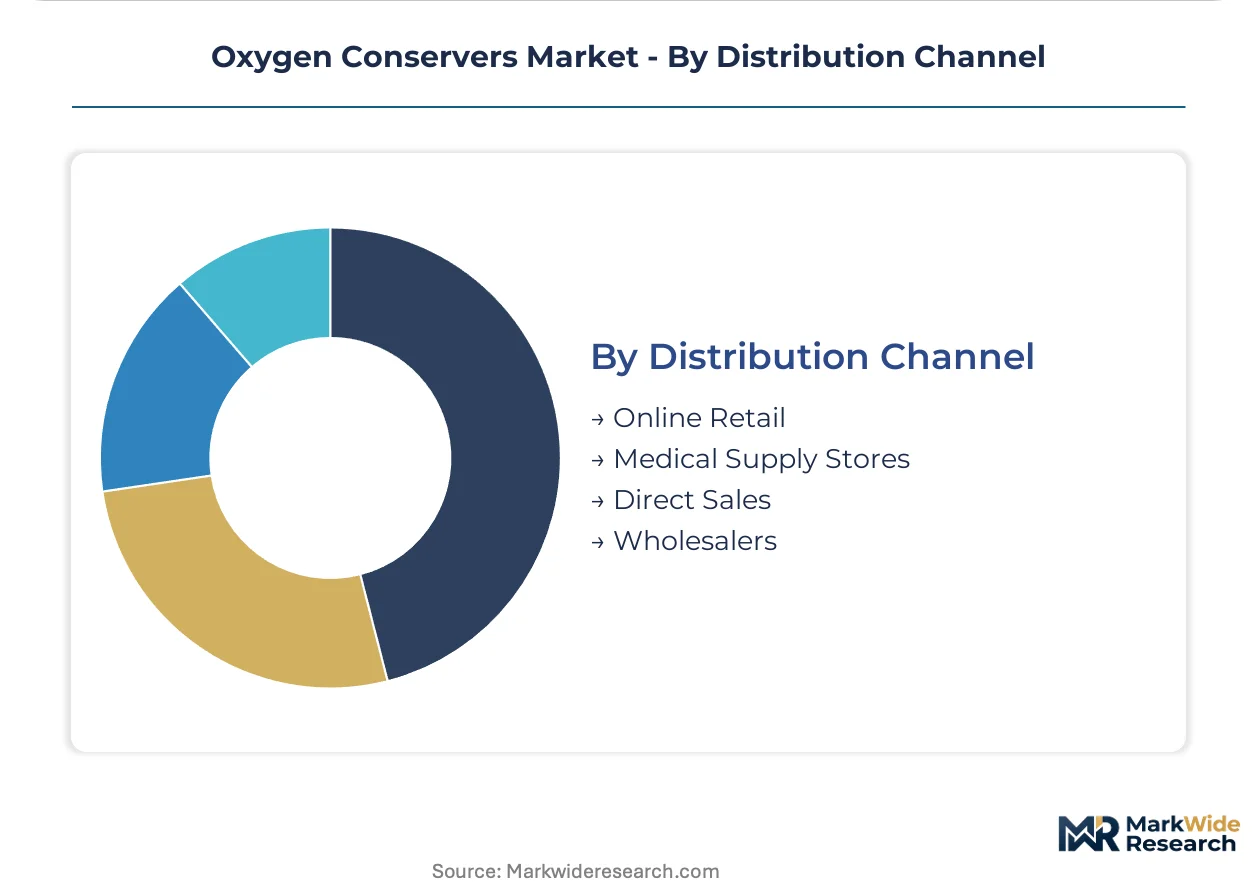
- Direct Sales:Manufacturer-controlled channels enable patient relationship ownership and subscription service attachment. Inogen leverages direct-to-patient channel control to sustain brand loyalty among homecare users, with this model most advanced in the United States where high-deductible health plans increase price transparency sensitivity.
- Online Retail:E-commerce platforms capture cash-pay transactions for travel configurations, with sleep apnea equipment retailers and online respiratory specialists now stocking portable conserving devices.
- Medical Supply Stores:Local durable medical equipment distributors maintain relationships with Medicare and Medicaid beneficiaries.
- Wholesalers:Aggregated procurement serves institutional buyers and regional provider networks.
Channel concentration remains with Medical Supply Stores for insured populations. Fastest channel expansion is occurring in Online Retail as direct-to-patient e-commerce captures transactions previously mediated through distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelter concentration in the Ohio River Valley and Chinese industrial corridors anchors cylinder manufacturing for portable oxygen conservers. Device assembly clusters track respiratory equipment hubs in the United States, Germany, and Japan.
United States
CMS competitive bidding program adjustments compress reimbursement rates while accelerating provider consolidation toward algorithm-driven delivery systems. FDA 510(k) clearance requirements and ISO 80601-2-69 standards govern device safety and electromagnetic compatibility, directly shaping product development timelines. North Carolina and Ohio host manufacturing operations where Inogen and Invacare Corporation maintain production facilities serving domestic homecare networks.
Germany
Statutory health insurance frameworks mandate portable oxygen systems for COPD patients with mobility requirements, expanding prescription volumes for electronic conserver units in outpatient settings. EU MDR transition deadlines for Class IIa respiratory devices force portfolio rationalization among manufacturers serving European markets. Bavaria and Baden-Württemberg concentrate medical device engineering talent where breath-detection algorithm development occurs.
Japan
Rural municipalities in Hokkaido and Tottori face acute homecare workforce shortages, creating demand for automated oxygen delivery systems requiring minimal patient manipulation. METI industrial policy supports domestic production of respiratory equipment through targeted subsidies for aging-care technology. The Kansai region around Osaka maintains precision manufacturing capabilities for miniaturized pneumatic components.
India
Production-linked incentive structures for respiratory equipment manufacturing under the PLI scheme attract contract assembly investments serving South Asian and Middle Eastern export markets. CDSCO medical device regulations establish quality benchmarks for imported and domestically produced conservers. Gujarat and Karnataka emerge as assembly hubs where multinational OEMs source cost-optimized electronic pulse dose units.
China
Domestic demand for ambulatory oxygen therapy rises with COPD prevalence among aging urban populations in Beijing and Shanghai. NMPA medical device registration requirements align with international standards to facilitate export certification for local manufacturers. The Yangtze River Delta concentrates aluminum alloy cylinder fabrication capacity serving both domestic OEMs and export markets.
Oxygen Conservers Market Vendor Landscape
Global majors compete with regional champions across algorithmic breath-detection technology and direct-to-patient distribution channels. Market structure tilts toward consolidation among R&D-intensive players capable of navigating FDA and EU MDR regulatory pathways while maintaining pulse dose validation expertise. Three archetypes dominate: integrated respiratory equipment conglomerates with diversified portfolios, specialized portable oxygen device manufacturers with channel control, and contract assemblers serving price-sensitive procurement. Competitive moves center on technology licensing for machine learning inference at the device edge and strategic partnerships with homecare providers for remote monitoring integration.
Among US-based device manufacturers, Inogen, Inc. exemplifies the direct-to-patient channel control archetype, while Invacare Corporation anchors geographic dominance through rehabilitation center distribution networks. Koninklijke Philips N.V. represents the R&D-intensive conglomerate model with European headquarters and global respiratory equipment scale. These three entities occupy distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Inogen, Inc. |
| Koninklijke Philips N.V. |
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Medline Industries, Inc. |
| Precision Medical, Inc. |
| Chart Industries |
| CAIRE Inc. |
| Teleflex Incorporated |
| Others |
Supply Flow & Price Mechanics
Aluminum alloy price indices on the London Metal Exchange cascade through cylinder fabrication costs into three distinct pricing tiers for oxygen conserver procurement. Electronic pulse dose units with integrated remote monitoring command premium positioning against pneumatic alternatives, while CMS reimbursement compression forces providers toward volume-contracted sourcing arrangements that sacrifice margin for fleet standardization.
Pricing Analysis
Warranty and calibration service bundling separates premium electronic conserver offerings from unbundled pneumatic alternatives sold through cash-pay channels. Three-tier pricing structure across premium algorithm-driven, standard electronic, and economy pneumatic levels reflects FDA 510(k) certification investment and ISO 80601-2-69 compliance overhead. Price differentiation hinges on breath-detection precision grade and geographic service coverage radius. Cost compression in the standard tier is intensifying because homecare provider consolidation concentrates procurement leverage. Cash-pay patients through direct-to-patient e-commerce exhibit highest price sensitivity, while hospital systems prioritize reliability guarantees over unit economics.
Supply Chain Analysis
FDA 510(k) clearance and EU MDR Class IIa certification gate access to reimbursed procurement channels, filtering assembly partnerships toward established respiratory equipment hubs. Manufacturing concentrates in the United States, Germany, and China, with aluminum alloy cylinder sourcing anchored in North American and Chinese smelters. Component dependencies include precision pneumatic valves, microprocessor controllers, and breath-detection sensors. Single-source vulnerability in aluminum alloy supply exposes manufacturers to tariff volatility and logistics bottlenecks. Distribution runs through durable medical equipment wholesalers serving institutional buyers, with direct-to-patient e-commerce capturing growing cash-pay volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen conservers market sits in a technology-transition phase where algorithmic breath detection displaces mechanical pneumatic sensing as the dominant control paradigm. Machine learning inference at the device edge is automating clinical oversight functions and reshaping competitive positioning toward R&D-intensive players.
For Market Incumbents: Hedge against stationary oxygen concentrator substitution by deepening software subscription attachment rates to hardware deployments. Secure backward integration into aluminum alloy cylinder supply through long-term offtake agreements with Ohio River Valley and Yangtze River Delta smelters. Accelerate FDA 510(k) pathway investment for next-generation pulse dose algorithms before competitive bidding program adjustments further compress reimbursement headroom. For New Entrants and Emerging Players: Bluetooth-enabled remote patient monitoring integration offers a technology-first wedge into the homecare segment where legacy fleet interoperability gaps create switching friction. Target Japan's super-aging prefectures where rural homecare workforce shortages demand automated oxygen delivery with minimal patient manipulation. Pursue contract assembly partnerships under India's PLI scheme for respiratory equipment to serve South Asian and Middle Eastern export markets with cost-optimized electronic units. For Investors and Strategic Acquirers: The window for entry favors specialized portable oxygen device manufacturers with direct-to-patient channel control and pulse dose validation expertise. Long-term viability hinges on reimbursement strategy alignment with CMS national coverage determinations and EU MDR compliance capability. Watch competitive bidding program adjustments as the inflection indicator for provider consolidation velocity and technology substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways govern market entry timelines and product development investment recovery. |
| CE Marking Pathway | EU MDR Class IIa compliance enables access to German statutory insurance reimbursement frameworks. |
| Hospital System Partnership | GPO contracts with US rehabilitation networks secure volume procurement commitments against competitive bidding pressure. |
| Software Companion Development | Bluetooth-enabled usage analytics create recurring revenue streams attached to hardware deployments. |
| Reimbursement Strategy | Alignment with CMS national coverage determinations shapes provider procurement specifications and patient access. |
Methodological Framework
Document review covered FDA 510(k) filings, CMS Medicare data, EU MDR technical documentation, and hospital procurement databases, complemented by interviews with biomedical engineers, homecare provider operations directors, GPO contracts managers, and respiratory equipment distributors. Secondary validation drew from SEC 10-K disclosures, customs trade records, and notified body capacity reports. Bottom-up patient population modeling and top-down equipment replacement cycle analysis were triangulated against reimbursement trajectory assumptions.
Segment-level projections across product type, end user, technology, and distribution channel dimensions were generated through the forecast framework. CAGRs were derived from equipment replacement velocity, ambulatory oxygen therapy protocol expansion, and remote monitoring adoption curves. Industry-specific inputs included CMS competitive bidding program adjustment schedules, EU MDR transition deadlines, and aluminum alloy price index trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway modifications, raw material supply disruptions, and competitive bidding program structural reforms. Forecasts reflect documented assumptions about reimbursement stability and certification timeline continuity. A model refresh is warranted upon material change in CMS national coverage determinations or EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Hearing Loop Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Injection Pen Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Global Medical Composite Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Global Capnography Market