
 Artificial Retina Market | 2026-2036
Artificial Retina Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Retina Market Intelligence
Israel is rewriting competitive dynamics in artificial retina development through concentrated neurotechnology R&D clusters. Nano Retina leverages its photodiode array expertise to anchor advanced subretinal device pipelines. Second Sight Medical Products sustains market presence through extensive clinical trial infrastructure across North American and European sites. Pixium Vision competes on wireless transmission architectures that reduce surgical complexity for retinal surgeons.
An artificial retina constitutes a bioelectronic implant that restores partial vision by converting optical signals into electrical impulses delivered to surviving retinal neurons, typically employing microelectrode arrays with electrode densities exceeding 100 pixels per millimeter to stimulate bipolar or ganglion cell layers. These devices serve the primary commercial purpose of addressing inherited retinal dystrophies and age-related photoreceptor degeneration where pharmacological interventions remain ineffective. Epiretinal implants currently dominate procedural volumes due to established surgical accessibility and retinal surgeon familiarity, while subretinal devices represent the fastest-growing category as photodiode arrays achieve superior proximity to residual inner retinal circuitry. Wireless microstimulators are capturing margin pools by eliminating trans-scleral power cables and reducing long-term complication rates.
FDA breakthrough device designations and EMA's Medical Device Regulation collectively shape product standards, trial endpoints, and reimbursement pathways for artificial retina developers seeking commercial access. ISO 14155 clinical investigation standards and national ophthalmology society guidelines further constrain market entry to firms with robust quality management systems and longitudinal safety databases. Stakeholders must monitor evolving visual acuity endpoint definitions and payer evidence requirements as regulatory bodies calibrate approval thresholds against real-world functional outcomes.
Market Dynamics
The artificial retina market pivots on FDA breakthrough device designations compressing clinical trial timelines, which accelerates commercial access for subretinal implants while reshaping competitive positioning among neurotechnology developers.
Growth Catalysts
- EMA Medical Device Regulation:Germany's ophthalmology clinics are scaling implant procedures under harmonized European standards, creating procedural volume momentum across EMA-member states.
- Photodiode array miniaturization:Subretinal devices achieve superior proximity to residual inner retinal circuitry, displacing epiretinal alternatives in fastest-growing procedural categories.
- Wireless microstimulator adoption:Trans-scleral cable elimination reduces long-term complication rates, expanding addressable patient pools among surgeons prioritizing implant durability.
Market Restraints
- Electrode density manufacturing limits:Microelectrode arrays exceeding 100 pixels per millimeter require specialized semiconductor fabrication capacity concentrated in East Asian foundries.
- ISO 14155 compliance costs:Longitudinal safety database requirements constrain market entry to firms with robust quality management systems and multi-year clinical investigation funding.
- Pharmacological substitution:Gene therapy candidates for inherited retinal dystrophies threaten addressable patient pools for bioelectronic interventions in early-stage disease segments.
Strategic Opportunities
- India's CDSCO pathway acceleration:Underpenetrated South Asian markets present first-mover potential for cost-optimized wireless device architectures adapted to emerging healthcare infrastructure.
- AI-assisted surgical planning convergence:Integration of preoperative retinal imaging analytics with implant programming software reduces surgeon learning curves and expands addressable specialist pools.
- Japan's PMDA regenerative medicine framework:Hybrid device-biological product classifications create regulatory tailwinds for photodiode arrays combined with neurotrophic factor delivery systems.
Industry Challenges
- Retinal surgeon training bottlenecks:Subretinal implant procedures require specialized vitreoretinal surgical skills that concentrate in academic medical centers, limiting procedural scaling.
- Reimbursement evidence generation timelines:Payer visual acuity endpoint definitions vary across national ophthalmology society guidelines, complicating parallel market access strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Retina Market |
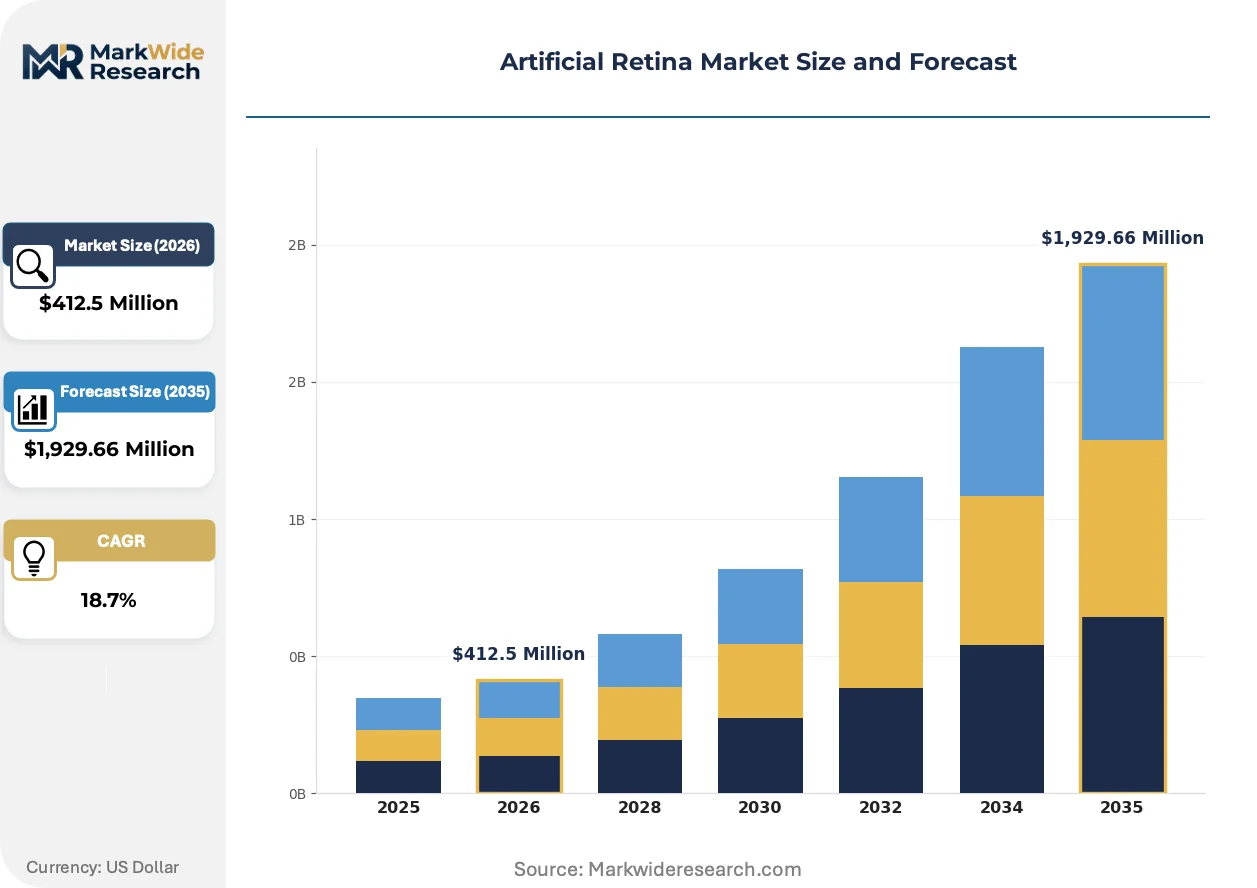
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epiretinal Implants, Subretinal Devices, Suprachoroidal Implants, Optic Nerve Implants, Wireless Microstimulators Application: Retinitis Pigmentosa, Age-related Macular Degeneration, Diabetic Retinopathy, Stargardt Disease, Choroideremia Technology: Microelectrode Arrays, Photodiode Arrays, Wireless Transmission, Visual Processing Units, Electroactive Polymers End User: Ophthalmology Clinics, Research Institutes, Vision Rehabilitation Centers, Specialized Hospitals |
| Companies Covered | Nano Retina, Optobionics, Second Sight Medical Products, Science Corp., Alcon Inc., Pixium Vision, Bionic Vision Technologies, LambdaVision Incorporated, Retina Implant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Retina Market Strategic Shifts & Innovations
Neurotechnology R&D clusters in Israel and the United States are compressing development cycles for next-generation retinal prosthetics, while regulatory harmonization efforts reshape trial endpoint standards across major markets.
Photodiode array technology is digitizing optical signal conversion in subretinal implants, replacing analog electrode stimulation with pixel-level light-to-electrical transduction. Retinal surgeons in Germany and the United States are adopting these arrays at accelerating rates for advanced retinitis pigmentosa cases. This digitization is compressing the performance gap between biological photoreceptors and artificial substitutes, enabling finer spatial resolution in restored vision.
REACH and RoHS substance restrictions are tightening material compliance requirements for implantable microelectrode arrays and wireless transmission components. European manufacturers must reformulate packaging and conductive materials to eliminate restricted substances from supply chains. Subretinal device developers targeting EMA approval face the most acute reformulation pressures, with several firms accelerating alternative metallurgy qualification programs.
Academic medical centers are consolidating artificial retina procurement through specialized ophthalmology purchasing cooperatives, displacing traditional distributor relationships. These cooperatives negotiate directly with device manufacturers for multi-site volume commitments, unbundling surgical training from hardware pricing. This concentration is most visible in the United States, where integrated delivery networks capture increasing shares of Medicare-reimbursed retinal implant procedures.
Artificial Retina Market Segmentation
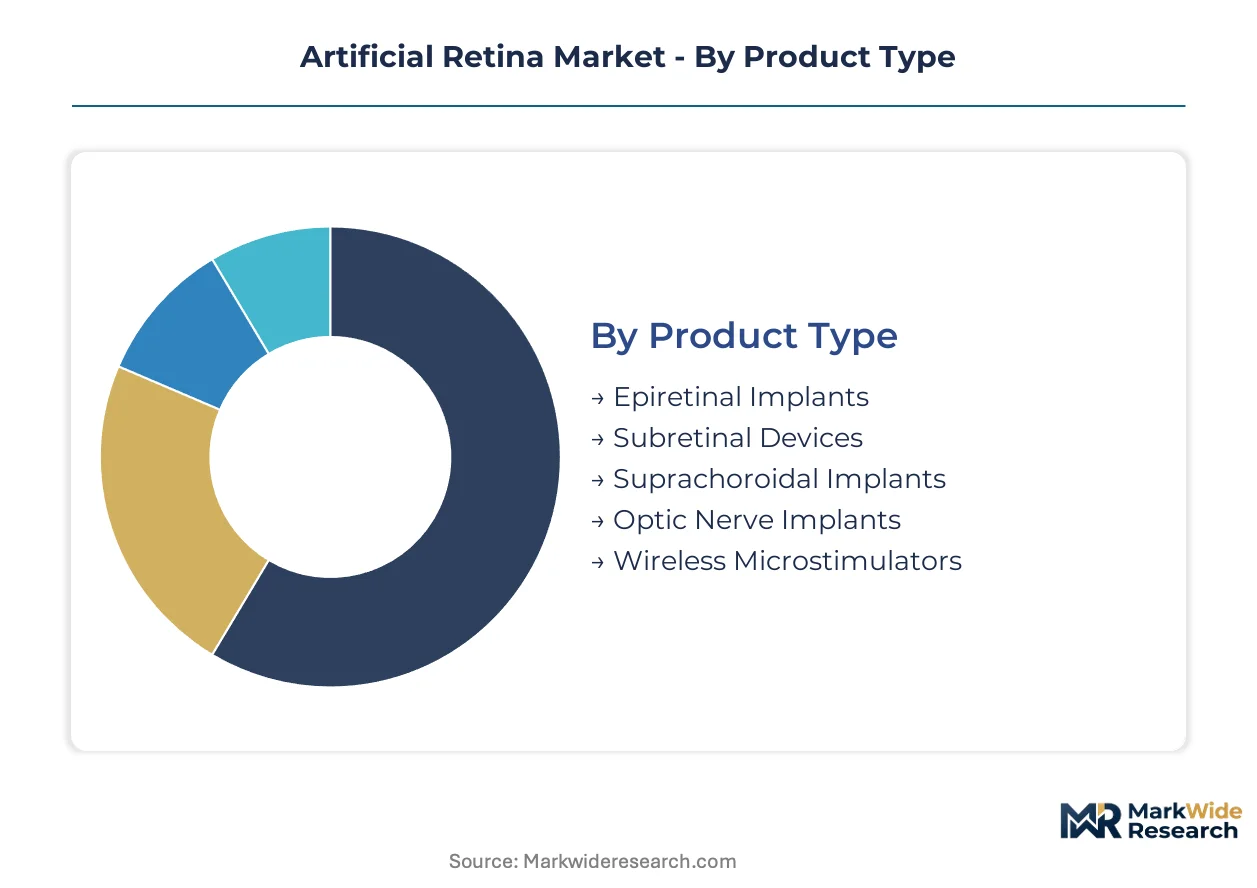
Segmentation in artificial retina markets reveals divergent technical requirements across implant architectures and patient populations. Each dimension carries distinct regulatory pathways, reimbursement structures, and surgical training demands that reshape competitive positioning among device developers.
Product Type:
After-sales service intensity varies sharply across implant categories, with wireless architectures demanding remote monitoring infrastructure while tethered systems require cable-related complication management.
- Epiretinal Implants:These devices position electrode arrays on the inner retinal surface, leveraging established vitrectomy surgical techniques. Demand concentrates in the United States, where FDA breakthrough designations compress trial timelines and retinal surgeon familiarity accelerates procedural scaling.
- Subretinal Devices:Photodiode arrays achieve direct proximity to bipolar cell layers, converting light to electrical signals without external cameras. Germany's ophthalmology clinics are scaling these procedures under EMA harmonized standards, driven by superior spatial resolution outcomes in advanced retinitis pigmentosa cases.
- Suprachoroidal Implants:Choroidal space positioning reduces surgical trauma to delicate retinal tissue.
- Optic Nerve Implants:Direct optic nerve stimulation bypasses damaged retinal circuitry entirely.
- Wireless Microstimulators:Trans-scleral power elimination reduces long-term complication rates and expands addressable surgeon pools prioritizing implant durability.
By volume, epiretinal implants lead. By expansion trajectory, subretinal devices are climbing the fastest.
Application:
Patient population heterogeneity drives divergent endpoint definitions across clinical trials, with inherited dystrophies requiring longitudinal functional vision metrics versus age-related conditions emphasizing activities-of-daily-living outcomes.
- Retinitis Pigmentosa:Inherited photoreceptor degeneration creates substantial addressable pools for bioelectronic intervention where pharmacological options remain ineffective. Clinical trial infrastructure concentrates in academic medical centers across the United States and Germany, with Medicare and statutory health insurance reimbursement pathways respectively established.
- Age-related Macular Degeneration:Late-stage geographic atrophy patients with bilateral vision loss represent expanding candidacy pools. Japan's PMDA regenerative medicine framework creates regulatory tailwinds for hybrid device-biological approaches targeting this segment.
- Diabetic Retinopathy:Proliferative disease complications occasionally progress to photoreceptor irreversible damage.
- Stargardt Disease:Juvenile macular dystrophy presents early-onset candidacy for implant intervention.
- Choroideremia:X-linked retinal degeneration with predictable progression patterns suits staged intervention protocols.
Retinitis pigmentosa dominates current procedural volumes. Age-related macular degeneration is gaining share fastest as demographic aging expands candidacy pools.
Technology:
Component cost structures stratify across analog versus digital signal processing architectures, with semiconductor fabrication requirements concentrating supply risk for high-density microelectrode arrays.
- Microelectrode Arrays:Silicon-based electrode grids exceeding 100 pixels per millimeter deliver spatially patterned stimulation to surviving retinal neurons. Specialized foundry capacity constraints in East Asia limit manufacturing scale for next-generation density targets.
- Photodiode Arrays:Pixel-level light-to-electrical transduction digitizes optical signal conversion without external image processing hardware. Israel's neurotechnology R&D clusters anchor development leadership for subretinal photodiode integration.
- Wireless Transmission:Inductive power and data coupling eliminates percutaneous connections, reducing infection risk and improving patient quality of life.
- Visual Processing Units:Real-time image enhancement algorithms optimize contrast and edge detection for prosthetic vision.
- Electroactive Polymers:Flexible conducting materials enable conformal electrode-tissue interfaces with reduced mechanical mismatch.
Microelectrode arrays command the largest installed base. Photodiode arrays are expanding most quickly as digitization compresses performance gaps with biological photoreceptors.
End User:
Procurement concentration is shifting toward specialized purchasing cooperatives that unbundle surgical training from hardware pricing, particularly visible in United States integrated delivery networks capturing Medicare-reimbursed procedures.
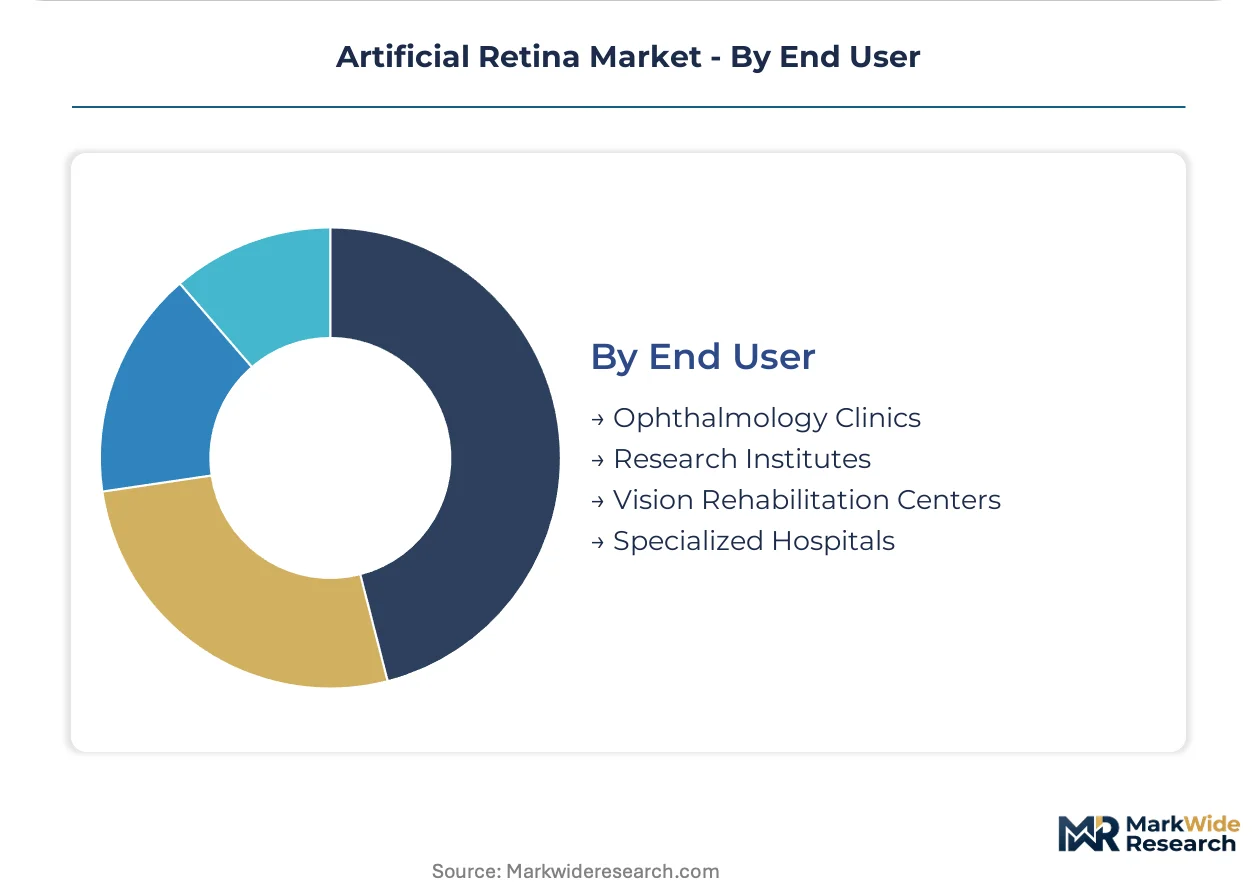
- Ophthalmology Clinics:Outpatient surgical facilities perform the majority of implant procedures under ambulatory surgery center reimbursement frameworks. Germany's clinic networks are scaling volumes under EMA Medical Device Regulation harmonized standards.
- Research Institutes:Academic medical centers concentrate longitudinal safety databases and next-generation protocol development. FDA breakthrough designation pathways and ISO 14155 compliance infrastructure requirements favor established institutional participants.
- Vision Rehabilitation Centers:Post-implant programming and patient training services extend device functional utility.
- Specialized Hospitals:Tertiary referral centers manage complex surgical candidates with comorbid ocular conditions.
Ophthalmology clinics lead by procedural volume. Research institutes are climbing fastest as regulatory evidence requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's ophthalmology clinics favor subretinal photodiode arrays for advanced retinitis pigmentosa cases, while the United States concentrates procedural volumes in epiretinal implants under FDA breakthrough pathways. Israel's neurotechnology R&D clusters anchor photodiode miniaturization leadership. Japan's aging demographics expand age-related macular degeneration candidacy pools for hybrid device-biological approaches.
United States
FDA breakthrough device designations compress clinical trial timelines for subretinal implants, accelerating commercial access. Medicare reimbursement pathways for retinal implant procedures concentrate in academic medical centers and integrated delivery networks. Retinal surgeon familiarity with vitrectomy techniques sustains epiretinal implant procedural dominance across major metropolitan hospital systems.
Germany
Statutory health insurance reimbursement for retinal implants scales procedural volumes in ophthalmology clinic networks. EMA Medical Device Regulation harmonized standards streamline cross-border device approval pathways for manufacturers. Heidelberg and Tübingen academic medical centers concentrate longitudinal safety databases and next-generation protocol development for photodiode array integration.
Israel
Concentrated neurotechnology R&D clusters in Rehovot and Haifa anchor photodiode array miniaturization pipelines for subretinal devices. Government-backed innovation programs fund early-stage retinal prosthetic development through technology transfer offices. Weizmann Institute-affiliated ventures supply specialized semiconductor fabrication expertise for high-density microelectrode arrays.
Japan
PMDA regenerative medicine framework creates regulatory tailwinds for hybrid device-biological product classifications targeting age-related macular degeneration. Tokyo and Osaka metropolitan areas concentrate tertiary referral centers managing late-stage geographic atrophy patients. National health insurance coverage expansion for retinal implants accelerates candidacy screening in aging population segments.
India
CDSCO pathway acceleration presents first-mover potential for cost-optimized wireless device architectures in underpenetrated South Asian markets. Hyderabad and Bengaluru medical device manufacturing clusters adapt implant designs to emerging healthcare infrastructure constraints. Government production-linked incentive schemes for medical electronics attract subretinal device assembly operations targeting price-sensitive patient segments.
Artificial Retina Market Key Industry Players
Capability concentration sits with photodiode array specialists; scale advantage sits with established ophthalmic device conglomerates. The market structures around three tiers: subretinal technology pioneers, epiretinal implant incumbents, and wireless transmission architecture specialists. Strategic moves center on clinical trial infrastructure consolidation and surgical training program unbundling from hardware pricing. Technology licensing agreements and backward integration into semiconductor fabrication capacity represent dominant competitive vectors.
Within the subretinal technology tier, Nano Retina and Pixium Vision exemplify photodiode array specialization. Second Sight Medical Products occupies a position bridging clinical trial infrastructure and epiretinal implant legacy presence. These three anchors represent divergent geographic R&D concentrations—Israeli photodiode expertise, French wireless transmission architecture, and North American clinical site networks—each commanding distinct regulatory relationship strengths across FDA, EMA, and PMDA jurisdictions.
| Leading Market Players |
|---|
| Nano Retina |
| Optobionics |
| Second Sight Medical Products |
| Science Corp. |
| Alcon Inc. |
| Pixium Vision |
| Bionic Vision Technologies |
| LambdaVision Incorporated |
| Retina Implant AG |
| Others |
Cost & Logistics Intelligence
Single-source dependency on East Asian semiconductor foundries for microelectrode arrays exceeding 100 pixels per millimeter determines both the premium-to-economy pricing spread across implant tiers and the elongated supply chain structure favoring consolidated procurement through academic medical center cooperatives.
Pricing Analysis
Geographic price spreads separate German statutory health insurance reimbursement bands from United States Medicare-reimbursed academic medical center rates and emerging-market CDSCO pathways. Three-tier pricing structure across premium wireless microstimulators, standard epiretinal implants, and economy tethered systems reflects certification grade differentiation and after-sales service bundling. Cost compression in economy tiers intensifies as Indian manufacturing clusters adapt designs for price-sensitive segments. Research institutes demonstrate lowest price sensitivity due to grant-funded procurement, while ophthalmology clinics in emerging markets face acute budget constraints.
Supply Chain Analysis
Tariff exposure between United States and China semiconductor fabrication capacity dominates supply chain risk assessment for artificial retina manufacturers. Specialized foundry output concentrates in Taiwan, South Korea, and China, with photodiode array wafers and microelectrode silicon substrates drawing from these nodes. Single-source vulnerability in high-density electrode manufacturing feeds from concentrated East Asian cleanroom capacity. Distribution runs through specialized ophthalmology purchasing cooperatives that unbundle surgical training from hardware pricing, displacing traditional distributor relationships in United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial retina markets function as service-attach opportunities where remote monitoring infrastructure and patient programming support expand faster than device hardware revenue, particularly for wireless microstimulator architectures requiring longitudinal technical engagement.
For Market Incumbents: Build regulatory data moats through ISO 14155 longitudinal safety databases that exceed new entrant funding capacity. Deepen backward integration into semiconductor fabrication partnerships in Israel and Taiwan to secure photodiode array supply. Gene therapy substitution threats in inherited retinal dystrophies demand defensive expansion into age-related macular degeneration segments where pharmacological alternatives remain distant. For New Entrants and Emerging Players: Build out CDSCO-optimized wireless device architectures targeting India's underpenetrated South Asian markets before incumbent cost adaptation. India's production-linked incentive schemes for medical electronics offer manufacturing footprint advantages for price-sensitive segments. Surgical training program partnerships with Hyderabad and Bengaluru academic centers provide go-to-market acceleration. For Investors and Strategic Acquirers: FDA breakthrough device designation reshapes the acquisition landscape by compressing clinical timeline risk for subretinal implant portfolios. Long-term viability across the analysis window favors targets with photodiode array miniaturization pipelines and established EMA quality management systems. Watch for PMDA regenerative medicine framework hybrid classifications as signal for device-biological convergence inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA Medical Device Regulation harmonization accelerates cross-border commercial access for subretinal devices. |
| Hospital System Partnership | Integrated delivery network procurement concentration in United States Medicare channels captures volume commitment leverage. |
| Software Companion Development | AI-assisted surgical planning integration reduces vitreoretinal specialist training bottlenecks for subretinal procedures. |
| Reimbursement Strategy | Statutory health insurance pathway navigation in Germany scales ophthalmology clinic procedural volumes. |
| Backward Integration | In-house photodiode array fabrication secures supply continuity against East Asian foundry concentration risk. |
Research Approach
A spread of perspectives from retinal surgeons, biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads converged on the working assumptions underlying this analysis. Primary interviews with clinicians and procurement specialists combined with secondary validation against FDA 510(k) filings, EMA CE marking databases, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up segmentation modeling and top-down market sizing triangulation anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with implant architecture segmentation by product type, application indication, signal processing technology, and end-user procurement channel informing the modeling architecture. CAGRs derived from procedure volume trajectories in United States, German, and Japanese reimbursement datasets, calibrated against photodiode array manufacturing capacity expansion timelines and retinal surgeon training pipeline outputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene therapy developers or wireless microstimulator specialists would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygenator Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Medical Face Shield Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Slip Disc Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Self-Injections Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
3D-Printed Maxillofacial Implants Market