
 Dental Devices and Consumables Market | 2026-2036
Dental Devices and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Devices and Consumables Market Insights
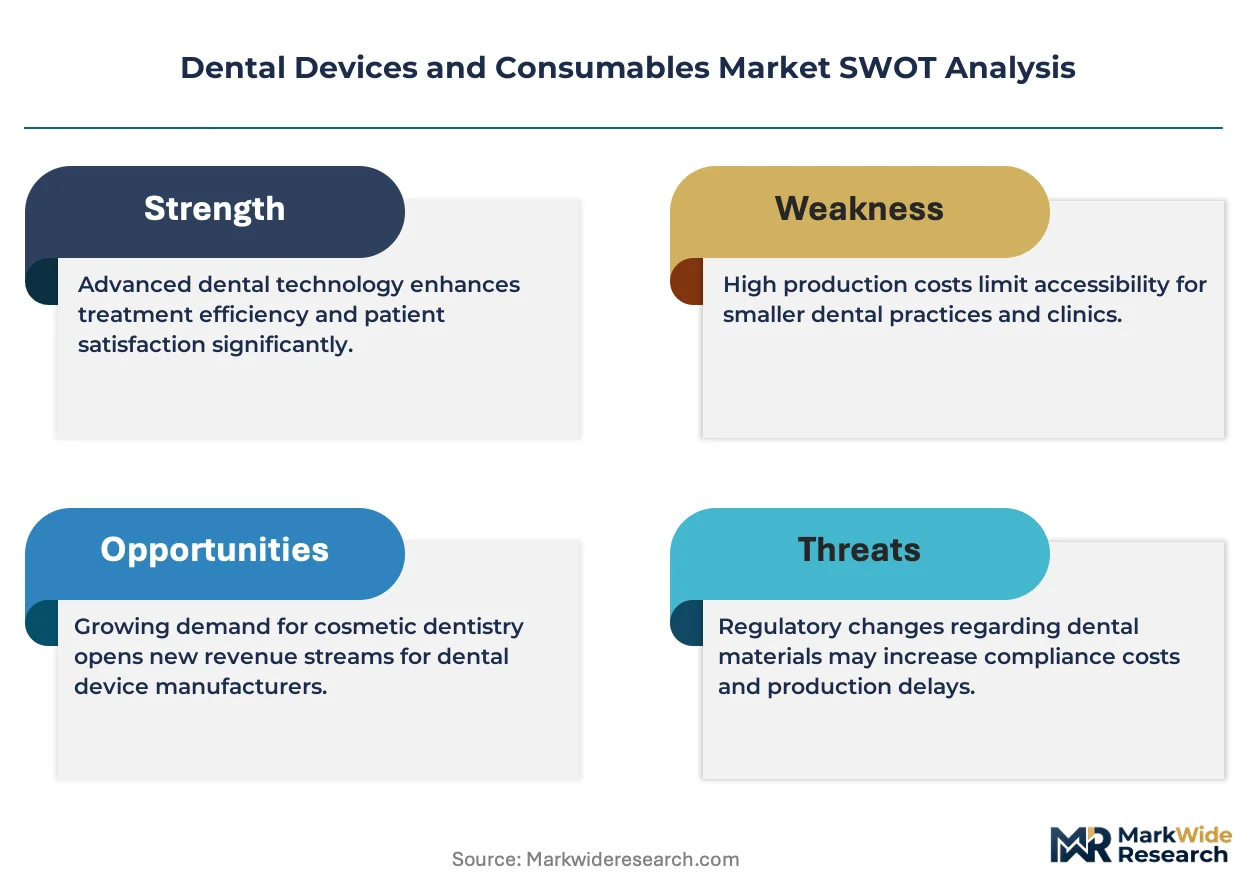
A shift from single-source to multi-source procurement is restructuring supply relationships across the dental devices sector. Dentsply Sirona leverages its integrated manufacturing footprint to control end-to-end production of CAD/CAM hardware and consumables. Institut Straumann AG anchors its position through deep specialization in premium implant systems and digital workflow solutions. Envista Holdings competes by extending its brand portfolio across orthodontics, implants, and imaging equipment.
Dental devices and consumables encompass instruments, materials, and equipment used to diagnose, treat, and restore oral health, including titanium alloy implants with osseointegration surfaces, composite resin restoratives with nanofiller compositions, and nickel-titanium endodontic files manufactured via electrochemical machining. These products serve commercial purposes across preventive care, restorative reconstruction, and aesthetic enhancement procedures. Dental implants command the largest revenue pool among product types due to high procedure volumes and premium pricing, while digital dentistry technologies including CAD/CAM systems and 3D printing represent the fastest-expanding segment as chairside manufacturing displaces traditional laboratory workflows. Cosmetic dentistry applications generate outsized margins compared to periodontal treatment, though preventive care maintains the highest procedure frequency across dental clinics and hospital settings.
The FDA regulates dental devices through 510(k) premarket notification and quality system requirements under 21 CFR Part 820, while the EU MDR imposes stricter clinical evidence standards and post-market surveillance obligations on implantable devices. ISO 13485 certification serves as the baseline quality management framework for manufacturers seeking access to both markets. Stakeholders must monitor evolving reimbursement codes for digital workflows and chairside milling as payor policies increasingly influence capital investment decisions in dental practice technology.
Market Dynamics
Digital dentistry workflows are compressing traditional laboratory margins while forcing equipment manufacturers to bundle hardware, software, and consumables into integrated subscription models that lock in recurring revenue streams.
Growth Catalysts
- Chairside CAD/CAM adoption:Dental clinics in the United States and Germany are installing intraoral scanners and milling units that eliminate third-party lab fees. The FDA's 510(k) clearance pathway accelerates hardware deployment timelines.
- EU MDR standardization:Stricter clinical evidence requirements for implantable devices are consolidating supplier bases toward ISO 13485-certified manufacturers with robust quality management systems.
- Titanium alloy osseointegration surfaces:Advanced surface treatments including hydroxyapatite coatings and SLA (sand-blasted, large-grit, acid-etched) topography improve primary stability and reduce healing times for immediate-load protocols.
Market Restraints
- Precious metal volatility:Palladium and gold price swings in commodity markets directly compress margin on crown and bridge alloys, forcing dental laboratories to absorb cost or pass through to clinics.
- Supply concentration in zirconia blanks:Sintered zirconia disc manufacturing concentrates among Japanese and German ceramic suppliers, creating single-source risk for CAD/CAM milling centers.
- Biocompatibility testing burdens:ISO 10993 cytotoxicity and sensitization studies add twelve-to-eighteen-month lead times for new composite resin formulations seeking CE marking under EU MDR.
Strategic Opportunities
- India preventive care expansion:Government health initiatives and rising disposable incomes in tier-two cities are driving first-time dental visits and basic restorative procedures among previously underserved populations.
- AI-powered treatment planning:Machine learning algorithms integrated into cone-beam CT software automate nerve canal detection and implant positioning, reducing specialist training barriers for general practitioners.
- Direct-to-clinic 3D printing resin distribution:Photopolymer manufacturers are bypassing traditional dental distributors to sell biocompatible resins through e-commerce portals with same-day fulfillment.
Industry Challenges
- Digital workflow technician shortage:Dental laboratories struggle to recruit CAD designers proficient in exocad and 3Shape software, slowing scanner-to-milling integration despite capital availability.
- Legacy equipment interoperability:Proprietary file formats from closed-system manufacturers block data portability between scanners, design software, and third-party mills, fragmenting digital investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Devices and Consumables Market |
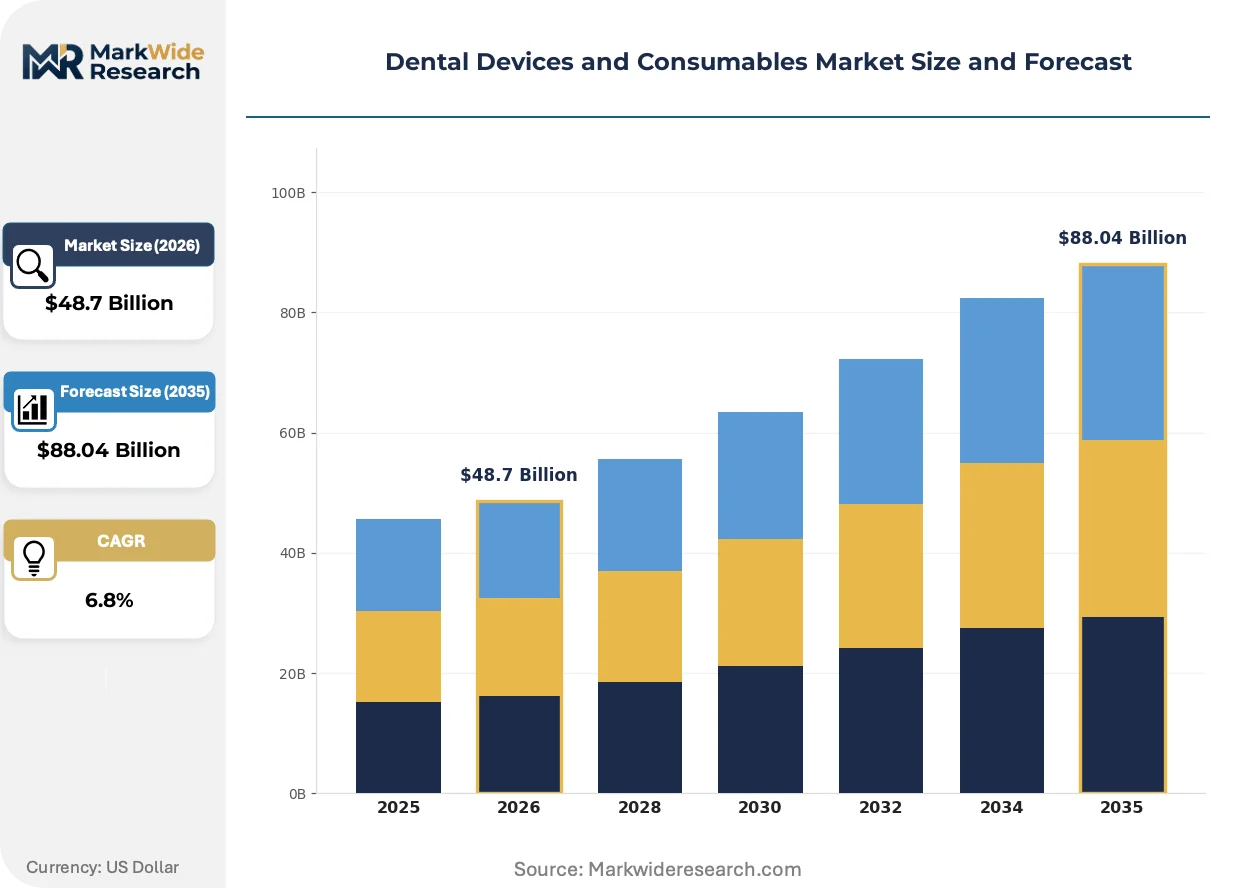
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthodontic Supplies, Restorative Materials, Endodontic Instruments End User: Dental Clinics, Hospitals, Laboratories, Research Institutions Technology: Digital Dentistry, CAD/CAM Systems, 3D Printing, Laser Dentistry Application: Cosmetic Dentistry, Periodontal Treatment, Oral Surgery, Preventive Care |
| Companies Covered | Dentsply Sirona, Henry Schein, Envista Holdings, Institut Straumann AG, Ivoclar Vivadent, 3M Company, ZimVie, Patterson Companies, Align Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Devices and Consumables Market Trends and Innovations
Material science breakthroughs and regulatory digitization are converging to shorten product development cycles while expanding the treatable patient population through personalized manufacturing techniques.
Photopolymer resins with ceramic filler loadings above fifty percent by weight are absorbing mechanical stress applications previously reserved for milled zirconia and lithium disilicate. Prosthodontists in Japan and South Korea are adopting these materials for long-term temporary restorations and definitive crown fabrication in posterior quadrants. This absorption of functional load-bearing applications is compressing the addressable market for subtractive milling equipment while expanding printer hardware placements.
The EU Medical Device Regulation's EUDAMED database mandates unique device identification and post-market surveillance for all implantable dental devices sold in member states. Manufacturers must now maintain clinical follow-up data for ten years, forcing smaller implant companies to withdraw SKUs or consolidate under larger quality infrastructures. Premium implant lines with established clinical documentation are capturing shelf space formerly occupied by economy-tier alternatives.
Group purchasing organizations representing multi-location dental service organizations are unbundling after-sales service contracts from capital equipment sales. These buyers negotiate separate maintenance agreements with third-party field service networks, pressuring original equipment manufacturers to compete on hardware margin alone. The unbundling trend is most visible in the United States, where DSOs operate over ten percent of dental chairs and standardize procurement across fifty-plus location footprints.
Dental Devices and Consumables Market Segmentation
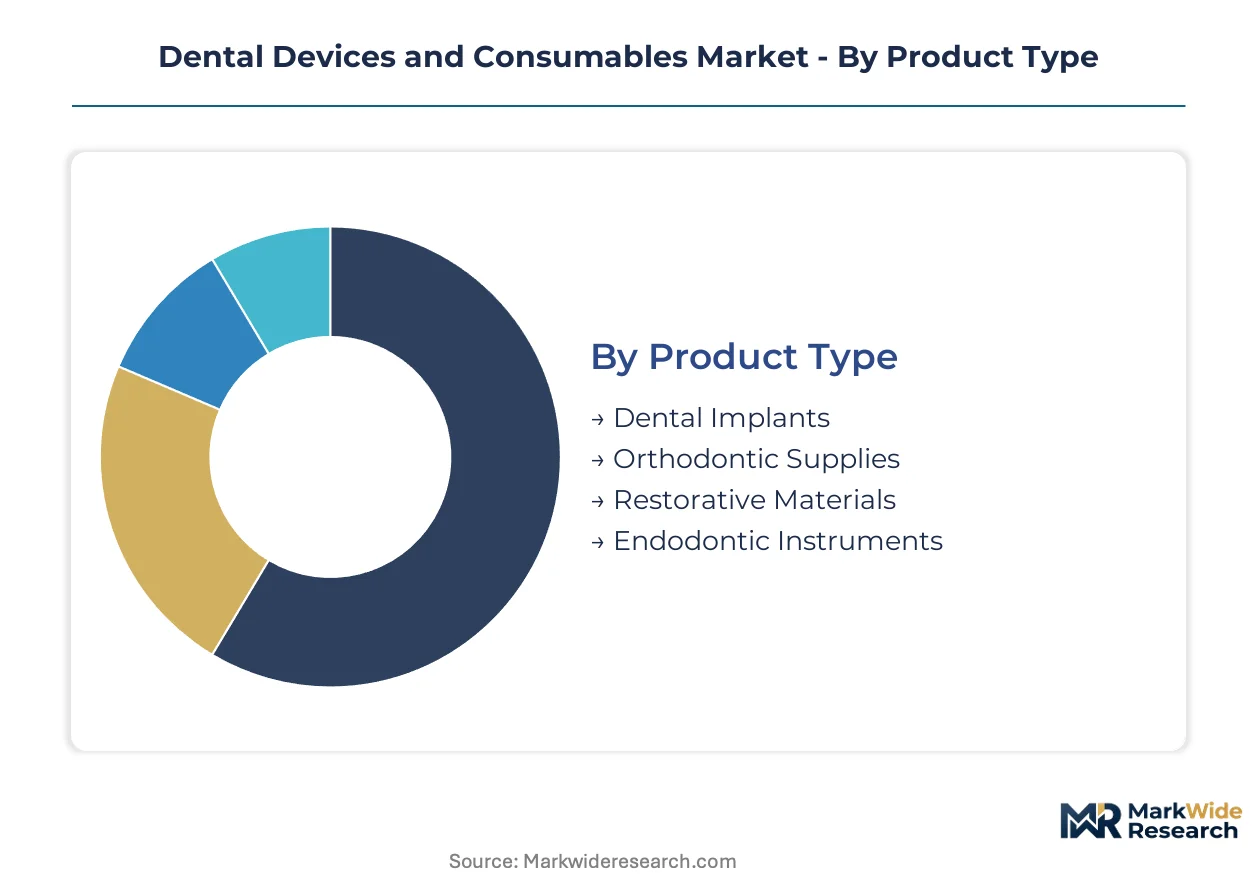
Segmentation in dental devices reveals how clinical workflows, capital intensity, and reimbursement patterns fragment purchasing decisions across patient care settings. Understanding these divides exposes where hardware bundling, consumable lock-in, and service contracts generate sustainable revenue pools.
Product Type:
Integration depth varies sharply: implants and restorative materials embed into multi-step surgical workflows, while orthodontic and endodontic supplies often deploy as standalone consumable purchases.
- Dental Implants:Titanium alloy fixtures with SLA-treated surfaces command premium pricing through osseointegration reliability. Demand clusters in Germany and Japan where immediate-load protocols and favorable reimbursement support high procedure volumes.
- Orthodontic Supplies:Clear aligner systems and fixed appliances serve adolescent and adult aesthetic correction. United States orthodontic practices drive volume through DSO-standardized procurement and direct-to-consumer marketing channels.
- Restorative Materials:Composite resins, glass ionomers, and amalgam alternatives fill caries and trauma defects. ISO 10993 biocompatibility testing extends development timelines for novel nanofiller formulations.
- Endodontic Instruments:Nickel-titanium rotary files manufactured via electrochemical machining navigate curved canal anatomies. Single-use sterile packaging trends are displacing traditional autoclave-reprocessed instruments.
Volume placements concentrate in Dental Implants; the faster expansion belongs to Orthodontic Supplies.
End User:
Capital availability and procedure complexity determine which settings adopt integrated digital workflows versus fragmented point solutions.
- Dental Clinics:Private practices and group settings deploy chairside CAD/CAM and intraoral scanning to capture laboratory margin. United States DSOs standardize technology stacks across fifty-plus location footprints.
- Hospitals:Academic medical centers and trauma units manage complex oral-maxillofacial reconstruction. FDA 510(k) clearance pathways accelerate adoption of surgical navigation systems in these high-acuity environments.
- Laboratories:Independent and manufacturer-affiliated labs process scanner files into milled or printed restorations. Technician shortages in exocad and 3Shape software constrain throughput despite scanner penetration.
- Research Institutions:Universities and material science centers validate novel surface treatments and biocompatible polymers. EU MDR clinical evidence requirements increasingly source longitudinal data from these sites.
Procurement scale favors Dental Clinics; technology validation partnerships cluster with Research Institutions.
Technology:
Maturity gradients separate established imaging modalities from emerging manufacturing platforms still seeking clinical acceptance and reimbursement codes.
- Digital Dentistry:Intraoral scanners, cone-beam CT, and practice management software form the connectivity layer. Germany's dental clinics lead hardware density per practicing dentist.
- CAD/CAM Systems:Chairside milling units and design software eliminate third-party laboratory turnaround. Proprietary file formats from closed-system manufacturers fragment interoperability.
- 3D Printing:Photopolymer and resin-based additive manufacturing produces surgical guides and provisional restorations. Photopolymers with ceramic filler loadings above fifty percent by weight now absorb posterior functional loads.
- Laser Dentistry:Hard and soft tissue lasers serve periodontal debridement and caries preparation. Capital cost and training requirements limit penetration outside premium clinic tiers.
Revenue concentration sits with Digital Dentistry; steepest expansion trajectory belongs to 3D Printing.
Application:
Margin structure inverts between high-frequency preventive services and episodic aesthetic procedures with premium pricing power.
- Cosmetic Dentistry:Veneers, whitening systems, and aesthetic orthodontics generate outsized margins per procedure. Japan and South Korea patient populations demonstrate elevated willingness-to-pay for aesthetic enhancement.
- Periodontal Treatment:Scaling, root planing, and regenerative procedures address gum disease progression. Procedure frequency exceeds cosmetic work but reimbursement compression limits profitability.
- Oral Surgery:Implant placement, bone grafting, and extraction services require specialized training and capital equipment. Immediate-load protocols in the United States reduce chair time per implant case.
- Preventive Care:Examinations, cleanings, and fluoride applications maintain highest visit frequency across all settings. India's tier-two city expansion drives first-time patient acquisition in this category.
Procedure volume concentrates in Preventive Care; margin expansion favors Cosmetic Dentistry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy feedstock from Japanese and German metallurgical suppliers anchors the geographic concentration of implant manufacturing. Dental device production clusters near these material sources and adjacent to high-procedure-volume clinical markets.
United States
FDA 510(k) clearance pathways accelerate CAD/CAM hardware deployment across dental service organizations. Reimbursement codes for digital workflows and chairside milling influence capital investment decisions in private practices. Greater Boston and Minneapolis-St. Paul host dense concentrations of implant manufacturers and digital dentistry software developers.
Germany
Immediate-load implant protocols and favorable statutory health insurance reimbursement sustain high procedure volumes in Bavaria and North Rhine-Westphalia. EU MDR clinical evidence requirements and ISO 13485 certification standards filter supplier bases toward established quality infrastructures. Stuttgart and Munich anchor precision machining clusters for nickel-titanium endodontic instruments.
Japan
Osseointegration surface treatment technologies from domestic suppliers command premium positioning in immediate-load protocols. PMDA regulatory harmonization with ISO standards streamlines market access for implantable devices. Tokyo and Osaka metropolitan areas concentrate dental clinic chains with standardized digital workflow adoption.
India
Government health initiatives and rising disposable incomes in tier-two cities drive first-time dental visits and basic restorative procedures. CDSCO medical device regulations and BIS quality standards shape import substitution dynamics for consumables. Gujarat and Maharashtra host emerging manufacturing clusters for zirconia blanks and composite resin formulations.
South Korea
Aesthetic dentistry patient willingness-to-pay supports premium pricing for ceramic-filled photopolymer restorations. MFDS regulatory frameworks align with ISO 10993 biocompatibility testing requirements for novel materials. Seoul Capital Area dental clinics lead adoption of 3D-printed surgical guides and provisional restorations.
Dental Devices and Consumables Market Competitive Landscape
Global majors compete with regional champions across integrated digital workflow platforms and specialized implant portfolios. Market structure consolidates around three tiers: diversified multinationals with end-to-end manufacturing footprints, premium specialists anchored in osseointegration science, and regional distributors with deep clinic relationships. Dominant competitive moves include strategic portfolio diversification across orthodontics, implants, and imaging modalities, plus backward integration into consumable manufacturing to capture recurring revenue streams.
Among diversified multinationals, Dentsply Sirona and Envista Holdings exemplify the integrated-platform archetype, spanning hardware, software, and consumable categories. Institut Straumann AG occupies a position within the premium-specialist tier, anchored in implantology and digital workflow solutions. These three companies represent distinct strategic postures: scale-driven bundling, premium clinical positioning, and multi-brand portfolio extension.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Henry Schein |
| Envista Holdings |
| Institut Straumann AG |
| Ivoclar Vivadent |
| 3M Company |
| ZimVie |
| Patterson Companies |
| Align Technology |
| Others |
Pricing and Supply Chain Analysis
Group purchasing organizations unbundling after-sales service contracts from capital equipment sales force original equipment manufacturers to compete on hardware margin alone, compressing pricing power while shifting supply relationships toward third-party field service networks. This procurement restructuring concentrates price sensitivity among dental service organizations operating standardized technology stacks across multi-location footprints.
Pricing Analysis
Warranty and service bundling separates premium-tier equipment manufacturers from competitors offering unbundled hardware-only sales. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and after-sales support depth. Cost compression in economy-tier CAD/CAM hardware intensifies because group purchasing organizations negotiate maintenance agreements separately. Dental service organizations demonstrate highest price sensitivity; academic medical centers and premium independent clinics show lowest sensitivity due to clinical outcome prioritization.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German ceramic suppliers controlling sintered zirconia disc manufacturing for CAD/CAM milling centers. Titanium alloy feedstock draws from Japanese and German metallurgical suppliers; nickel-titanium endodontic file wire sources from precision machining clusters in Stuttgart and Munich. Tariff exposure on imported zirconia blanks and precious metal alloys threatens margin stability for dental laboratories. Distribution runs through dental service organization procurement consortia and traditional dealer networks serving independent clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chairside CAD/CAM systems and intraoral scanners are displacing traditional laboratory-dependent workflows, compressing turnaround times while restructuring capital allocation across dental clinics. This technology transition rewards manufacturers bundling hardware, software, and consumable subscriptions.
For Market Incumbents: Deepen backward integration into consumable manufacturing to capture recurring revenue streams from photopolymer resins and zirconia blanks. Expand ISO 13485-certified production capacity in Germany and Japan to meet EU MDR clinical evidence requirements. Defend against direct-to-clinic 3D printing resin distributors by locking in exclusive supply agreements with dental service organization procurement consortia. For New Entrants and Emerging Players: Direct-to-clinic e-commerce portals offer the most penetrable route for photopolymer manufacturers bypassing traditional dental distributors. Target tier-two cities in India where government health initiatives drive first-time dental visits and basic restorative procedures. Establish same-day fulfillment capabilities for biocompatible resins to capture laboratory margin compression opportunities. For Investors and Strategic Acquirers: The window for entry favors premium implant specialists with established clinical documentation under EU MDR post-market surveillance requirements. Long-term viability hinges on ten-year clinical follow-up data maintenance capabilities and EUDAMED database compliance. Monitor FDA 510(k) clearance timelines for chairside milling units as inflection indicator for digital dentistry hardware deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter supplier bases toward ISO 13485-certified manufacturers with robust quality systems. |
| Hospital System Partnership | Academic medical centers in the United States accelerate surgical navigation system adoption through FDA 510(k) clearance pathways. |
| Software Companion Development | AI-powered cone-beam CT algorithms automate nerve canal detection, reducing specialist training barriers for general practitioners. |
| Reimbursement Strategy | Payor policies for digital workflows and chairside milling increasingly influence capital investment decisions in dental practice technology. |
| Backward Integration | In-house production of zirconia blanks and titanium alloy feedstock captures margin from Japanese and German ceramic suppliers. |
Research Methodology
FDA 510(k) premarket notification filings, EU MDR EUDAMED database entries, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with dental clinic owners, group purchasing organization contracts managers, biomedical engineers, and dental laboratory technicians validated demand assumptions and technology adoption timelines. Bottom-up and top-down triangulation reconciled procedure volume estimates with equipment placement data across the United States, Germany, and Japan.
Bottom-up modeling built from intraoral scanner installations, CAD/CAM unit placements, and consumable throughput per clinic; top-down validation cross-checked against aggregate dental device import data and manufacturer revenue disclosures. Segmentation dimensions included product type, end user setting, technology platform, and application category across the analysis window. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and reimbursement code expansion for digital workflows.
The model holds under stable regulatory pathways and continued dental service organization consolidation; deviation in precious metal commodity volatility or EU MDR enforcement intensity would shift equipment procurement timelines. Forecasts reflect assumptions about chairside manufacturing adoption and laboratory margin compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Dental Splints Market
Dental Devices
US Dental Splint Market
Dental Devices
Dental Radiometer Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Dental Dam Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Sealants Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Plaque Disclosing Aids Market