
 Global Vessel Sealing Devices Market | 2026-2036
Global Vessel Sealing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vessel Sealing Devices Market Foresight
Germany is reshaping competitive dynamics in vessel sealing devices through precision manufacturing clusters around Tuttlingen and Erlangen. Medtronic plc leverages integrated energy platforms to sustain leadership across bipolar and ultrasonic modalities. Erbe Elektromedizin GmbH anchors European supply with deep specialization in electrosurgical generators and vessel sealing instruments. Johnson & Johnson (Ethicon Inc.) competes through broad surgical stapling and energy portfolios that extend into open and laparoscopic sealing applications.
Vessel sealing devices are electrosurgical instruments that apply controlled thermal energy to coagulate and transect blood vessels during surgical procedures, typically operating at frequencies between 300 and 500 kHz with impedance feedback systems to limit lateral thermal spread. Their primary purpose is to achieve hemostasis while minimizing charring and tissue adherence, reducing operative time across laparoscopic and open surgical workflows. Laparoscopic sealers dominate procedural volume as minimally invasive surgery expands, while ultrasonic sealers command premium positioning in delicate tissue applications where precision limits collateral damage. Bipolar sealers retain the largest installed base in general surgery, though hybrid technology platforms that combine radiofrequency and ultrasonic energy represent the fastest-growing segment as surgeons seek single-instrument versatility.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence standards for vessel sealing devices entering commercial distribution. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards further constrain design choices and materials selection for manufacturers targeting regulated markets. Stakeholders must monitor how FDA guidance on reusable device reprocessing and EU Green Deal sustainability mandates will alter cost structures and competitive positioning across the supply chain.
Market Dynamics
Hybrid energy platforms combining radiofrequency and ultrasonic modalities are compressing instrument replacement cycles as surgeons demand single-device versatility across laparoscopic and open procedures.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter clinical evidence requirements for electrosurgical instruments are filtering out marginal competitors and consolidating procurement toward validated platforms.
- Minimally invasive surgery expansion:Laparoscopic procedure volumes in academic medical centers are accelerating capital equipment refresh rates for advanced sealing systems.
- Impedance feedback systems:Real-time tissue response monitoring is reducing thermal spread complications and driving preference for next-generation bipolar instruments.
Market Restraints
- Copper and ceramic substrate costs:Input material volatility for generator components is squeezing gross margins on electrosurgical hardware.
- Tuttlingen manufacturing cluster concentration:German precision instrument supply is vulnerable to single-region disruption from logistics or labor constraints.
- IEC 60601 electrical safety certification:Extended validation timelines for novel energy delivery modes delay product launches by 18-24 months.
Strategic Opportunities
- India tertiary hospital expansion:Underpenetrated surgical infrastructure in tier-2 cities offers first-mover positioning for sealing platform vendors.
- EU Green Deal sustainability mandates:Reusable instrument reprocessing requirements favor modular device architectures over disposable-heavy competitors.
- AI-assisted tissue recognition:Machine vision integration with sealing algorithms enables automated power modulation in delicate anatomical zones.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-disciplinary expertise in electrosurgical physics and surgical workflow design remains concentrated among a handful of specialized programs.
- Legacy generator incompatibility:Hospital installed bases of 5-10 year-old energy platforms resist seamless integration with advanced sealing handpieces.
- ISO 10993 biocompatibility retesting:Coating or insulation material changes trigger expensive revalidation even for minor design iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vessel Sealing Devices Market |
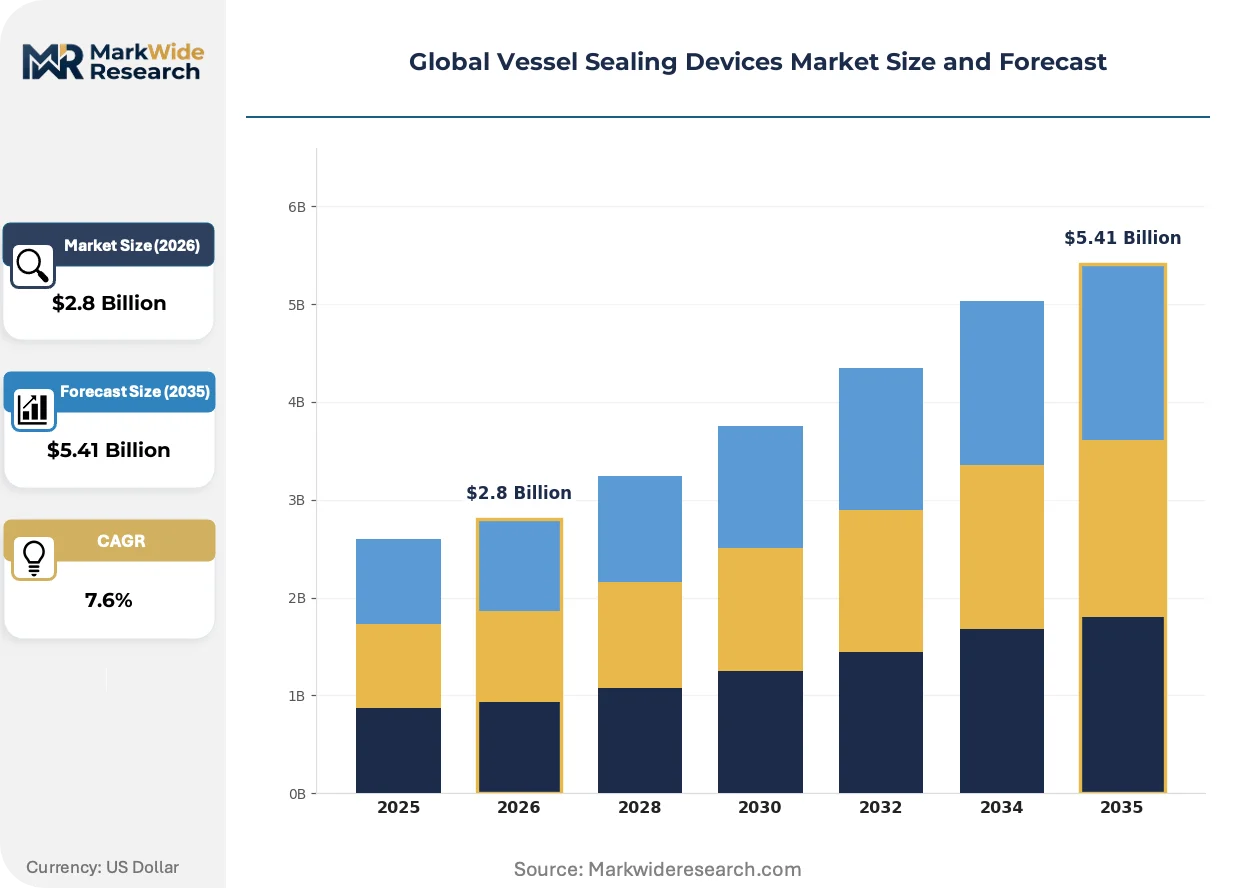
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Sealers, Open Surgery Sealers, Bipolar Sealers, Ultrasonic Sealers, Manual Sealers Technology: Radiofrequency, Ultrasound, Laser, Electrothermal, Mechanical, Hybrid Application: Gynecology, Urology, General Surgery, Thoracic Surgery, Neurosurgery, Colorectal Procedures End User: Ambulatory Surgery Centers, Specialty Clinics, Academic Hospitals, Medical Research Institutes, Cancer Treatment Facilities |
| Companies Covered | Olympus Corporation, Intuitive Surgical Inc., Medtronic plc, Stryker Corporation, ConMed Corporation, Johnson & Johnson (Ethicon Inc.), Erbe Elektromedizin GmbH, Karl Storz SE & Co. KG, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vessel Sealing Devices Market Shifts & Advancements
Convergence of energy modalities and intelligent tissue sensing is redefining competitive advantage away from raw power output toward precision control and procedural integration.
Ultrasonic shears with integrated temperature monitoring are rendering obsolete conventional bipolar forceps in thyroid and parathyroid procedures where thermal spread risks nerve injury. Otolaryngology and endocrine surgery departments in US academic centers are standardizing these platforms within 18-month procurement windows. The shift is compressing price premiums for standalone bipolar instruments while elevating bundled platform contracts.
EU MDR Article 10 post-market surveillance obligations are extending clinical follow-up requirements from two to five years for electrosurgical devices. Manufacturers must now maintain active implantable-level vigilance systems for instruments previously regulated as lower-risk. German notified bodies are experiencing 14-month backlog queues, forcing smaller competitors to abandon European market entry.
Hospital procurement committees are unbundling service contracts from capital equipment sales, demanding transparent per-procedure costing for consumables and maintenance. US integrated delivery networks are negotiating multi-hospital sealing platform agreements with performance guarantees on device longevity. This behavioral shift is pressuring vendors to disclose true lifecycle costs and compete on total cost of ownership rather than upfront capital pricing.
Global Vessel Sealing Devices Market Segmentation
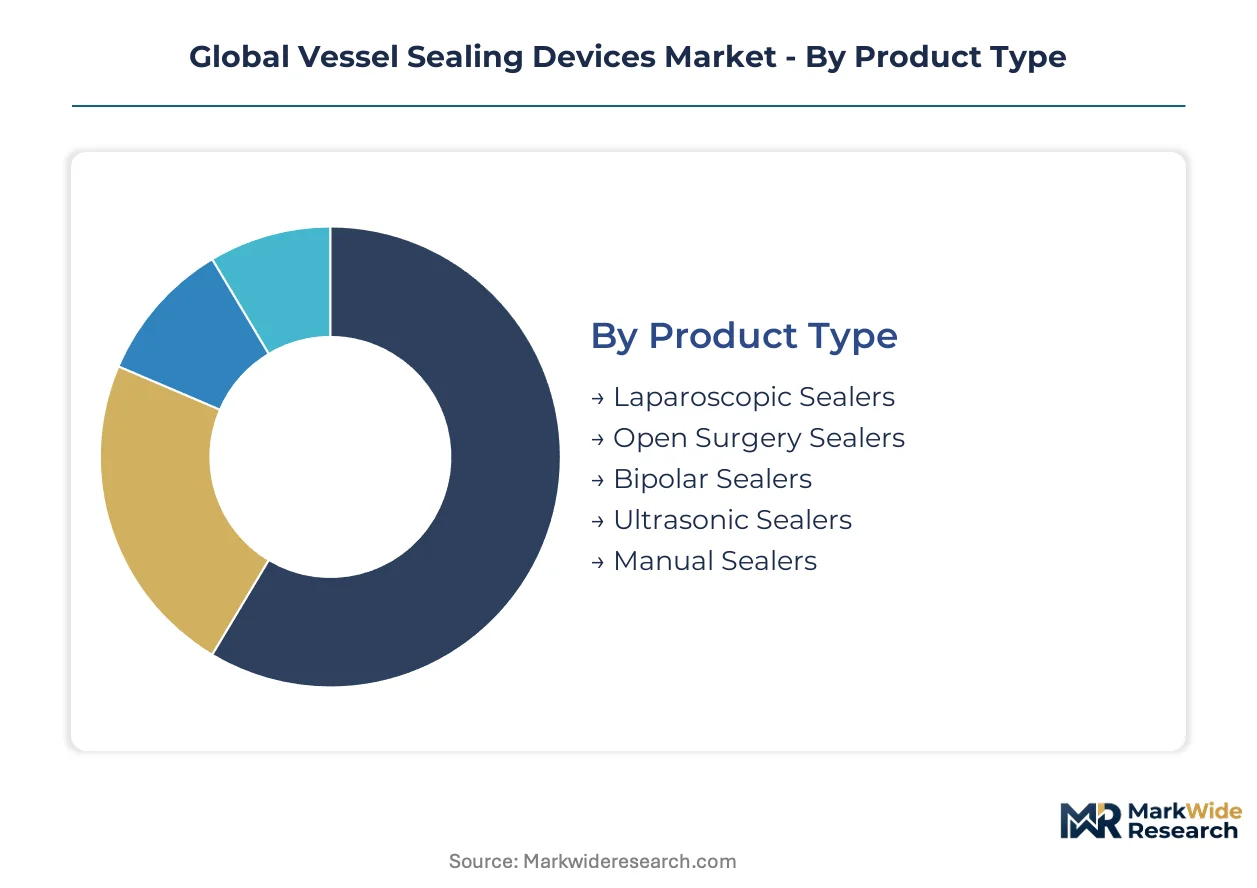
Segmentation in vessel sealing devices reveals how technology maturity, procedural setting, and clinical specialty dictate purchasing behavior and product specification. Manufacturers configure platform architectures around these divides to optimize generator compatibility, handpiece durability, and consumable attach rates across divergent surgical workflows.
Product Type:
Mature modalities anchor installed base economics while emerging formats reshape replacement cycles through hybrid functionality.
- Bipolar Sealers:These instruments deliver radiofrequency energy between two jaws with impedance feedback limiting thermal spread to 1-2 mm. General surgery suites in Germany and the United States maintain the largest installed bases, though procurement committees now demand compatibility with legacy generators as a condition of contract renewal.
- Ultrasonic Sealers:High-frequency mechanical vibration (55.5 kHz) denatures protein for sealing without electrical current, critical in nerve-proximate procedures. Thyroid and parathyroid departments in US academic centers are standardizing these platforms within compressed 18-month procurement windows to minimize thermal injury risk.
- Laparoscopic Sealers:Shafted instruments designed for trocar insertion dominate procedural volume as minimally invasive surgery expands across gynecology and colorectal specialties.
- Open Surgery Sealers:Pistol-grip and forceps-style configurations persist in trauma and emergency settings where rapid conversion from laparotomy is required.
- Manual Sealers:Non-energy mechanical clips and clamps serve cost-constrained settings and backup scenarios when generator failure occurs.
Bipolar sealers handle the majority of throughput; ultrasonic sealers are gaining share fastest in delicate tissue applications.
Technology:
Cost tiering separates premium intelligent platforms from standard electrosurgical and economy mechanical alternatives.
- Hybrid:Combines radiofrequency and ultrasonic energy in single instruments, enabling tissue transection with simultaneous hemostasis. Academic medical centers in China and the United States are accelerating adoption as surgeons demand instrument versatility across laparoscopic and open workflows.
- Radiofrequency:Alternating current at 300-500 kHz generates resistive heating for coagulation. The technology commands the largest generator installed base but faces compression as hospitals unbundle service contracts and demand transparent per-procedure costing.
- Ultrasound:Mechanical energy conversion avoids electrical current passage through tissue, preferred in pacemaker-dependent patients and conductive fluid environments.
- Electrothermal:Direct resistive heating elements provide consistent temperature output for vessel bundles in open procedures.
- Laser:Coherent light energy enables precise cutting with minimal collateral thermal damage, restricted to specialized otolaryngology and neurosurgical applications by capital cost and safety training requirements.
- Mechanical:Physical clamping and ligation without energy delivery serves emergency backup and regulatory-constrained markets.
Radiofrequency platforms retain the dominant installed position; hybrid systems are climbing the fastest as procurement shifts toward bundled versatility.
Application:
Volume concentration in high-throughput specialties contrasts with margin-rich complex procedures requiring precision instrumentation.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair generate the highest annual procedure counts, driving standardized sealing platform deployment across hospital systems.
- Gynecology:Hysterectomy and myomectomy procedures demand reliable hemostasis in vascular pelvic anatomy, with sealing technology replacing mechanical stapling in laparoscopic approaches.
- Urology:Prostatectomy and nephrectomy require nerve-sparing precision where thermal spread control determines functional outcomes.
- Colorectal Procedures:Low anterior resection and mesorectal excision benefit from sealing devices that reduce staple line complications in irradiated tissue.
- Thoracic Surgery:Video-assisted thoracoscopic surgery relies on sealers for pulmonary vessel management where mechanical stapler angles are restricted.
- Neurosurgery:Cranial and spinal applications demand the lowest thermal signature, restricting adoption to specialized ultrasonic and laser platforms.
General surgery generates the highest absolute device consumption; gynecology is expanding fastest as minimally invasive hysterectomy rates rise.
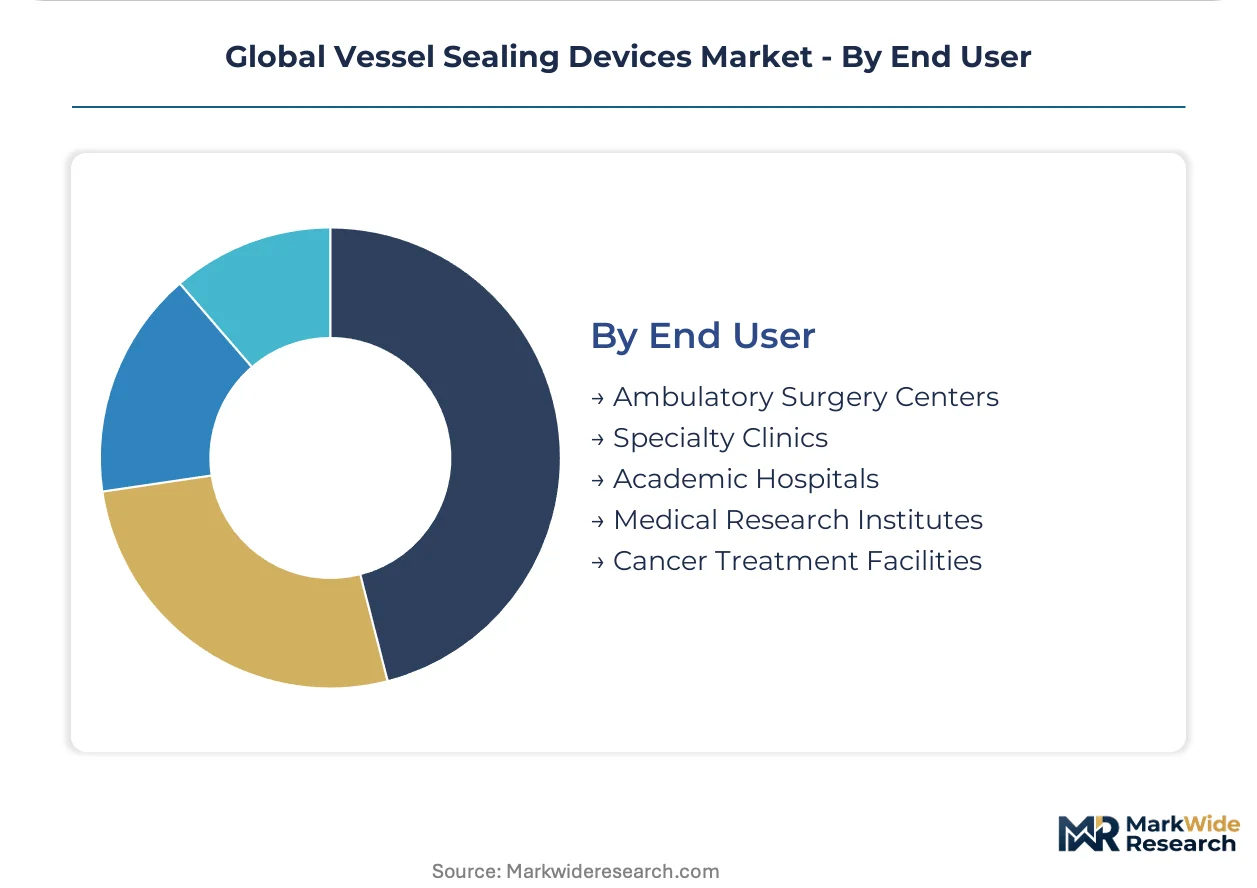
End User:
Customer type determines capital equipment refresh rates, service contract structures, and consumable attach rate economics.
- Academic Hospitals:Teaching institutions with residency programs require advanced sealing platforms with data logging and training mode functionality. These centers in the United States, Germany, and China drive adoption of next-generation impedance feedback systems.
- Ambulatory Surgery Centers:Freestanding facilities prioritize device reliability and rapid turnover, favoring disposable-heavy models over capital-intensive reusable platforms.
- Cancer Treatment Facilities:Oncology-focused hospitals require precision sealing in cytoreductive and reconstructive procedures, with procurement committees emphasizing device longevity guarantees.
- Specialty Clinics:Gynecology and urology-focused practices concentrate volume in specific procedures, enabling standardized instrument protocols.
- Medical Research Institutes:Preclinical and translational research settings drive early evaluation of AI-assisted tissue recognition and automated power modulation technologies.
Academic hospitals anchor premium platform demand; ambulatory surgery centers are expanding fastest as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across surgical markets. German hospitals prioritize precision-manufactured reusable platforms with extended service contracts, while Chinese academic centers accelerate capital equipment procurement for minimally invasive expansion. US procurement committees now demand transparent per-procedure costing that unbundles hardware from consumables.
United States
Academic medical centers in Boston and the Research Triangle drive adoption of impedance feedback systems for laparoscopic sealers. FDA 510(k) clearance timelines for novel energy delivery modes extend validation by 18-24 months, filtering marginal competitors. The Pacific Northwest corridor concentrates surgical robotics integration with advanced sealing platforms.
Germany
Tuttlingen's precision instrument cluster anchors European supply chains for electrosurgical generators and vessel sealing handpieces. EU MDR technical documentation mandates and 14-month notified body backlogs consolidate procurement toward validated platforms with established vigilance systems. Erlangen's medical technology corridor specializes in intelligent tissue sensing algorithms.
China
Tier-2 city hospital expansion in Sichuan and Shandong provinces drives demand for hybrid energy platforms combining radiofrequency and ultrasonic modalities. NMPA registration requirements for electrosurgical devices align with international electrical safety standards. The Yangtze River Delta concentrates domestic manufacturing of generator components and ceramic substrates.
India
Underpenetrated surgical infrastructure in tier-2 cities such as Jaipur and Lucknow offers first-mover positioning for sealing platform vendors as tertiary hospital construction accelerates. CDSCO medical device regulations tighten clinical evidence standards for imported electrosurgical instruments. Maharashtra's Mumbai-Pune corridor hosts the largest concentration of private hospital chains standardizing minimally invasive protocols.
Japan
Precision thyroid and parathyroid procedures in Tokyo and Osaka academic centers drive preference for ultrasonic sealers with integrated temperature monitoring. PMDA pharmaceutical and medical device agency requirements maintain stringent post-market surveillance for energy-based surgical instruments. The Nagoya medical device cluster specializes in miniaturized handpiece engineering for laparoscopic applications.
Global Vessel Sealing Devices Market Competitive Landscape
Capability concentration sits with integrated energy platform specialists; scale advantage sits with diversified surgical conglomerates. The vendor base separates into three functional tiers: precision electrosurgical specialists with deep generator expertise, diversified medical device majors with broad surgical portfolios, and emerging platform vendors competing on hybrid modality integration. Consolidation pressure intensifies as hospital procurement committees demand single-source contracts spanning capital equipment, consumables, and multi-year service guarantees. Technology licensing agreements and modular device architectures represent the dominant competitive vectors as regulatory validation costs escalate.
Among diversified surgical conglomerates, Medtronic plc and Johnson & Johnson (Ethicon Inc.) occupy positions spanning bipolar, ultrasonic, and hybrid energy modalities. Erbe Elektromedizin GmbH exemplifies the precision electrosurgical specialist archetype with concentrated expertise in generator systems and European supply chain anchoring. Stryker Corporation and Olympus Corporation represent scale-driven competitors integrating sealing platforms with broader surgical visualization and instrumentation portfolios.
| Leading Market Players |
|---|
| Olympus Corporation |
| Intuitive Surgical Inc. |
| Medtronic plc |
| Stryker Corporation |
| ConMed Corporation |
| Johnson & Johnson (Ethicon Inc.) |
| Erbe Elektromedizin GmbH |
| Karl Storz SE & Co. KG |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors absorb ceramic substrate and copper coil shipments from Tuttlingen, with container rate volatility amplifying cost differentials between German precision-manufactured generators and Asian-assembled handpieces. This logistics tension compresses margins on mid-tier bipolar instruments while allowing premium ultrasonic platforms to sustain wider geographic price spreads through bundled service contracts.
Pricing Analysis
Geographic price spreads between German-manufactured and Chinese-assembled platforms exceed three-to-one at the premium tier. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked reusable systems from FDA-cleared disposable-heavy configurations and unregulated mechanical alternatives. Cost compression in the standard tier intensifies as hospital procurement committees unbundle service contracts and demand transparent per-procedure costing. Ambulatory surgery centers exhibit the highest price sensitivity, while academic medical centers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for electrosurgical generator components. Manufacturing concentrates in Germany, China, and the United States, with Tuttlingen's precision instrument cluster anchoring European supply for impedance feedback systems and ceramic substrates. Raw material dependencies center on high-purity copper for generator windings, alumina ceramics for thermal management, and medical-grade polymers for handpiece insulation. Distribution runs through hospital procurement committees and group purchasing organizations that negotiate multi-year platform agreements with performance guarantees on device longevity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary expertise in electrosurgical physics and surgical workflow design remains concentrated among a handful of specialized academic programs, constraining platform innovation velocity and consolidating competitive advantage with incumbent specialists who have captive access to this talent pipeline.
For Market Incumbents: Build regulatory validation moats through accelerated EU MDR technical documentation completion and FDA 510(k) pathway pre-submission engagement. Deepen backward integration into ceramic substrate manufacturing to offset copper price volatility and secure generator component supply. Channel control through exclusive GPO contracts with tier-1 hospital systems in the United States and Germany limits entrant access to high-volume reference sites. For New Entrants and Emerging Players: Pursue modular device architectures compatible with legacy generator installed bases to circumvent 18-24 month IEC 60601 certification delays. White-space targets concentrate in India's tier-2 tertiary hospital expansion and hybrid energy platform segments where academic medical centers demand single-instrument versatility. A software companion strategy emphasizing AI-assisted tissue recognition algorithms enables differentiation without capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified surgical conglomerates seeking to divest non-core electrosurgical assets amid procurement committee pressure for single-source platform consolidation. Long-term viability over the projection horizon favors precision electrosurgical specialists with established notified body relationships and active implantable-level vigilance systems. The signal to watch is EU MDR Article 10 post-market surveillance obligation compliance completion rates among mid-tier competitors.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Establishes market access continuity as notified body backlogs extend to 14 months. |
| Legacy Generator Compatibility Development | Unlocks installed base economics in hospitals resisting full platform replacement. |
| AI-Assisted Tissue Recognition Integration | Enables automated power modulation in nerve-proximate thyroid and parathyroid procedures. |
| Modular Reusable Instrument Architecture | Aligns with EU Green Deal sustainability mandates favoring reprocessing over disposables. |
| Hospital System Partnership Agreements | Secures multi-year consumable attach rates through transparent per-procedure costing models. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions driving segmentation and competitive positioning. Primary interviews with clinicians performing laparoscopic and open procedures supplemented secondary validation through FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, hospital procurement contract registries, and electrosurgical device adverse event reporting systems. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data from generator manufacturers.
Demand-supply balance framing anchored the forecast framework across the analysis window, with modeled dimensions spanning product type, energy modality, surgical application, and end-user facility tier. CAGRs derived from procedure volume elasticity to surgical workforce expansion, capital equipment replacement cycles, and minimally invasive surgery adoption curves. Industry-specific inputs included laparoscopic procedure migration rates, impedance feedback system penetration in academic centers, and hybrid platform attach rates to existing generator installed bases.
Sensitivities concentrate around EU MDR notified body capacity constraints, copper and ceramic substrate commodity price trajectories, and NMPA registration timeline acceleration in China. Forecasts reflect documented assumptions on surgical procedure volume growth, regulatory validation throughput, and hospital capital expenditure prioritization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Midline Catheters Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
APAC AMH Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Global Medical Composite Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Cardiac Implants Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Europe Manual Resuscitators Market