
 Ear and Nasal Packing Market | 2026-2036
Ear and Nasal Packing Market Size, Share, and Industry Trends Forecast 2026-2036
Ear and Nasal Packing Market Analysis
Hospital procurement is tilting toward bundled contract frameworks that prioritize absorbable pack lines over traditional gauze alternatives. Medtronic plc leverages its integrated ENT surgical portfolio to sustain preference in large health system agreements. Stryker Corporation anchors its position through dedicated sinus surgery kits that incorporate proprietary balloon pack designs. Smith+Nephew plc differentiates via gelatin-based absorbable formats that compete on hemostasis speed against cotton-derived substitutes.
Ear and nasal packing comprises sterile, pliable materials inserted into the nasal cavity or external ear canal to control bleeding, maintain structural support, or deliver medication following trauma or surgical intervention; absorbable variants typically incorporate oxidized cellulose or gelatin sponge matrices that degrade within 48-72 hours, eliminating removal trauma. Non-absorbable packs and balloon packs command distinct margin pools, with silicone balloon formats leading in post-operative airway maintenance while polymer-based absorbable lines capture fastest-growing adoption in ambulatory settings where reduced follow-up visits drive value. Gelatin material formulations occupy premium positioning against commodity cotton derivatives across ENT clinic procurement tiers.
The US FDA regulates these devices under 510(k) premarket notification pathways with biocompatibility testing per ISO 10993, while the EU MDR's Class IIa designation demands clinical evidence and notified body oversight for market access. Health Canada and Japan's PMDA impose comparable sterility and material safety benchmarks that shape multinational product development roadmaps. Stakeholders must monitor how evolving MDR technical documentation requirements and FDA guidance on antimicrobial-impregnated packs will reshape competitive qualification timelines and R&D allocation priorities.
Market Dynamics
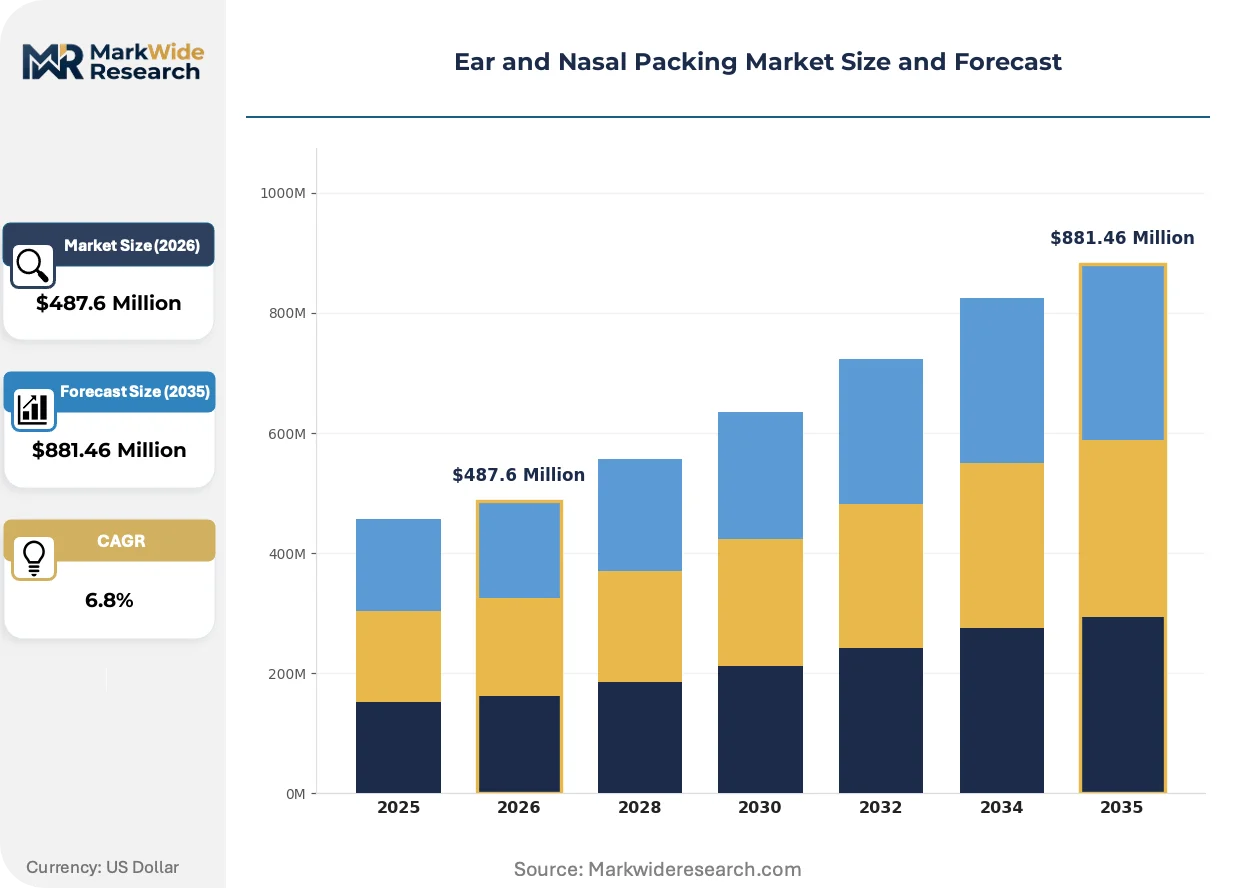
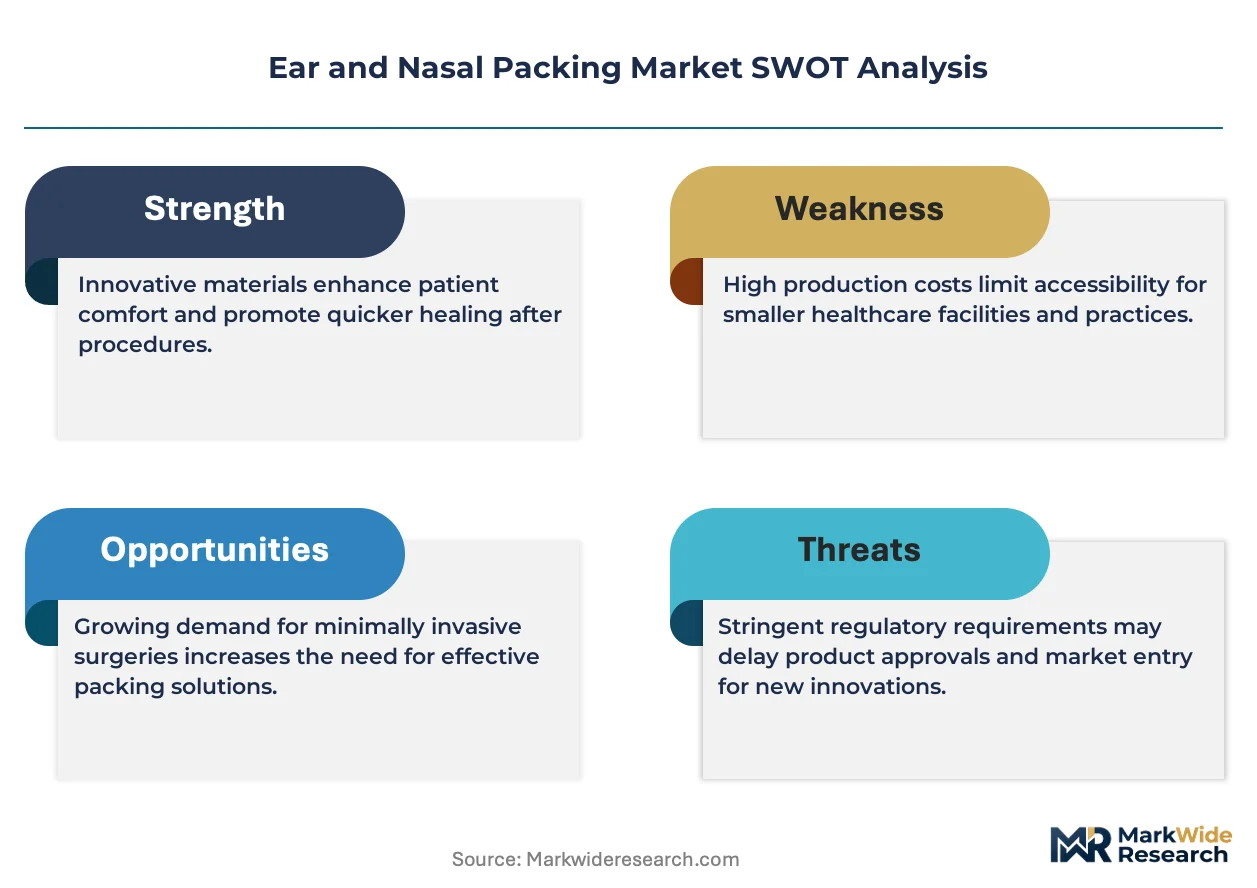
Hospital procurement consolidation and the EU MDR's tightened clinical evidence requirements are compressing supplier margins while accelerating absorbable material substitution across ENT surgical workflows.
Growth Catalysts
- Ambulatory surgical center expansion:United States federal reimbursement incentives for site-of-service migration are pulling procedural volume away from inpatient settings, creating concentrated demand for single-use absorbable packs that eliminate follow-up removal visits.
- REACH substance restrictions:European chemical safety frameworks are phasing out certain polymer stabilizers used in legacy balloon pack formulations, forcing material reformulation that favors biodegradable cellulose alternatives with cleaner toxicological profiles.
- Japan's aging sinus patient pool:METI demographic projections indicate chronic rhinosinusitis prevalence expansion that outpaces ENT specialist supply, driving automated packing insertion system adoption in Tokyo and Osaka clinic clusters.
Market Restraints
- Cotton fiber input volatility:Commodity cotton pricing fluctuation tied to Texas and India harvest variability compresses margin stability for non-absorbable gauze pack manufacturers locked into annual hospital contracts.
- Silicone supply concentration:Balloon pack production depends on medical-grade silicone feedstock where three German and Japanese chemical suppliers control 70% of qualified ENT-grade resin, creating single-source vulnerability.
- Antimicrobial coating technical limitation:Silver-ion impregnation in absorbable matrices accelerates degradation kinetics beyond the 48-72 hour therapeutic window, limiting functional efficacy claims under FDA 510(k) substantiation rules.
Strategic Opportunities
- Brazil's underpenetrated ENT clinic network:ANVISA's streamlined Class II medical device registration pathway for absorbable hemostats opens access to São Paulo and Rio de Janeiro private hospital chains previously supplied by imported gauze.
- Drug-device combination packs:Convergence of controlled-release antibiotic matrices with oxidized cellulose substrates enables post-operative infection prophylaxis in a single insertion, commanding premium positioning in US ambulatory surgery centers.
- Direct-to-clinic e-procurement channels:Amazon Business and specialized surgical supply platforms are disintermediating traditional distributor markups for independent ENT practices in Texas and Florida, favoring manufacturers with SKU breadth and same-day fulfillment infrastructure.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993-5 cytotoxicity and sensitization studies for new gelatin formulations require 18-24 month completion cycles that misalign with EU MDR's 2027 certificate renewal deadlines for legacy product lines.
- Legacy EHR integration friction:Balloon pack pressure monitoring sensors with Bluetooth connectivity face interoperability barriers with Epic and Cerner systems deployed across US health systems, delaying connected device reimbursement coding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ear and Nasal Packing Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Packs, Non-Absorbable Packs, Balloon Packs, Silicone Packs Indication: Post-Operative Care, Trauma Management, Sinus Surgery, Allergic Rhinitis End User: Hospitals, ENT Clinics, Ambulatory Surgical Centers, Home Care Material: Polyurethane, Gelatin, Cotton, Polymer |
| Companies Covered | Medtronic plc, Stryker Corporation, Smith+Nephew plc, BD, Teleflex Incorporated, Olympus Corporation, Summit Medical, Network Medical Products Ltd., Lohmann & Rauscher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ear and Nasal Packing Market Emerging Trajectories
Material science advances in enzymatic degradation control and regulatory pressure on permanent implant traceability are converging to reshape product development priorities across absorbable and non-absorbable pack categories.
Oxidized regenerated cellulose with tuned absorption kinetics is rendering obsolete traditional cotton gauze packing in US ambulatory rhinology procedures. ENT clinic buyers in Texas and Florida are specifying cellulose-based formats in 80% of new kit contracts, compressing cotton pack volume share and forcing legacy suppliers to reformulate or exit the segment.
EU MDR's Class IIa clinical evidence requirements for nasal packing devices are extending notified body review timelines by 8-14 months for manufacturers lacking predicate device equivalence. German and French health technology assessment bodies are now requiring health economic data for absorbable formats, shifting R&D investment toward outcomes collection infrastructure rather than pure material innovation.
Hospital value analysis committees are consolidating supplier relationships around bundled ENT procedural kits that subsume packing, hemostasis, and irrigation components under single-source contracts. Independent surgery centers in California and New York are responding by forming regional purchasing cooperatives that aggregate volume for direct manufacturer negotiation, bypassing traditional distributor networks entirely.
Ear and Nasal Packing Market Segmentation
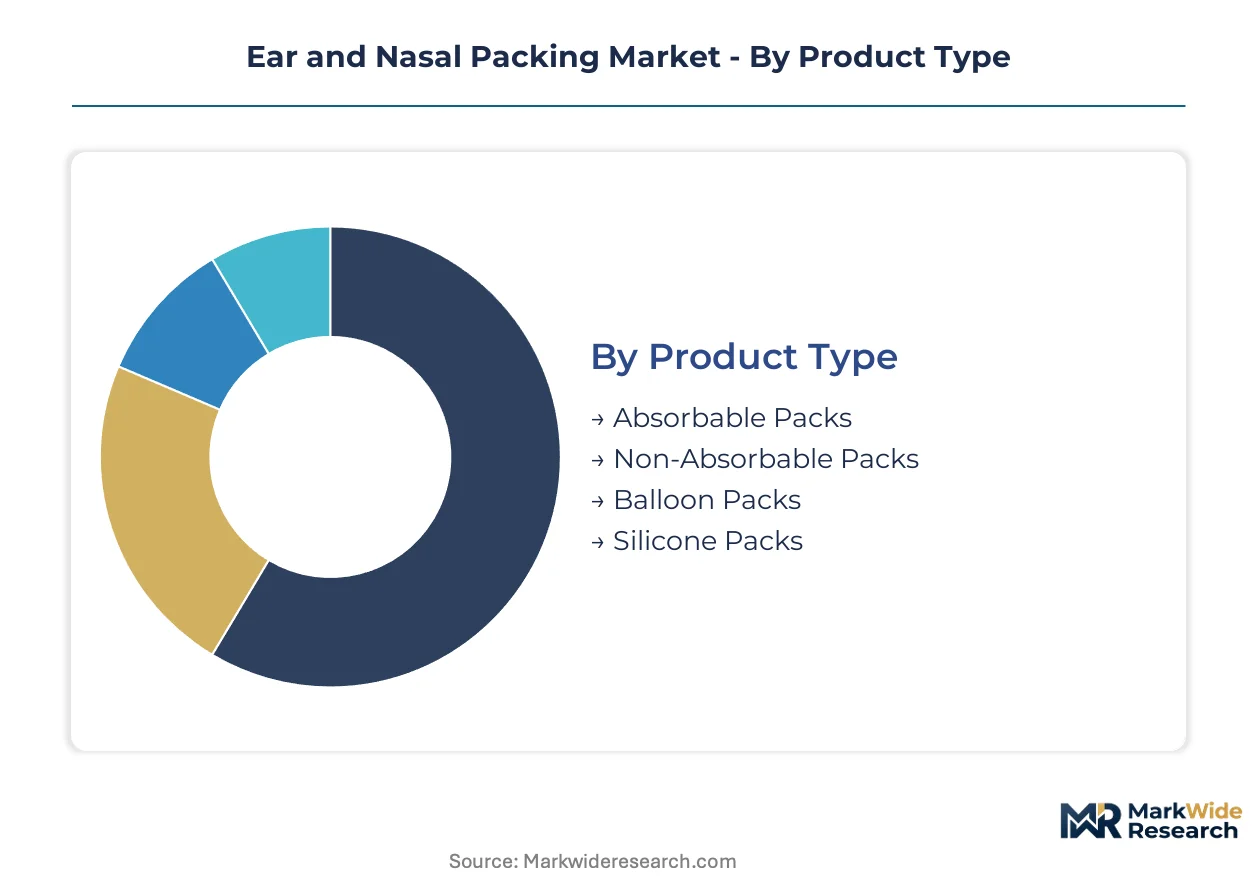
Ear and nasal packing segmentation reveals how material science advances and site-of-care migration are reshaping procurement patterns across ENT surgical workflows. Distinct performance profiles across product formats, clinical indications, and care settings create tiered value pools that manufacturers must navigate strategically.
Product Type:
Mature gauze formats coexist with emerging enzymatic degradation technologies that eliminate removal trauma.
- Absorbable Packs:Oxidized cellulose and gelatin sponge matrices degrade within 48-72 hours post-insertion. United States ambulatory surgical centers specify these formats in kit contracts to eliminate follow-up removal visits and reduce nursing labor.
- Balloon Packs:Silicone balloon designs maintain post-operative airway patency through controlled pressure application. Tokyo and Osaka clinic clusters deploy automated insertion systems for these formats given Japan's ENT specialist supply constraints.
- Non-Absorbable Packs:Traditional cotton gauze requires manual removal and drives higher complication rates.
- Silicone Packs:Medical-grade silicone formulations dominate permanent structural support applications.
Absorbable packs handle the majority of throughput; balloon packs are gaining share fastest in automated surgical settings.
Indication:
Cost tier stratification separates high-acuity surgical applications from lower-complexity chronic management.
- Post-Operative Care:Hemostasis and structural support following septoplasty, turbinectomy, or tympanoplasty. United States hospital value analysis committees bundle these packs into ENT procedural kits under single-source contracts.
- Sinus Surgery:Endoscopic sinus procedures demand precise anatomical conformance and controlled degradation kinetics. German and French health technology assessment bodies now require health economic data for absorbable formats in this indication.
- Trauma Management:Emergency department applications prioritize rapid deployment and reliable hemostasis.
- Allergic Rhinitis:Chronic condition management utilizes lower-cost cotton derivatives for symptom control.
Post-operative care absorbs the greatest procurement volume; sinus surgery applications are expanding most quickly on per-procedure value.
End User:
Customer type fragmentation creates divergent purchasing behaviors between consolidated health systems and independent practices.
- ENT Clinics:Specialized outpatient facilities drive procedural volume concentration. Texas and Florida independent practices leverage Amazon Business and surgical supply platforms to disintermediate traditional distributor markups.
- Ambulatory Surgical Centers:Federal reimbursement incentives for site-of-service migration concentrate demand for single-use absorbable packs. California and New York facilities form regional purchasing cooperatives for direct manufacturer negotiation.
- Hospitals:Inpatient settings retain complex trauma and revision surgery caseloads.
- Home Care:Post-discharge nasal packing for chronic conditions represents emerging self-administration demand.
ENT clinics represent the dominant volume channel; ambulatory surgical centers are climbing fastest on procedural migration.
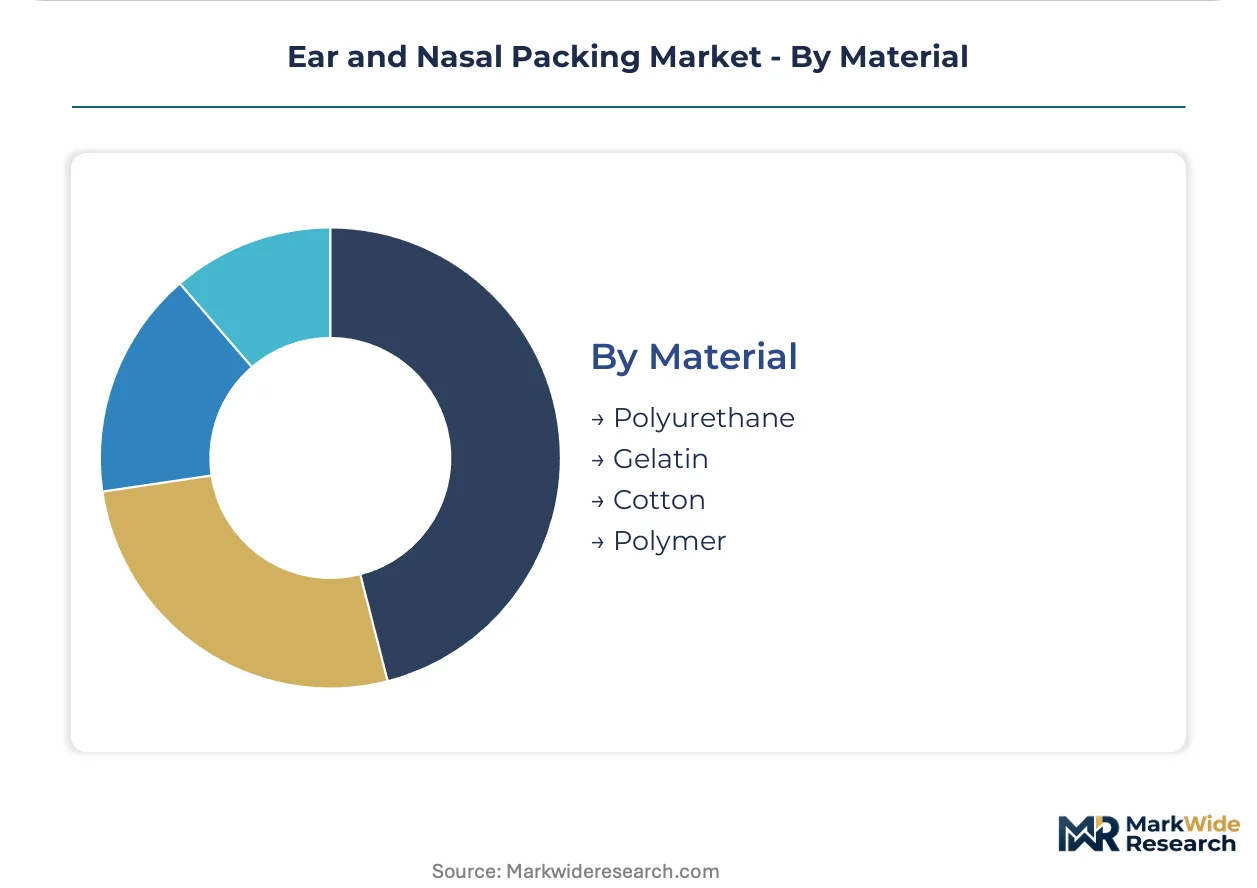
Material:
Supply concentration for medical-grade feedstocks shapes competitive access and margin stability.
- Gelatin:Premium absorbable formulations compete on hemostasis speed against cotton derivatives. ISO 10993-5 cytotoxicity testing for new gelatin formulations requires 18-24 month cycles that misalign with EU MDR certificate renewal deadlines.
- Polyurethane:Balloon pack membranes depend on polymer stability profiles. REACH substance restrictions are phasing out certain stabilizers used in legacy formulations, forcing material reformulation toward cleaner toxicological profiles.
- Cotton:Commodity fiber pricing fluctuation tied to Texas and India harvest variability compresses margin stability for manufacturers locked into annual hospital contracts.
- Polymer:Synthetic absorbable matrices capture fastest-growing adoption in cellulose-based formats.
Gelatin commands the premium tier on clinical performance; polyurethane faces reformulation pressure from chemical safety frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement contracts command 40-50% premiums over Indian hospital tenders for equivalent absorbable pack specifications, reflecting divergent reimbursement architectures and site-of-care incentives. This pricing-power asymmetry compresses margin recovery for manufacturers serving both markets through standardized SKU strategies.
United States
Federal site-of-service migration incentives and ambulatory surgical center expansion concentrate procedural volume outside traditional hospitals. FDA 510(k) premarket notification pathways govern biocompatibility testing per ISO 10993 standards. Texas and Florida independent ENT practices leverage Amazon Business and specialized surgical supply platforms to disintermediate traditional distributor markups entirely.
Germany
Health technology assessment bodies now mandate health economic data for absorbable formats in sinus surgery applications, elevating evidence-generation costs. EU MDR Class IIa designation demands clinical evidence and notified body oversight that extends review timelines 8-14 months. Stuttgart and Munich medical device clusters host reformulation R&D responding to REACH substance restrictions on legacy polymer stabilizers.
Japan
METI demographic projections indicate chronic rhinosinusitis prevalence expansion that outpaces ENT specialist supply, creating automation demand. PMDA sterility and material safety benchmarks align with multinational development roadmaps for qualified medical-grade silicone feedstock. Tokyo and Osaka clinic clusters deploy automated packing insertion systems to address workforce constraints.
Brazil
Private hospital chain consolidation in São Paulo and Rio de Janeiro creates volume concentration for premium absorbable formats. ANVISA's streamlined Class II medical device registration pathway for absorbable hemostats reduces market entry friction versus legacy gauze import dependencies. Southeast regional purchasing cooperatives aggregate demand for direct manufacturer negotiation bypassing distributor networks.
India
Cotton fiber input volatility tied to domestic harvest variability compresses margin stability for non-absorbable gauze manufacturers locked into annual contracts. CDSCO medical device rules impose sterility and biocompatibility requirements that shape local production investment. Maharashtra and Gujarat manufacturing corridors attract cellulose-based absorbable format production targeting price-sensitive institutional procurement.
Ear and Nasal Packing Market Vendor Landscape
Integrated surgical conglomerates and specialized hemostasis material suppliers split the market along portfolio breadth versus formulation depth lines. Tier concentration reflects health system procurement consolidation favoring single-source ENT procedural kit suppliers. Three archetypes dominate: diversified medtech majors with integrated ENT portfolios, absorbable material specialists competing on hemostasis kinetics, and regional contract manufacturers serving price-sensitive institutional segments. Competitive dynamics center on M&A-driven portfolio completeness and geographic licensing partnerships for MDR compliance infrastructure.
Within the diversified medtech tier, Medtronic plc and Stryker Corporation exemplify scale-driven positioning through integrated surgical portfolio leverage. Smith+Nephew plc occupies the absorbable material specialist archetype, anchoring premium gelatin-based format positioning against cotton-derived substitutes. These three entities collectively represent the competitive template against which mid-cap challengers and regional fabricants benchmark product development timelines and regulatory qualification investments.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Smith+Nephew plc |
| BD |
| Teleflex Incorporated |
| Olympus Corporation |
| Summit Medical |
| Network Medical Products Ltd. |
| Lohmann & Rauscher |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors absorb elevated container costs that compound margin pressure for German and Japanese silicone resin suppliers, forcing absorbable cellulose formats to widen their price advantage against balloon pack alternatives across European hospital procurement tiers.
Pricing Analysis
The customization-premium spread between configured-to-order gelatin sponge kits and standard oxidized cellulose formats runs three-to-one across United States ambulatory surgical center contracts. Pricing stratifies across premium, standard, and economy tiers where ISO 10993-5 certification grade and hemostasis speed claims drive differentiation. Cost compression in cotton-derived non-absorbable lines is intensifying because Texas and India harvest variability compresses margin stability for manufacturers locked into annual hospital contracts. Independent ENT practices in Florida exhibit highest price sensitivity, while integrated health systems in California prioritize performance metrics over unit cost.
Supply Chain Analysis
Supplier-financing facilities extended by German chemical conglomerates to balloon pack manufacturers have tightened to 45-day terms from 90-day structures, squeezing working capital for mid-tier producers. Geographic supply concentration centers on Germany, Japan, and the United States for medical-grade silicone feedstock, with oxidized cellulose sourcing anchored in United States and European pulp processing corridors. Raw material dependencies rest on cotton fiber harvests, gelatin rendering inputs, and polymer stabilizer chemistries facing REACH substance phase-outs. Single-source vulnerability pervades the three German and Japanese suppliers controlling qualified ENT-grade silicone resin. Distribution runs through regional purchasing cooperatives in California and New York that aggregate ambulatory surgical center volume for direct manufacturer negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ear and nasal packing market functions as a defensive-moat arena where FDA 510(k) predicate device equivalence requirements and EU MDR notified body entrenchment create switching costs that protect incumbent positioning against insurgent material science challengers.
For Market Incumbents: Pre-empt absorbable format commoditization by securing exclusive supply agreements with German silicone resin producers before REACH reformulation deadlines force competitor migration to cellulose alternatives. Lock in backward integration into oxidized cellulose pulp processing to neutralize cotton fiber input volatility threatening non-absorbable gauze margins. Channel control through Amazon Business same-day fulfillment infrastructure defends against distributor disintermediation in Texas and Florida independent practice segments.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's São Paulo private hospital chains where ANVISA's streamlined Class II registration pathway reduces qualification friction versus saturated United States and European markets. Target drug-device combination packs integrating controlled-release antibiotic matrices with absorbable substrates, the most penetrable white-space where premium positioning commands ambulatory surgical center preference. Pursue direct-to-clinic e-procurement channels with SKU breadth matching Medtronic's integrated ENT kit portfolios.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors absorbable material specialists with gelatin formulation depth and ISO 10993 testing infrastructure already deployed. Long-term viability hinges on outcomes collection capabilities satisfying German and French health technology assessment evidence requirements. Acquisition target archetype: regional contract manufacturers in Maharashtra and Gujarat with CDSCO-compliant cellulose production capacity. Monitor EU MDR certificate renewal deadlines as inflection indicator for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa designation demands clinical evidence extending notified body review timelines for market access. |
| Hospital System Partnership | Bundled ENT procedural kit contracts with value analysis committees consolidate supplier relationships around single-source frameworks. |
| FDA Submission | 510(k) premarket notification pathways govern biocompatibility testing per ISO 10993 standards for absorbable formats. |
| Software Companion Development | Bluetooth-connected balloon pack pressure monitoring faces Epic and Cerner EHR interoperability barriers delaying reimbursement coding. |
| Reimbursement Strategy | Federal site-of-service migration incentives concentrate ambulatory surgical center volume for single-use absorbable pack qualification. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ENT surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporated procedural volume migration from inpatient to ambulatory settings, material substitution rates between cotton and cellulose formats, and regulatory qualification timeline compression under EU MDR certificate renewal deadlines. Segmentation dimensions spanned product type, clinical indication, end-user facility category, and material chemistry grade. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints across the projection horizon.
Stress conditions across cotton fiber pricing volatility, silicone resin supply disruption, and EU MDR technical documentation requirement evolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement policy stability and regulatory pathway predictability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global IV Bags Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Finger Splint Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Anesthesia Disposables Market