
 Global Hernia Repair Devices and Consumables Market | 2026-2036
Global Hernia Repair Devices and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hernia Repair Devices and Consumables Market Foresight
Ambulatory surgical centers are bifurcating demand away from traditional hospital procurement, favoring single-use fixation devices and pre-packaged mesh kits over bulk institutional contracts. Medtronic leverages its laparoscopic portfolio to sustain channel control across outpatient settings. Johnson & Johnson anchors open surgery segments through Ethicon's suture dominance, while B. Braun Melsungen AG differentiates via specialized composite meshes for complex incisional repairs.
Hernia repair devices and consumables encompass synthetic and biologic mesh implants, absorbable and non-absorbable sutures, mechanical fixation tacks, tissue adhesives, and specialized surgical instruments designed to reinforce abdominal wall defects and prevent recurrence. Polypropylene meshes remain the most widely deployed synthetic substrate due to tensile strength, pore architecture, and established long-term hernioplasty outcomes. Mesh implants command the largest revenue pool among product types, though robotic-assisted deployment represents the fastest-expanding procedural category as capital equipment amortization shifts toward high-volume ambulatory networks. Sutures and fixation devices constitute mature, price-sensitive segments where procurement consolidation squeezes margin pools.
FDA 510(k) pathways govern mesh implant clearance in the United States, while the EU MDR and CE marking requirements impose stricter clinical evidence standards for permanent implants. Japan's PMDA maintains distinct biocompatibility testing protocols that extend market access timelines for foreign manufacturers. Stakeholders must monitor reimbursement parity between laparoscopic and robotic-assisted codes across Medicare, Germany's G-DRG system, and Japan's fee schedules to anticipate capital allocation shifts.
Market Dynamics
Ambulatory surgical centers are capturing procedure volume from inpatient settings, forcing manufacturers to reconfigure product formats and distribution economics around same-day discharge protocols and reduced sterilization infrastructure.
Growth Catalysts
- Laparoscopic procedure expansion:Minimally invasive techniques reduce recovery timelines and complication rates, pulling volume from open repair methods across United States, Germany, and Japan surgical networks.
- EU MDR biocompatibility mandates:Stricter clinical evidence requirements for permanent implants accelerate淘汰 of inferior mesh substrates while consolidating procurement toward validated suppliers.
- Robotic-assisted deployment:Capital equipment amortization across high-volume ambulatory networks creates new revenue pools for precision fixation and navigation-compatible mesh systems.
Market Restraints
- Polypropylene raw material concentration:Synthetic mesh substrate supply clusters among petrochemical processors in Texas and Rotterdam, exposing manufacturers to feedstock volatility and logistics disruption.
- PMDA biocompatibility testing protocols:Japan's distinct evaluation timelines extend market access by months, compressing effective patent life and delaying revenue recognition for foreign entrants.
- Biologic mesh cost structures:Porcine and bovine-derived substrates carry harvest-to-sterilization complexity that limits price elasticity and constrains penetration in cost-sensitive health systems.
Strategic Opportunities
- Composite mesh specialization:Multi-layer synthetic-biologic hybrids address complex incisional repairs with recurrence-resistant architecture, commanding premium positioning in tertiary referral centers.
- Single-use fixation device formats:Pre-sterilized, procedure-matched tack and suture kits align with ambulatory center inventory constraints and eliminate reprocessing overhead.
- Medicare reimbursement parity expansion:Laparoscopic-robotic code convergence in United States fee schedules accelerates capital equipment placement and consumable pull-through.
Industry Challenges
- Mesh implant litigation exposure:Chronic pain and adhesion-related product liability claims require dedicated legal reserves and influence R&D prioritization toward next-generation substrates.
- EU MDR technical documentation:Clinical evidence compilation for legacy devices strains regulatory affairs capacity while Notified Body capacity constraints extend certification timelines.
- Surgeon retraining requirements:Robotic platform proficiency demands simulation-based credentialing that slows adoption velocity in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hernia Repair Devices and Consumables Market |
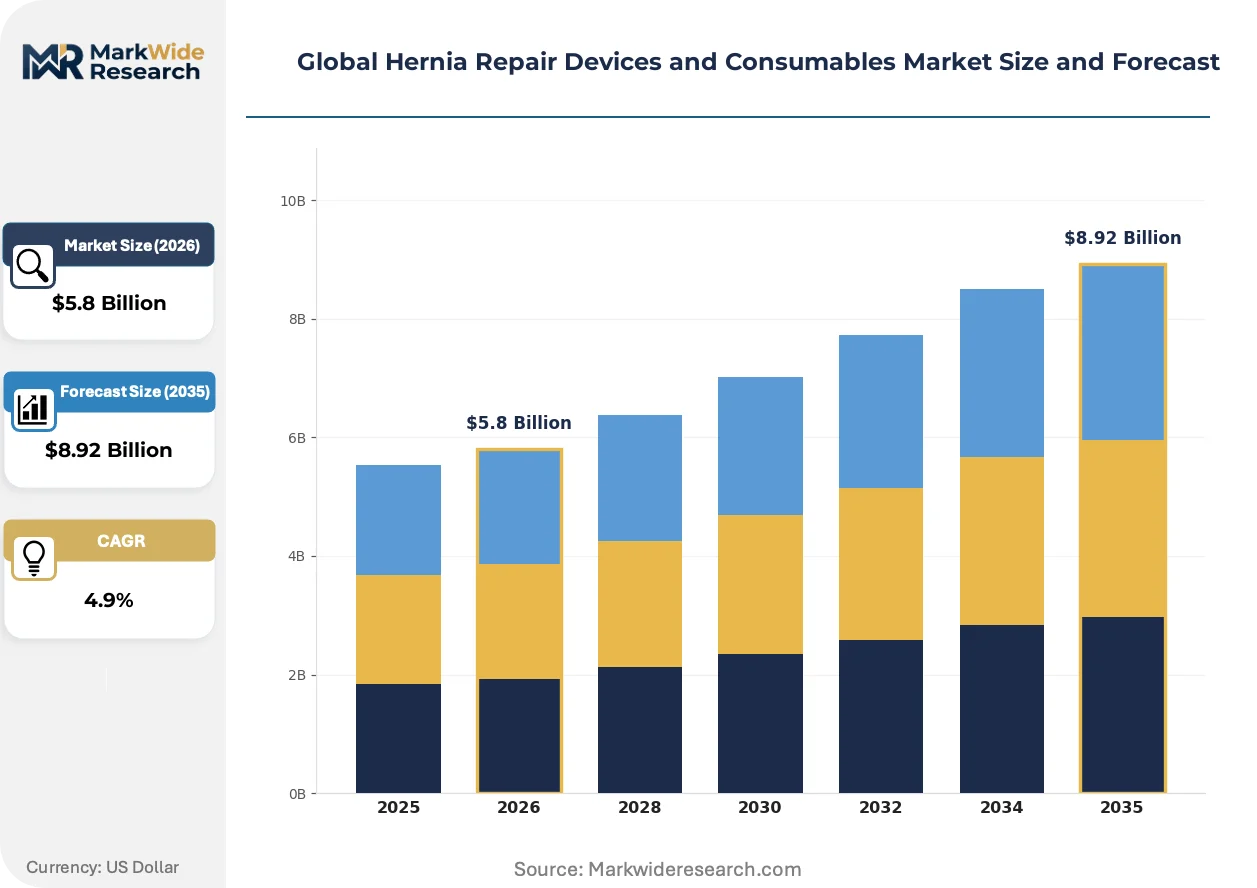
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh Implants, Sutures, Fixation Devices, Adhesives, Surgical Instruments Application: Inguinal Hernia Repair, Umbilical Hernia Repair, Incisional Hernia Repair, Femoral Hernia Repair, Hiatal Hernia Repair End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Outpatient Facilities, Academic Medical Centers Deployment: Laparoscopic Surgery, Open Surgery, Robotic-assisted Surgery, Hybrid Techniques, Minimally Invasive Procedures |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun Melsungen AG, Becton Dickinson and Company, Ethicon, W. L. Gore & Associates, Cook Medical, Baxter International, Allergan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hernia Repair Devices and Consumables Market Shifts & Advancements
Mesh implant technology is fragmenting across performance tiers while regulatory scrutiny intensifies substrate biocompatibility standards. Distribution economics are compressing as procurement authority consolidates.
Resorbable synthetic polymers are bifurcating the biologic mesh segment by offering controlled degradation timelines without xenograft sourcing complexity. Ambulatory surgical centers in United States metropolitan clusters are adopting these substrates for ventral and inguinal repairs where long-term foreign body presence is clinically undesirable. The technology is bifurcating procurement patterns toward procedure-specific kits that bundle mesh with matched fixation systems.
EU MDR Article 10 clinical evaluation requirements are forcing systematic post-market surveillance infrastructure for permanent implants. Manufacturers must maintain periodic safety update reports and vigilance systems that track device performance across diverse European patient populations. Germany's G-DRG reimbursement framework is responding with procedure code refinements that differentiate mesh complexity tiers.
Hospital procurement consolidation is aggregating demand through centralized contracting organizations that standardize mesh specifications across multi-facility networks. United States integrated delivery networks are displacing individual surgeon preference with value-analysis committee decisions that prioritize contract compliance over brand loyalty. This concentration is most visible in mid-Atlantic and Midwest health systems where Catholic and for-profit chains dominate regional capacity.
Global Hernia Repair Devices and Consumables Market Segmentation
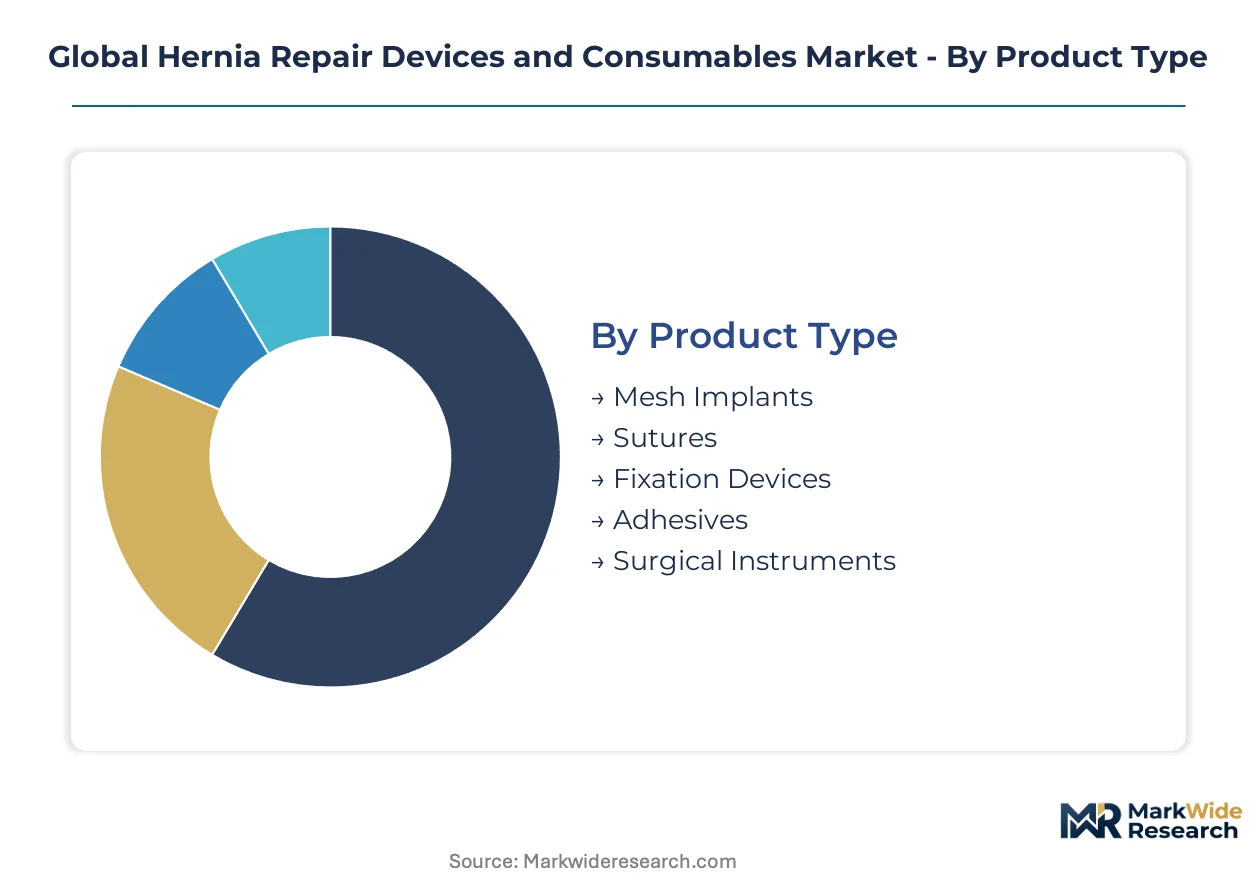
Segmentation in hernia repair reveals divergent substitution pressures across substrate technologies and procedural formats. Procurement patterns fragment sharply between inpatient volume centers and ambulatory networks with incompatible inventory economics.
Product Type:
Substitution pressure concentrates most intensely on sutures and mechanical fixation, where resorbable polymers and tissue adhesives erode legacy mechanical formats.
- Mesh Implants:Polypropylene substrates dominate synthetic deployment due to tensile strength and pore architecture optimized for tissue ingrowth. Demand concentrates in United States metropolitan ambulatory clusters where laparoscopic pre-packaged kits displace bulk institutional purchasing. EU MDR biocompatibility mandates accelerate consolidation toward validated suppliers with established vigilance systems.
- Sutures:Absorbable and non-absorbable filament formats anchor open surgery segments, particularly in community hospital settings with limited minimally invasive infrastructure. Germany's G-DRG system and Japan's fee schedules maintain reimbursement parity that sustains volume despite robotic encroachment in tertiary centers.
- Fixation Devices:Mechanical tacks and suture anchors face displacement from tissue adhesives in selected ventral repairs.
- Adhesives:Synthetic sealants target mesh fixation without foreign body penetration in thin abdominal walls.
- Surgical Instruments:Graspers, dissecting forceps, and mesh deployment systems complete procedure-specific kits.
Mesh implants anchor the volume base while adhesives gain share at the steepest rate.
Application:
Cost tier stratification separates high-complexity incisional repairs from commoditized inguinal procedures.
- Inguinal Hernia Repair:Laparoscopic transabdominal preperitoneal and totally extraperitoneal approaches dominate volume, with polypropylene mesh standardization driving procurement consolidation. United States Medicare reimbursement codes and Germany's G-DRG framework maintain procedural incentives that sustain outpatient migration.
- Incisional Hernia Repair:Complex abdominal wall reconstructions demand composite mesh architectures with synthetic-biologic layering. Tertiary referral centers in Japan and the United States command premium positioning for recurrence-resistant substrates in contaminated fields.
- Umbilical Hernia Repair:Small defect closures favor suture-only techniques in pediatric and thin adult populations.
- Femoral Hernia Repair:Emergency presentations sustain open surgery dominance with synthetic mesh reinforcement.
- Hiatal Hernia Repair:Fundoplication mesh augmentation remains controversial, limiting substrate penetration.
Inguinal repair commands the largest procedure volume while incisional applications expand most quickly through tertiary center specialization.
End User:
Customer type fragmentation reflects sterilization infrastructure divergence and capital equipment access.
- Hospitals:Inpatient surgical departments maintain open surgery capacity for emergency and complex cases, with centralized sterilization supporting reusable instrument formats. United States integrated delivery networks and German hospital federations aggregate procurement through value-analysis committees.
- Ambulatory Surgical Centers:Same-day discharge protocols favor single-use fixation kits and pre-sterilized mesh formats that eliminate reprocessing overhead. United States metropolitan clusters lead deployment, with reimbursement parity between facility fees and hospital outpatient departments sustaining margin structures.
- Specialty Clinics:Hernia-focused practices concentrate laparoscopic volume with dedicated credentialing pathways.
- Outpatient Facilities:Hospital-affiliated satellite locations bridge acute and ambulatory care models.
- Academic Medical Centers:Robotic platform training and complex case referral sustain hybrid technique development.
Hospitals retain the highest absolute case volume while ambulatory surgical centers climb the fastest as procedural migration accelerates.
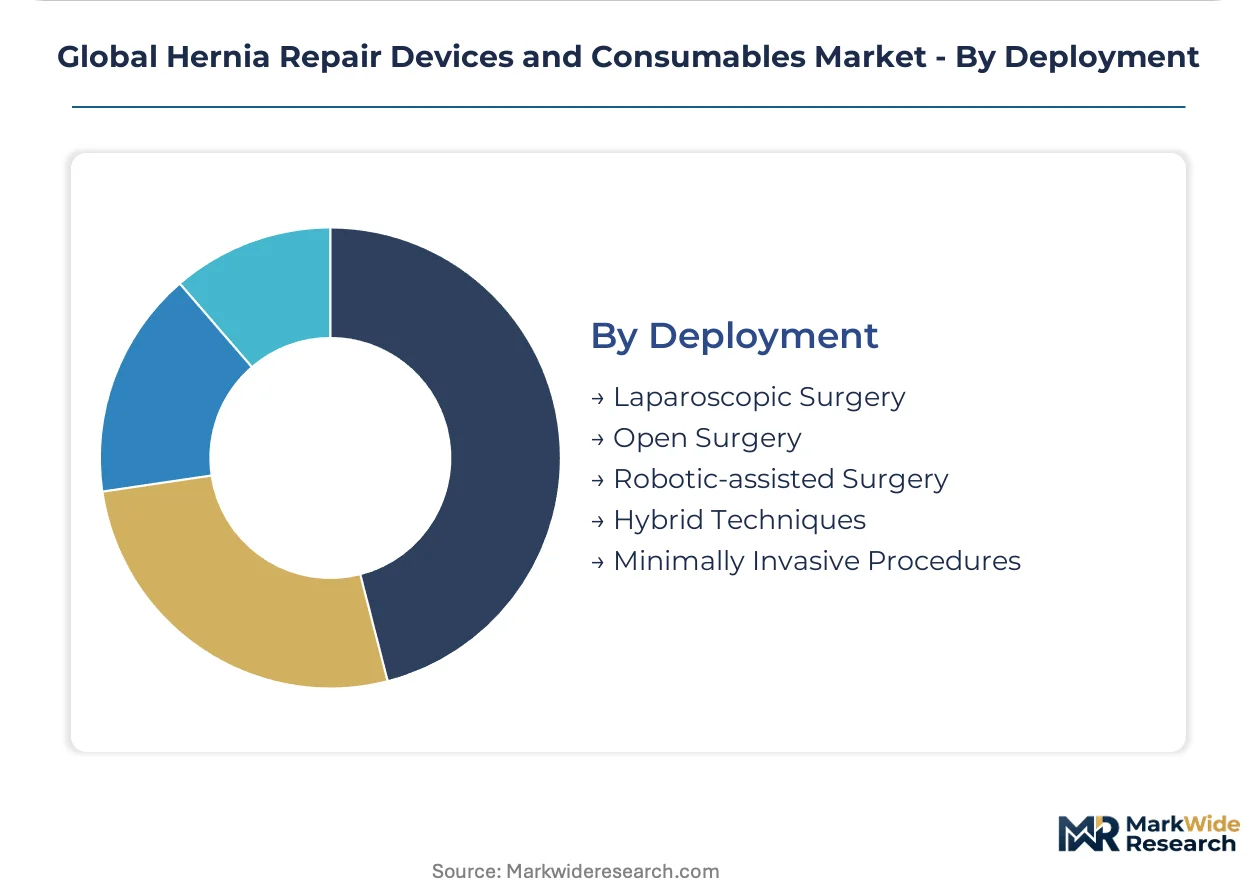
Deployment:
Technology maturity curves separate established laparoscopic formats from capital-intensive robotic expansion.
- Laparoscopic Surgery:Minimally invasive techniques with standardized port placement and mesh deployment systems dominate inguinal and ventral repairs. Surgeon training infrastructure in the United States, Germany, and Japan sustains volume growth with established complication profiles and recurrence data.
- Robotic-assisted Surgery:Capital equipment amortization across high-volume United States ambulatory networks creates dedicated revenue pools for navigation-compatible mesh and precision fixation systems. Japan's PMDA regulatory timelines and reimbursement negotiations constrain comparable deployment velocity.
- Open Surgery:Emergency presentations, contaminated fields, and resource-limited settings sustain mechanical suture and mesh placement.
- Hybrid Techniques:Combined laparoscopic and open approaches address complex incisional defects.
- Minimally Invasive Procedures:Umbrella category capturing evolving percutaneous and single-port formats.
Laparoscopic deployment anchors current procedure volume while robotic-assisted modalities gain share at the steepest rate through capital equipment placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered mesh substrates to ambulatory networks across the United States and Japan, establishing a critical trade corridor in advanced hernia repair materials.
United States
Medicare reimbursement parity between laparoscopic and robotic-assisted procedures accelerates capital equipment placement in metropolitan ambulatory clusters. FDA 510(k) clearance pathways govern mesh implant market entry, with post-market surveillance requirements intensifying after high-profile litigation. Texas and California medical device corridors concentrate sterilization infrastructure and distribution hubs serving same-day surgery networks.
Germany
G-DRG procedure code refinements differentiate mesh complexity tiers, sustaining premium positioning for composite substrates in incisional repairs. EU MDR Article 10 clinical evaluation mandates strain Notified Body capacity, extending certification timelines for permanent implants. Baden-Württemberg and Bavaria host specialized textile processors supplying polypropylene mesh substrates to European and Asian manufacturers.
Japan
PMDA biocompatibility testing protocols extend market access timelines by months, compressing effective patent life for foreign entrants. METI reimbursement negotiations constrain robotic-assisted deployment velocity relative to laparoscopic volume growth. Tokyo and Osaka metropolitan surgical networks concentrate tertiary referral capacity for complex abdominal wall reconstructions.
United Kingdom
NHS procurement consolidation through centralized contracting aggregates demand across integrated care systems, standardizing mesh specifications. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining national variation assessments. London and Manchester academic medical centers sustain hybrid technique development for complex incisional repairs.
India
CDSCO medical device rules impose quality management system requirements that extend registration timelines for imported mesh implants. Cost-sensitive public health systems favor polypropylene substrates over biologic alternatives, constraining premium penetration. Maharashtra and Karnataka medical device manufacturing zones develop domestic mesh production capabilities for regional supply.
Global Hernia Repair Devices and Consumables Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with laparoscopic portfolio breadth, creating tiered competition between full-spectrum suppliers and specialized mesh fabricators. Market structure consolidates around entities with sterilization infrastructure and ambulatory distribution networks. Three archetypes dominate: integrated surgical technology platforms, specialized biomaterial substrate developers, and regional contract manufacturers. Competitive dynamics center on EU MDR certification velocity and ambulatory surgical center procurement consolidation.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson occupy positions spanning laparoscopic instrumentation and mesh substrates, while B. Braun Melsungen AG represents specialized European fabrication expertise. These entities exemplify contrasting strategic postures: full-surgical-workflow control versus substrate-specific specialization. The competitive terrain rewards entities with established vigilance systems for EU MDR compliance and pre-sterilized kit formats aligned with ambulatory inventory constraints.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Becton Dickinson and Company |
| Ethicon |
| W. L. Gore & Associates |
| Cook Medical |
| Baxter International |
| Allergan |
| Others |
Supply & Pricing Matrix
Ninety-day sterilization validation cycles for pre-packaged mesh kits compress inventory turns and amplify pricing power for suppliers with captive ethylene oxide infrastructure. This lead-time architecture concentrates margin capture among vertically integrated manufacturers while forcing ambulatory surgical centers into long-term offtake commitments that lock in volume tiers.
Pricing Analysis
Next-generation resorbable synthetic polymers command 40-60% premiums over standard polypropylene substrates, while legacy mechanical fixation devices face commoditization in open surgery segments. Three-tier pricing structure across premium composite meshes, standard polypropylene substrates, and economy suture kits reflects EU MDR certification grade and sterilization complexity. Cost compression in mechanical fixation stems from procurement consolidation through United States integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge economics, while tertiary referral centers absorb premium positioning for complex incisional repairs.
Supply Chain Analysis
Germany and the United States anchor precision mesh substrate fabrication, with Baden-Württemberg textile processors and Texas petrochemical corridors supplying polypropylene resin to global sterilization hubs. Raw material flows draw from Rotterdam propylene derivatives, Japanese precision weaving equipment, and domestic ethylene oxide sterilization capacity. Single-source vulnerability concentrates in Texas Gulf Coast propylene supply following regional weather disruptions. Distribution runs through hospital procurement organizations and ambulatory center group purchasing organizations that aggregate demand across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as robotic-assisted deployment creates interoperable consumable ecosystems that lock ambulatory networks into navigation-compatible mesh and fixation bundles.
For Market Incumbents: Secure EU MDR certification velocity by dedicating regulatory affairs capacity to legacy device technical documentation, insulating against Notified Body bottlenecks that threaten market access. Anchor backward integration into polypropylene resin supply through long-term offtake agreements with Rotterdam and Texas petrochemical processors, defending margin structures against feedstock volatility. For New Entrants and Emerging Players: Differentiate on resorbable synthetic polymer formulations that bypass xenograft sourcing complexity, targeting ambulatory surgical centers in United States metropolitan clusters where long-term foreign body presence faces clinical resistance. Penetrate through procedure-specific kit formats that bundle mesh with matched fixation systems, exploiting inventory constraints that disadvantage bulk institutional suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across robotic-assisted consumables as capital equipment amortization shifts toward high-volume ambulatory networks, reducing per-procedure equipment overhead. Target specialized biomaterial substrate developers with established vigilance systems for EU MDR compliance. Monitor Medicare reimbursement parity negotiations between laparoscopic and robotic-assisted codes as the signal for capital allocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerated technical documentation investment secures permanent implant market access amid Notified Body capacity constraints. |
| Pre-Sterilized Kit Format Development | Procedure-matched bundles align with ambulatory surgical center inventory constraints and eliminate reprocessing overhead. |
| Composite Mesh Specialization | Multi-layer synthetic-biologic hybrids command premium positioning in tertiary referral centers for complex incisional repairs. |
| Hospital System Partnership | Value-analysis committee relationships displace individual surgeon preference with contract compliance in integrated delivery networks. |
| Reimbursement Strategy | Medicare and G-DRG code convergence between laparoscopic and robotic modalities accelerates capital equipment placement. |
Research Methodology
A standing panel of hernia repair surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across synthetic and biologic substrate categories.
Forecast outputs were stress-tested against external benchmarks including capital equipment placement rates in United States ambulatory networks and EU MDR certification velocity timelines. Segmentation dimensions spanned substrate technology, procedural approach, end-user facility type, and geographic regulatory cluster. CAGRs were derived from procedure volume elasticity to reimbursement parity shifts and capital equipment amortization curves. Industry-specific inputs incorporated laparoscopic-to-robotic migration rates and sterilization infrastructure expansion timelines.
Material uncertainties — PMDA biocompatibility testing delays, polypropylene feedstock disruption, and mesh litigation settlement waves — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement code maintenance. Recalibration cycles align with material shifts in EU MDR implementation velocity and Medicare fee schedule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Retractors Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Sphincterotomes Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Smart Vision Aids Market