
 High Flow Ventilators Market | 2026-2036
High Flow Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
High Flow Ventilators Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote monitoring platforms as hospitals seek to maximize device uptime. Fisher & Paykel Healthcare leverages its integrated humidification technology to anchor recurring consumables sales alongside hardware placements. ResMed competes through cloud-connected ventilation platforms that extend clinical oversight into home care settings. Drägerwerk AG & Co. KGaA dominates European hospital procurement channels through comprehensive service-level agreements.
High flow ventilators deliver heated, humidified oxygen at flow rates exceeding traditional nasal cannula systems, typically operating between 8 and 80 liters per minute with precise fraction of inspired oxygen control. These devices reduce intubation rates in acute hypoxemic respiratory failure by providing positive airway pressure through nasal prongs. Stationary units installed in intensive care settings capture the largest margin pools due to bundled consumables contracts, while portable configurations designed for emergency transport and home transition represent the fastest-expanding segment. Non-invasive technology platforms are displacing conventional oxygen delivery in pre-intubation protocols across tertiary hospitals.
The FDA enforces 510(k) clearance pathways with escalating clinical data requirements for novel high flow interfaces, while the EU MDR mandates notified body oversight and post-market surveillance for respiratory support devices. These frameworks lengthen product development timelines but create structural barriers that favor established manufacturers with regulatory infrastructure. Stakeholders must monitor reimbursement policy shifts for non-invasive respiratory support as payors recalibrate coverage criteria between acute and ambulatory settings.
Market Dynamics
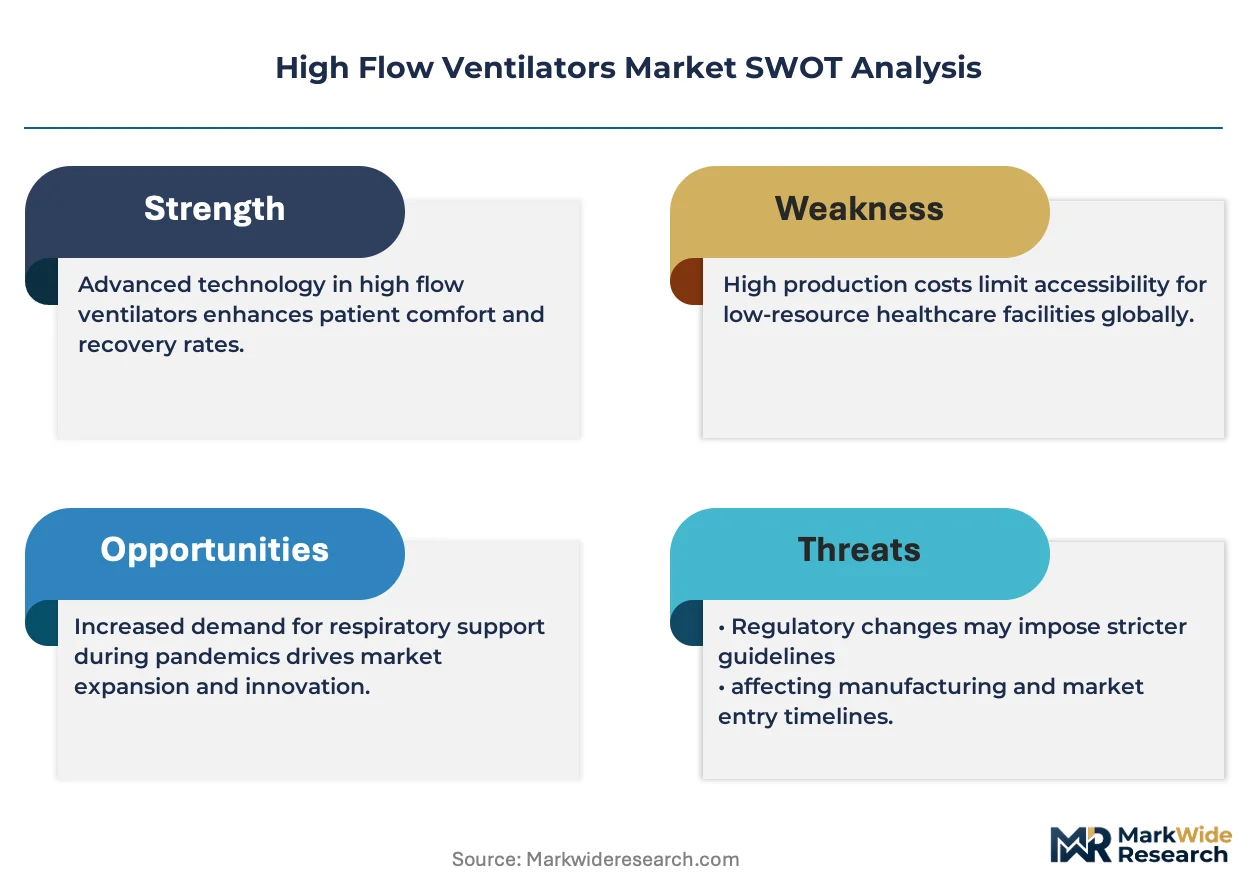
Heated humidification systems are displacing conventional oxygen delivery in pre-intubation protocols, forcing manufacturers to reconfigure R&D budgets toward clinical validation infrastructure and recurring consumables revenue models.
Growth Catalysts
- EU MDR compliance mandates:Stricter notified body oversight for respiratory support devices creates structural barriers that reward established manufacturers with regulatory infrastructure investments.
- Intensive care unit expansion:Tertiary hospital systems across the United States, Germany, and China are scaling critical care bed capacity, anchoring stationary unit demand.
- Humidification technology maturation:Precision FiO2 control at 8-80 L/min flow rates enables non-invasive alternatives to mechanical ventilation in acute hypoxemic respiratory failure.
Market Restraints
- 510(k) pathway escalation:FDA clinical data requirements for novel high flow interfaces extend product development timelines and compress returns on innovation.
- Consumables cost concentration:Bundled contracts for heated breathing circuits and nasal interfaces lock hospitals into single-source dependencies.
- Home care reimbursement uncertainty:Payor recalibration between acute and ambulatory coverage criteria creates demand volatility for portable configurations.
Strategic Opportunities
- Emergency transport applications:Portable configurations designed for inter-hospital transfer and field deployment represent underserved demand pockets.
- Remote monitoring convergence:Cloud-connected platforms integrating high flow data with electronic health records enable predictive maintenance contracts.
- Post-market surveillance infrastructure:EU MDR mandated vigilance systems create service revenue streams for manufacturers with established quality management systems.
Industry Challenges
- Clinical validation capacity:Randomized controlled trial execution for novel interfaces requires specialized respiratory research networks that concentrate in academic medical centers.
- Legacy system integration:Hospital information system connectivity for ventilation data streams demands interoperability investments that strain mid-tier manufacturer budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Flow Ventilators Market |
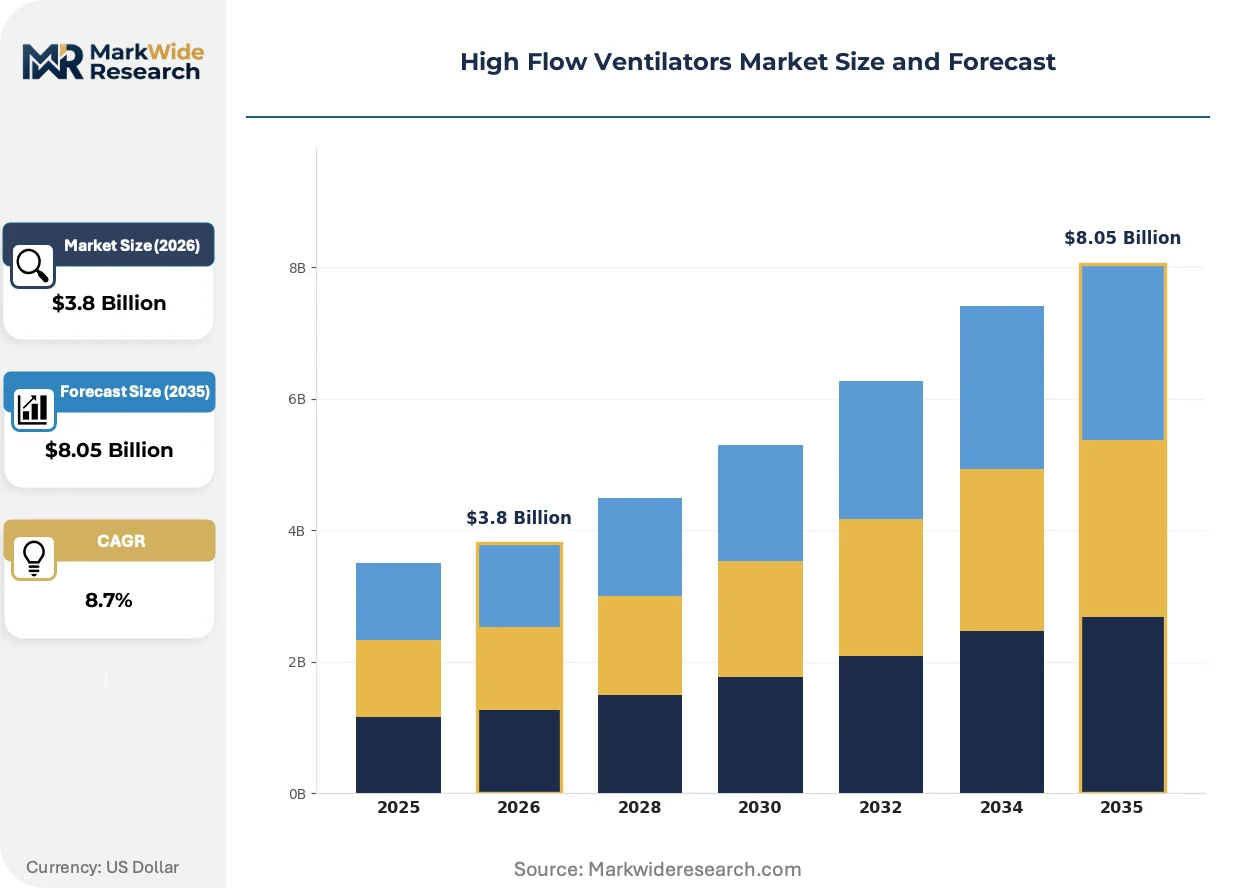
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Emergency, Pediatric End User: Hospitals, Home Care, Emergency Services, Long-term Care Facilities Technology: High-Pressure, Low-Pressure, Heated Humidity, Non-Invasive Application: Respiratory Failure, COVID-19 Treatment, Sleep Apnea, Anesthesia |
| Companies Covered | Getinge AB, Hamilton Medical, Koninklijke Philips NV, Medtronic PLC, ResMed, VYAIRE, Fisher & Paykel Healthcare, Vapotherm, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Flow Ventilators Market Shifts & Advancements
Digital integration is compressing the boundary between acute and ambulatory respiratory care, with platform architectures determining competitive positioning more than hardware specifications alone.
Integrated humidification modules with embedded flow sensors and automated temperature regulation are virtualizing the distinction between device and consumable revenue streams. ICU procurement committees in the United States and Germany now evaluate total cost of ownership across multi-year contracts rather than capital expenditure alone. This shift is virtualizing hardware margins into recurring revenue pools that favor manufacturers with captive supply of heated breathing circuits.
EU MDR Article 10 technical documentation requirements and post-market clinical follow-up obligations are restructuring competitive entry barriers for respiratory support devices. Manufacturers must maintain notified body relationships across multiple European member states to sustain market access. This regulatory architecture most affects novel interface designs and software-enabled flow algorithms, pushing development resources toward incremental improvements of cleared predicate devices.
Service unbundling is fragmenting traditional equipment procurement into separate hardware, consumables, and remote monitoring contracts. Hospital supply chain directors in China and the United States are negotiating predictive maintenance agreements that transfer uptime risk to manufacturers. This purchasing pattern shift concentrates in tertiary care networks with dedicated biomedical engineering departments capable of managing multi-vendor platform integrations.
High Flow Ventilators Market Segmentation
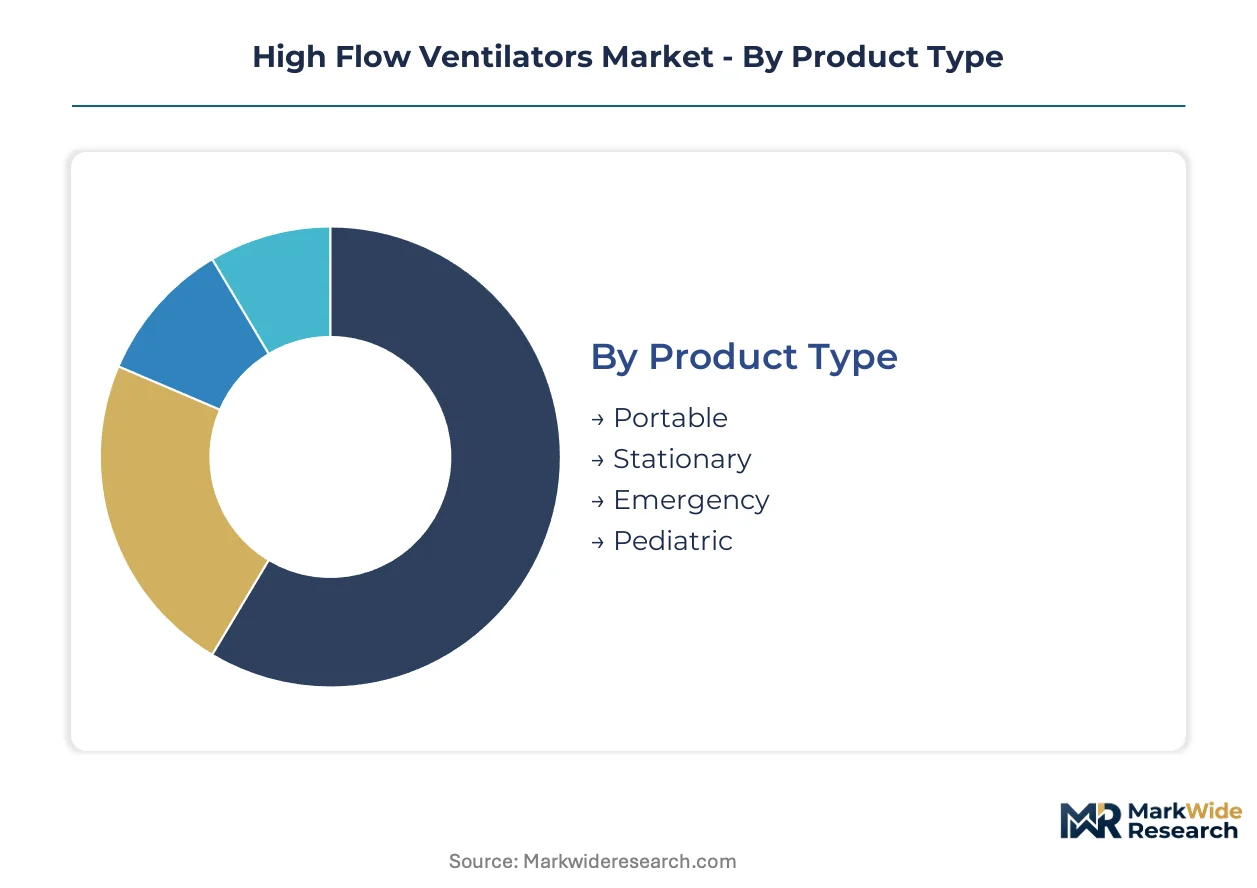
Segmentation in the high flow ventilators market reveals divergent procurement cycles and margin structures across device configurations. Product type determines replacement frequency, while end-user concentration shapes service contract economics and consumables bundling strategies.
Product Type:
Replacement cycles stretch from emergency field units replaced every 3-4 years to stationary ICU platforms with 7-10 year lifespans, creating distinct revenue timing for manufacturers.
- Stationary:Fixed installations in intensive care units integrate heated humidification modules with embedded flow sensors for precise FiO2 control. Tertiary hospital systems in the United States and Germany anchor demand through multi-year consumables contracts that virtualize hardware margins into recurring revenue pools.
- Portable:Battery-powered configurations designed for inter-hospital transfer and emergency transport operate at reduced flow ranges with modular humidification attachments. Demand concentrates in emergency medical services networks across China and the United States as pre-hospital respiratory protocols expand.
- Emergency:Ruggedized field units prioritize rapid deployment and simplified interfaces for paramedic operation.
- Pediatric:Smaller nasal interfaces and calibrated flow ranges address neonatal and infant respiratory support requirements.
Stationary systems anchor the volume base while portable configurations gain share at the steepest rate.
End User:
Customer concentration varies from consolidated hospital procurement committees to fragmented home care distributors, reshaping pricing power and service bundling requirements.
- Hospitals:Tertiary care networks with dedicated biomedical engineering departments manage multi-vendor platform integrations and negotiate predictive maintenance agreements. ICU expansion across the United States, Germany, and China concentrates stationary unit placements in academic medical centers with respiratory research capabilities.
- Home Care:Transition-to-home protocols for chronic respiratory patients require portable configurations with cloud-connected monitoring platforms. Reimbursement recalibration between acute and ambulatory coverage criteria creates demand volatility that manufacturers address through remote oversight subscriptions.
- Emergency Services:Municipal and private ambulance operators prioritize device durability and rapid warmup times for field deployment.
- Long-term Care Facilities:Skilled nursing operators seek simplified interfaces with reduced training requirements for nursing staff.
Hospitals dominate capital expenditure allocation while home care represents the most expansionary customer segment.
Technology:
Technology platforms differentiate through humidification precision, pressure delivery mechanisms, and regulatory clearance pathways that determine market access speed.
- Heated Humidity:Integrated modules with automated temperature regulation and embedded sensors enable non-invasive alternatives to mechanical ventilation in acute hypoxemic respiratory failure. FDA 510(k) clearance pathways with escalating clinical data requirements favor established manufacturers with regulatory infrastructure investments.
- Non-Invasive:Nasal prong delivery systems operating at 8-80 L/min flow rates reduce intubation rates in pre-intubation protocols across tertiary hospitals. EU MDR notified body oversight and post-market surveillance obligations create structural barriers that reward manufacturers with quality management systems.
- High-Pressure:Conventional turbine-driven systems deliver elevated flow rates without integrated humidification for specific clinical scenarios.
- Low-Pressure:Reduced-pressure alternatives address patient comfort concerns in extended therapy applications.
Heated humidity systems anchor installed base value while non-invasive platforms expand most quickly across pre-intubation protocols.
Application:
Clinical use cases span acute intervention to chronic management, with therapy duration and reimbursement pathways determining device specification requirements.
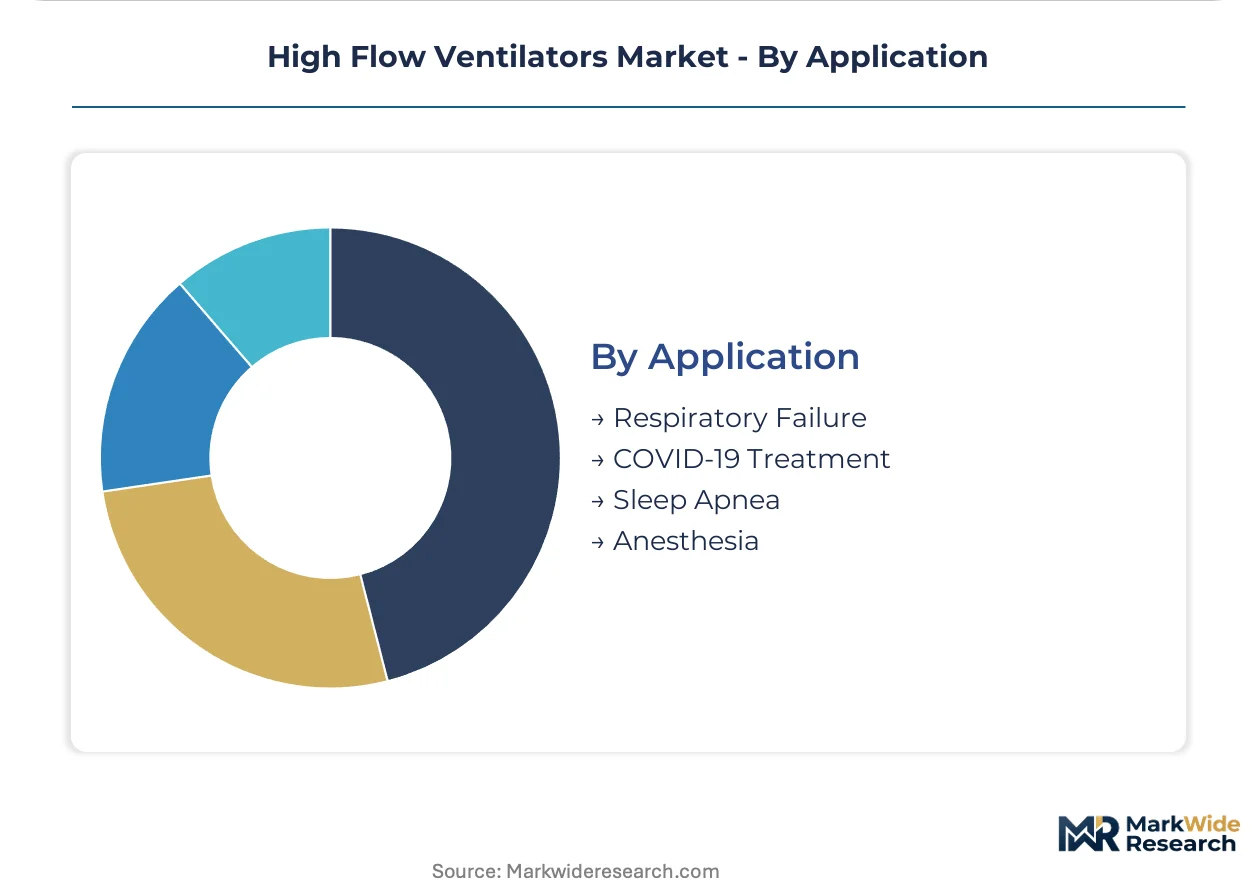
- Respiratory Failure:Acute hypoxemic presentations in intensive care settings demand precise FiO2 control and rapid flow adjustment capabilities. Clinical validation requirements for novel interfaces concentrate randomized controlled trial execution in academic medical centers with specialized respiratory research networks.
- COVID-19 Treatment:Pandemic-era protocol adoption established high flow therapy as standard of care for moderate respiratory distress, sustaining post-acute demand for surge capacity planning.
- Sleep Apnea:Chronic nocturnal applications prioritize patient comfort and noise reduction for home compliance.
- Anesthesia:Perioperative respiratory support requires integration with surgical workflow and anesthesia delivery systems.
Respiratory failure applications anchor clinical validation investments while COVID-19 treatment protocols established the category's acute care legitimacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement environments. Hospital systems in Germany and the United States absorb premium pricing for bundled service contracts, while municipal purchasers in emerging markets prioritize capital expenditure minimization over total cost of ownership.
United States
Academic medical centers in Boston and Houston drive stationary unit placements through NIH-funded respiratory research networks. FDA 510(k) pathway escalation for novel high flow interfaces concentrates clinical validation investments in institutions with established pulmonary trial infrastructure. The Cleveland Clinic and Mayo Clinic anchor multi-hospital procurement consortia negotiating predictive maintenance agreements.
Germany
Tertiary care expansion in Bavaria and North Rhine-Westphalia sustains demand for heated humidification systems with embedded flow sensors. EU MDR notified body oversight through TÜV SÜD and BSI creates regulatory infrastructure advantages for established manufacturers. The Berlin-Brandenburg medical technology cluster concentrates post-market surveillance service providers.
China
Critical care bed construction in Shanghai and Guangzhou accelerates portable configuration demand for inter-hospital transfer protocols. NMPA medical device registration requirements for Class III respiratory support equipment extend approval timelines for novel interfaces. The Yangtze River Delta medical device manufacturing base supplies heated breathing circuits to domestic hospital procurement networks.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas expand home care transition protocols requiring cloud-connected monitoring platforms. PMDA quality management system inspections for respiratory devices enforce documentation standards that favor manufacturers with established Japanese subsidiary operations. The Kansai region biomedical engineering cluster supports remote oversight subscription service development.
United Kingdom
NHS England integrated care systems in London and Manchester recalibrate reimbursement criteria between acute and ambulatory respiratory support. MHRA post-Brexit medical device regulations maintain alignment with EU MDR technical documentation requirements while streamlining UK-specific market access pathways. The Cambridge-Oxford-London life sciences corridor concentrates digital health platform developers integrating ventilation data with electronic health records.
High Flow Ventilators Market Competitive Landscape
Integrated platform specialists and component-focused manufacturers split the market along service-bundling versus hardware-differentiation axes. The vendor base concentrates around respiratory device incumbents with captive humidification technology and regulatory infrastructure investments. Three archetypes dominate: comprehensive critical care platform providers, dedicated high flow technology specialists, and diversified medical device conglomerates with respiratory divisions. Competitive moves center on multi-year consumables contract capture and predictive maintenance service unbundling.
Among diversified medical technology conglomerates, Getinge AB and Medtronic PLC exemplify platform breadth strategies spanning surgical workflows through critical care. Fisher & Paykel Healthcare occupies a distinct position as a dedicated respiratory and acute care specialist with integrated humidification technology origins. These three anchors demonstrate how regulatory infrastructure scale and recurring revenue model maturity determine positioning in procurement environments shifting toward total cost of ownership evaluation.
| Leading Market Players |
|---|
| Getinge AB |
| Hamilton Medical |
| Koninklijke Philips NV |
| Medtronic PLC |
| ResMed |
| VYAIRE |
| Fisher & Paykel Healthcare |
| Vapotherm |
| Drägerwerk AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Single-source dependency on heated breathing circuit suppliers from the Yangtze River Delta determines both pricing tier spreads and supply chain shape, forcing procurement committees to accept bundled consumables contracts or face device downtime risk.
Pricing Analysis
Consumables bundling drives lifetime value, with heated humidification circuits and nasal interfaces generating recurring revenue pools that exceed hardware margins by year three. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with predictive maintenance agreements from municipal purchasers prioritizing capital expenditure minimization. Pricing pressure stems from EU MDR compliance costs transferring to end-user contracts. Emergency medical services networks exhibit highest price sensitivity due to municipal budget constraints.
Supply Chain Analysis
Medical-grade polymers and precision flow sensors feed from concentrated manufacturing bases in China, Germany, and the United States. Heated breathing circuits draw from silicone suppliers in Guangdong and sensor fabricators in Bavaria. Single-source vulnerability concentrates in nasal interface molding operations. Distribution runs through group purchasing organizations and hospital procurement consortia with multi-year contract leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High flow ventilator adoption sits in early-cycle expansion as pre-intubation protocols displace conventional oxygen delivery across tertiary hospitals, with heated humidification technology penetration still below saturation in emergency transport and home care settings.
For Market Incumbents: Insulate installed base value through captive supply of heated breathing circuits and predictive maintenance contracts that transfer uptime risk from hospital biomedical engineering departments. Deepen regulatory infrastructure investments across FDA 510(k) and EU MDR notified body relationships to extend structural barriers against emerging entrants lacking clinical validation capacity.
For New Entrants and Emerging Players: China's emergency medical services networks offer the most penetrable white-space target, with inter-hospital transfer protocols expanding faster than domestic manufacturer service coverage. Target cloud-connected portable configurations with simplified interfaces for paramedic operation, leveraging remote monitoring subscriptions to bypass capital expenditure procurement friction.
For Investors and Strategic Acquirers: Regional consumables specialists with heated humidification circuit manufacturing and established hospital GPO contracts present acquisition targets with immediate revenue integration potential. Long-term viability hinges on recurring revenue model maturity rather than hardware differentiation alone. Watch for NHS England reimbursement recalibration between acute and ambulatory settings as inflection indicator for home care segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clinical Data Investment | Escalating clearance requirements for novel high flow interfaces favor established manufacturers with pulmonary trial infrastructure. |
| EU MDR Notified Body Expansion | Multi-member state relationships sustain market access as post-market surveillance obligations restructure competitive barriers. |
| Hospital System Partnership | Multi-year consumables contracts with Cleveland Clinic and Mayo Clinic procurement consortia virtualize hardware margins. |
| Software Companion Development | Cloud-connected platforms integrating ventilation data with electronic health records enable predictive maintenance revenue streams. |
| Reimbursement Strategy | Payor recalibration between acute and ambulatory coverage criteria determines portable configuration demand volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Interviews with respiratory therapists, ICU directors, biomedical engineers, and GPO contracts managers anchor demand-side validation. Supply-side perspectives draw from regulatory affairs leads at device manufacturers and heated humidification component suppliers. Bottom-up unit placement estimates triangulate against top-down critical care bed expansion data across the United States, Germany, and China.
Forecast inputs span stationary, portable, emergency, and pediatric product configurations alongside heated humidity and non-invasive technology platforms. End-user segmentation incorporates hospitals, home care, emergency services, and long-term care facilities with divergent procurement cycles. CAGRs derive from installed base replacement timing and consumables attachment rate modeling. Respiratory failure and COVID-19 treatment application demand, plus NMPA and PMDA registration pathway timelines, inform regional trajectory differentiation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medical technology conglomerates into bundled service contracts would shift outcomes. Regulatory timeline delays at FDA or notified bodies, plus reimbursement recalibration at NHS England or CMS, present revision risks. Quarterly review of hospital capital expenditure announcements and GPO contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Light Therapy Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Baby Warmer Devices Market