
 Australia Drug Delivery Devices Market | 2026-2036
Australia Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Drug Delivery Devices Market Outlook
Hospital procurement channels in Australia are rewriting how drug delivery devices reach end users, with group purchasing organisations consolidating contract awards across state health systems. CSL Limited leverages its domestic manufacturing footprint to sustain preferential supply terms with public hospital networks. Johnson & Johnson competes through specialized catheter and infusion portfolios tailored to Australian clinical protocols. Novartis AG anchors its position via oncology and respiratory device distribution partnerships with major tertiary centres.
Drug delivery devices are engineered systems designed to administer therapeutic agents through precise dosing mechanisms, incorporating specifications such as flow-rate accuracy within five percent variance and biocompatible materials meeting ISO 10993 standards; their primary purpose is to ensure patient safety, therapeutic efficacy, and compliance across acute and chronic care settings. Autoinjectors and smart delivery systems command premium positioning due to patient self-administration trends and connected-health integration requirements. Infusion pumps represent a mature segment with replacement-driven demand, while needle-free injectors attract development investment focused on paediatric and needle-phobic populations. Wearable devices within the technology segment are expanding fastest, though margin pools remain concentrated in validated hospital-grade systems with software integration capabilities.
TGA medical device regulations and the Therapeutic Goods (Medical Devices) Standard shape product registration timelines and clinical evidence requirements for market entry in Australia. ISO 13485 quality management certification and MDSAP recognition further filter supplier eligibility for public tenders. Stakeholders must monitor evolving software-as-a-medical-device classifications and cybersecurity guidance, as connected delivery platforms attract heightened regulatory scrutiny without harmonised international pathways.
Market Dynamics
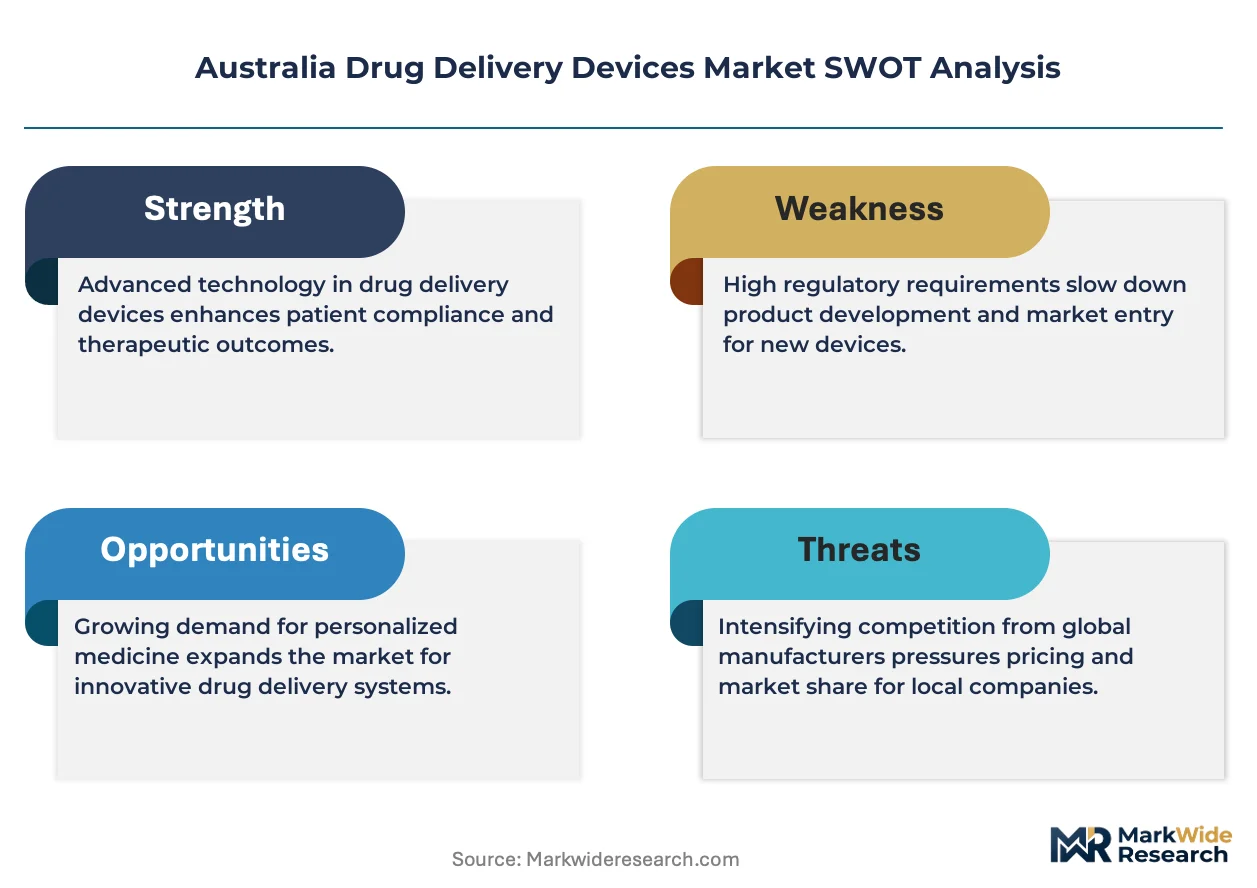
Hospital procurement consolidation across New South Wales and Victoria is compressing vendor margins while elevating compliance requirements for TGA registration and ISO 13485 certification as gatekeeping mechanisms for contract eligibility.
Growth Catalysts
- Homecare expansion:State health systems in Queensland and Western Australia are reimbursing self-administration devices for chronic disease management, expanding addressable volume beyond acute settings.
- TGA software-as-medical-device guidance:Clarified pathways for connected delivery platforms are accelerating regulatory submissions for Bluetooth-enabled autoinjectors and dose-tracking applications.
- Biologic therapy pipelines:Oncology and immunology drug developers require precision delivery systems with cold-chain compatibility, pulling demand for validated infusion hardware into Australian hospital networks.
Market Restraints
- Polymer feedstock volatility:Medical-grade polycarbonate and cyclic olefin polymer pricing fluctuates with petrochemical input costs, squeezing moulded component margins for disposable device manufacturers.
- Single-source sensor dependency:Flow-rate sensors and pressure transducers concentrate among German and Japanese suppliers, exposing Australian assemblers to extended lead times and currency risk.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitisation studies face capacity constraints at accredited Australian laboratories, extending product validation timelines.
Strategic Opportunities
- Tasmanian manufacturing incentives:Federal and state grants for medical technology production are attracting device assembly investment with lower labour cost structures than mainland centres.
- Paediatric needle-free delivery:Vaccination programmes and growth hormone therapies create unmet need for jet injector systems calibrated to infant and adolescent physiology.
- Remote patient monitoring integration:Convergence of drug delivery hardware with telehealth platforms enables adherence tracking and real-time dose adjustment for rural and regional patients.
Industry Challenges
- Embedded software engineering scarcity:Firmware development for connected devices competes for talent against broader medtech and automotive sectors, delaying connected-health product roadmaps.
- Legacy hospital IT interoperability:Integration of smart delivery systems with existing electronic medical record architectures requires custom middleware development, complicating deployment at tertiary centres.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Drug Delivery Devices Market |
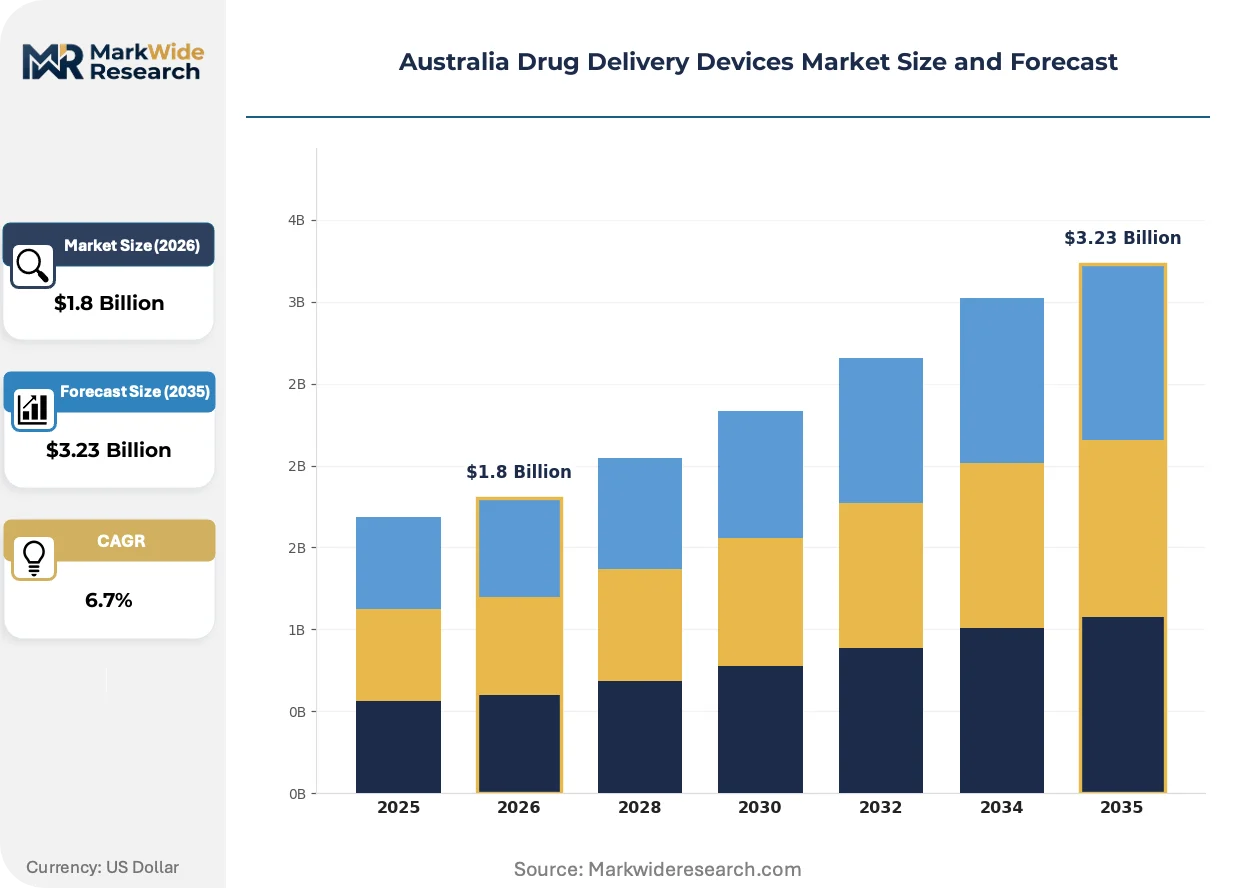
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Needle-Free Injectors, Infusion Pumps, Inhalers, Autoinjectors Administration Route: Oral, Subcutaneous, Intravenous, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Smart Delivery Systems, Wearable Devices, Microchip Implants, Nanotechnology |
| Companies Covered | CSL Limited, Johnson & Johnson, Novartis AG, Terumo, Sanofi, GlaxoSmithKline Plc, Novo Nordisk A/S, Medtronic, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Drug Delivery Devices Market Strategic Shifts
Connected-health architectures are redefining device value propositions across Australian healthcare, with data capture and interoperability capabilities now as critical as mechanical dosing precision in procurement evaluations.
Smart autoinjector platforms incorporating Bluetooth Low Energy and near-field communication are digitizing patient adherence monitoring for biologic therapies. Rheumatology and gastroenterology clinics in Melbourne and Sydney are piloting dose-verification systems that transmit injection timestamps to specialist dashboards. This connectivity layer is digitizing the traditional patient-reported outcome model, compressing reliance on manual diary entries and enabling proactive intervention for missed doses.
TGA guidance on cybersecurity for connected medical devices, aligned with FDA premarket expectations, is mandating threat-risk assessments and software bill of materials documentation for network-enabled delivery systems. Manufacturers must demonstrate penetration testing and vulnerability management protocols before market authorisation. Implantable and infusion pump categories face the steepest evidentiary requirements, with several sponsors extending registration timelines to accommodate security validation.
Group purchasing organisations in Victoria and New South Wales are consolidating tender evaluations around total cost of ownership metrics rather than unit price alone. Public hospital networks now weight service response times, training provision, and spare parts availability alongside device acquisition cost. This recalibration favours suppliers with domestic technical support infrastructure, disadvantaging pure import distributors without local engineering presence.
Australia Drug Delivery Devices Market Segmentation
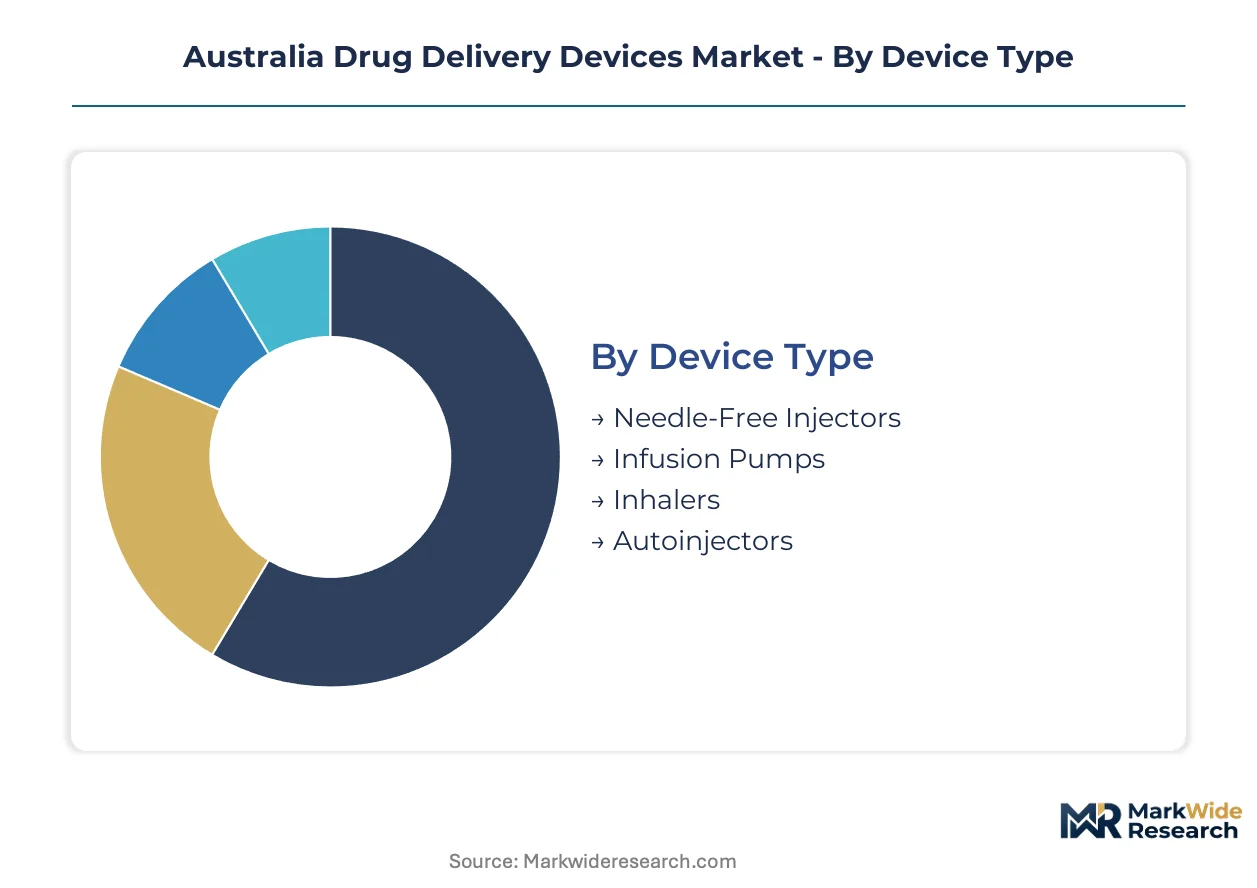
Device classification in the Australian market determines regulatory pathway, reimbursement eligibility, and procurement channel access. TGA registration requirements vary sharply across administration routes and connectivity levels, creating distinct competitive arenas for suppliers.
Device Type:
Use-case spectrum spans acute hospital infusion through chronic self-administration, with each device category commanding different technical specifications and margin structures.
- Autoinjectors:Spring-loaded or gas-powered systems delivering fixed-dose biologics through subcutaneous injection. Demand concentrates in rheumatology and gastroenterology clinics across New South Wales and Victoria, driven by TGA-cleared Bluetooth-enabled adherence tracking for specialist oversight of patient self-administration.
- Infusion Pumps:Programmable electromechanical systems controlling flow-rate accuracy within five percent variance for parenteral therapy delivery. Replacement cycles dominate Victorian and Queensland hospital procurement, constrained by polymer feedstock volatility squeezing disposable component margins.
- Needle-Free Injectors:Jet injection systems using high-pressure fluid streams to penetrate skin without hypodermic needles. Paediatric vaccination programmes and needle-phobic populations in Western Australia generate development investment.
- Inhalers:Pressurised metered-dose or dry-powder devices for respiratory drug deposition. Community pharmacy distribution channels in urban centres sustain volume.
The dominant share belongs to infusion pumps, while autoinjectors are closing the gap fastest.
Administration Route:
Route selection dictates device complexity, sterility requirements, and patient training intensity across Australian care settings.
- Intravenous:Direct vascular access requiring aseptic technique and flow-rate precision for hospital-grade infusion systems. Tertiary centres in Sydney and Melbourne drive validated hardware procurement with cold-chain compatibility for oncology biologics.
- Subcutaneous:Tissue-layer deposition suitable for patient self-administration via autoinjector or prefilled syringe. Homecare reimbursement expansion in Queensland and Western Australia pulls volume beyond acute settings.
- Inhalation:Pulmonary deposition through aerosol or powder devices for respiratory therapy. Specialist respiratory clinics anchor demand.
- Oral:Enteric delivery via modified-release formulations or active implantable pumps for gastrointestinal targeting. Niche applications in gastroenterology.
Intravenous administration holds the largest installed base, though subcutaneous delivery is expanding most quickly into homecare channels.
End User:
Customer type determines procurement authority, technical support expectations, and software integration requirements for device suppliers.
- Hospitals:Public and private acute facilities with group purchasing organisation consolidation across state health systems. New South Wales and Victorian networks compress vendor margins while elevating ISO 13485 certification and domestic technical support infrastructure as contract gatekeepers.
- Homecare:Patient-directed administration with remote monitoring integration for chronic disease management. State reimbursement programmes in Queensland and Western Australia are accelerating addressable volume.
- Clinics:Specialist outpatient facilities requiring dose-verification systems and training provision. Rheumatology and endocrinology practices in metropolitan centres pilot connected adherence platforms.
- Pharmacies:Community retail channels for inhaler and autoinjector dispensing with patient counselling obligations.
Hospitals retain the dominant procurement volume, while homecare is gaining share fastest through reimbursement expansion.
Technology:
Technology tier separates validated mechanical systems from connected-health platforms with software integration and data capture capabilities.
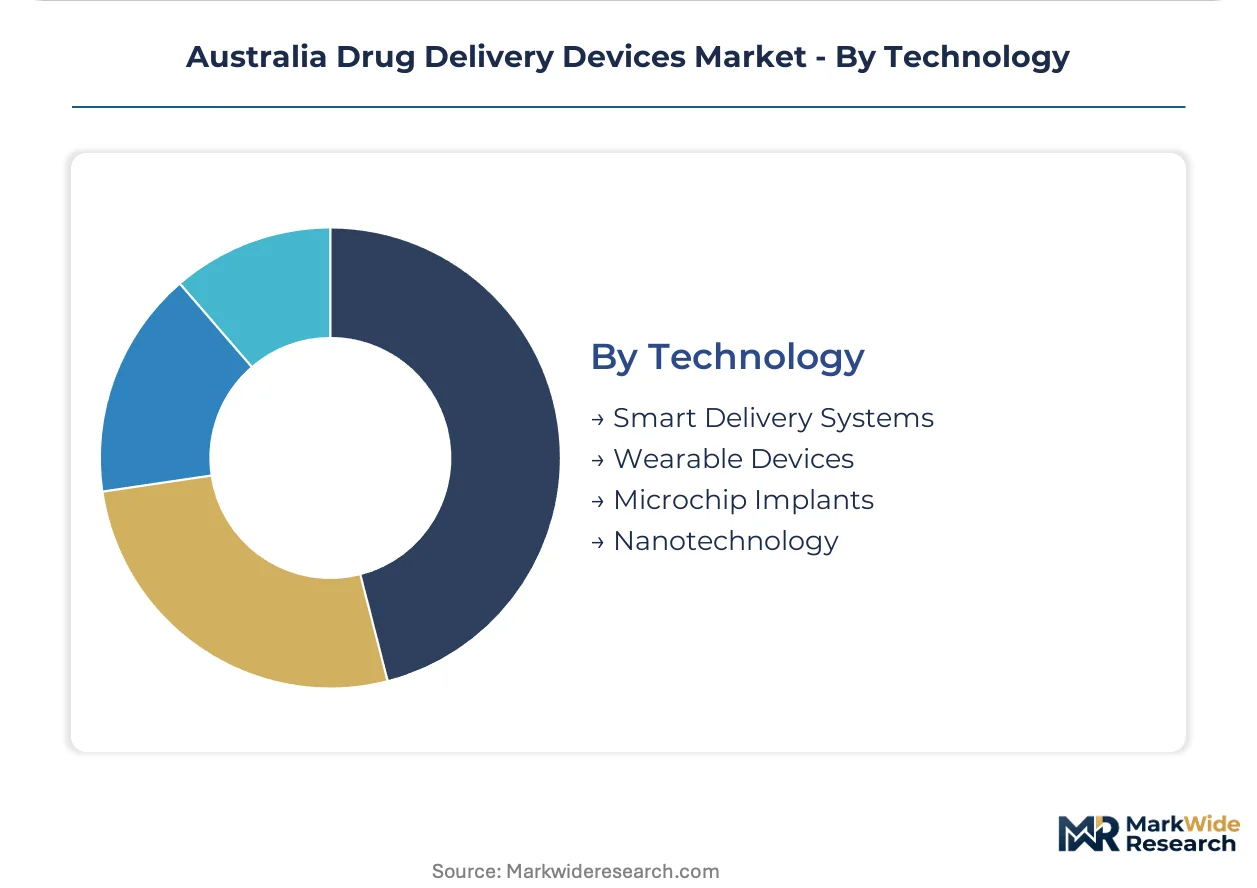
- Smart Delivery Systems:Network-enabled devices with Bluetooth Low Energy, near-field communication, and dose-tracking applications. TGA software-as-medical-device guidance and cybersecurity mandates are extending registration timelines for sponsors of connected autoinjectors and infusion pumps.
- Wearable Devices:Body-adhered or garment-integrated delivery systems for continuous or on-demand therapy. Patch pumps and wearable injectors are expanding fastest, though margin pools concentrate in hospital-grade systems with software integration capabilities.
- Nanotechnology:Particle-scale drug carriers and targeted delivery mechanisms for enhanced bioavailability. Research-phase applications in oncology.
- Microchip Implants:Programmable implantable reservoirs for long-term controlled release. Experimental status in Australian regulatory landscape.
Smart delivery systems command the premium positioning, while wearable devices are climbing the fastest on patient self-administration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Melbourne and Sydney's Port Botany container terminals underpin Australia's medical device import infrastructure, handling precision-manufactured components from German sensor suppliers and Japanese polymer feedstock sources that feed domestic assembly operations.
New South Wales
Sydney's tertiary hospital networks drive procurement volumes for validated infusion systems with cold-chain compatibility. TGA registration requirements and ISO 13485 certification filter supplier eligibility for state health system tenders. The Westmead Health Precinct and Royal North Shore Hospital cluster anchor specialist oncology and rheumatology device demand.
Victoria
Melbourne's biomedical manufacturing corridor concentrates CSL Limited's domestic production footprint and medical technology R&D facilities. The Therapeutic Goods (Medical Devices) Standard shapes local product validation timelines. The Parkville medical research precinct and Monash Health network pilot connected autoinjector adherence platforms for biologic therapy monitoring.
Queensland
State reimbursement programmes for self-administration devices expand homecare addressable volume beyond acute settings. The Queensland Health procurement framework prioritizes remote patient monitoring integration for chronic disease management. The Brisbane Metro North Hospital and Health Service and Gold Coast University Hospital anchor specialist clinic demand.
Western Australia
Paediatric vaccination programmes and needle-phobic population needs generate development investment for jet injector systems. The state health system's rural and regional patient distribution drives telehealth platform convergence with drug delivery hardware. Perth's Fiona Stanley Hospital and Sir Charles Gairdner Hospital networks concentrate procurement authority.
Tasmania
Federal and state medical technology production grants attract device assembly investment with lower labour cost structures than mainland centres. The Tasmanian Government's advanced manufacturing incentives target precision polymer component moulding operations. Hobart's Royal Hobart Hospital anchors the island's specialist device demand.
Australia Drug Delivery Devices Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying sensors, polymers, and precision-machined parts to finished device assemblers. The Australian market presents a consolidated structure where multinational healthcare conglomerates with TGA-registered portfolios dominate hospital procurement channels. Three archetypes define competitive positioning: domestic manufacturing champions leveraging local production for preferential supply terms; global diversified medtech conglomerates competing through specialized catheter and infusion portfolios; and biopharmaceutical-device convergence players anchoring distribution through oncology and respiratory therapy partnerships. Dominant competitive moves include geographic expansion through state health system tender participation and technology licensing for connected-health platform capabilities.
Among the named participants, CSL Limited exemplifies the domestic manufacturing champion archetype through its Australian production footprint. Johnson & Johnson occupies a position within the global diversified medtech tier. Novartis AG represents the biopharmaceutical-device convergence model, anchoring market presence through therapy-specific distribution partnerships with major tertiary centres.
| Leading Market Players |
|---|
| CSL Limited |
| Johnson & Johnson |
| Novartis AG |
| Terumo |
| Sanofi |
| GlaxoSmithKline Plc |
| Novo Nordisk A/S |
| Medtronic |
| Becton, Dickinson and Company |
| Others |
Value Chain & Pricing Dynamics
Single-source sensor dependency on German and Japanese flow-rate component suppliers compresses both margin tier spreads and supply chain resilience across Australian device assembly operations. This concentration forces domestic manufacturers to absorb currency volatility while group purchasing organisations exploit volume leverage to compress premium-tier pricing.
Pricing Analysis
Volume-discount tiering structures dominate public hospital procurement through consolidated state health system tenders. Pricing stratifies across TGA-registered premium systems, ISO 13485-certified standard devices, and economy-tier disposable components. Cost compression in the economy tier intensifies because polymer feedstock volatility squeezes moulded component margins. Homecare channels exhibit the highest price sensitivity due to patient out-of-pocket exposure, while tertiary oncology centres demonstrate the lowest sensitivity given cold-chain compatibility requirements for biologic therapies.
Supply Chain Analysis
Export-control restrictions on precision sensor technology from Germany and Japan limit alternative sourcing for flow-rate transducers and pressure monitoring components. Australian assembly operations draw from German sensor suppliers, Japanese polymer feedstock sources, and domestic moulding facilities in Victoria and Tasmania. Single-source vulnerability concentrates in specialty electromechanical components, exposing manufacturers to extended lead times. Distribution runs through Port Melbourne and Port Botany container terminals feeding state health system warehouses and hospital receiving docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA regulatory entrenchment creates formidable defensive moats for established suppliers, as ISO 13485 certification and MDSAP recognition function as non-negotiable gatekeepers for public tender eligibility. Switching costs escalate for hospital networks replacing validated infusion systems with embedded electronic medical record integrations.
For Market Incumbents: Entrench market position through backward integration into precision polymer component moulding and captive sensor calibration capabilities. CSL Limited's domestic manufacturing footprint exemplifies how local production infrastructure secures preferential supply terms with New South Wales and Victorian health networks. Threats from emerging connected-health platforms require accelerated firmware development investment to maintain interoperability leadership with hospital IT architectures. For New Entrants and Emerging Players: Pursue paediatric needle-free delivery systems and remote patient monitoring integration as white-space targets with lower incumbent saturation. Western Australia's rural patient distribution and Queensland's homecare reimbursement expansion represent the most penetrable geographic channels. A go-to-market angle anchored in telehealth platform partnerships with regional health services bypasses consolidated metropolitan hospital procurement barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with software-as-medical-device capabilities and established TGA registration portfolios. Acquisition targets should display ISO 13485 certification, domestic technical support infrastructure, and Bluetooth-enabled adherence tracking development pipelines. The signal to watch is TGA cybersecurity guidance evolution, as escalating evidentiary requirements for connected devices will accelerate sponsor consolidation among well-capitalised players.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-Medical-Device Registration | Accelerates market entry for Bluetooth-enabled autoinjectors through clarified regulatory pathways. |
| Hospital System Partnership | Secures preferential supply terms with New South Wales and Victorian group purchasing organisations. |
| Backward Integration into Polymer Moulding | Reduces feedstock cost exposure through Tasmanian manufacturing incentive utilisation. |
| Software Companion Development | Enables dose-verification system integration with Melbourne and Sydney specialist clinic dashboards. |
| Reimbursement Strategy | Unlocks Queensland and Western Australia homecare volume through state health programme alignment. |
Study Parameters
The analysis maps autoinjector platforms, infusion pump systems, needle-free injectors, and connected adherence technologies, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and TGA regulatory affairs leads. Primary interview intelligence combined with secondary validation from TGA registration databases, state health system tender records, ISO certification registries, and hospital procurement disclosures. Bottom-up device shipment estimates and top-down healthcare expenditure triangulation anchored market sizing across the projection horizon.
Assumption sets held regulatory pathway timelines and reimbursement policy frameworks fixed while varying polymer feedstock cost trajectories and sensor supply lead times. Segmentation dimensions modeled include device type, administration route, end-user setting, and connectivity tier. CAGRs derived from installed base replacement cycles, biologic therapy pipeline expansion, and homecare reimbursement growth rates. Forecast inputs incorporated TGA software-as-medical-device submission volumes and state health system capital expenditure plans.
Sensitivities concentrate around TGA cybersecurity guidance evolution, German and Japanese sensor export control adjustments, and Queensland homecare reimbursement policy continuity. Forecasts reflect documented assumptions regarding regulatory pathway stability and supply chain lead time normalisation. Material shifts in TGA software classification requirements or major sensor supplier capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market