
 China Pharmaceutical Warehousing Market | 2026-2036
China Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
China Pharmaceutical Warehousing Market Insights
Chinese third-party logistics providers is restructuring pharmaceutical storage capacity to meet NMPA's revised Good Supply Practice standards. Sinopharm Logistics anchors national distribution through its state-backed cold chain network spanning provincial hubs. JD Logistics leverages autonomous warehouse robotics to sustain same-day delivery promises for temperature-sensitive biologics. SF Express differentiates through dedicated pharmaceutical air freight corridors linking manufacturing clusters in Jiangsu to hospital systems in Guangdong.
China pharmaceutical warehousing encompasses climate-controlled facilities, inventory management systems, and value-added services designed to maintain product integrity across the pharmaceutical supply chain. These operations rely on validated temperature mapping, real-time monitoring infrastructure, and segregation protocols to prevent cross-contamination between ambient, cold chain, and controlled room temperature zones. Cold chain storage leads investment allocation as biologics and vaccines expand their share of pharmaceutical throughput. Ambient and climate-controlled segments retain volume dominance for generic oral solid dosages distributed through wholesale and retail pharmacy channels. Managed services capture expanding margin pools as manufacturers outsource compliance-heavy inventory management to specialized operators.
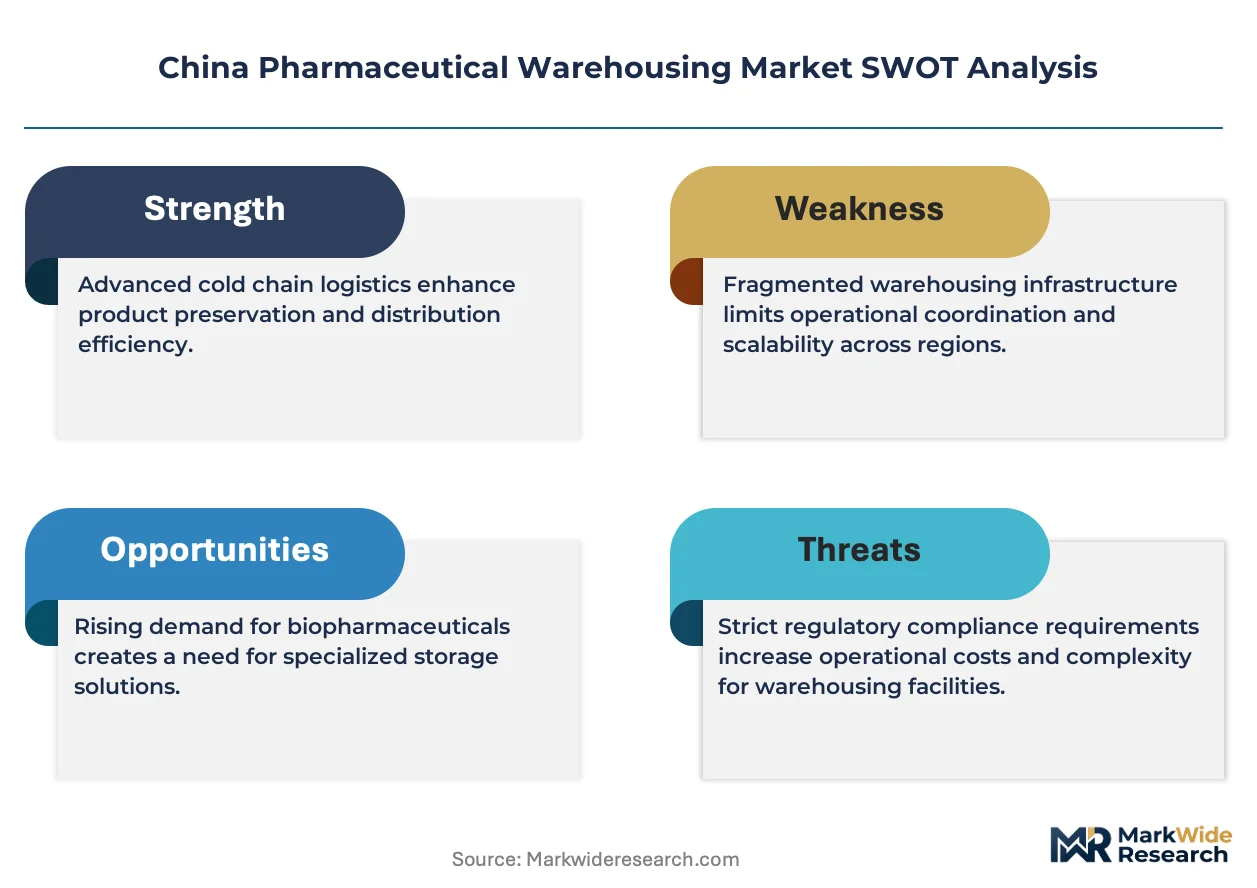
NMPA's Good Supply Practice enforcement and the National Healthcare Security Administration's centralized procurement mandates reshape facility requirements and distribution economics for pharmaceutical warehouses across China. Provincial drug regulators conduct unannounced inspections that determine facility licensing renewal, creating compliance-driven demand for qualified storage infrastructure. Stakeholders must weigh the capital intensity of dual-certified cold chain expansion against the revenue stability of long-term managed service contracts with state hospital consortia.
Market Dynamics
NMPA's Good Supply Practice enforcement is compressing facility licensing timelines and forcing wholesale consolidation across China's pharmaceutical distribution tier. State hospital procurement centralization is simultaneously reshaping volume concentration and service-level requirements for third-party warehouse operators.
Growth Catalysts
- Biologics throughput expansion:Vaccine and monoclonal antibody production clusters in Jiangsu and Zhejiang are demanding validated cold chain capacity at scale. Temperature-sensitive biopharmaceuticals now represent the fastest-growing throughput category.
- NMPA GSP facility certification:The regulator's unannounced inspection regime and license renewal protocols are disqualifying substandard ambient storage operators. Compliance-driven replacement demand is accelerating.
- Yangtze River Delta manufacturing concentration:Shanghai and surrounding provinces anchor domestic pharmaceutical production. Proximity requirements between manufacturing and certified warehousing are tightening.
Market Restraints
- Refrigeration energy cost volatility:Cold chain facilities face margin pressure from electricity price fluctuations and peak-demand surcharges. Dual-certified temperature zones compound energy intensity.
- Provincial licensing fragmentation:Subnational drug regulators maintain non-harmonized facility standards across China's 31 provincial-level jurisdictions. Multi-province operators face duplicated compliance burdens.
- Real estate constraints in tier-one cities:Land scarcity and zoning restrictions around Shanghai and Beijing limit greenfield cold chain development. Brownfield conversions carry contamination remediation risks.
Strategic Opportunities
- Western China pharmaceutical corridor development:Chengdu and Chongqing biotech manufacturing parks lack sufficient certified cold chain infrastructure. Early-mover warehouse positioning captures inland demand growth.
- Autonomous mobile robotics convergence:Integration of automated guided vehicles with warehouse management systems reduces labor dependency and picking error rates in high-SKU environments.
- Centralized procurement managed services:Hospital consortia under National Healthcare Security Administration mandates seek outsourced inventory management. Long-term service contracts offer revenue stability.
Industry Challenges
- Qualified validation engineer scarcity:NMPA's temperature mapping and equipment qualification requirements exceed available specialist labor supply. Certification bottlenecks delay facility commissioning.
- Legacy warehouse management system integration:State-owned pharmaceutical distributors operate on fragmented software platforms. API connectivity for real-time inventory visibility requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pharmaceutical Warehousing Market |
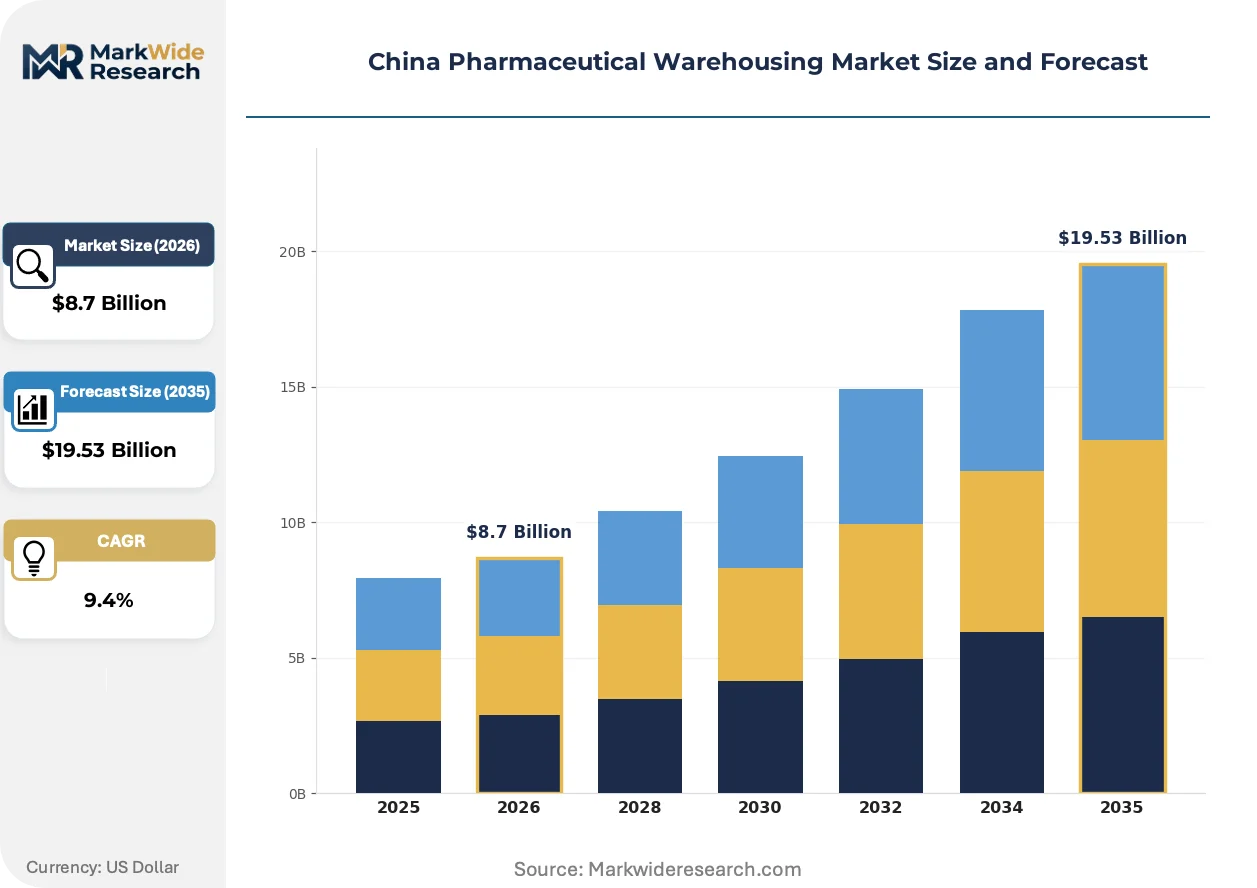
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biotechnology, Medical Devices, Diagnostics End User: Wholesalers, Distributors, Retail Pharmacies, Hospitals Storage Type: Cold Chain, Ambient, Controlled Room Temperature, Climate-Controlled Service Type: Managed Services, Transportation, Inventory Management, Value-Added Services |
| Companies Covered | DHL Supply Chain, Yunda Holding, Sinopharm Logistics, Nippon Express, DB Schenker, JD Logistics, Kerry Logistics, CJ Rokin Logistics, SF Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pharmaceutical Warehousing Market Trends and Innovations
Digital infrastructure and automation are compressing operational response times while regulatory digitization is tightening audit trails across China's pharmaceutical warehousing tier.
Modular cold chain units with plug-and-play refrigeration skids are modularizing facility deployment economics. Regional operators in secondary cities are adopting containerized temperature-controlled pods to bypass capital-intensive fixed-build construction. This architecture is modularizing market entry barriers for mid-scale third-party logistics providers.
NMPA's electronic drug traceability mandate requires serialization at the package level through the national drug regulatory information platform. Warehouse operators must deploy scanning infrastructure and data interchange protocols to maintain distribution eligibility. Cold chain facilities face the steepest compliance investment given biologics' higher regulatory scrutiny.
Direct-to-hospital distribution contracts are displacing traditional wholesale tier relationships. Manufacturers are contracting warehouse operators for last-mile delivery to state hospital procurement consortia. This pattern is most visible in Guangdong and Jiangsu provinces where centralized procurement volumes concentrate.
China Pharmaceutical Warehousing Market Segmentation
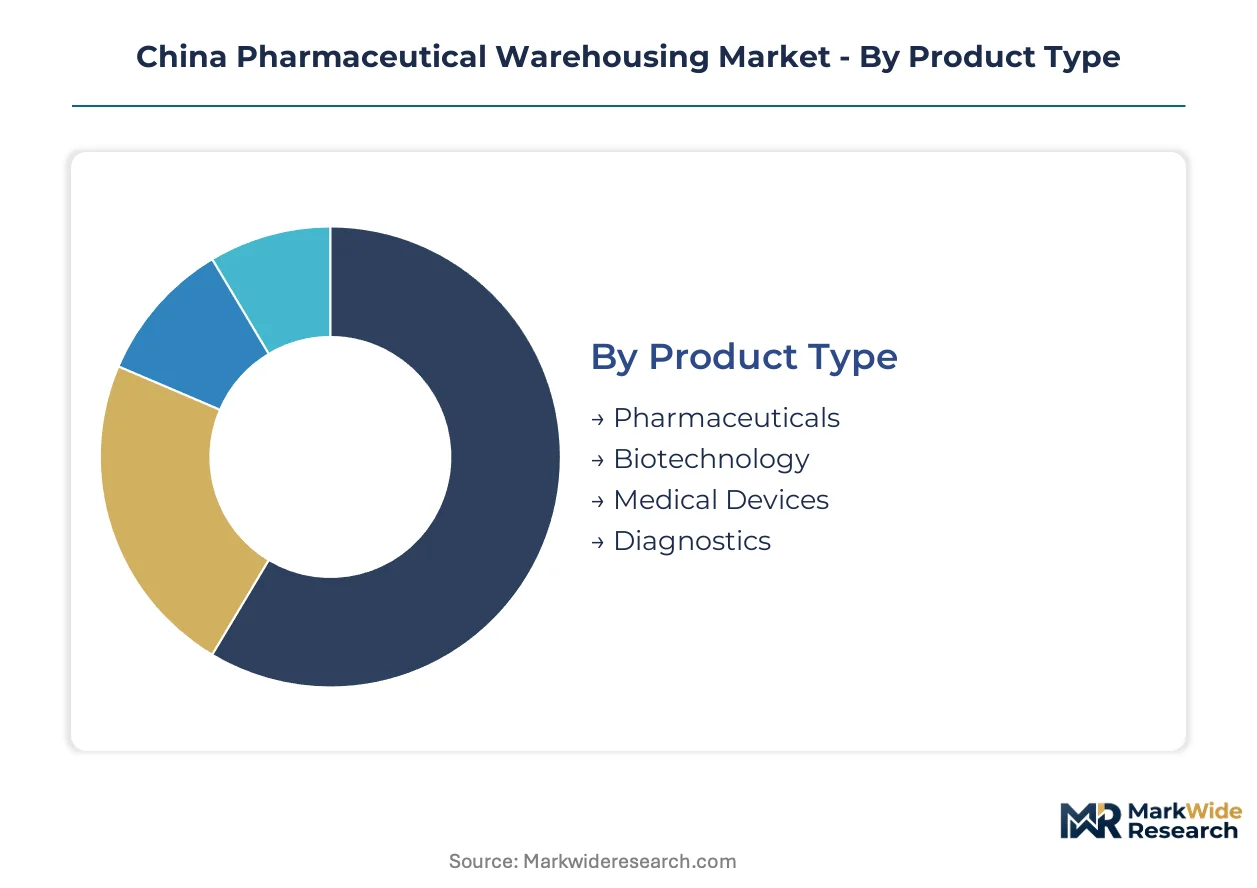
China's pharmaceutical warehousing market segments around temperature integrity requirements, regulatory certification tiers, and service complexity levels. Each dimension shapes capital deployment decisions and margin structures differently across the Yangtze River Delta manufacturing corridor and inland distribution networks.
Product Type:
Volume dominance sits with generic oral solid dosages, while premium margins concentrate in temperature-sensitive biologics requiring validated cold chain infrastructure.
- Pharmaceuticals:Oral solid dosages and small-molecule drugs dominate throughput tonnage across wholesale and retail channels. State hospital procurement consortia in Jiangsu and Zhejiang drive volume concentration through centralized tendering.
- Biotechnology:Monoclonal antibodies, vaccines, and cell therapies demand dual-certified cold chain storage with continuous temperature monitoring. NMPA's Good Supply Practice enforcement is disqualifying ambient-only facilities from handling these products, compressing qualified supplier pools.
- Medical Devices:Class II and III implantable devices require humidity-controlled environments with sterile handling protocols. Distribution concentrates through specialized third-party logistics providers with medical device licensing.
- Diagnostics:Reagent kits and testing consumables need stable temperature ranges to maintain assay reliability. Hospital laboratory networks in Guangdong and Shanghai anchor demand clusters.
Today's leader: Pharmaceuticals. Tomorrow's challenger: Biotechnology.
End User:
Procurement centralization is reshaping customer concentration, with state hospital consortia displacing fragmented wholesale relationships.
- Wholesalers:Traditional tier-one distributors face margin compression from National Healthcare Security Administration procurement mandates. Consolidation is accelerating as NMPA license renewals disqualify substandard operators.
- Distributors:Regional pharmaceutical distributors require multi-temperature zone facilities to serve mixed product portfolios. Western China corridors around Chengdu and Chongqing show fastest network expansion.
- Retail Pharmacies:Chain pharmacies demand frequent replenishment with same-day or next-day service levels. Urban density in Shanghai and Beijing supports micro-fulfillment center placement.
- Hospitals:State hospital procurement consortia under centralized procurement mandates seek direct distribution contracts with warehouse operators. Volume concentration is highest in Jiangsu and Guangdong provincial health systems.
Volume gravity centers on Hospitals. Margin expansion concentrates in Distributor captive contracts.
Storage Type:
Energy intensity and certification complexity create a three-tier cost structure across temperature zones.
- Cold Chain:Validated refrigeration infrastructure maintains 2-8°C for biologics and vaccines, with redundant backup systems and real-time temperature logging. Jiangsu manufacturing clusters drive fastest capacity expansion.
- Ambient:Standard warehouse environments handle temperature-stable oral solid dosages with basic humidity control. This segment retains volume dominance but faces price pressure from commoditized competition.
- Controlled Room Temperature:15-25°C zones with tight tolerances serve sensitive APIs and finished formulations. NMPA inspection protocols are tightening qualification requirements.
- Climate-Controlled:Humidity-managed environments protect moisture-sensitive products and diagnostic reagents. Seasonal variation in the Yangtze River Delta increases operational complexity.
Investment flows toward Cold Chain. Ambient storage faces structural margin compression.
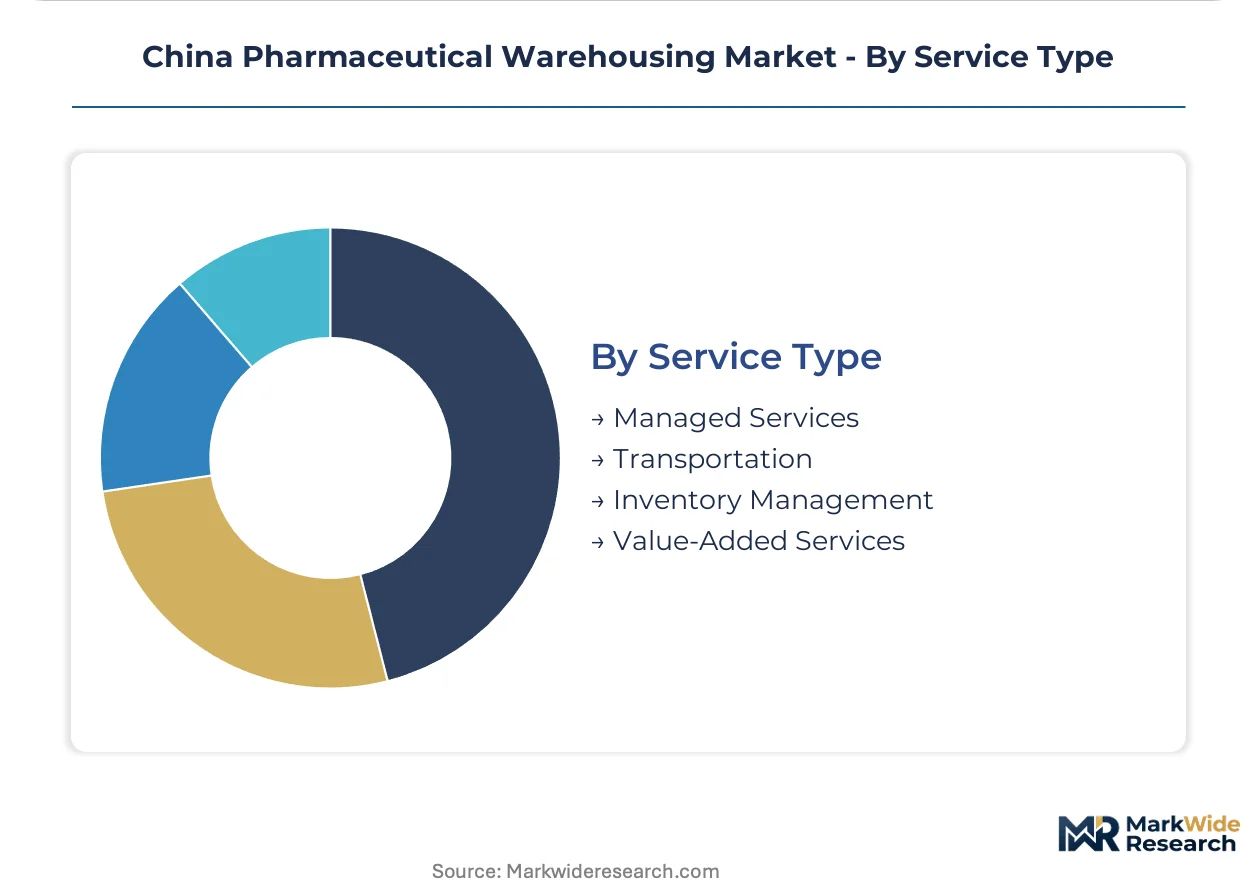
Service Type:
Outsourcing depth varies by customer sophistication, with compliance-heavy functions migrating fastest to specialized operators.
- Managed Services:Comprehensive inventory management, regulatory documentation, and NMPA compliance oversight contracted on multi-year terms. State hospital consortia favor this model for risk transfer.
- Transportation:Temperature-validated last-mile delivery with chain-of-custody documentation. JD Logistics and SF Express compete on autonomous vehicle deployment and pharmaceutical air freight corridors.
- Inventory Management:Warehouse management system integration with serialization tracking for NMPA's electronic drug traceability mandate. Real-time visibility requirements are upgrading legacy platforms.
- Value-Added Services:Labeling, kitting, and secondary packaging for clinical trial materials or specialty distribution. Higher margins attract third-party logistics providers seeking differentiation.
Revenue stability resides in Managed Services. Technology differentiation concentrates in Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing pharmaceutical warehousing investment across China as operators seek cost-of-compliance advantages outside saturated coastal markets. Tier-one cities impose stringent land-use restrictions and energy surcharges that inflate cold chain operating costs. Interior provinces offer subsidized industrial park development and streamlined NMPA facility licensing to attract certified capacity.
Yangtze River Delta
Shanghai anchors the densest concentration of biologics manufacturing and cold chain warehousing infrastructure in China. NMPA's unannounced inspection regime concentrates qualified storage capacity within Jiangsu and Zhejiang provinces to minimize transport time to production sites. Suzhou and Hangzhou biotech parks are driving fastest capacity expansion for monoclonal antibody storage.
Pearl River Delta
Guangdong's state hospital procurement consortia generate concentrated demand for direct-to-hospital distribution services. The province's drug regulator maintains harmonized standards with NMPA national protocols, reducing multi-jurisdiction compliance burdens for warehouse operators. Shenzhen and Guangzhou are attracting pharmaceutical air freight corridors linking to international manufacturing supply chains.
Beijing-Tianjin-Hebei
State-owned pharmaceutical distributors maintain legacy wholesale networks requiring ambient storage modernization to meet revised GSP standards. The municipal drug administration in Beijing enforces stricter temperature mapping protocols than national baselines. Tianjin port facilities are expanding climate-controlled bonded warehousing for imported specialty pharmaceuticals.
Sichuan-Chongqing
Chengdu and Chongqing biotech manufacturing parks lack sufficient certified cold chain infrastructure relative to production growth. Western China development programs offer tax incentives for pharmaceutical logistics investment in the region. Chongqing's pharmaceutical industrial zone is emerging as an inland hub for vaccine distribution to central and western provinces.
Shandong Peninsula
Qingdao and Yantai pharmaceutical manufacturing clusters require expanded controlled room temperature capacity for active pharmaceutical ingredient storage. Provincial regulators are accelerating GSP license timelines for facilities serving generic drug exporters. Jinan is developing regional distribution nodes connecting Shandong production to national hospital procurement networks.
China Pharmaceutical Warehousing Market Competitive Landscape
Established operators occupy the standard tier; emerging entrants pursue autonomous robotics and specialized biologics handling to differentiate. The market structure reflects state-backed consolidation alongside private logistics platform expansion. Three archetypes dominate: state-affiliated national distributors with captive hospital relationships, e-commerce logistics platforms leveraging automation density, and international third-party logistics providers with cross-border pharmaceutical expertise. Competitive moves center on cold chain capacity expansion in western corridors and multi-year managed service contracts with centralized procurement consortia.
Among state-backed national distributors, Sinopharm Logistics anchors the tier through provincial hub networks and direct government relationships. JD Logistics and SF Express occupy the technology-intensive segment, with the former deploying autonomous warehouse robotics and the latter constructing dedicated pharmaceutical air freight infrastructure. DHL Supply Chain represents the international third-party logistics archetype, bringing cross-border pharmaceutical compliance capabilities to multinational manufacturers operating in China.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Yunda Holding |
| Sinopharm Logistics |
| Nippon Express |
| DB Schenker |
| JD Logistics |
| Kerry Logistics |
| CJ Rokin Logistics |
| SF Express |
| Others |
Pricing and Supply Chain Analysis
Cold chain certification tiers bifurcate warehouse economics sharply, with NMPA-validated facilities commanding premium rates while ambient-only operators face commoditization. This divergence concentrates supply chain leverage among dual-certified operators in Jiangsu and Zhejiang, where proximity to biologics manufacturing clusters amplifies pricing power.
Pricing Analysis
Wholesaler margin compression under National Healthcare Security Administration procurement mandates is reshaping contract structures toward long-term managed service agreements. Price differentiation stems from NMPA GSP certification grade and geographic proximity to Yangtze River Delta manufacturing hubs. Cost compression in ambient storage intensifies because of electricity price volatility and peak-demand surcharges. State hospital consortia exhibit highest price sensitivity for standardized storage, while biotech manufacturers show lowest sensitivity for validated cold chain capacity.
Supply Chain Analysis
Refrigeration equipment supply rests on German and Japanese compressor manufacturers, with domestic Chinese panel fabrication expanding rapidly. Warehouse operators draw from imported precision cooling systems, domestic steel construction, and IoT sensor networks. Single-source vulnerability concentrates in ultra-low-temperature refrigeration components for cell therapy storage. Distribution runs through provincial hub-and-spoke networks anchored by state-affiliated national distributors with direct hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Western China pharmaceutical corridor development offers a geographic-arbitrage play, with Sichuan and Chongqing tax incentives and streamlined NMPA licensing offsetting coastal land scarcity costs.
For Market Incumbents: Acquire brownfield cold chain facilities in Chengdu and Chongqing to capture inland biologics demand growth. Consolidate substandard ambient storage competitors facing NMPA license disqualification. Defensive positioning requires backward integration into refrigeration equipment maintenance capabilities to reduce dependency on German and Japanese service networks.
For New Entrants and Emerging Players: The premium-to-economy price gap in controlled room temperature storage creates entry opportunity for mid-scale operators serving Shandong generic drug exporters. Target modular containerized cold chain deployment in secondary cities bypassing fixed-build capital intensity. Go-to-market leverage rests on NMPA compliance documentation outsourcing for regional distributors lacking in-house validation expertise.
For Investors and Strategic Acquirers: Consolidation pressure builds where provincial licensing fragmentation creates duplicated compliance burdens for multi-region operators. Long-term viability centers on operators with captive hospital relationships under centralized procurement mandates. Acquisition target archetype: mid-scale third-party logistics providers with NMPA dual-certification in western corridor geographies. Watch NMPA electronic drug traceability mandate enforcement as inflection indicator for technology infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Western Corridor Cold Chain Expansion | Captures biologics manufacturing growth in Chengdu and Chongqing biotech parks. |
| Autonomous Mobile Robotics Deployment | JD Logistics validates warehouse automation density for same-day biologics delivery. |
| Managed Service Contract Consolidation | Long-term agreements with Jiangsu hospital consortia transfer compliance risk. |
| Modular Containerized Facility Deployment | Containerized pods reduce capital barriers for secondary city market entry. |
| NMPA Electronic Traceability Integration | Scanning infrastructure maintains distribution eligibility under serialization mandates. |
Research Methodology
Direct dialogue with pharmaceutical warehouse operators, NMPA compliance officers, hospital procurement managers, and cold chain equipment suppliers grounded the qualitative foundation. Secondary validation drew from NMPA facility licensing databases, National Healthcare Security Administration procurement bulletins, provincial drug regulatory inspection reports, and China Customs pharmaceutical trade statistics. Bottom-up capacity modeling triangulated against top-down pharmaceutical production throughput estimates.
Segment-level outputs across temperature zones, service types, and regional clusters informed the analytical framework throughout the projection horizon. Modeled dimensions included storage certification tier, end-user procurement structure, and proximity to manufacturing clusters. CAGRs derived from capacity expansion pipelines, NMPA licensing velocity, and biologics production growth trajectories. Forecast inputs incorporated electricity price scenarios and western corridor infrastructure investment schedules.
Caveats apply where NMPA inspection regime intensity or National Healthcare Security Administration procurement mandate scope could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement consistency and biologics manufacturing location decisions. A small set of triggers—provincial licensing harmonization, energy subsidy revisions, and western corridor tax incentive duration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market