
 Endoscopic Mucosal Resection Device Market | 2026-2036
Endoscopic Mucosal Resection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Mucosal Resection Device Market Insights
The gap between hospital-based and ambulatory surgical center procurement is collapsing as outpatient gastrointestinal procedures migrate to lower-acuity settings. Olympus sustains its installed base dominance through proprietary endoscope channel architectures that lock in accessory compatibility. Boston Scientific Corp. competes with a broad electrosurgical portfolio spanning snares, injection needles, and thermal ablation platforms. Medtronic anchors North American distribution through direct sales teams embedded in integrated delivery networks.
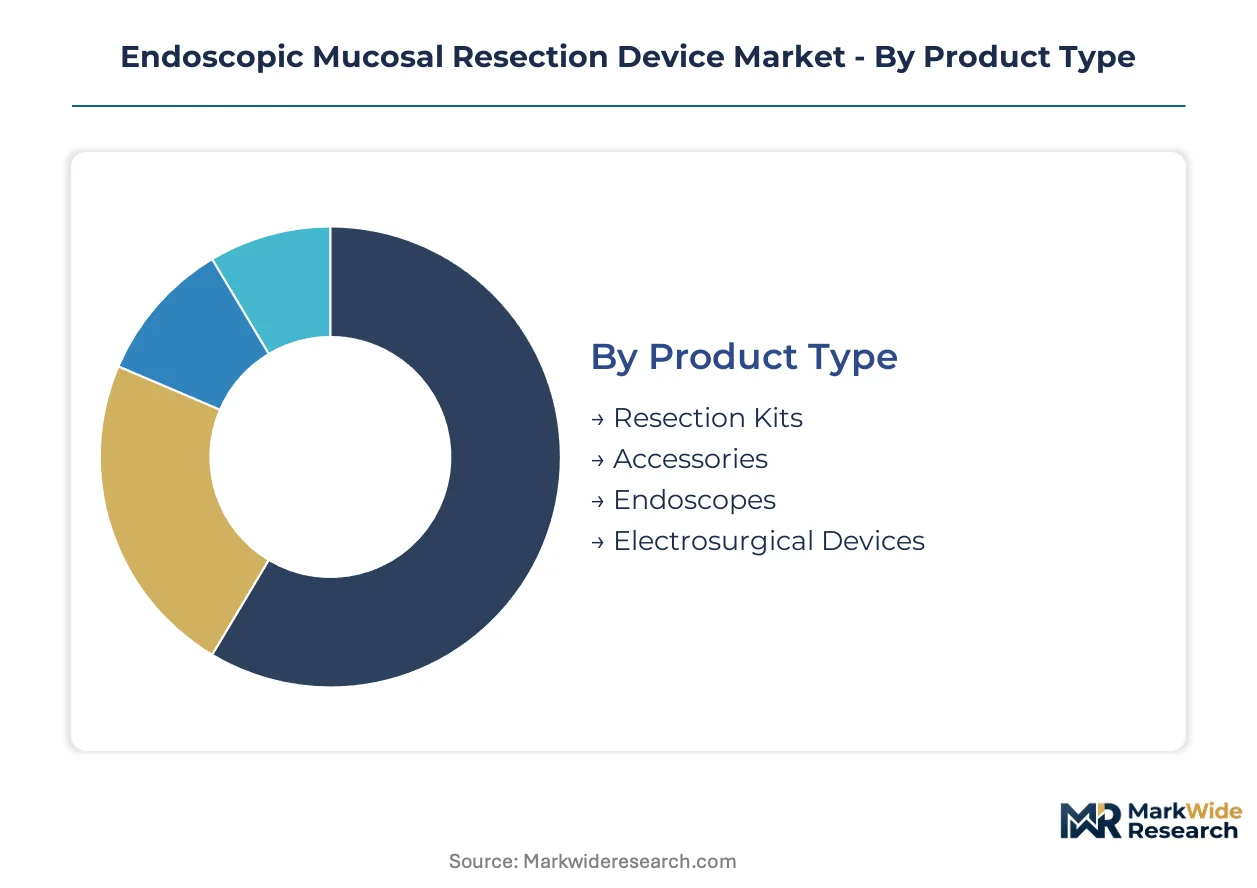
Endoscopic mucosal resection devices encompass electrosurgical snares, injection solutions, cap-assisted aspiration systems, and tissue retrieval tools designed to excise superficial gastrointestinal lesions without open surgery. These instruments operate at controlled power outputs with insulated delivery channels to enable precise submucosal lifting and en-bloc resection of lesions up to 20 millimeters. Resection kits command the largest revenue pool due to bundled pricing and recurring consumption of disposable snares and injection needles. Electrosurgical devices represent the fastest-growing product category as bipolar and hybrid energy modalities displace monopolar systems in advanced endoscopy suites. Visualization systems within the technology dimension are capturing margin expansion through 4K and linked-color imaging platforms that improve dysplasia detection rates.
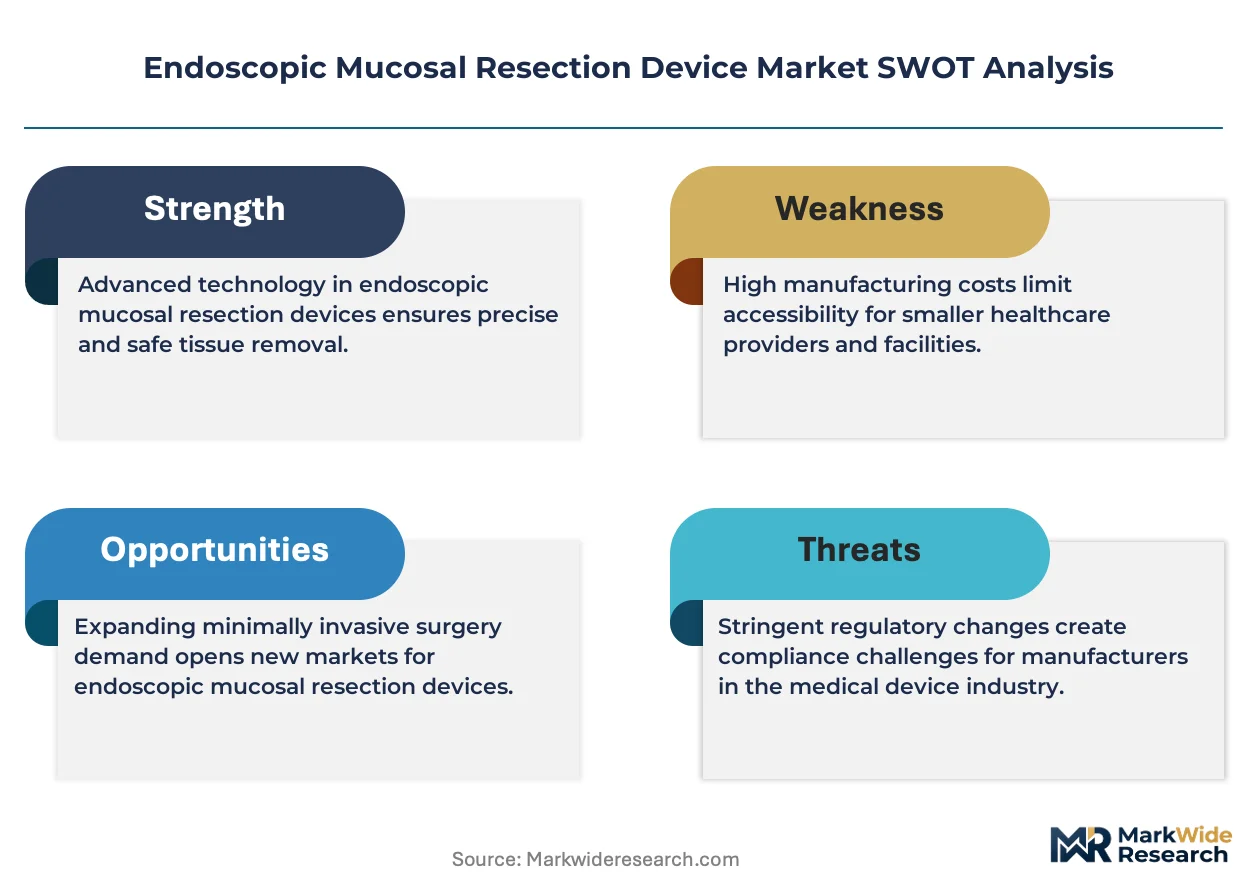
FDA 510(k) clearance requirements govern electrosurgical device safety and electromagnetic compatibility in the United States, while the EU MDR mandates clinical evidence and post-market surveillance for resection accessories sold under CE marking. Japan's PMDA enforces JIS standards for endoscope electrical safety and biocompatibility, creating layered compliance costs for manufacturers serving multiple jurisdictions. Stakeholders must monitor how reimbursement shifts toward value-based colonoscopy screening will reshape purchasing authority between hospital procurement departments and ambulatory center administrators.
Market Dynamics
The migration of gastrointestinal procedures from inpatient to outpatient settings is compressing procurement hierarchies and forcing device manufacturers to reconfigure sales coverage toward ambulatory surgical center administrators rather than hospital materials management departments.
Growth Catalysts
- EU MDR Clinical Evidence Mandates:Stricter post-market surveillance requirements for electrosurgical accessories are accelerating replacement cycles as older devices lack sufficient clinical documentation for CE marking renewal.
- Hybrid Energy Modalities:Bipolar and hybrid electrosurgical systems are capturing procedural share in advanced endoscopy suites by reducing thermal injury depth compared to monopolar alternatives.
- Japan:National colorectal cancer screening programs and aging demographics sustain high-volume colonoscopy throughput, driving consistent device utilization in metropolitan hospital networks.
Market Restraints
- Single-Use Plastic Components:Reliance on petroleum-derived polymers for disposable snares and injection needles exposes manufacturers to feedstock price volatility and sustainability scrutiny.
- Proprietary Channel Architectures:Dominant endoscope manufacturers lock accessory compatibility through patented channel dimensions, constraining third-party device penetration in installed base accounts.
- Technical Limitation:Lesion size thresholds for safe en-bloc resection remain bounded at approximately 20 millimeters, limiting addressable indications without piecemeal resection protocols.
Strategic Opportunities
- Germany:Outpatient gastrointestinal procedure expansion under statutory health insurance reforms creates procurement entry points for bundled resection kit suppliers.
- 4K Linked-Color Imaging Convergence:Integration of high-definition visualization platforms with electrosurgical devices enables margin capture through differentiated dysplasia detection workflows.
- Direct-to-Ambulatory Distribution:Bypassing traditional hospital procurement through specialized distributors serving independent endoscopy centers reduces channel friction and accelerates inventory turns.
Industry Challenges
- Advanced Endoscopist Training:Submucosal dissection and complex EMR techniques require specialized fellowship-level skills that remain concentrated in academic medical centers, constraining procedural expansion.
- FDA 510(k) Electromagnetic Compatibility:Evolving electromagnetic interference standards for electrosurgical devices extend premarket notification timelines and increase regulatory compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Mucosal Resection Device Market |
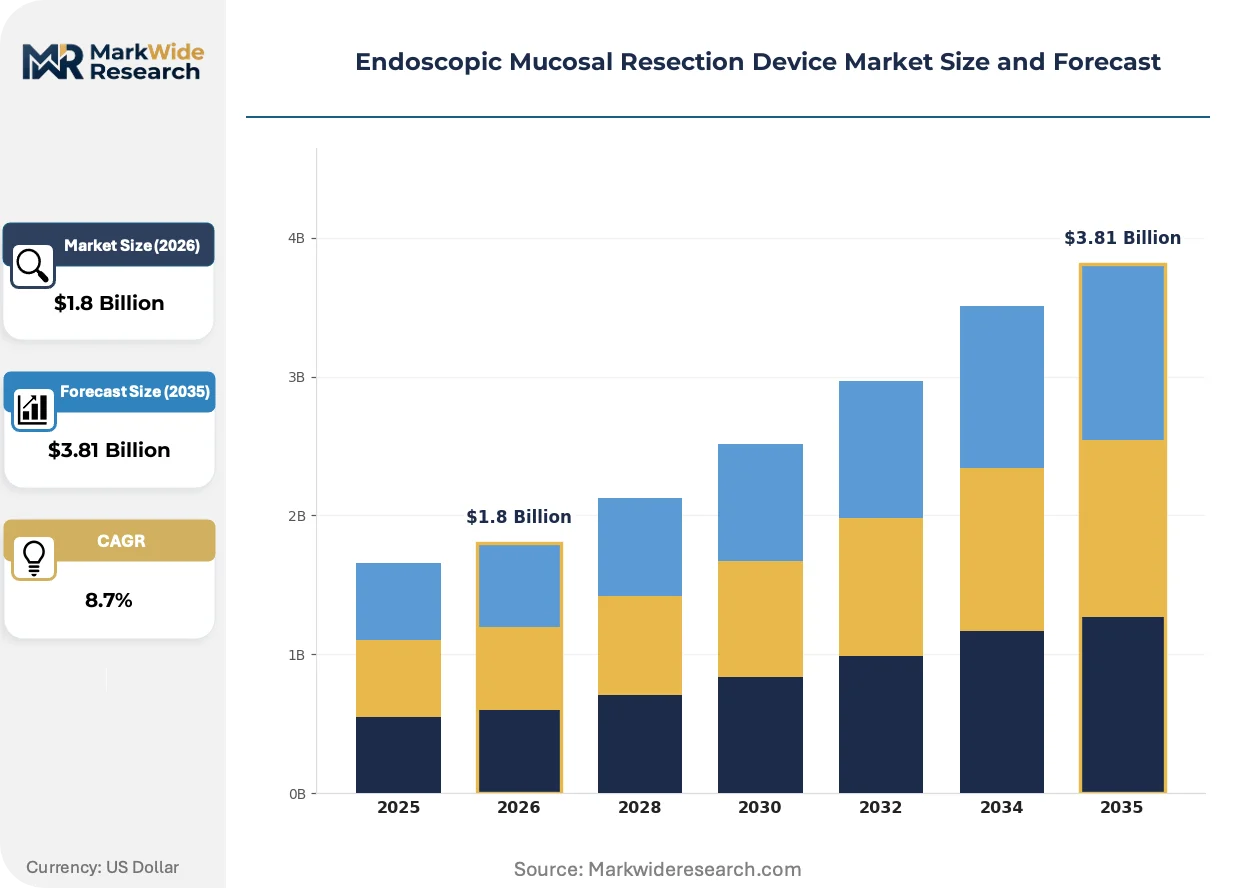
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resection Kits, Accessories, Endoscopes, Electrosurgical Devices Application: Gastrointestinal Disorders, Tumor Resection, Precancerous Lesions, Esophageal Conditions End User: Hospitals, Ambulatory Surgical Centers, Gastroenterology Clinics, Research Laboratories Technology: Flexible Endoscopy, Visualization Systems, Light Sources, Energy Devices |
| Companies Covered | Erbe Elektromedizin GmbH, Olympus, CONMED, Sumitomo Bakelite Co., Ltd., STERIS, Boston Scientific Corp., Interscope Medical, Medtronic, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Mucosal Resection Device Market Trends and Innovations
Energy delivery mechanisms and visualization platforms are converging to redefine procedural safety margins, while regulatory documentation burdens and purchasing authority shifts are restructuring commercial engagement models across the supply chain.
Bipolar electrosurgical systems with integrated impedance feedback are supplanting monopolar platforms in high-volume endoscopy suites. Academic medical centers and tertiary referral hospitals are adopting these systems at accelerated replacement cycles. The technology is supplanting legacy monopolar setups by enabling precise submucosal coagulation with reduced perforation risk, compressing the addressable market for conventional snare designs.
Japan's PMDA has tightened electrical safety and biocompatibility enforcement for endoscope accessories under revised JIS standards. Manufacturers must now submit expanded preclinical testing documentation for device registration renewal. Electrosurgical snare suppliers serving the Japanese market are responding by establishing localized quality management systems and dedicated regulatory affairs functions in Tokyo.
Hospital materials management departments are losing purchasing authority to ambulatory surgical center administrators as outpatient colonoscopy volumes expand. Specialized distributors and manufacturer direct sales teams are displacing traditional medical-surgical distributors in these accounts. This pattern is most visible in the United States, where integrated delivery networks are unbundling gastrointestinal service lines into freestanding endoscopy centers with independent procurement autonomy.
Endoscopic Mucosal Resection Device Market Segmentation
Segmentation in the EMR device market reveals how procurement authority, clinical workflow complexity, and technology integration requirements reshape competitive positioning across customer tiers. Manufacturers must align product configurations with distinct purchasing behaviors between integrated hospital networks and independent ambulatory settings.
Product Type:
Domestic manufacturing concentration varies sharply across product categories, with electrosurgical devices and resection kits produced primarily in the United States and Germany, while endoscope manufacturing clusters in Japan.
- Resection Kits:Bundled disposable configurations combine snares, injection needles, and retrieval tools in sterile single-procedure packs. Hospital procurement departments in the United States and Germany favor these kits for inventory simplification and standardized protocol adherence across high-volume endoscopy suites.
- Electrosurgical Devices:Bipolar and hybrid energy platforms with integrated impedance feedback enable precise submucosal coagulation. Demand concentrates in tertiary academic centers in Japan and metropolitan hospital networks in Germany where advanced endoscopists perform complex submucosal dissection procedures.
- Accessories:Individual injection solutions, cap-assisted aspiration devices, and tissue retrieval tools sold separately from bundled configurations.
- Endoscopes:Flexible gastrointestinal scopes with proprietary channel architectures that lock in accessory compatibility across installed base accounts.
Resection kits command the established base. The steepest expansion runs through electrosurgical devices.
Application:
Procedure complexity and reimbursement differentiation create distinct margin profiles across clinical indications, with tumor resection commanding premium pricing versus screening protocols.
- Tumor Resection:En-bloc excision of superficial gastrointestinal malignancies up to 20 millimeters requires precise submucosal lifting and controlled energy delivery. Academic medical centers in Japan and comprehensive cancer centers in the United States drive utilization through fellowship-trained advanced endoscopists performing complex submucosal dissection.
- Precancerous Lesions:Removal of dysplastic Barrett's esophagus and colonic adenomas represents high-frequency indications with standardized reimbursement pathways. Screening colonoscopy expansion in Germany under statutory health insurance reforms sustains consistent device consumption across outpatient settings.
- Gastrointestinal Disorders:Therapeutic intervention for benign structural abnormalities including strictures and polyps.
- Esophageal Conditions:Specialized procedures targeting Barrett's surveillance and early esophageal neoplasia detection.
Tumor resection captures premium positioning. The volume base concentrates in precancerous lesion management.
End User:
Customer concentration patterns reflect the migration of gastrointestinal procedures from inpatient to outpatient environments, reshaping sales coverage requirements and distribution economics.
- Hospitals:Integrated delivery networks and academic medical centers maintain centralized procurement through materials management departments. These accounts in the United States and Japan emphasize bundled contracting and established vendor relationships with endoscope manufacturers.
- Ambulatory Surgical Centers:Freestanding endoscopy facilities with independent procurement autonomy prioritize rapid inventory turns and specialized distributor relationships. Germany's outpatient gastrointestinal expansion under statutory reforms accelerates this segment's procurement velocity.
- Gastroenterology Clinics:Physician-owned practices performing office-based endoscopy with limited procedure volumes.
- Research Laboratories:Academic and clinical research settings evaluating novel resection techniques and device iterations.
Hospitals anchor the revenue base. Ambulatory surgical centers are climbing the fastest.
Technology:
Technology integration requirements determine competitive differentiation, with visualization convergence and energy modality advancement driving replacement cycles.
- Visualization Systems:4K and linked-color imaging platforms improve dysplasia detection rates through enhanced mucosal pattern recognition. Adoption concentrates in Japan's metropolitan hospital networks where PMDA-enforced JIS standards mandate electrical safety and biocompatibility documentation for integrated accessories.
- Energy Devices:Bipolar electrosurgical systems with real-time impedance monitoring reduce thermal injury depth versus monopolar alternatives. German endoscopy suites and United States academic centers lead replacement cycles as FDA electromagnetic compatibility requirements extend premarket notification timelines for new entrants.
- Flexible Endoscopy:Core platform technology with proprietary channel architectures constraining third-party accessory penetration.
- Light Sources:LED and xenon illumination systems supporting high-definition imaging workflows.
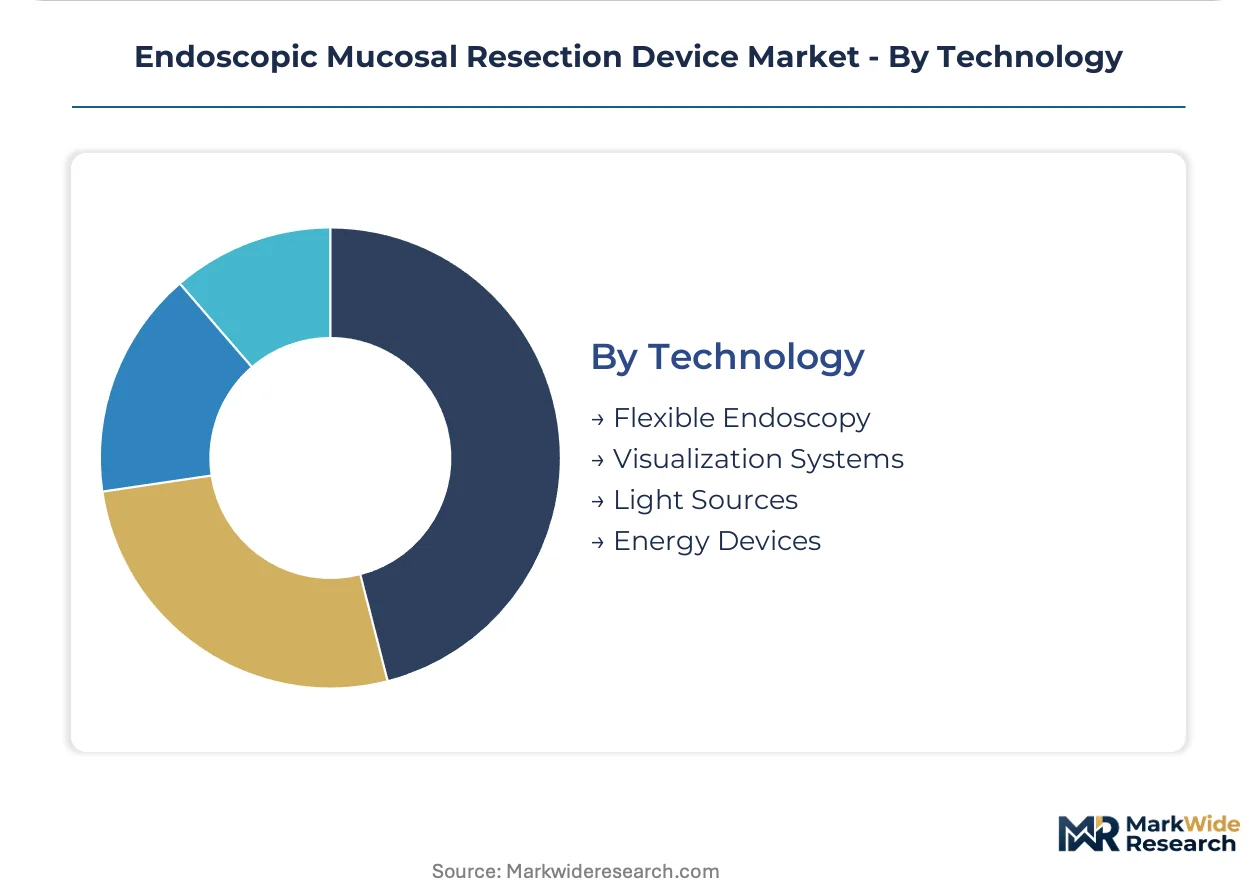
Flexible endoscopy provides the installed base foundation. Visualization systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export electrosurgical resection systems to Japanese hospital networks, while United States distributors channel bundled kits into ambulatory surgical centers across North America. This trade-flow pattern concentrates procurement authority in three distinct regulatory environments.
United States
Screening colonoscopy volumes and integrated delivery network unbundling sustain device utilization. FDA 510(k) electromagnetic compatibility requirements extend premarket timelines for electrosurgical accessories. Greater Boston and the Pacific Northwest host academic medical centers where advanced endoscopists perform complex submucosal dissection.
Germany
Statutory health insurance reforms expand outpatient gastrointestinal procedures, creating procurement entry points for bundled resection kit suppliers. EU MDR clinical evidence mandates accelerate replacement cycles for older devices lacking CE marking documentation. The North Rhine-Westphalia cluster anchors electrosurgical device production for European distribution.
Japan
National colorectal cancer screening programs and aging demographics drive high-volume colonoscopy throughput. PMDA-enforced JIS standards for electrical safety and biocompatibility require expanded preclinical testing documentation. Tokyo metropolitan hospital networks concentrate demand for bipolar energy platforms with impedance feedback.
United Kingdom
NHS bowel cancer screening expansion increases diagnostic colonoscopy volumes across hospital trusts. MHRA post-Brexit regulatory alignment with EU MDR creates transitional compliance burdens for resection accessory suppliers. London and the Southeast concentrate private endoscopy center investment with independent procurement autonomy.
South Korea
MFDS-enforced medical device quality management standards govern electrosurgical snare registration and renewal. The Seoul Capital Area hosts tertiary referral hospitals where fellowship-trained endoscopists adopt hybrid energy modalities. Domestic manufacturers supply cap-assisted aspiration systems to metropolitan clinic networks.
Endoscopic Mucosal Resection Device Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with endoscope manufacturing heritage. Market structure concentrates around three to four integrated device manufacturers controlling proprietary channel architectures. Strategic archetypes include endoscope-native suppliers, electrosurgical platform specialists, and procedure-kit bundlers. Dominant competitive moves encompass direct-to-ambulatory distribution restructuring and visualization platform convergence.
Among diversified medical technology conglomerates, Olympus and Boston Scientific Corp. exemplify endoscope-native and electrosurgical platform archetypes respectively. Erbe Elektromedizin GmbH occupies a position within the specialized energy delivery tier. Medtronic anchors North American distribution scale through embedded sales teams. Sumitomo Bakelite Co., Ltd. represents Japanese material science integration into disposable component supply.
| Leading Market Players |
|---|
| Erbe Elektromedizin GmbH |
| Olympus |
| CONMED |
| Sumitomo Bakelite Co., Ltd. |
| STERIS |
| Boston Scientific Corp. |
| Interscope Medical |
| Medtronic |
| Cook Medical |
| Others |
Pricing and Supply Chain Analysis
Bipolar energy platforms displacing monopolar systems in Japanese and German endoscopy suites simultaneously concentrates procurement power with academic medical centers and compresses margins for legacy snare manufacturers tethered to older electrosurgical architectures. This substitution dynamic redistributes value capture toward visualization-integrated suppliers while forcing commodity producers toward ambulatory surgical center contracts with compressed unit economics.
Pricing Analysis
Next-generation bipolar systems with impedance feedback command substantial premiums over prior-generation monopolar platforms, while economy-tier disposable snares face persistent cost compression. Three-tier pricing structure across premium visualization-integrated platforms, standard electrosurgical devices, and economy disposable kits reflects FDA electromagnetic compatibility certification tiers and volume scale. Pricing pressure stems from EU MDR clinical evidence mandates accelerating replacement cycles for undocumented legacy devices. Ambulatory surgical centers exhibit acute price sensitivity versus academic medical centers prioritizing procedural safety margins.
Supply Chain Analysis
Japan and Germany anchor electrosurgical device manufacturing, while the United States concentrates resection kit assembly and sterile packaging operations. Supply chains draw from petroleum-derived polymers for disposable snares, specialized copper alloys for bipolar electrodes, and medical-grade silicone for insulated delivery channels. Single-source vulnerability concentrates in proprietary endoscope channel architectures that constrain third-party accessory compatibility. Distribution runs through specialized medical-surgical distributors serving hospital networks and direct-to-ambulatory channels for independent endoscopy centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained advanced endoscopists capable of complex submucosal dissection remain concentrated in metropolitan academic centers across Japan, Germany, and the United States, creating a bottleneck that constrains procedural expansion and locks device demand to narrow customer segments.
For Market Incumbents: Fortify installed base retention through proprietary channel architecture exclusivity and accelerated visualization platform convergence. Defend against hybrid energy modality entrants by embedding electrosurgical systems within 4K imaging workflows. Prioritize backward integration into bipolar electrode material supply to secure cost position against feedstock volatility. For New Entrants and Emerging Players: Differentiate on direct-to-ambulatory distribution models bypassing hospital procurement hierarchies. Target Germany's outpatient gastrointestinal expansion under statutory health insurance reforms as the most penetrable geography. Pursue CE marking pathway acceleration for electrosurgical accessories lacking legacy clinical documentation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed electrosurgical platform specialists holding FDA 510(k) clearances but limited visualization integration. Long-term viability hinges on convergence with imaging modalities and ambulatory surgical center procurement autonomy. Monitor PMDA enforcement patterns for JIS standard compliance as inflection indicator for Japanese market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR clinical evidence mandates compress renewal timelines for legacy devices lacking documentation. |
| Hospital System Partnership | Integrated delivery network unbundling creates procurement entry points for bundled resection kit suppliers. |
| Software Companion Development | Impedance feedback algorithms embedded in electrosurgical generators enable precise submucosal coagulation control. |
| Reimbursement Strategy | Value-based colonoscopy screening shifts shift purchasing authority toward ambulatory center administrators. |
| FDA Submission | Electromagnetic compatibility requirements extend premarket notification timelines for new electrosurgical entrants. |
Research Methodology
Initial hypotheses were tested against primary input from advanced endoscopists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, PMDA device registration records, and hospital procurement contract repositories. Bottom-up demand modeling across product type, application, end user, and technology dimensions was triangulated against top-down macroeconomic indicators and healthcare expenditure trends.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension. CAGRs were derived from fitted growth curves calibrated to historical procedure volumes, replacement cycle acceleration patterns, and regulatory compliance cost trajectories. Forecast inputs incorporate colonoscopy screening program expansion rates, fellowship training pipeline outputs, and ambulatory surgical center construction permits.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement support for outpatient gastrointestinal procedures or accelerated EU MDR enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding screening compliance rates and electrosurgical device replacement elasticity. Recalibration cycles align with material shifts in regulatory documentation requirements and ambulatory procedural migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Injection Practice Pad Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
North America Portable Medical and Healthcare Devices Market