
 Europe Urinary Catheters Market | 2026-2036
Europe Urinary Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Urinary Catheters Market Analysis
Germany is narrowing its position as the dominant production base for silicone-based urinary catheters distributed across the continent. B. Braun SE leverages its manufacturing scale in Melsungen to supply hospital systems throughout Central Europe. Coloplast Corp sustains competitive positioning through specialized intermittent catheter lines designed for self-catheterization protocols. Hollister Incorporated anchors its presence with hydrophilic-coated products targeting infection prevention pathways.
Urinary catheters are flexible tubular devices inserted through the urethra or abdominal wall to drain urine from the bladder, typically constructed from latex, silicone, or PVC with outer diameters measured in French units and incorporating balloon retention mechanisms for indwelling applications. Their primary purpose spans acute urinary retention management, post-operative drainage, and chronic incontinence care across institutional and home settings. Intermittent catheters lead volume due to lower infection risk profiles and expanding self-catheterization training programs, while silicone materials command premium positioning driven by latex allergy prevalence and extended dwell-time requirements. Hydrogel-coated segments are gaining fastest traction as coating technologies reduce urethral trauma and encrustation incidence in long-term Foley applications.
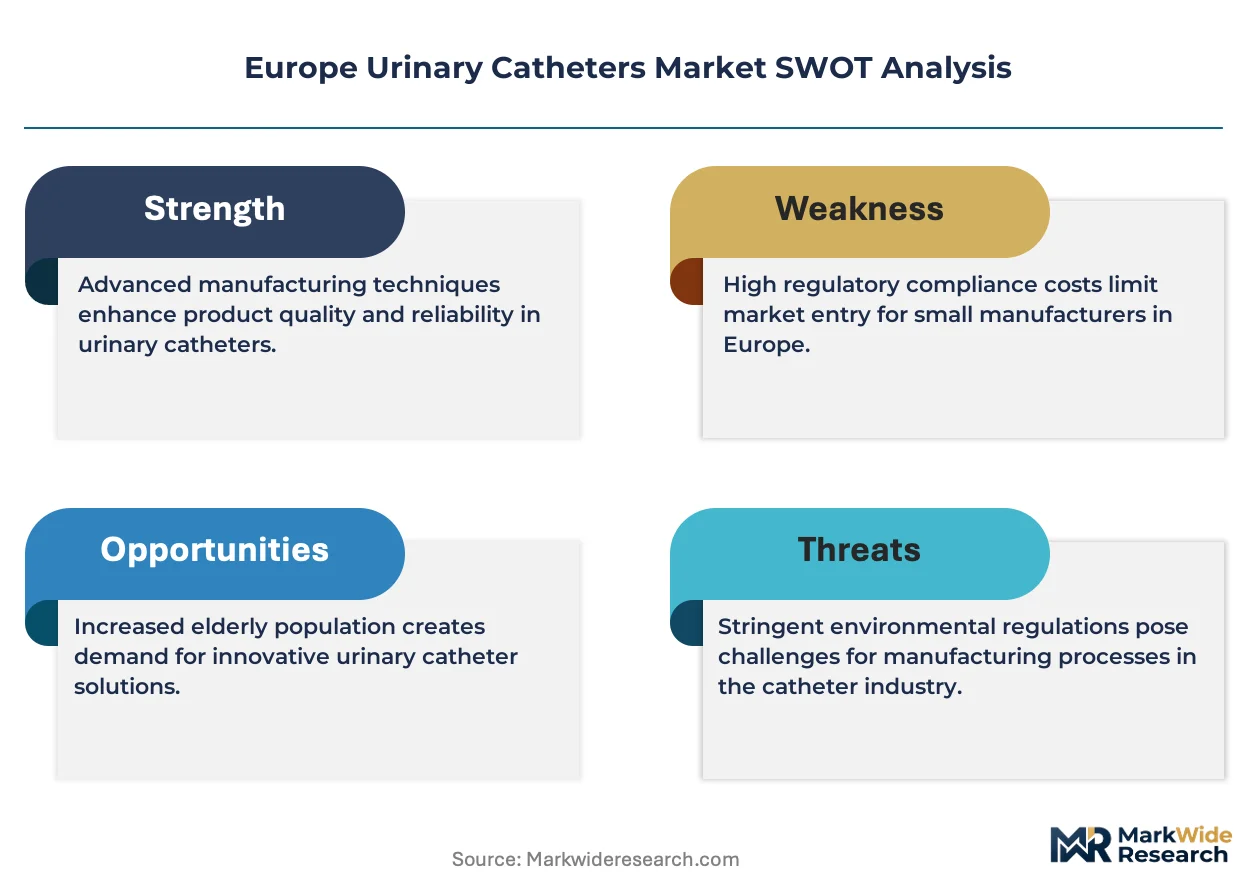
The EU Medical Device Regulation and CE marking framework mandate clinical evidence and post-market surveillance, elevating compliance costs for catheter manufacturers seeking European market access. EMA-aligned biocompatibility standards and REACH chemical safety protocols further constrain material selection and coating chemistries. National health technology assessment bodies in France, Germany, and the United Kingdom increasingly evaluate catheter cost-effectiveness against catheter-associated urinary tract infection reduction metrics. Stakeholders must monitor evolving reimbursement thresholds for hydrophilic and antimicrobial-coated devices as payers tighten value-based procurement criteria across European hospital networks.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing manufacturer margins while forcing rapid material platform shifts toward silicone and hydrogel chemistries that satisfy biocompatibility surveillance mandates.
Growth Catalysts
- Home Care Expansion:Aging demographics across Italy and Spain are accelerating intermittent catheter volume through self-catheterization training programs administered by regional health authorities.
- REACH Chemical Safety Protocols:Stricter substance restrictions are eliminating latex-based alternatives, pulling demand toward silicone platforms that meet ECHA compliance thresholds.
- Antimicrobial Coating Advances:Silver-alloy and nitrofurazone-impregnated surfaces are reducing catheter-associated urinary tract infection rates in long-term indwelling applications.
Market Restraints
- MDR Clinical Evidence Burden:Post-market surveillance requirements and notified body capacity constraints are extending CE marking timelines by 18-24 months for novel coating technologies.
- Silicone Raw Material Concentration:Precipitated silica and medical-grade silicone elastomer supply chains cluster in Germany and Belgium, creating geographic vulnerability to energy price volatility.
- Catheter-Associated Infection Liability:Hospital-acquired condition penalties in France and the United Kingdom are making payers reluctant to reimburse standard uncoated Foley devices.
Strategic Opportunities
- Poland and Romania Home Care Networks:Underdeveloped intermittent catheter penetration in Eastern European long-term care facilities offers first-mover positioning for hydrophilic-coated product lines.
- Digital Urinary Monitoring Integration:Bluetooth-enabled volume sensors and cloud-connected drainage bags are converging with traditional catheter hardware to create remote patient monitoring revenue streams.
- EU Green Deal Procurement Incentives:Public hospital tenders are weighting biodegradable packaging and reduced plastic content, favoring suppliers with circular material certifications.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise for hydrogel cross-linking and drug-eluting coatings remains concentrated among a narrow pool of medical device specialists in Switzerland and southern Germany.
- Legacy Sterilization Infrastructure:Ethylene oxide sterilization capacity constraints are forcing manufacturers to validate gamma or electron beam alternatives, requiring substantial capital requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Urinary Catheters Market |
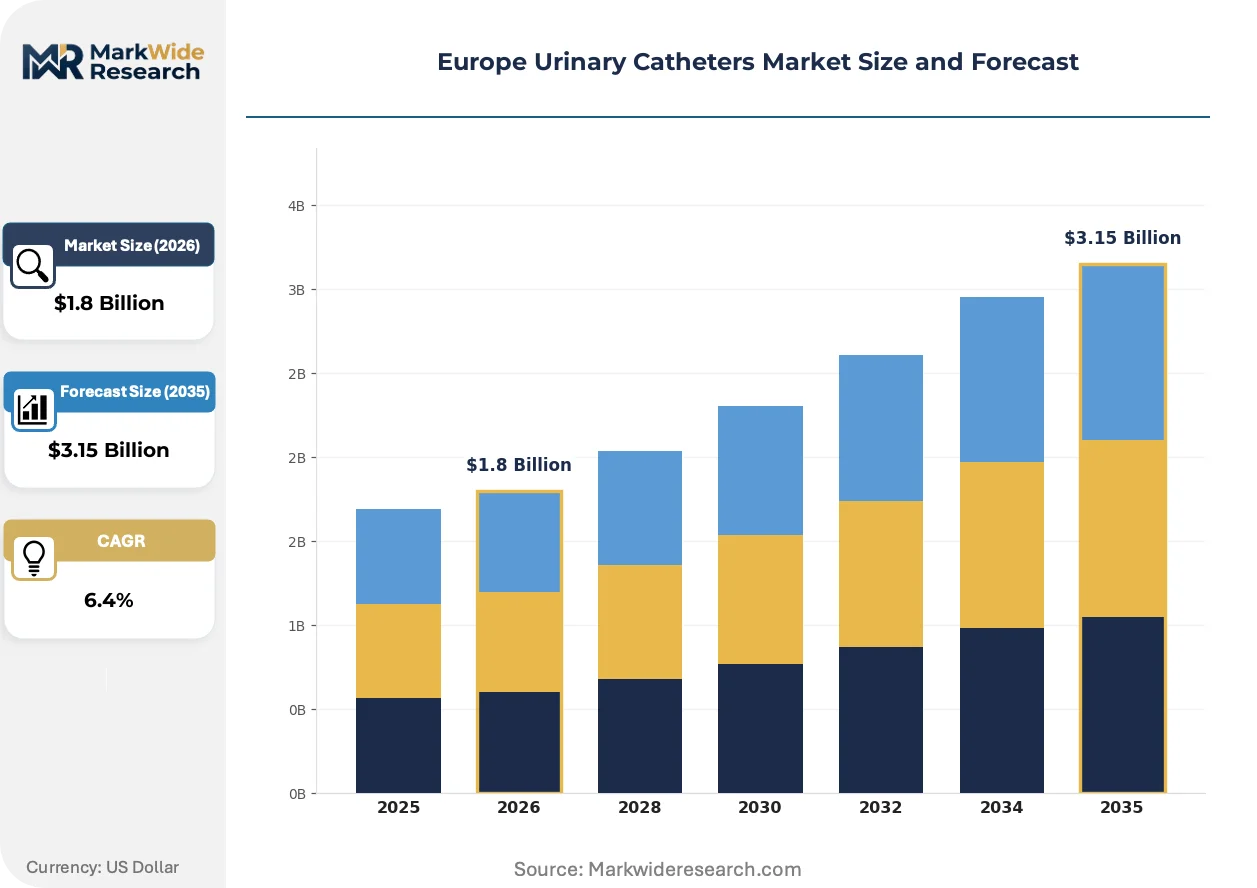
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Catheters, Foley Catheters, Suprapubic Catheters, External Catheters Material: Latex, Silicone, PVC, Hydrogel End User: Hospitals, Home Care, Nursing Facilities, Ambulatory Surgical Centers Application: Urinary Retention, Incontinence, Post-Surgical Care, Diagnostics |
| Companies Covered | Coloplast Corp, B. Braun SE, Hollister Incorporated, Convatec Inc., Bactiguard AB, Teleflex Inc., Boston Scientific Corporation, Wellspect Healthcare, Medline Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Urinary Catheters Market Emerging Trajectories
Coating chemistry and connected device architectures are converging to redefine performance benchmarks and reimbursement pathways across European catheter procurement networks.
Silicone-hydrogel composite surfaces are hybridizing to deliver simultaneous lubricity and antimicrobial release in indwelling applications. German hospital systems are piloting these platforms for neurogenic bladder patients requiring 30-day dwell times. The technology is hybridizing competitive positioning by collapsing the distinction between premium infection-prevention and standard comfort categories.
MDR Article 10 clinical evaluation requirements are mandating prospective post-market clinical follow-up studies for all novel catheter coatings. Manufacturers must now generate real-world evidence on encrustation rates and urethral trauma incidence before securing notified body approval. France's Haute Autorité de Santé is incorporating these data into hospital formulary decisions, advantaging firms with established surveillance infrastructure.
Hospital purchasing consortia in the United Kingdom and the Netherlands are consolidating catheter procurement into multi-year framework agreements with infection-rate guarantees. Traditional distributor relationships are compressing as direct manufacturer-to-health-system contracting captures 60% of acute care volume. Spain's autonomous community health services are replicating this model, bundling catheter supply with urology nursing training contracts.
Europe Urinary Catheters Market Segmentation

Segmentation in the Europe urinary catheters market reveals distinct procurement rhythms and clinical utility patterns. Product lifecycle duration varies dramatically across intermittent versus indwelling formats, while material selection increasingly tracks regulatory compliance rather than cost alone.
Product Type:
Cycle times diverge sharply across catheter formats, with single-use intermittent devices turning over daily while indwelling Foley systems remain in place for weeks. This temporal spread creates fundamentally different inventory and reimbursement economics for procurement teams.
- Intermittent Catheters:Single-use devices designed for self-catheterization protocols, typically uncoated or hydrophilic-coated for lubricity. Demand concentrates in German and French home care networks where regional health authorities fund patient training programs. REACH chemical restrictions are accelerating the shift from latex to silicone and PVC alternatives in bulk hospital tenders.
- Foley Catheters:Indwelling devices with balloon retention mechanisms for continuous drainage over 14-30 day dwell periods. Italian and Spanish hospital systems are the primary volume anchors, though catheter-associated urinary tract infection penalties in France and the United Kingdom are squeezing standard uncoated variants.
- Suprapubic Catheters:Surgically placed through the abdominal wall for patients with urethral trauma or stricture. Neurological rehabilitation centers in Belgium and the Netherlands generate concentrated demand for long-term suprapubic management.
- External Catheters:Non-invasive sheath or condom-type devices for male incontinence. Nursing facilities across Poland and Romania are expanding adoption as lower-acuity alternatives to indwelling placement.
Intermittent catheters anchor the volume base while hydrogel-coated Foley variants gain share at the steepest rate.
Material:
Cost tier stratification has inverted as regulatory compliance premiums now outweigh raw material economics. Silicone and hydrogel command price multiples over latex and PVC, yet procurement officers absorb these premiums to satisfy EMA biocompatibility surveillance mandates.
- Silicone:Medical-grade elastomer with superior biocompatibility and extended dwell-time tolerance. German manufacturing clusters in Melsungen and Tuttlingen supply silicone platforms across Central European hospital systems. ECHA substance restrictions are cementing silicone as the default for long-term indwelling applications.
- Hydrogel:Cross-linked polymer coatings applied to silicone or latex substrates for lubricity and encrustation resistance. French Haute Autorité de Santé evaluations are driving fastest adoption in neurogenic bladder populations requiring 30-day catheterization cycles.
- Latex:Natural rubber substrate with lowest unit cost but declining clinical acceptance. Allergy prevalence and REACH chemical safety protocols are restricting latex to emergency and short-term applications in Eastern European markets.
- PVC:Thermoplastic polymer for cost-sensitive intermittent catheter production. Polish and Romanian home care networks favor PVC for high-volume self-catheterization programs where daily consumption drives material cost sensitivity.
Silicone dominates revenue contribution while hydrogel coatings expand most quickly across premium tenders.
End User:
Customer type determines specification complexity and contracting leverage. Hospital purchasing consortia wield volume concentration for infection-rate guarantees, while fragmented home care channels favor standardized intermittent formats.
- Hospitals:Acute care systems with centralized procurement and formulary committees. United Kingdom and Netherlands hospital consortia are bundling catheter supply with nursing training contracts under multi-year framework agreements.
- Home Care:Dispersed patient populations managing self-catheterization with regional health authority reimbursement. Italian and Spanish autonomous community health services are scaling intermittent catheter distribution through pharmacy networks.
- Nursing Facilities:Long-term care institutions with mixed acuity populations. German Pflegekassen reimbursement structures favor cost-efficient PVC intermittent devices for mobile residents and silicone Foley systems for bedbound cases.
- Ambulatory Surgical Centers:Same-day procedure facilities with minimal inventory carrying capacity. French and Belgian day surgery networks prioritize pre-packaged sterile kits combining catheter with drainage bag and securement device.
Hospitals retain the largest absolute spend while home care channels are climbing the fastest.
Application:
Clinical indication shapes dwell-time requirements and coating specifications. Post-surgical and retention applications favor shorter-cycle intermittent formats, while chronic conditions demand advanced material platforms.
- Urinary Retention:Acute or chronic bladder emptying failure requiring immediate drainage intervention. German urology departments are piloting silicone-hydrogel composites for neurogenic retention patients needing extended catheterization without encrustation.
- Incontinence:Chronic involuntary urine loss managed through catheterization or external collection. French and British payer reluctance to reimburse standard Foley devices for incontinence alone is redirecting volume toward external catheters and intermittent protocols.
- Post-Surgical Care:Temporary drainage following urological, gynecological, or orthopedic procedures. Spanish hospital systems standardize on hydrophilic-coated intermittent catheters for post-operative voiding recovery to minimize infection liability.
- Diagnostics:Catheterization for urodynamic testing or specimen collection. Specialized urodynamics centers in Switzerland and Austria require pressure-resistant catheters with radiopaque markers for fluoroscopic visualization.
Urinary retention anchors the volume base while post-surgical applications are gaining share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital systems favor silicone Foley platforms for extended dwell times, while Italian and Spanish autonomous communities drive intermittent catheter volume through pharmacy-dispensed home care programs. This consumption-mix differential separates procurement patterns across Western European markets.
Germany
Pflegekassen reimbursement structures split demand between PVC intermittent devices for mobile residents and silicone Foley systems for bedbound long-term care patients. The EU MDR clinical evidence requirements extend CE marking timelines for novel coating technologies entering German hospital formularies. Manufacturing clusters in Melsungen and Tuttlingen supply medical-grade silicone platforms across Central European health systems.
France
Haute Autorité de Santé evaluations incorporate real-world evidence on encrustation rates into hospital procurement decisions, favoring suppliers with established post-market surveillance infrastructure. Catheter-associated urinary tract infection penalties in acute care settings restrict reimbursement for standard uncoated Foley devices. The Paris-Saclay corridor concentrates polymer chemistry expertise for hydrogel cross-linking formulations.
United Kingdom
Hospital purchasing consortia consolidate catheter procurement into multi-year framework agreements bundling supply with infection-rate guarantees and urology nursing training contracts. NHS England value-based procurement criteria weight hydrophilic-coated devices against CAUTI reduction metrics. The Oxford-Cambridge health technology assessment cluster shapes regional formulary standards.
Italy
Autonomous community health services scale intermittent catheter distribution through pharmacy networks serving aging demographics managing chronic urinary retention. Regional health authorities fund patient self-catheterization training programs in Lombardy and Emilia-Romagna. Milan-based medical device distributors coordinate supply chains for both institutional and home care channels.
Spain
Post-surgical voiding recovery protocols standardize on hydrophilic-coated intermittent catheters to minimize infection liability in Catalan and Madrid hospital systems. Autonomous community procurement offices replicate UK-style framework agreements with bundled nursing education components. Barcelona medical technology clusters support coating validation services for MDR compliance.
Europe Urinary Catheters Market Vendor Landscape
Capability concentration sits with specialized coating chemistry firms; scale advantage sits with diversified medical device conglomerates. The vendor base separates into three functional tiers: integrated hospital supply contractors, regional home care distributors, and niche coating technology licensors. Consolidation pressure intensifies as notified body capacity constraints favor larger players with dedicated regulatory affairs infrastructure. Dominant competitive moves include direct manufacturer-to-health-system contracting and backward integration into medical-grade silicone raw material supply.
Among diversified European medical technology groups, B. Braun SE and Coloplast Corp occupy positions spanning hospital and home care channels. Hollister Incorporated anchors the hydrophilic-coated product segment. These three entities exemplify the scale-regulatory capability combination that MDR compliance demands, with established notified body relationships and post-market surveillance infrastructure separating them from smaller regional competitors.
| Leading Market Players |
|---|
| Coloplast Corp |
| B. Braun SE |
| Hollister Incorporated |
| Convatec Inc. |
| Bactiguard AB |
| Teleflex Inc. |
| Boston Scientific Corporation |
| Wellspect Healthcare |
| Medline Industries |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German and Belgian medical-grade silicone feedstock determines both the premium pricing tier spread and the geographic clustering of catheter manufacturing across Central Europe. REACH chemical safety protocols and EU MDR biocompatibility mandates have collapsed the traditional cost hierarchy, forcing procurement officers to absorb silicone platform premiums regardless of raw material economics.
Pricing Analysis
Geographic price spreads separate Western European hospital tenders from Eastern European home care channels by a factor of two to three across equivalent product specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating complexity and dwell-time certification, with hydrogel-coated Foley devices commanding the top tier and PVC intermittent catheters anchoring the bottom. Pricing pressure stems from catheter-associated urinary tract infection penalties in France and the United Kingdom that squeeze reimbursement for standard uncoated variants. Home care networks in Poland and Romania exhibit the highest price sensitivity due to daily consumption volumes in self-catheterization programs, while German hospital purchasing consortia prioritize infection-rate guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Germany, Belgium, and Switzerland anchors the medical-grade silicone elastomer supply for catheter production across the continent. Precipitated silica and platinum-cured silicone precursors draw from chemical clusters in Melsungen, Tuttlingen, and Basel, with hydrogel cross-linking agents sourced from specialized polymer chemistry houses in the Paris-Saclay corridor. Single-source vulnerability to energy price volatility in German industrial zones poses the dominant structural risk, given the energy intensity of silicone synthesis and sterilization validation. Distribution runs through hospital purchasing consortia in the United Kingdom and the Netherlands, direct manufacturer-to-health-system contracting in Spain, and pharmacy networks in Italy for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across coating technology tiers and regional reimbursement systems creates multiple entry points for specialized players. The shift toward value-based procurement with infection-rate guarantees is segmenting demand into distinct technical-performance niches that favor focused capability over scale.
For Market Incumbents: Build regulatory moats through dedicated notified body relationships and post-market surveillance infrastructure that MDR Article 10 mandates require. B. Braun SE and Coloplast Corp should deepen backward integration into medical-grade silicone raw material supply to offset feedstock concentration risk in German chemical clusters. Capacity addition in Swiss and southern German polymer chemistry centers addresses the talent scarcity for hydrogel formulation expertise that constrains coating innovation. For New Entrants and Emerging Players: Pursue underdeveloped intermittent catheter penetration in Polish and Romanian long-term care facilities where hydrophilic-coated product lines face minimal incumbent saturation. Eastern European home care networks represent the most penetrable geography given the absence of bundled procurement frameworks and the cost sensitivity that favors challenger pricing. A go-to-market angle anchored on pharmacy-dispensed patient training programs, replicating Italian autonomous community models, bypasses hospital purchasing consortia gatekeepers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with MDR compliance infrastructure over pure-play coating technology licensors. Long-term viability over the next decade hinges on the ability to generate real-world clinical evidence for novel surfaces, positioning firms with established surveillance capabilities as acquisition targets. The signal to watch is notified body capacity constraints extending CE marking timelines, which advantages larger players with dedicated regulatory affairs teams and compresses valuations for smaller competitors facing approval bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance separates scalable players from regional competitors facing 18-24 month approval delays. |
| Hospital System Partnership | Direct manufacturer contracting with UK and Netherlands consortia captures 60% of acute care volume. |
| Backward Integration | Captive supply of medical-grade silicone from German chemical clusters mitigates energy price volatility exposure. |
| Software Companion Development | Bluetooth-enabled volume sensors create remote patient monitoring revenue streams converging with catheter hardware. |
| Reimbursement Strategy | Alignment with France's Haute Autorité de Santé value criteria secures formulary placement for premium coated devices. |
Methodological Framework
Operator-level perspectives from hospital procurement managers, biomedical engineers, GPO contracts directors, and urology nursing coordinators anchored the qualitative base for this study. Primary interviews across German, French, and United Kingdom health systems combined with secondary validation from EMA device registrations, CE marking databases, hospital procurement records, and national health technology assessment publications. Bottom-up demand modeling by product type and material tier triangulated against top-down macroeconomic indicators for the European medical device sector.
Scenario-bracketing around regulatory implementation timelines and reimbursement policy shifts framed the analytical approach across the projection horizon. Segmentation dimensions modeled include catheter format, material platform, coating technology, end-user channel, and regional procurement system type. CAGRs were derived from fitted growth curves calibrated to historical volume data and elasticity-adjusted for payer policy changes. Industry-specific forecast inputs incorporated REACH chemical restriction phase-in schedules and MDR notified body capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in energy prices, euro exchange rates, or healthcare expenditure growth would shift the trajectory. Forecasts reflect assumptions on regulatory implementation pace and reimbursement stability that may require revision if policy timelines accelerate or delay. Cross-checking against national health accounts data and medical device trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Microwave Ablation Devices Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Germany Anesthesia Devices Market
Medical Devices
Indonesia Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Breathing Circuits Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Pulse Lavage Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market